

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Civil Engineering Shape Memory Alloys Hit $245.5M in 2025, Growing 8.5% to $434.58M by 2032

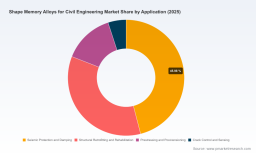
Unlocking the Future of Structural Resilience: A Strategic Overview of the Shape Memory Alloys in Civil Engineering Market 2026-2032
The global civil infrastructure landscape is undergoing a fundamental transformation. Driven by aging assets, increasing seismic risks, and the urgent demand for sustainable construction methodologies, engineers and investors are turning toward advanced material sciences to redefine structural integrity. At the forefront of this technological shift is the Shape Memory Alloys (SMA) sector. As we move further into 2026, the convergence of material innovation and structural engineering necessity presents a compelling investment thesis.
PW Consulting has released our comprehensive Worldwide Shape Memory Alloys for Civil Engineering Market research to provide stakeholders with the granular intelligence required to navigate this evolving terrain. This article serves as a strategic preview of the findings, highlighting the macro-economic trajectory, competitive dynamics, and technological catalysts that will define the market through 2032.
The Macro-Economic Trajectory: Growth Amidst Complexity
The expansion of the SMA civil engineering market is not merely incremental; it represents a structural recalibration of how infrastructure is built and maintained. Our analysis tracks revenue developments from 2020 through the forecast period ending in 2032. The historical data indicates a steady climb in market valuation, reflecting early adoption phases transitioning into broader commercial viability. Starting from a baseline in the mid-2020s, the market has demonstrated resilience despite global supply chain volatility.
Looking forward, the growth curve is projected to accelerate. The overall market size trajectory suggests a significant uplift in capital allocation toward SMA-integrated projects over the next decade. This growth is underpinned by a compound annual growth rate (CAGR) that signals robust demand penetration across multiple civil engineering verticals. For decision-makers, this implies that timing is critical. Entering the market or expanding existing portfolios now allows organizations to capture share during the steep ascent of the adoption curve. The revenue figures forecast for the late 2020s and early 2030s indicate a mature market phase where early movers will likely consolidate their technological lead.
However, growth is not uniform. It is mediated by material costs, regulatory frameworks, and geographical readiness. Understanding the interplay between these macro drivers and the specific revenue streams is essential for accurate budgeting and strategic planning.
Key Drivers Shaping the 2026 Landscape
Several converging factors are catalyzing demand for shape memory technologies in infrastructure. First, the imperative for seismic resilience is paramount. Traditional reinforcement methods are often heavy, labor-intensive, and reactive. SMAs offer superelastic properties that dissipate energy during seismic events, potentially reducing structural damage and lifecycle costs. This capability is shifting SMAs from experimental novelties to viable components in high-risk zones.
Shape Memory Alloys Market
Second, the focus on structural retrofitting and rehabilitation is intensifying. With vast networks of bridges and buildings reaching the end of their design lives, the industry requires solutions that can be deployed with minimal disruption to ongoing operations. SMA-based strengthening methods, particularly those involving iron-based alloys, offer advantages in terms of weight and corrosion resistance compared to traditional steel, facilitating easier installation and long-term durability.
Third, sustainability and efficiency are driving material innovation. The construction industry is under pressure to reduce carbon footprints. SMAs can contribute to lighter structures, reduced material usage, and extended service life. Furthermore, recent developments in digital fabrication and smart infrastructure integration are creating new use cases. For instance, the integration of SMA actuators in building technology for ventilation, shading, and fire protection systems represents an adjacent growth vector that complements core structural applications.
Finally, standardization is reducing market friction. The establishment of ASTM standards, including F2516 for shape memory alloys and related test methods, provides a framework for quality evaluation. This regulatory clarity supports procurement confidence and accelerates adoption among conservative engineering firms and government entities.
Competitive Dynamics and Vendor Landscape
The market structure is characterized by a mix of specialized material manufacturers and diversified engineering solution providers. Our research indicates a consolidated competitive environment where a core group of players holds a significant share of the revenue. The concentration ratio among the top firms highlights the technical barriers to entry and the importance of established supply chains and intellectual property.
Leading entities are not merely suppliers of raw materials; they are evolving into solution partners. Companies with vertically integrated operations, capable of managing the process from melting to component fabrication, are positioned to control quality and cost more effectively. For example, manufacturers specializing in nickel-titanium based alloys leverage high-performance properties for actuator and damping systems. Simultaneously, firms focusing on iron-based shape memory alloys are gaining traction for large-scale civil infrastructure elements due to advantages in mass production using conventional metallurgical equipment. This dual-track development suggests that the market will segment based on specific application requirements, with nickel-titanium dominating high-precision actuation and iron-based variants scaling for heavy structural strengthening.
Regional presence and application specialization further differentiate competitors. Some players have established strong footholds in structural strengthening and repair of concrete and masonry structures, including bridges, buildings, and silos. Others are integrating SMAs into building technology systems, offering full value chains from specification to assembly. Recent real-world applications demonstrate the transition from pilot projects to commercial deployment. Demonstrations of heat-activated strengthening methods for aging bridge decks and the use of memory-alloy steel in digitally fabricated concrete structures highlight the practical viability of these technologies.
Furthermore, collaborative research efforts are expanding the horizon. Upcoming international symposia focused on shape memory alloys in infrastructure are bringing together researchers and practitioners to discuss future directions. These knowledge exchanges are critical for aligning academic innovation with industrial application, ensuring that emerging technologies meet the rigorous demands of civil engineering practice.
For investors and procurement leaders, the key takeaway is that vendor selection must align with project-specific technical requirements. The optimal partner depends on whether the priority is high-performance actuation, cost-effective mass production for large elements, or integrated system solutions. The market offers diverse capabilities, but due diligence regarding supply chain stability and technical support is essential.
Strategic Implications for Stakeholders
The findings of this report have direct implications for various stakeholders in the construction and infrastructure ecosystem.
- Infrastructure Owners and Operators: Understanding the lifecycle cost benefits of SMA integration is crucial. While initial material costs may be higher, the potential for reduced maintenance, enhanced seismic performance, and extended service life can yield favorable total cost of ownership outcomes. Strategic planning should consider pilot projects in critical assets where performance gains justify material premiums.
- Engineering Firms: Incorporating SMA technologies into design capabilities can differentiate service offerings. Firms that master the specification, detailing, and construction methods for SMA applications will be well-positioned to lead projects that demand advanced resilience features. Continuous training and knowledge acquisition regarding standards and best practices are recommended.
- Material Suppliers and Manufacturers: The projected growth trajectory supports capacity expansion and R&D investment. However, attention to raw material volatility is necessary. Feedstocks such as nickel and titanium are subject to price fluctuations influenced by mining restrictions and geopolitical factors. Developing robust supply chain strategies and exploring alternative alloy formulations, such as iron-based variants, can mitigate exposure.
- Investors: The market shows promise, but due diligence is required. Focusing on companies with proven application records, vertical integration, and strong IP positions offers a pathway to capturing value. Monitoring the evolution of regional demand and regulatory support can provide leading indicators of market shifts.
The Value of PW Consulting's Deep Dive
While the trends outlined above provide the strategic context, execution requires precision. Market growth rates, competitive positioning, and application-specific revenue streams vary significantly across regions and segments. Generalizations can obscure the specific opportunities and risks relevant to your organization.
PW Consulting's Worldwide Shape Memory Alloys for Civil Engineering Market report offers the depth required to move from strategy to action. The report provides a detailed segmentation analysis, examining the market through lenses such as alloy type, application focus, and geography. It includes granular data on demand drivers, restraints, and opportunities that enable accurate forecasting and scenario planning.
Moreover, the competitive analysis goes beyond company profiles. It evaluates market share dynamics, strategic moves, and the implications of recent developments, such as new strengthening methods and symposia that shape industry consensus. The report also contextualizes regulatory environments, including the impact of standards and material availability, helping stakeholders anticipate compliance costs and supply constraints.
Worldwide Shape Memory Alloys for Civil Engineering Market
Readers interested in leveraging this intelligence for their 2026 decision-making are encouraged to access the full report. The detailed data tables, segmentation splits, and competitive assessments contained within the document provide the granularity necessary to refine market entry strategies, optimize procurement negotiations, and identify high-potential niches. Access to the complete analysis ensures that your strategic initiatives are built on a foundation of verified, up-to-date market intelligence.
Conclusion
The intersection of advanced materials and civil engineering is creating a new paradigm for infrastructure resilience. Shape memory alloys are moving from the laboratory to the construction site, driven by seismic needs, aging infrastructure, and the pursuit of efficiency. The market outlook through 2032 indicates substantial growth, supported by technological maturation and increasing standardization.
As the industry navigates this transition, informed decision-making will be the differentiator between leaders and laggards. PW Consulting remains committed to providing the analytical rigor and strategic insight necessary to thrive in this dynamic environment. The full market study offers the detailed roadmap required to capitalize on the opportunities presented by the evolving shape memory alloys landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Shape Memory Alloys for Civil Engineering Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com