

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Global CRPG Market Hits $2.54B in 2025, to Reach $3.95B by 2032 at 6.48% CAGR
By pmarketresearch, 2026-09-16
Strategic Horizons: The Worldwide CRPG Games Market Through 2032
The computer role-playing game segment has evolved from a niche enthusiast category into a structurally significant pillar of the global interactive entertainment economy. As narrative depth, player agency, and complex mechanics regain commercial prominence, the CRPG market presents a uniquely resilient demand profile that rewards studios capable of balancing artistic ambition with disciplined production economics. Our newly released Worldwide CRPG Games Market research is designed to give executives, investors, and product leaders a precise analytical foundation for navigating this shifting landscape through 2032.
This report is built for decision-makers who need more than headline revenue figures. It translates historical trajectory, platform allocation, distribution behavior, and competitive intensity into actionable intelligence for portfolio strategy, pipeline prioritization, capital allocation, and go-to-market planning. The following overview outlines the analytical framework, the strategic questions the research answers, and why the 2026 planning cycle makes this intelligence especially timely.
Market Trajectory and the Reshaping of Demand
Over the historical review window from 2020 through 2025, the worldwide CRPG market expanded from approximately USD 1,350.5 million to USD 2,540.0 million, reflecting an acceleration that outpaced earlier expectations. That trajectory was not simply a function of a single breakout release; it emerged from converging demand shifts, including renewed interest in deep narrative systems, stronger audience willingness to invest in premium single-player experiences, and expanding modding ecosystems that extend product lifecycles.
Looking forward across the 2026 to 2032 forecast period, the research projects sustained growth with a compound annual growth rate of 6.48 percent. The market is forecast to reach approximately USD 2,801.97 million in 2026 and continue climbing toward USD 3,947.12 million by 2032. Importantly, this path reflects a maturing category rather than a speculative bubble. The growth curve indicates a market increasingly shaped by franchise continuity, post-launch engagement, and distribution choices that determine how effectively studios monetize long-tail audiences.
For enterprise planning, the strategic implication is clear: CRPG demand is becoming more predictable in direction but more complex in execution. Companies that rely solely on broad genre assumptions will miss the structural nuances that separate durable franchises from short-lived hype cycles.
What the Research Covers and Why It Matters for 2026 Decisions
The Worldwide CRPG Games Market study was engineered to support practical strategic use rather than abstract market description. Its scope spans historical performance mapping, forward-looking demand modeling, segmentation analysis, competitive profiling, and infrastructure-adjacent market dynamics that increasingly shape digital entertainment Economics.
Executives can use the report to answer core questions such as:
- How should organizations size their exposure to CRPG development, publishing, or adjacent service opportunities over the next planning cycle?
- Which platform and distribution behaviors signal durable monetization versus temporary concentration?
- Where do competitive pressures intensify most quickly, and what does that mean for differentiation strategy?
- How do infrastructure, data regulation, and chip availability trends affect development roadmaps and operational cost assumptions?
The report integrates these questions into a decision-oriented structure. Rather than presenting isolated statistics, it contextualizes market sizing within the behaviors that drive value: player retention, franchise lifecycle management, digital distribution dominance, and the strategic choices studios make when balancing scope, narrative complexity, and release cadence.
Segmentation Insight: Platform, Distribution, and Regional Structure
Segmentation is where the CRPG market becomes especially instructive. The research breaks down revenue behavior across platform environments, distribution channels, and regional demand patterns, allowing stakeholders to see where value concentrates and where structural shifts are underway.
Worldwide Roguelike Game Market
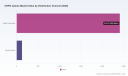
Platform allocation reveals a market still strongly anchored by PC, with consoles representing a substantial secondary base and mobile and handheld devices forming a smaller but strategically relevant segment. This configuration matters because platform choice affects design scope, release timing, audience acquisition cost, and post-launch support models. It also influences how studios plan cross-platform ambitions versus platform-specific optimization. The full segmentation detail in the report allows teams to benchmark platform exposure and model scenario outcomes without relying on assumptions from adjacent genres.
Distribution channel analysis similarly shows a market defined by digital downloads as the dominant commercial pathway, with physical retail maintaining a much smaller footprint. The strategic significance lies not only in the scale difference but in what it implies for logistics, pricing flexibility, direct consumer relationships, and the economics of recurring content updates. Companies evaluating publishing partnerships, storefront strategy, or bundled release models can use the segmentation framework to assess which channel dynamics will shape margin and visibility.
Regional analysis further sharpens the picture by identifying where demand exerts the strongest pull. North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa each present distinct market characteristics, audience expectations, and go-to-market considerations. These regional patterns interact with platform habits, pricing sensitivity, localization priorities, and infrastructure conditions. The report provides regional context in a way that helps strategy teams align development, marketing, and investment decisions with demand geography without overgeneralizing in ways that lead to inefficient resource allocation.
To protect the analytical integrity of the research, granular regional and platform split percentages and exact sub-segment revenue figures are reserved for the full study. This allows the published introduction to demonstrate methodological rigor while ensuring that clients who depend on precise planning parameters are directed to the complete dataset for execution-level work.
Competitive Landscape and Strategic Positioning
CRPG competition is defined less by pure scale than by franchise identity, narrative credibility, system depth, and the ability to sustain active communities over time. The report profiles a range of influential developers and publishers whose approaches illustrate different viable strategies within the category.
Larian Studios demonstrates the commercial power of narrative-driven, choice-rich CRPG design paired with strong post-launch engagement. Obsidian Entertainment highlights the value of dialogue-heavy storytelling and branching narrative systems that cultivate dedicated audiences. BioWare remains associated with cinematic, companion-centered RPG experiences and moral-choice frameworks that influenced broader audience expectations for the genre. CD Projekt Red illustrates the scale achievable through open-world CRPG design with mature themes and strong player agency, along with the operational complexity such ambition entails.
The competitive set also includes studios with more specialized strategic positions. inXile Entertainment reflects sustained interest in classic-style, isometric, party-based design. Owlcat Games shows how licensed intellectual property can be translated into deep CRPG experiences with strong strategic and narrative mechanics. Tactical Adventures underscores demand for turn-based systems inspired by tabletop frameworks. Paradox Interactive bridges grand strategy and role-playing mechanics in ways that expand the definition of audience overlap. Bethesda Game Studios represents expansive open-world design with strong modding ecosystems and player freedom. Square Enix contributes a global publishing and development perspective tied to narrative-heavy RPG output with CRPG influences across certain titles.
Recent developments reinforce how active this competitive field remains. Owlcat Games advanced development on Warhammer 40,000: Dark Heresy with alpha and beta signals and expanded party-based mechanics. Tactical Adventures announced Solasta II with larger environments, refined storytelling, and broader D&D-inspired worldbuilding. Larian Studios continued post-launch support for Baldur's Gate 3, demonstrating how sustained updates and modding pathways can maintain active audience engagement within the CRPG segment.
From a strategy perspective, these moves matter because they reveal how studios balance originality, licensing, sequel development, and community retention. The report uses these examples not as promotional highlights but as strategic evidence points within a broader competitive intensity framework. Market concentration is also examined through a structured lens, showing how competitive share is distributed and where consolidation risk, differentiation opportunity, and audience loyalty converge. Exact concentration metrics beyond the top-level concentration overview are reserved for the full report so that stakeholders can evaluate positioning with the precision required for partnership, investment, and launch planning.
Infrastructure and Regulatory Forces Shaping the Next Cycle
CRPG market strategy cannot be separated from the operational environment in which games are built, distributed, and maintained. The report integrates current industry-context dynamics that increasingly affect cost structures, release feasibility, and regional deployment decisions.
One important backdrop is the pressure on digital infrastructure. Primary North American data center supply increased 36 percent year-over-year to 9,432 MW in 2025, supported by record net absorption of 2,497.6 MW driven by hyperscale demand relevant to game distribution and online features. At the same time, vacancy rates in key North American data center markets reached a record low of 1.4 percent at the end of 2025, limiting large-scale deployments for digital entertainment platforms. The strategic implication is that infrastructure availability and cost conditions can influence hosting plans, online service scaling, update delivery, and broader digital ecosystem planning.
Regulatory forces are equally consequential. Data sovereignty and privacy regulations are driving demand for local or edge data center deployments to comply with cross-border data flow restrictions. In parallel, U.S. export controls on high-performance AI chips are affecting hardware availability for data centers that support game development and cloud features, influencing regional deployment strategies. For CRPG stakeholders, these conditions do more than raise costs; they shape where and how online features, distribution infrastructure, and development pipelines can be scaled.
These factors are included in the report because they connect market opportunity to execution risk. A CRPG strategy that ignores infrastructure constraints or regulatory exposure may overestimate flexibility in digital service design, regional launch sequencing, or post-launch content delivery. By embedding these dynamics into the market analysis, the research gives leaders a more realistic operational frame for planning in 2026 and beyond.
How Organizations Should Use This Research
The Worldwide CRPG Games Market study is intended to support several practical applications. Product and portfolio teams can use it to validate demand assumptions, assess whether proposed CRPG investments align with category trajectory, and benchmark scope decisions against segment realities. Publishing and distribution leaders can use the segmentation and channel analysis to refine storefront strategy, launch sequencing, and digital-versus-physical planning. Investment and business development teams can use the competitive profiling and concentration context to evaluate partnership opportunities, acquisition rationale, and market entry risk.
Worldwide CRPG Games Market
The report also supports scenario thinking. Because CRPG growth is not uniform across platforms, regions, and distribution behaviors, organizations benefit from understanding where resilience is strongest and where volatility may emerge. The 2026 to 2032 forecast framework provides a forward view that can anchor multi-year roadmaps without creating overconfidence in linear outcomes.
Clients relying on the full dataset can further drill into the exact split structures, sub-segment comparisons, and concentration detail needed for quantitative modeling. That is why the complete report is structured to serve both strategic orientation and operational precision.
Conclusion: Why the 2026 Planning Window Is Critical
The CRPG market has entered a phase where narrative quality, system depth, community longevity, and infrastructure-aware planning all influence commercial outcomes. With a forecast CAGR of 6.48 percent and a projected market trajectory from approximately USD 2,801.97 million in 2026 toward nearly USD 3,947.12 million by 2032, the opportunity is real, but so is the need for disciplined segmentation, competitive intelligence, and operational awareness.
This research is designed to help organizations move from general confidence in the category to specific, defensible decisions. The introduction provided here establishes the strategic logic and analytical depth of the study; the full market research delivers the detailed figures, segment-level breakdowns, and competition-specific intelligence necessary for execution. For leadership teams preparing CRPG-related strategy in 2026, the complete report offers the evidence base needed to prioritize investment, shape pipeline direction, and anticipate the infrastructure and regulatory conditions that will increasingly define market performance.
For detailed analysis of this topic, please visit the official page: Worldwide CRPG Games Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Turbocharger Bearing Market Hits $2.15B in 2025, Expand to $3.08B by 2032 at 5.25% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for Executive Decision-Making: The Worldwide Turbocharger Bearing Market Outlook 2026-2032
As the global automotive and industrial sectors navigate a profound transformation driven by electrification, emission regulations, and supply chain realignments, component-level intelligence has become a cornerstone of resilient strategy. Turbocharger bearings, once viewed as commoditized mechanical parts, now sit at the critical intersection of thermal management, fuel efficiency mandates, and performance optimization. PW Consulting's latest Worldwide Turbocharger Bearing Market study delivers a comprehensive, data-backed blueprint designed specifically to equip C-suite leaders, R&D directors, and procurement strategists with the actionable intelligence required to navigate the 2026 commercial landscape and beyond.
Worldwide Turbocharger Bearing Market
Why This Research Matters for 2026 Strategic Planning
The turbocharger bearing ecosystem is experiencing structural shifts that render legacy forecasting models obsolete. Regulatory pressure from Euro 7 standards and EPA Phase 3 heavy-duty engine requirements is forcing original equipment manufacturers to pursue measurable gains in turbo efficiency, directly translating into demand for advanced low-friction bearing architectures. Simultaneously, macroeconomic volatility has reshaped input cost trajectories, with high-strength alloy steel prices climbing sharply in recent cycles due to persistent global supply chain friction. Copper-dependent bronze journal bearings have faced acute cost escalation, compelling manufacturers to reassess material sourcing, supplier contracts, and product portfolio pricing strategies.
In this environment, intuition-driven procurement and reactive capacity planning are no longer viable. Decision-makers require forward-looking visibility into demand inflection points, competitive positioning, and segment-level growth vectors. Our study was engineered to provide exactly that clarity. By anchoring analysis in verified historical data from 2020 through the base year of 2025 and projecting through 2032, the report transforms fragmented market signals into a coherent strategic narrative. It answers the critical questions that boardrooms and operational leaders are asking right now: Where is the market heading, which structural drivers will dominate the next cycle, and how should enterprises position their portfolios to capture durable share?
Macro Trajectory and Growth Architecture
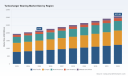
The worldwide turbocharger bearing market has demonstrated consistent expansion over the past half-decade, reflecting both steady vehicle production recovery and incremental technological upgrades across powertrain architectures. Measured in millions of US dollars, the market progressed from 1940.0 in 2023 to 2042.0 in 2024, reaching 2150.0 in 2025. Looking ahead, the forecast period extends from 2026 through 2032, with market size expected to advance to 2262.88 in 2026, continuing its upward trajectory to 3075.89 by 2032. This path reflects a compound annual growth rate of 5.25 percent, signaling a market that is neither stagnant nor explosively speculative, but steadily compounding through technological adoption, regulatory compliance cycles, and sustained demand from both passenger and commercial transport segments.
Such growth is rarely uniform across all operational dimensions. The structural composition of the market reveals a nuanced picture. In terms of bearing technology, journal-based configurations and ball-based architectures represent the two dominant technology pathways, each catering to distinct performance requirements around load capacity, rotational speed, thermal tolerance, and lubrication regimes. Application-wise, the demand base spans passenger vehicles, commercial vehicles, and industrial and heavy-duty engines, with each segment responding to different regulatory timelines, duty cycles, and engineering optimization priorities. Geographic distribution further shapes competitive dynamics, with regional manufacturing footprints, local content requirements, trade policy environments, and logistics networks influencing where capacity is built, where sourcing occurs, and which customer relationships yield the highest strategic returns.
For strategic planners, the core insight is that growth is increasingly driven by structural upgrades rather than pure volume expansion. The push toward downsized engines, hybrid powertrains, and electrified auxiliary systems is reshaping performance benchmarks, while emission mandates are accelerating the adoption of bearing solutions that deliver reduced friction, enhanced durability, and superior thermal stability. Understanding how these segments interact, where substitution risk exists, and which applications will command premium pricing requires a granular view that goes well beyond headline figures.
Competitive Landscape and Strategic Positioning
The turbocharger bearing market is characterized by a moderately concentrated competitive structure, with the top three players commanding approximately 48.5 percent of total market share and the top five extending that reach to roughly 62.2 percent. This concentration signals a landscape where scale, technological differentiation, and long-term customer integration heavily influence commercial outcomes. At the same time, a broader field of specialized manufacturers continues to compete through niche engineering strengths, regional service capabilities, and targeted material innovations.
Among the leading organizations shaping this ecosystem, the Schaeffler Group has established itself as a prominent supplier of journal and foil air bearings across automotive and commercial vehicle applications. Its recent showcase of next-generation foil bearings for electric turbochargers underscores how incumbent players are reinvesting in next-wave architectures as electrification redefines boosting requirements. SKF AB has reinforced its differentiation through hybrid ceramic and air foil bearing solutions optimized for high-speed turbocharger operations, notably introducing hybrid turbocharger bearings with extended durability designed specifically for heavy-duty engines. These product moves reflect a broader trend where bearing longevity and operating envelope expansion are becoming decisive commercial differentiators.
Japanese manufacturers continue to play a central role in the competitive matrix. NTN Corporation manufactures full complement roller and ball bearings for turbochargers deployed in passenger cars and heavy-duty engines, and has emphasized low-friction bearing technologies for downsized turbocharger platforms at major industry exhibitions. NSK Ltd. develops high-temperature angular contact ball bearings engineered for turbocharger shafts, addressing the thermal and load challenges that intensify as combustion and post-combustion systems operate under tighter efficiency tolerances. JTEKT Corporation contributes through its Koyo-brand needle roller and ball bearings tailored for turbocharger applications, reinforcing the breadth of engineering options available to tier suppliers and OEMs seeking optimized shaft support and rotation stability.
North American and European specialists add further depth to the competitive field. The Timken Company offers tapered roller and super precision bearings serving both industrial and automotive turbocharger applications, leveraging its broader precision bearing heritage to address demanding operational environments. RBC Bearings Incorporated specializes in foil air bearings and thrust bearings for turbochargers across aerospace and automotive sectors, demonstrating how bearing expertise in high-performance rotating machinery translates across end markets. Waukesha Bearings Corporation supplies hydrodynamic journal and tilt pad bearings for turbochargers in power generation and marine uses, highlighting how heavy-duty and stationary power applications remain a meaningful demand pillar alongside mobile transport. Taken together, these players illustrate a market where technology leadership, application specialization, and cross-industry capability transfer are all viable pathways to competitive advantage.
Industry Dynamics, Cost Pressures, and Regulatory Forces
Navigating 2026 and the subsequent forecast window requires a clear understanding of the forces that will compress margins, accelerate innovation, or create new barriers to entry. Regulatory frameworks represent one of the most powerful structural drivers. Euro 7 emission standards mandate improved turbo efficiency, directly stimulating demand for advanced low-friction bearings that can support tighter combustion controls and higher boost responsiveness without compromising durability. On the other side of the Atlantic, EPA Phase 3 heavy-duty engine standards require a 25 percent nitrogen oxide reduction by 2027, further boosting turbocharger bearing upgrades as engine manufacturers work to meet stringent output and emissions targets simultaneously. These regulations do more than influence product specifications; they reshape procurement priorities by shifting demand toward higher-performance bearing generations and incentivizing early adoption of engineered solutions that align with compliance timelines.
Raw material dynamics add a parallel layer of strategic complexity. High-strength alloy steel prices for bearings increased by 8 percent in 2023 due to global supply chain disruptions, while copper content in bronze journal bearings faced a 12 percent price hike from mining shortages. These input cost pressures interact directly with pricing architecture, inventory strategy, and supplier diversification planning. Enterprises that rely on single-source supply or rigid contract structures face heightened exposure, whereas organizations that integrate forward-looking material forecasting, alternative alloy evaluation, and multi-region sourcing frameworks are better positioned to protect margins without sacrificing performance. At the same time, trade policy remains a persistent variable. US-China tariffs on automotive components have increased bearing import costs, altering regional cost competitiveness and prompting both suppliers and end users to reevaluate manufacturing footprints, cross-border logistics, and regional substitution strategies.
Turbocharger Market
What the Study Delivers for Strategic Teams
PW Consulting's Worldwide Turbocharger Bearing Market research is structured to move beyond descriptive market sizing and deliver operational intelligence that can be embedded directly into planning cycles. The report provides a detailed examination of market segmentation across technology types, application categories, and regional distributions, allowing teams to benchmark demand concentrations, identify where growth is accumulating, and understand the practical implications for product roadmaps and commercial strategy. The analysis is anchored in verified historical performance and a forward-looking forecast architecture, enabling scenario planning rather than static target setting.
Beyond segmentation, the study delivers a competitive assessment that maps out the strategic behaviors of leading manufacturers, including their product focus, regional presence, and recent commercial developments. It examines how companies are responding to performance requirements through material innovation, design optimization, and targeted exhibition and product launch activity. The research also integrates regulatory, macroeconomic, and supply-side dynamics so that strategic readers can connect market growth with the operational realities that shape execution, such as material cost exposure, compliance-driven specification upgrades, and trade-related cost redistribution.
For procurement and supply chain leaders, the findings provide context for sourcing decisions, supplier evaluation frameworks, and inventory planning in an environment where input volatility and regulatory shifts can quickly alter the cost-performance equation. For product strategy and engineering teams, the report offers insight into technology migration patterns, application-specific performance demands, and the operational implications of bearing architecture choices. For commercial and corporate development professionals, it supports competitive positioning assessments, partnership evaluation, and market entry or expansion planning by clarifying where share is evolving and which capabilities are most closely associated with durable competitive advantage.
Translating Market Intelligence into 2026 Advantage
The strategic value of this research lies in its ability to connect macroeconomic indicators, technology trends, and competitive behavior into a coherent decision-support framework. A 5.25 percent compound annual growth trajectory over a seven-year forecast period is not merely a number; it is a signal about the pace of structural adoption, the timing of capital allocation, and the window of opportunity for organizations that align their portfolios with emerging demand. Market size progression from 2150.0 in 2025 to projected levels above 3000.0 by 2032 reflects a market where incremental performance gains, regulatory compliance, and application expansion will continue to drive commercial activity. Recognizing which applications, technologies, and geographies will carry the greatest strategic weight requires the depth and segmentation detail that this study provides.
Leaders who act on this intelligence can better calibrate product development priorities, anticipate competitive pressure points, and structure supplier relationships to reduce exposure to input cost volatility and trade disruptions. They can evaluate whether their current bearing portfolios align with the trajectory of emission mandates and powertrain evolution, and they can identify where differentiation is likely to shift from cost competition to engineering performance and reliability. In a market with meaningful concentration at the top and active competition across specialized niches, timing and positioning matter as much as scale.
Access the Full Strategic Blueprint
This overview outlines the strategic context, competitive architecture, and operational dynamics that make the Worldwide Turbocharger Bearing Market a critical focus area for 2026 planning. Yet many of the most valuable insights, including detailed segmentation trajectories, regional and application-level demand patterns, specific competitive positioning metrics, and forward-looking scenario frameworks, are developed in full within the complete research document. For executive teams that need granular data, comparative benchmarks, and actionable recommendations tailored to real operating decisions, the full report provides the depth required to move from strategic awareness to execution-ready intelligence.
To obtain the complete Worldwide Turbocharger Bearing Market study and integrate its findings into your 2026 strategic planning, procurement models, and portfolio decisions, access the full report through PW Consulting's official research portal and secure the comprehensive market intelligence your organization needs to compete with precision in the years ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Turbocharger Bearing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: SPECT Camera Market Hits $2,195M in 2025, Projected to Reach $3,305M by 2032 with 6.02% CAGR
By pmarketresearch, 2026-09-16
Strategic Horizon 2026: Unlocking Value in the Global SPECT Camera Market
Executive Summary
The global landscape for Single Photon Emission Computed Tomography (SPECT) imaging is undergoing a transformative shift. As healthcare systems worldwide pivot toward precision medicine and value-based care, the demand for advanced molecular imaging solutions has never been more critical. Our latest Worldwide SPECT Camera Market research provides a comprehensive roadmap for navigating this evolution through 2032. For strategic decision-makers operating in 2026, understanding the trajectory of this market is not merely an academic exercise; it is a prerequisite for capital allocation, product development, and competitive positioning.
This report synthesizes historical performance from 2020 through 2025 with robust forecasts extending to 2032. The analysis reveals a sector characterized by steady growth, technological consolidation, and shifting regulatory dynamics. With the total market valuation reflecting significant expansion over the past half-decade, stakeholders must look beyond surface-level metrics to understand the underlying drivers of revenue. This article serves as a primer to the full study, highlighting the strategic imperatives that will define success in the coming years.
Market Trajectory and Growth Vectors
The historical data indicates a resilient market that has rebounded strongly following global disruptions. From 2020 to 2025, the industry demonstrated a clear upward trend, culminating in a baseline valuation that sets the stage for the forecast period. The growth is not linear; it is propelled by specific technological adoptions and clinical shifts that vary across segments. Our analysis projects a Compound Annual Growth Rate (CAGR) of 6.02 percent throughout the forecast period ending in 2032. This figure suggests a maturing market that is still capable of substantial expansion, driven by the replacement cycle of legacy equipment and the introduction of high-sensitivity systems.
Revenue projections indicate that the market will continue to scale significantly, moving from recent valuations toward higher thresholds by the early 2030s. However, the aggregate numbers only tell part of the story. The real value for strategists lies in understanding the velocity of adoption across different system types and clinical applications. The shift from standalone systems to hybrid SPECT/CT configurations represents a fundamental change in procurement behavior among hospitals and imaging centers. This transition is influencing not only hardware sales but also the ecosystem of consumables and software services that accompany these installations.
Technological Divergence and System Segmentation
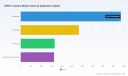
The market is currently defined by a divergence in technology platforms, each catering to specific clinical needs and operational constraints. Hybrid SPECT/CT Systems dominate the revenue share, reflecting the industry consensus that anatomical correlation enhances diagnostic confidence. These systems are becoming the standard for oncology and complex cardiology cases where precise localization is paramount. The integration of computed tomography with nuclear medicine data has streamlined workflow, reducing the time required for diagnosis and improving patient throughput.
Conversely, Standalone SPECT Systems maintain a presence, particularly in cost-sensitive environments or specialized facilities where CT infrastructure is already available or unnecessary for the specific clinical question. While their share is smaller compared to hybrid units, they remain vital for basic perfusion studies and regions where budget constraints dictate procurement. Additionally, Dedicated Cardiac SPECT systems represent a niche but critical segment. Given the prevalence of cardiovascular disease globally, these specialized units offer optimized protocols for myocardial perfusion imaging, balancing cost efficiency with high diagnostic accuracy for heart disease.
Strategists must pay close attention to the technological arms race between manufacturers. The differentiation is no longer just about resolution; it is about workflow integration, dose reduction, and scan speed. Companies that can demonstrate tangible improvements in patient experience—such as reduced scan times or lower radiation exposure—are gaining traction in competitive tenders. This technological premium is a key factor in the pricing structures observed across different regions and hospital networks.
Clinical Applications Driving Demand
The application landscape is equally pivotal in understanding market dynamics. Cardiology remains the primary driver of SPECT imaging volume. Myocardial perfusion imaging continues to be a cornerstone in the diagnosis and management of coronary artery disease. As the global burden of cardiovascular conditions rises, the reliance on nuclear cardiology for risk stratification ensures steady demand for both equipment and radiotracers. The integration of AI-enabled quantification tools is further enhancing the utility of cardiac SPECT, allowing for more precise assessment of blood flow and myocardial viability.
Oncology represents a rapidly growing application segment. The use of SPECT for tumor imaging, bone scans, and the localization of specific receptors is expanding alongside the growth of personalized oncology. Hybrid systems are particularly valuable here, enabling clinicians to correlate functional metabolic data with anatomical structures. This synergy supports better staging, treatment planning, and follow-up monitoring. As new radiopharmaceuticals gain approval, the versatility of SPECT technology positions it as a complementary tool to PET imaging in many healthcare settings.
Neurology and Orthopedics also contribute significantly to the market footprint. In neurology, SPECT is utilized for evaluating dementia, epilepsy, and cerebrovascular diseases. While the volume may not match cardiology, the complexity of these cases often requires high-resolution imaging capabilities. In orthopedics and other specialties, the technology aids in detecting infections, fractures, and bone metabolism disorders. A diversified application base provides stability to the market, insulating it from fluctuations in any single clinical area.
Competitive Landscape and Strategic Positioning
The market concentration is notable, with the top three players commanding a significant portion of the revenue. This concentration indicates high barriers to entry regarding regulatory compliance, distribution networks, and technological R&D. However, regional players and specialized innovators are carving out niches by focusing on specific technologies such as CZT detectors or digital imaging platforms.
GE HealthCare remains a dominant force, leveraging its extensive installed base and continuous innovation in SPECT/CT systems. Their recent clearances for evolution models highlight a focus on AI-enabled quantification, particularly for cardiology. Siemens Healthineers is equally aggressive, integrating intelligent imaging features into their Symbia family to optimize workflow. Their recent FDA clearances underscore a commitment to AI-driven process optimization, which appeals to high-volume centers looking to reduce staffing burdens.
Philips Healthcare continues to compete with systems optimized for low-dose applications, addressing the growing concern over radiation exposure. Meanwhile, Spectrum Dynamics Medical is disrupting the market with CZT-based technology, promising higher resolution and faster scans. This technological differentiation allows them to challenge incumbents in specific high-end segments. United Imaging Healthcare represents the rising influence of manufacturers from Asia, offering digital detectors and whole-body imaging capabilities that compete on performance and value. Mediso rounds out the competitive field with a focus on both preclinical and clinical molecular imaging, providing flexibility for research hospitals and specialized clinics.
Strategic partnerships and regulatory milestones are key indicators of future market share. Recent FDA clearances for systems like the Symbia Pro.Spect AI and the VERITON-CT scanner demonstrate the regulatory pathway active in 2024 and 2025. These approvals are not just compliance checkboxes; they are market access enablers that allow manufacturers to expand their footprint in key regions like the United States. Companies that navigate the 510(k) process efficiently gain a first-mover advantage in deploying next-generation technology.
Regulatory and Reimbursement Dynamics
Navigating the regulatory environment is a critical component of market strategy. SPECT cameras are classified as Class II devices, requiring 510(k) premarket notification in the United States. This regulatory framework ensures safety and efficacy but also imposes timelines and costs that influence product launch strategies. Compliance with standards such as IEC 61223-3-1 for evaluation and routine testing is mandatory for acceptance and quality control, affecting both manufacturers and end-users.
Reimbursement policies directly impact the adoption rate of imaging procedures. CPT codes covering myocardial perfusion SPECT imaging dictate the revenue cycle for providers. Variations in reimbursement rates by payer can influence which procedures are prioritized within a hospital system. Furthermore, bundled payments under DRG groups for acute myocardial infarction include SPECT procedures, creating incentives for efficient diagnosis to manage overall episode costs. Understanding the interplay between procedure codes, payer policies, and hospital budget cycles is essential for forecasting demand accurately.
Professional societies also play a role in shaping market standards. Guidelines such as the SNMMI Procedure Standard outline minimum performance specifications for general SPECT imaging systems. Adherence to these standards ensures consistency in image quality and diagnostic reliability, which indirectly supports the demand for high-quality equipment that meets these specifications. Manufacturers must align their product development with these evolving standards to maintain credibility and market access.
PET and SPECT Scanners Market
Regional Insights and Market Heterogeneity
While global aggregates provide a top-down view, regional heterogeneity dictates tactical execution. Market maturity, healthcare infrastructure, and reimbursement landscapes vary significantly across geographies. In North America, the market is characterized by high adoption rates of advanced hybrid systems and a strong focus on technological upgrades. The presence of major manufacturers and established distribution channels supports a robust ecosystem.
Europe presents a mixed landscape where national health systems and private providers coexist. Regulatory harmonization within the region facilitates cross-border equipment deployment, but reimbursement variations between countries can affect pricing strategies. Asia Pacific represents a growth frontier, driven by expanding healthcare access and increasing prevalence of lifestyle-related diseases. The demand here is often value-conscious, yet the volume potential is substantial for manufacturers who can offer scalable solutions.
Latin America and the Middle East and Africa regions operate with different dynamics, often influenced by procurement budgets and infrastructure development. In these markets, reliability and service support are often as critical as initial purchase price. Understanding the specific procurement cycles and regulatory requirements in these regions is vital for companies looking to expand their global footprint. The distribution of revenue across these regions highlights where investment and sales efforts should be prioritized over the forecast period.
Strategic Imperatives for 2026 and Beyond
For corporate strategists, the implications of this market analysis are clear. First, investment in hybrid technology should be a priority, as the shift toward integrated SPECT/CT continues to dominate procurement trends. Second, differentiation through software and AI capabilities is becoming a key battleground. Hardware specifications are converging, but workflow solutions that reduce time and improve accuracy offer a unique value proposition.
Third, monitoring regulatory and reimbursement changes is non-negotiable. Shifts in policy can alter the economic viability of certain procedures overnight. Companies must maintain agile compliance teams and active dialogue with payers and policymakers. Fourth, regional customization is essential. A one-size-fits-all approach fails in a market where clinical needs and economic constraints vary so widely.
Finally, the competitive intensity suggests that mergers, acquisitions, or strategic partnerships may accelerate as companies seek to fill technology gaps or expand geographic reach. The high concentration among top firms indicates that scale matters, but niche players with superior technology can still disrupt established relationships. Stakeholders should assess their supply chain resilience and R&D pipelines against these competitive pressures.
Conclusion and Next Steps
The Worldwide SPECT Camera Market is on a defined growth path, underpinned by clinical necessity and technological advancement. The data from 2020 to 2032 paints a picture of an industry that is expanding steadily while undergoing significant structural change. The 6.02 percent CAGR reflects confidence in the modality's long-term relevance, even as new imaging technologies emerge.
However, aggregate data alone is insufficient for precise planning. The nuances of segmentation, regional pricing, competitor roadmaps, and specific regulatory hurdles require deeper examination. Our full market research report provides the granular intelligence needed to translate these high-level trends into actionable strategies. It includes detailed breakdowns of market sizes, competitive profiling, and scenario analyses that go beyond the summary provided here.
Worldwide SPECT Camera Market
To access the complete dataset, including specific revenue figures by region and application type, as well as comprehensive profiles of all key market participants, we invite you to explore the full report. Equip your organization with the precise intelligence needed to navigate the complexities of the SPECT camera market through 2032. Contact our research team or visit the product page to secure your copy of the full study.
For detailed analysis of this topic, please visit the official page: Worldwide SPECT Camera Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Smart Thermometer Patch Market Hits $812.45M in 2025, Projects 10.45% CAGR Through 2032
By pmarketresearch, 2026-09-16
Global Smart Thermometer Patch Market: Strategic Intelligence for 2026 Decision-Makers
Market Trajectory and the Case for Deep-Dive Intelligence
The global smart thermometer patch market has transitioned from a niche innovation to a structurally significant segment of the digital health and continuous remote monitoring ecosystem. Between 2020 and 2025, cumulative revenue expanded from approximately 495.2 million USD to 812.45 million USD, reflecting sustained commercialization momentum across both disposable and reusable product architectures. As we enter the 2026-2032 forecast horizon, the market is projected to scale to roughly 1.63 billion USD by 2032, supported by a compound annual growth rate of 10.45 percent. This trajectory is not merely a function of incremental demand, but of converging clinical workflows, regulatory pathway maturity, and patient-centric care models that increasingly prioritize continuous axillary temperature tracking over intermittent manual measurement.
For executives, investors, and product strategists, the critical question for 2026 is no longer whether smart thermometer patches will gain share, but how to position operations, supply chains, and commercial roadmaps against a landscape defined by fragmented application use cases, geographically uneven adoption, and an increasingly scrutinized regulatory environment. This research briefing is designed to move procurement, clinical affairs, and market development teams past headline-level awareness and into a structured, decision-ready intelligence framework. The following narrative previews the analytical dimensions covered in the full Worldwide Smart Thermometer Patch Market study, helping leadership assess where actionable intelligence will most materially influence capital allocation, partnership strategy, and product positioning in the coming planning cycle.
The macro trajectory underscores a market that has consistently compounded its valuation across the 2020-2025 historical window, with year-over-year expansion that signals durable end-user pull rather than one-off pandemic-era adoption. The 2026 baseline of approximately 870 million USD serves as the launch point for a forecast curve that accelerates through the latter half of the decade. Strategic planners evaluating expansion, R&D prioritization, or channel build-out must recognize that this growth is distributed unevenly across product formats, clinical and consumer applications, and regional ecosystems. Decoding that distribution, the operational constraints attached to it, and the competitive responses shaping it is the core purpose of the full report.
Structural Segmentation and the Strategic Implications of Product, Application, and Regional Architecture
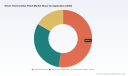
Understanding where value concentrates, and why, begins with a disciplined examination of the market's structural layers. The full study decomposes the landscape across three interdependent segmentation axes: product type, application end-use, and geographic region. At the product level, the commercial ecosystem is anchored by single-use patches and reusable patches, each with distinct cost structures, clinical adoption drivers, replacement cycles, and supply chain considerations. Single-use architectures typically emphasize streamlined hospital and home-care deployment, reduced sterilization or reprocessing burden, and predictable unit economics tied to episodic monitoring or short-duration admission pathways. Reusable architectures, by contrast, are built around longer operational lifespans, rechargeable or extended-battery designs, and recurring value propositions tied to remote patient monitoring programs and chronic or longitudinal care. The strategic tension between these two formats is not simply about unit price; it is about reimbursement alignment, clinical workflow fit, waste and sustainability considerations, and the degree to which procurement organizations prefer consumable procurement versus capital-audited device programs.
The application layer adds another level of strategic complexity. Pediatric monitoring continues to represent a highly sensitive end-use environment, where caregiver anxiety, fever escalation risk, and the need for contactless or low-friction monitoring drive adoption. Remote clinical monitoring reflects a broader shift toward decentralized care and hospital-to-home transitions, where continuous temperature data is integrated into broader vitals dashboards and used to support early intervention logic. Fertility and ovulation tracking introduces a more consumer-facing, longitudinal use case, where temperature trends serve as an informational signal within broader reproductive health workflows. Each application pathway carries different purchase decision dynamics, user experience expectations, evidence requirements, and channel strategies. A product engineered for pediatric fever detection will face fundamentally different commercial and regulatory demands than one optimized for remote clinical deployment or consumer fertility tracking, even if the underlying sensing technology shares common foundations.
Regionally, the market reflects distinct maturity curves, reimbursement pressures, and healthcare infrastructure realities. North America remains a central anchor of commercial activity and regulatory precedent, supported by established hospital procurement mechanisms, growing home-care programs, and clearDevice classification pathways. Europe operates under a different compliance architecture, where quality management rigor and regional device regulation shape market entry and ongoing commercialization. Asia Pacific presents a structurally large and rapidly evolving opportunity set, characterized by expanding manufacturing capability, growing domestic demand, and varied regional adoption speeds across different healthcare systems. Latin America and the Middle East and Africa collectively represent smaller but strategically meaningful volumes, often shaped by import dynamics, pilot-based procurement, and the pace at which local care delivery models integrate continuous monitoring tools. The full report examines how these regional profiles interact with product format and application mix to shape where commercial traction is achieved, where scaling is constrained, and where competitive displacement risk is most pronounced.
Application-Layer Dynamics and Decision-Making Divergence
- Pediatric monitoring environments require designs that balance caregiver ease-of-use with clinically credible fever detection, often reinforcing disposable or short-duration patch adoption in domestic and outpatient contexts.
- Remote clinical monitoring pathways favor reusable or extended-life architectures that support integrated care teams, continuous data flow, and operational efficiency across hospital-to-home transitions.
- Fertility and ovulation tracking depends heavily on longitudinal trend interpretation, app experience, and consumer trust, creating differentiation opportunities beyond raw temperature accuracy alone.
- Each application layer imposes distinct evidence expectations, pricing assumptions, and partner ecosystems, meaning that a single product strategy rarely fits all commercial scenarios.
Competitive Landscape and the Emerging Battlegrounds
The market's competitive fabric is defined by a mid-tier concentration structure in which a limited set of established and emerging players collectively shape category standards, dissemination patterns, and procurement expectations. Concentration metrics indicate that the top three participants capture roughly 38.5 percent of market revenue, while the top five account for approximately 52.3 percent. This structure suggests a market that is not yet dominated by a single consolidated incumbent, but is nevertheless moving toward an environment where credible clinical endorsements, regulatory clearances, and workflow integration capabilities increasingly separate scaled participants from narrower niche offerings.
Worldwide Smart Thermometer Patch Market
Blue Spark Technologies has built its positioning around a Class II, FDA-cleared, disposable wireless continuous monitoring patch designed for extended axillary monitoring with Bluetooth connectivity. Its commercial narrative emphasizes early fever detection in hospital and home-care settings, aligning with institutional buyers seeking reliable, low-friction temperature surveillance for at-risk patient populations. VivaLNK Inc. has pursued a reusable, rechargeable axillary patch path, holding FDA clearance, CE marking, and NMPA approval, with an emphasis on IoT integration and extended battery life supporting remote patient monitoring across longer deployment cycles. SteadySense GmbH has oriented its offering around medical-grade, NFC-enabled measurement accuracy and compliance with quality management and regional device regulations, targeting both clinical and home use with a strong precision positioning. iWEECARE Co., Ltd. has entered the space with a compact Bluetooth patch cleared for continuous axillary temperature monitoring, addressing fever tracking, fertility, and remote patient monitoring use cases through a compact, connectivity-focused design. Guangdong Genial Technology Co., Ltd. has advanced a reusable Bluetooth-enabled axillary patch with app connectivity, and its recent regulatory clearance underscores how quickly the competitive field is being reshaped by new market entrants securing clearance pathways for continuous monitoring formats. Helyxon Healthcare Solutions Pvt Ltd has focused on a continuous Bluetooth temperature monitoring system with app-based real-time alerts, emphasizing pediatric and hospital use and reinforcing how regional players are targeting both institutional and caregiver-facing demand.
From a strategic standpoint, the competitive dynamics are less about who offers the highest specification on paper and more about who can convert clinical-grade accuracy, clearance status, and connectivity into procurement-ready value propositions. The differentiators that matter in 2026 include the durability of regulatory positioning, the practicality of deployment at scale, the integration footprint with existing monitoring or EHR-adjacent workflows, battery or consumable economics, and the credibility of clinical and real-world evidence supporting fever detection, remote monitoring workflows, and longitudinal temperature trend interpretation. The full report provides a deeper company-by-company assessment that maps these positioning choices against specific product architectures, application targeting, and the likely pressure points each competitor faces as adoption broadens.
Key Competitive Pressure Points
- Regulatory clearance breadth and maintenance capability increasingly determine which players can access institutional procurement and cross-border commercialization.
- Disposable versus reusable economics shape not only unit pricing, but also procurement category treatment, waste management expectations, and total cost of ownership calculations.
- Connectivity and data integration readiness influence whether a patch is adopted as a standalone device or as part of a broader remote monitoring program.
- Clinical accuracy, reliability, and ease of use remain the non-negotiable floor, but differentiation is increasingly earned through workflow fit and evidence depth.
Regulatory Dynamics, Technical Standards, and Market Access Realities
Regulatory classification and standards compliance form the operational backbone of market access in this category. Smart thermometer patches are generally classified as Class II clinical electronic thermometers under applicable regulatory frameworks governing continuous axillary temperature monitoring, requiring demonstration of substantial equivalence through appropriate premarket clearance pathways. This classification creates a baseline expectation: product developers and commercializing firms must navigate clearance requirements, maintain documentation discipline, and ensure that performance claims align with cleared indications. Accuracy expectations are closely tied to recognized clinical electronic thermometer standards, with the field increasingly oriented toward measurement precision at or near ±0.1°C or ±0.2°F, depending on the applicable conformance requirement. Devices that meet these performance thresholds have a structural advantage in institutional procurement, where temperature reliability directly affects clinical confidence.
In European markets, the compliance conversation extends beyond accuracy alone to include quality management certification and alignment with regional medical device regulation. ISO 13485 certification and MDR-compliant documentation practices are increasingly expected components of commercial readiness and are often evaluated by procurement, clinical affairs, and quality assurance teams before adoption is authorized. These compliance layers do not simply represent administrative overhead; they shape the speed of market entry, the credibility of product positioning, and the operational resilience of manufacturers facing audits, post-market surveillance obligations, and cross-border distribution requirements. For organizations assessing partnership, supplier qualification, or in-house development pathways, understanding the compliance burden associated with each product format and target region is essential to realistic timeline planning and risk modeling.
The report's dynamics section examines these regulatory and technical realities as live commercial forces rather than abstract compliance items. It situates clearance status, accuracy conformance, and quality system maturity within the broader context of procurement decision-making, reimbursement sensitivity, and the practical question of how a patch moves from approved device to routinely deployed monitoring solution in a given care setting. This is especially relevant for 2026 planning, where market participants are likely to encounter both new entrants accelerating through clearance and established players tightening their evidence and post-market documentation to defend institutional relationships.
Connected Wearable Patches Market
Report Architecture: Operational Content Designed for Decision Use
The full Worldwide Smart Thermometer Patch Market study is constructed to support applied decision-making rather than passive information consumption. It combines a macro-level market trajectory review with detailed structural segmentation, enabling readers to trace how revenue flows across product types, application pathways, and regional markets without relying on top-line aggregates alone. The research is organized to support parallel workstreams: corporate strategy teams can use the segmentation and dynamics sections to assess where to compete and how to sequence entry or expansion; product and clinical teams can use the regulatory and competitive sections to benchmark clearance positioning, accuracy-oriented differentiation, and workflow integration opportunities; and commercial and supply chain teams can use the regional and application analysis to prioritize distribution models, channel partnerships, and procurement-aligned value propositions.
Beyond the segmentation and competitive mapping, the report provides forward-looking context for the 2026-2032 period, including the demand drivers most likely to shape procurement volume, the clinical and consumer scenarios expected to generate sustained patch utilization, and the operational constraints that may slow or accelerate adoption in specific regions or application verticals. It also includes recent market developments and clearance events that illustrate how quickly the category is evolving, helping readers distinguish between durable structural shifts and temporary competitive noise. The intention is to give leadership a working map of the market's value creation logic, not a static snapshot of where the market stands today.
Strategic Takeaways for 2026 Planning and How to Use This Intelligence
For organizations planning in 2026, the smart thermometer patch market presents a rare combination of category growth, segmentation diversity, and competitive flux. The projected trajectory toward a multi-billion-dollar scale by 2032 implies that early positioning choices, partnership decisions, and evidence-generation strategies will have long-lasting effects on market access and competitive defensibility. Teams that treat the category as a single product opportunity risk misreading where value is actually created. Teams that instead map the interplay between product format economics, application-specific purchase drivers, regional compliance realities, and competitor positioning will be better equipped to allocate resources, prioritize clinical evidence, and build commercially credible go-to-market narratives.
The complete study translates these strategic themes into a structured analytical foundation, enabling readers to identify the most consequential opportunities and risks for their specific context. Because the most actionable detail, including granular segmentation figures, company-level positioning assessments, and region-by-region commercial dynamics, is developed in depth within the full report, the most effective next step for decision-makers is to use this overview as a framing tool and then move to the detailed intelligence for quantification and scenario planning. The 2026 planning window rewards early clarity, and this research is designed to provide exactly that clarity at the point where market growth, clinical utility, and competitive pressure intersect.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Thermometer Patch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Niraparib Market Hits $1.18B in 2025, Set for $2.68B by 2032 at 12.43% CAGR
By pmarketresearch, 2026-09-16
Navigating the Next Phase of Niraparib Growth: Strategic Intelligence for 2026 Decision-Makers
The Imperative for Precision Intelligence in Oncology Markets
The global landscape for poly (ADP-ribose) polymerase (PARP) inhibitors has entered a mature yet dynamically expanding phase, where competitive differentiation is increasingly defined by indication expansion, partnership structuring, and regulatory agility. As pharmaceutical leaders, investors, and market access strategists plan their portfolios for 2026, relying on fragmented secondary sources or legacy projections introduces significant strategic risk. This is precisely the gap our newly released Worldwide Niraparib Market research report is engineered to close. Designed as a decision-grade intelligence asset, the study translates multi-year epidemiological shifts, commercialization trajectories, and regulatory milestones into an actionable roadmap for enterprise planning.
Drawing on historical performance data spanning 2020 through 2025 and forward-looking projections through 2032, the report captures a market that has demonstrated remarkable compounding momentum. In 2020, global niraparib revenues stood at approximately $520.4 million, accelerating to $1.18 billion by 2025, with the trajectory projected to reach roughly $2.68 billion by 2032. This expansion reflects a compound annual growth rate of 12.43 percent, a figure that signals sustained commercial viability rather than transient momentum. For executives evaluating capital allocation, pipeline prioritization, or market entry timing, these macro indicators establish a foundational baseline. However, the true strategic value lies beyond the headline numbers. Our analysis isolates the structural drivers behind this growth, mapping how indication breadth, regional commercialization architectures, and formulation dynamics interact to shape revenue realization across different business models.
The report will be distributed and consumed as a comprehensive reference tool for strategy, business development, and market access teams. Rather than treating niraparib as a single-product narrative, we frame it within a multi-actor ecosystem where originator rights, territory-specific licensing, API supply chains, and companion diagnostics converge to determine market access and pricing leverage. For organizations preparing for 2026 and beyond, the study offers the analytical rigor required to anticipate shifts in competitive positioning, regulatory pathways, and reimbursement environments before they materialize in quarterly earnings calls or competitor press releases.
Decoding the Commercial Architecture: Indication Expansion and Dosage Dynamics
Niraparib's commercial story has evolved from a focused maintenance therapy in advanced ovarian, fallopian tube, and primary peritoneal cancers into a broader oncology asset with expanding therapeutic relevance. Our segmentation analysis provides granular visibility into how revenues are distributed across clinical indications, enabling stakeholders to assess where commercial gravity is concentrated and where incremental growth vectors are emerging. Ovarian cancer remains the dominant indication, reflecting niraparib's established positioning in maintenance treatment paradigms. Prostate cancer represents a structurally distinct and rapidly evolving revenue stream, driven by targeted combinations and molecularly defined patient populations. Additional solid tumor applications contribute a more specialized but strategically important share, often serving as platforms for clinical expansion and label broadening.
Equally critical to commercial planning is the dosage form architecture. The market reflects a clear preference for capsule-based formulations, which currently capture the majority of realized revenue, while tablet formats represent a meaningful complementary segment. For manufacturers, distributors, and market access teams, understanding formulation-level consumption patterns is essential for supply chain forecasting, packaging strategy, and payer negotiations. These dynamics are not static; they respond to clinical convenience, adherence considerations, and regulatory label evolution. Our report details how dosage form preferences intersect with patient population characteristics and prescribing behavior, giving commercial leaders a clearer view of where operational adjustments can protect or expand market share.
Worldwide Imbruvica Market
Importantly, the analysis does not stop at static segmentation snapshots. The study tracks how indication momentum and formulation adoption interact over the forecast horizon, enabling scenario-based planning for teams evaluating market penetration timelines, regional launch sequencing, or partnership structuring. By connecting clinical positioning to commercial outcomes, the report equips decision-makers with a more precise lens for evaluating which growth drivers are structural and which are contingent on regulatory or reimbursement developments.
Worldwide Niraparib Market
Competitive Ecosystem and the Strategic Role of Partnerships
Niraparib's market structure is highly concentrated, with a small number of players controlling the majority of commercial rights and supply pathways. This concentration shapes pricing behavior, launch timing, and the competitive intensity of indication expansion. At the core of the ecosystem, GlaxoSmithKline operates as the originator and primary marketer of ZEJULA, holding global commercialization rights outside specific partnered territories following its acquisition of Tesaro. GSK's leadership position is reinforced by continuous label optimization and strategic regulatory engagement, including recent prescribing information updates that refine dosage and administration guidance for maintenance treatment in ovarian cancer. These updates demonstrate how originator companies can sustain commercial relevance by aligning label language with evolving clinical practice.
Janssen Biotech, a Johnson & Johnson company, represents a strategically distinct contributor, holding exclusive rights outside Japan to niraparib in prostate cancer. This focused indication portfolio has enabled Janssen to build a differentiated commercial narrative, most notably through AKEEGA, a dual-action tablet combining niraparib with abiraterone acetate. Recent regulatory activity underscores the acceleration of this prostate cancer strategy: the U.S. FDA granted Priority Review for a supplemental new drug application for AKEEGA in BRCA-mutated metastatic castration-sensitive prostate cancer, followed by approval for expanded use in BRCA2-mutated metastatic castration-sensitive prostate cancer with prednisone. These milestones do more than expand indication coverage; they signal a broader shift toward molecularly targeted combination regimens in prostate oncology, where niraparib is positioned as a critical component of combination-based treatment architecture.
The commercial architecture is further shaped by territory-specific partners who localize execution and navigate regulatory and reimbursement complexities. Zai Lab Limited operates as GSK's commercialization partner for niraparib in Greater China under a licensing agreement, providing localized market access and distribution capabilities. Takeda Pharmaceutical holds exclusive rights to develop and commercialize niraparib in Japan through a legacy TESARO licensing agreement, reflecting how regional rights structures can preserve long-term market participation even when global originator control is consolidated elsewhere. These partnership models are central to understanding how niraparib reaches distinct patient populations while navigating varying healthcare system requirements.
Below the branded commercial layer, a network of API manufacturers supports supply chain resilience and regional formulation capacity. Companies such as Biophore India Pharmaceuticals, TAPI Technology & API Services, Sichuan Qingmu Pharmaceutical, Anhui Provincial, and Dr. Reddy's Laboratories operate as active suppliers within the niraparib API ecosystem, each with differing capabilities and market presence. For stakeholders evaluating supply security, cost structures, or potential generic entry timelines, mapping these upstream participants is essential. The report provides a structured view of this supplier landscape, helping procurement, business development, and competitive intelligence teams distinguish between manufacturing capability and commercial market impact.
Regulatory Catalysts, Diagnostic Integration, and Reimbursement Intelligence
Market performance in oncology therapeutics is increasingly inseparable from regulatory timing, diagnostic availability, and access negotiations. Niraparib's recent trajectory illustrates how closely these forces interact. In March 2026, the FDA approved Myriad Genetics' MyChoice CDx test as a companion diagnostic for niraparib in HRD-positive advanced ovarian cancer patients. The approval of a companion diagnostic is not merely a clinical milestone; it defines the eligible patient universe, influences testing adoption pathways, and shapes the economics of prescriber behavior. For market access strategists, diagnostic integration introduces both opportunity and complexity, because reimbursement for testing can directly affect therapy uptake and treatment sequencing.
On the regulatory front, GSK's June 2025 label update for ZEJULA demonstrates how ongoing engagement with prescribing information can reinforce clinical clarity and support appropriate use. Meanwhile, Janssen's late-2025 regulatory activity surrounding AKEEGA reflects the growing importance of combination product pathways in competitive oncology markets. The approval of AKEEGA for BRCA2-mutated metastatic castration-sensitive prostate cancer under Priority Review, alongside the earlier Priority Review filing, indicates that regulators are actively creating pathways for molecularly defined prostate cancer populations. These developments matter for forecasting because indication approvals can restructure competitive positioning, expand addressable populations, and shift payer expectations around value demonstration.
Reimbursement and access dynamics add another layer of strategic complexity. GSK's reported global net revenues for ZEJULA in 2025 reached approximately $1.8 billion, a figure that highlights the commercial scale already achieved while also underscoring the importance of sustained access performance across major markets. At the same time, patent protection remains a central variable in long-term market planning. Core U.S. patents for ZEJULA extend to March 2038 for compositions and January 2039 for formulations, and as of April 2026, no generic versions have been approved. This patent posture influences the timing of competitive entry, the durability of pricing power, and the strategic calculus for both originator teams and potential market entrants.
Our report integrates these regulatory, diagnostic, and access variables into a cohesive view of market dynamics. Instead of treating them as isolated news items, the analysis maps how they compound over time, affecting launch sequencing, patient identification, reimbursement negotiations, and competitive response. For organizations building 2026 plans, this integrated perspective reduces uncertainty and supports more resilient assumptions about uptake curves, pricing environments, and competitive pressure points.
Strategic Takeaways for 2026 and Beyond
For executives and analysts operating in the niraparib space, the 2026 planning environment demands more than aggregate market size estimates. It requires a clear understanding of how indication strategy, territory partnerships, dosage form dynamics, API supply structures, and regulatory momentum intersect to create competitive advantage. The Worldwide Niraparib Market research report is designed to deliver that integrated view. By combining historical performance through 2025 with a detailed forecast horizon through 2032, the study enables stakeholders to stress-test commercial assumptions, evaluate partnership opportunities, and anticipate the strategic implications of regulatory and diagnostic developments.
Several themes stand out as especially relevant for decision-makers. First, the market's 12.43 percent CAGR through 2032 reflects durable demand expansion, but that expansion is unevenly distributed across indications, formulations, and geographies. Second, competitive concentration remains high, meaning that strategic moves by GSK and Janssen can have outsized effects on pricing, launch timing, and indication competition. Third, partnership architectures in China and Japan illustrate how localized execution can sustain market participation in complex healthcare environments. Fourth, the companion diagnostic approval and evolving prostate cancer combination strategy demonstrate that future growth will increasingly depend on molecular targeting and access to defined patient populations.
To fully act on these insights, stakeholders need the deeper segmentation detail, company-level profiles, and scenario-ready forecasts contained in the complete report. The publication goes beyond the headline trajectory to provide the operational intelligence required for concrete planning: regional commercialization pathways, indication-level revenue architecture, dosage form consumption context, competitor positioning, and the evolving regulatory and reimbursement landscape. For organizations that need to convert market visibility into executable strategy, this research offers a structured foundation for confident decision-making.
The full report is available now for teams preparing their 2026 strategic plans. Accessing the complete analysis will provide the comprehensive segmentation breakdowns, competitor profiles, and forward-looking scenario data necessary to move from broad market awareness to precise commercial execution.
For detailed analysis of this topic, please visit the official page: Worldwide Niraparib Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aircraft Load Control Market to Hit $275M by 2032, 6.72% CAGR
By pmarketresearch, 2026-09-16
Navigating Precision: Strategic Insights into the Worldwide Aircraft Load Control Solution Market
The aviation industry stands at a critical juncture where operational efficiency and safety compliance are no longer mutually exclusive goals but intertwined necessities. As aircraft operations become increasingly complex and fuel costs continue to exert pressure on airline margins, the role of precise load control has evolved from a regulatory checkbox to a strategic asset. PW Consulting is proud to introduce our latest comprehensive market research, Worldwide Aircraft Load Control Solution Market, designed to equip industry leaders with the intelligence needed to navigate the forecast period of 2026 to 2032.
This report is not merely a collection of statistics; it is a strategic roadmap derived from rigorous analysis of historical performance and future projections. Based on a base year of 2025 and historical data spanning from 2020 to 2025, our forecast indicates a robust trajectory for the sector. The global market, valued at approximately 174.45 million USD in 2025, is projected to reach around 275.03 million USD by 2032. This growth represents a Compound Annual Growth Rate (CAGR) of 6.72 percent over the forecast period. Such expansion signals a shift in how airlines and ground handlers view weight and balance systems, moving from legacy on-premise setups toward more agile, integrated digital ecosystems.
Macroeconomic Drivers and Market Trajectory
The steady climb in revenue from 122.45 million USD in 2020 to the projected 2032 figures reflects more than just inflation or fleet expansion. It underscores a fundamental transformation in aviation operations. The post-pandemic recovery phase saw a resurgence in passenger demand, but the underlying driver for load control solutions is the increasing need for automation and data accuracy. As aircraft become heavier and routes more varied, the margin for error in weight distribution narrows. Regulatory bodies globally are tightening compliance requirements, necessitating solutions that minimize human error and provide real-time verification.
Our analysis suggests that the growth rate will be sustained by the dual pressures of safety mandates and cost optimization. Fuel burn is directly correlated to aircraft weight and center of gravity positioning. Solutions that enable precise loading calculations contribute directly to fuel savings, offering a clear ROI for airlines operating on thin margins. Furthermore, the integration of load control with flight planning and dispatch systems is becoming a standard expectation rather than a premium feature. This holistic approach to operations is driving the demand for sophisticated digital load monitoring technologies, aligning with broader industry initiatives like the FAA's NextGen implementation program which emphasizes data-driven decision-making in aircraft operations.
Solution Ecosystems: Cloud, On-Premise, and Deployment Models
When examining the solution landscape, the market is broadly categorized by deployment architecture and the nature of services provided. The industry is witnessing a gradual shift in preference regarding where these critical calculations reside. While traditional on-premise solutions have long been the standard for stability and security, the agility offered by cloud-based architectures is gaining traction, particularly among carriers looking for scalability and remote access capabilities. Our research delves into the revenue contributions of each model, analyzing how different carrier sizes and operational models influence their choice of deployment.
Similarly, the end-user landscape is diverse, encompassing passenger airlines, cargo airlines, and ground handling companies. Each segment faces unique challenges. Passenger airlines must balance baggage, cargo, and passenger distribution to maintain trim and safety, while cargo operators focus on maximizing payload within structural limits. Ground handling companies, often acting as service providers for multiple carriers, require systems that can adapt to varying airline protocols quickly. The report provides a detailed breakdown of how these end users are adopting specific technologies, highlighting the distinct value propositions that resonate with each group. For instance, centralized load control services are becoming increasingly popular among handlers seeking to standardize operations across multiple stations.
Competitive Landscape: Established Giants and Specialized Innovators
The market structure is characterized by a mix of large aerospace conglomerates, IT giants, and specialized niche players. Our concentration analysis indicates a moderately consolidated environment, with the top three companies holding a significant share of the market, while the top five extend this influence further. This concentration suggests that while there is room for innovation, scale and integration capabilities remain key differentiators.
Among the key players, Jeppesen, a Boeing company, continues to leverage its heritage with modules like Powerloader and eLoadsheet, integrating tightly with flight planning and dispatch workflows. Their presence underscores the importance of ecosystem integration, where load control is not a siloed function but part of a broader airline operations suite. Similarly, Amadeus IT Group and Sabre Corporation offer load control functionalities within their expansive airline IT ecosystems, providing seamless data flow between reservation, departure control, and load management systems.
On the specialized front, companies like Damarel Systems International Ltd. offer focused solutions such as LodeStone, catering specifically to narrow and wide-body commercial aircraft with an emphasis on central load control and station operations. Evionica distinguishes itself with smart Weight and Balance solutions that emphasize automation, claiming over 80 percent autonomous loadsheet generation, which appeals to airlines seeking to reduce manual workload. Smart4Aviation Technologies B.V. provides a visual exception-based approach with S4A Smart LOAD, monitoring the full loading process and supporting both centralized and decentralized models.
Other notable participants include ABOMIS Innovations, which focuses on optimized load allocation and real-time calculations, and AeroData, known for integrating weight and balance tools with performance platforms to maximize load capacity. Regional players like A-ICE in Italy and Air Dispatch in the Czech Republic contribute to the diversity of the market, offering tailored systems for specific operational contexts. In the service domain, Swissport International AG operates Central Load Control centers, recently highlighting operations in Morocco and Kenya supporting over 50 airlines and processing significant volumes of load sheets annually. This service-oriented approach is complemented by firms like Samsic Assistance Aviation and Global Load Control, which provide remote aviation load control services to enhance safety and fuel efficiency through accurate weight distribution.
Regulatory Dynamics and Operational Imperatives
Compliance is the bedrock upon which the load control market rests. Stringent aviation safety regulations from authorities like ICAO and FAA mandate precise weight and balance calculations. The consequence of non-compliance is not merely financial but existential, involving safety risks and regulatory sanctions. Consequently, solutions are required to minimize human error in weight distribution. This regulatory pressure is a primary catalyst for the adoption of automated systems that provide audit trails and verification checks.
IATA plays a crucial role in standardizing the workforce through training and design manuals for aircraft weight and balance. They prepare personnel for Load Controller certification under global aviation standards, ensuring that the human element operating these systems is equally qualified. Meanwhile, EASA and equivalent military certifications apply to related control loading and weight and balance systems in both simulation and operational contexts. The evolving regulatory framework drives demand for technologies that can adapt to new rules without massive hardware overhauls. Digital solutions that receive updates remotely offer a distinct advantage in maintaining compliance across global fleets operating in different jurisdictions.
Furthermore, the push for sustainability is intertwining with load control. Centralized Load Control systems are increasingly recognized for their ability to enable fuel consumption reduction through optimized weight distribution and Easy Final Weight calculations. This alignment of safety, compliance, and environmental goals creates a strong value proposition for investing in advanced load control technologies.
Worldwide Aircraft Load Control Solution Market
Strategic Value for 2026 Decision Making
For executives and strategists operating in 2026, understanding the nuances of this market is critical. The growth trajectory indicates a maturing market where differentiation lies in integration depth and operational automation. Our report goes beyond high-level numbers to explore the practical implications of these trends. We analyze how specific solution types are penetrating different regions without exposing the precise percentage splits that require a full subscription to validate against your specific operational footprint. This approach ensures that when you access the full data, the insights are actionable for your specific context, whether you are evaluating a vendor partnership, considering a technology upgrade, or assessing market entry opportunities.
The report also addresses the shifting dynamics in ground handling. As airports seek to optimize turnaround times, the efficiency of load control processes becomes a bottleneck or a enabler. Companies that can offer seamless integration with existing airport IT infrastructure while providing robust weight and balance capabilities are likely to capture greater market share. The recent developments in centralized load control services, such as those highlighted by major ground handlers expanding their center capabilities in strategic locations, illustrate the trend toward outsourcing complex calculations to specialized centers that can achieve economies of scale.
Load Cells Market
Additionally, the distinction between cloud-based and on-premise solutions is not just about technology preference but about risk management and connectivity. In regions with intermittent connectivity, hybrid models or robust offline capabilities, as offered by certain innovators, become critical. Our analysis evaluates these capabilities against the backdrop of global travel patterns and infrastructure reliability.
Conclusion: Preparing for the Future of Load Management
The Worldwide Aircraft Load Control Solution Market is poised for significant evolution over the next seven years. The projected growth to over 275 million USD by 2032 reflects a sector that is integral to the safe and efficient operation of modern aviation. For stakeholders, the opportunity lies in selecting solutions that not only meet current regulatory standards but are adaptable enough to handle future requirements. The competition among key players is driving innovation in automation, integration, and service delivery models.
PW Consulting's comprehensive study provides the depth required to make informed capital allocation and strategic partnership decisions. By understanding the historical performance from 2020 to 2025 and the forecasted dynamics through 2032, organizations can position themselves to leverage efficiency gains and mitigate compliance risks. We invite industry leaders to explore the full findings of this report, where detailed segmentation data, comprehensive competitor profiles, and granular regional analysis await. In a market defined by precision, your strategic decisions deserve intelligence of the same caliber. Access the complete market intelligence to ensure your operations remain balanced, compliant, and competitive in the global airspace.
For detailed analysis of this topic, please visit the official page: Worldwide Aircraft Load Control Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 5G NR Antenna Market to Hit $80.1B by 2032, 15.68% CAGR
By pmarketresearch, 2026-09-16
Navigating the 5G NR Antenna Revolution: Strategic Insights for 2026 and Beyond
The global telecommunications infrastructure is undergoing a structural transformation, driven by the relentless demand for higher throughput, lower latency, and ubiquitous connectivity. At the heart of this evolution lies the 5G NR antenna market, a critical enabler of network capacity and spectral efficiency. As we enter 2026, industry stakeholders face a complex landscape defined by rapid technological iteration, evolving regulatory frameworks, and shifting supply chain dynamics. PW Consulting's latest comprehensive market research offers a definitive guide to navigating this terrain, providing the granular intelligence necessary for informed strategic decision-making.
This report is not merely a snapshot of current revenues; it is a forward-looking strategic asset designed to help operators, equipment manufacturers, and investors align their roadmaps with market realities. By analyzing historical trajectories from 2020 through 2025 and projecting growth patterns through 2032, we uncover the underlying forces shaping the industry's next decade. The following insights distill the key findings of our analysis, highlighting why access to detailed market intelligence is indispensable for maintaining competitiveness in a consolidating and technologically intense environment.
Macro Market Trajectory and Growth Vectors
The financial scale of the 5G NR antenna sector underscores its strategic importance. Valued at approximately 12,500 million USD in 2020, the market has demonstrated aggressive expansion, reaching an estimated 28,900 million USD by the base year of 2025. This growth reflects the accelerated deployment of 5G networks across commercial and industrial sectors globally. Looking ahead, our forecasts indicate that revenue will continue to climb significantly, surpassing 33,000 million USD in 2026 and projecting toward a substantial 80,113.5 million USD mark by 2032.
Wireless Antenna Market
This trajectory corresponds to a compound annual growth rate (CAGR) of 15.68 percent over the forecast period from 2026 to 2032. Such sustained growth suggests that antenna systems will remain a high-priority capital expenditure category for network builders. However, raw market size tells only part of the story. The velocity of growth varies across technology adoptions, frequency bands, and deployment types, creating pockets of opportunity and risk that require precise navigation. Understanding the interplay between these segments is crucial for optimizing supply chain investments and R&D focus areas.
Technology and Frequency Band Dynamics
The architectural choices defining 5G NR deployments are heavily influenced by the balance between coverage requirements and capacity demands. Our analysis delves deep into the split between Sub-6 GHz and mmWave solutions, as well as the divergence between Massive MIMO and traditional SISO or Basic MIMO configurations. These technological distinctions drive different value propositions for urban dense environments versus broader rural or suburban coverage scenarios.
Massive MIMO technology, in particular, has become a cornerstone for high-capacity macro sites, allowing operators to multiplex multiple data streams and significantly improve spectral efficiency. Concurrently, the industry is witnessing a nuanced evolution in frequency band utilization. While Sub-6 GHz remains the workhorse for widespread coverage, mmWave solutions are carving out critical niches for high-throughput applications in specific locales. The report provides a detailed examination of how these technology and frequency segments interact with deployment types, distinguishing between the requirements for Macro Cells and the growing necessity of Small Cells to fill coverage gaps and enhance indoor performance.
Strategic planners must recognize that the choice of antenna technology is not isolated from infrastructure costs. For instance, the economics of fiber optic deployment for 5G backhaul, which can range significantly per kilometer, directly influence the feasibility and density of small cell deployments. Our research integrates these infrastructure cost factors to provide a holistic view of total network economics, ensuring that antenna selection aligns with broader capital efficiency goals.
Competitive Landscape and Key Player Strategies
The market structure is characterized by a mix of established telecommunications giants and specialized antenna manufacturers, creating a dynamic competitive environment. The top three companies collectively hold a significant portion of the market revenue, while the top five extend their influence further, indicating a moderately concentrated landscape where scale and technological expertise provide distinct advantages.
Ericsson and Nokia continue to lead in providing comprehensive radio access solutions, including massive MIMO and hybrid active-passive 5G NR base station antennas. Ericsson's integration of Kathrein technology and Nokia's AirScale mMIMO adaptive antennas exemplify the industry's push toward scalable radio access with passive-active integration. Huawei remains a formidable supplier of ultra-wideband Active Antenna Units (AAU) and multi-band 5G NR antennas, emphasizing energy efficiency and high-performance base station solutions for dense urban areas. Samsung contributes high-throughput massive MIMO radios and antenna systems, with strategic collaborations extending into non-terrestrial network testing.
Complementing these major players are specialized firms that address specific deployment needs. CommScope and Amphenol Antenna Solutions focus on manufacturing passive and hybrid panel and base station antennas, crucial for integrating with active radios in macro cell sites. Comba Telecom and Tongyu Communication provide robust passive and active elements for macro and distributed systems, while Tongyu's multi-band capabilities highlight the trend toward versatile antenna designs. In the realm of in-building and complex venue coverage, Corning's Everon distributed antenna systems (DAS) and JMA Wireless' TEKO and XRAN solutions offer optical and RF integration for 5G NR indoor and outdoor deployments. SOLiD specializes in ALLIANCE 5G DAS for high-density environments such as subways and arenas, and PROSE Technologies focuses on passive cellular antenna solutions optimized for performance and sustainability.
Recent developments underscore the pace of innovation. In early 2026, NEC prepared to launch a new 5G sub-6 GHz massive MIMO radio unit targeting higher throughput and lower power consumption, signaling continued pressure on energy efficiency and performance. Additionally, collaborations such as the PTCRB certification achievement by Anritsu for 5G NR NTN RF conformance test cases with Samsung highlight the expanding scope of antenna and radio technologies into satellite integration domains. These moves illustrate that competitive advantage increasingly depends on holistic ecosystem support and regulatory compliance capabilities.
Worldwide 5G NR Antenna Market
Regulatory and Infrastructure Influences Shaping Deployment
Market growth does not occur in a vacuum; it is heavily modulated by regulatory actions and infrastructure constraints. In 2025, 3GPP Release 19 introduced new over-the-air spatial emission requirements for 5G NR base station antennas, specifically to protect fixed satellite systems in the upper 6 GHz band. These specifications, detailed in 3GPP TS 38.104 and TR 38.908, mandate new test procedures and influence antenna design to ensure compliance while maintaining performance.
Simultaneously, spectrum availability remains a critical driver. US legislation (P.L. 119-21) directs the FCC to auction at least 100 MHz in the upper C-band (3.98-4.2 GHz) by July 2027, contributing to a broader 800 MHz spectrum pipeline through 2034. Furthermore, the FCC has restored auction authority through 2034 and is advancing the identification of 500 MHz in the 1.3-10.5 GHz range for commercial licensed use. These spectrum expansions will inevitably stimulate demand for antennas capable of operating across wider bandwidths and new frequency allocations.
On the infrastructure side, cost pressures persist. Fiber optic cable prices surged in early 2026 due to sustained demand from 5G backhaul and fronthaul requirements, as well as data center interconnects needing bend-insensitive and high-density cables. With average fiber deployment costs per kilometer forming a key component of overall network expenses, antenna solutions that reduce the need for extensive fiber runs or integrate efficiently with existing infrastructure gain strategic value. Our report evaluates how these regulatory and cost dynamics intersect with regional deployment strategies, helping stakeholders anticipate compliance costs and infrastructure bottlenecks.
Why This Report is Essential for 2026 Decision-Making
As the market matures, the margin for error in strategic planning narrows. Operators must decide where to deploy Massive MIMO versus SISO solutions, how to balance Sub-6 GHz and mmWave investments, and which deployment types—Macro versus Small Cells—offer the best return on investment in specific contexts. Equipment manufacturers need to anticipate shifts in demand across regions and technology segments to optimize production capacity and supply chain resilience. Investors require clarity on market concentration, growth sustainability, and the impact of regulatory changes on revenue streams.
This PW Consulting report delivers the actionable intelligence needed to address these challenges. It provides a detailed segmentation analysis across regions and application categories, offering granular data that generic industry summaries often obscure. By revealing the specific revenue contributions and growth rates within each segment, the report enables organizations to benchmark their performance, identify underserved markets, and refine their go-to-market strategies. The inclusion of company profiles and recent developments further equips readers with a competitive intelligence toolkit, highlighting who is leading in which technology domain and where the next product launches or standard updates might shift the balance of power.
Moreover, the integration of industry context noise—such as raw material price fluctuations, regulatory milestones, and infrastructure cost variables—ensures that decision-makers can stress-test their strategies against real-world disruptions. The ability to correlate antenna market data with broader telecom ecosystem trends is a distinct advantage in a sector where interdependencies are high.
Conclusion: Aligning Strategy with Market Reality
The 5G NR antenna market is poised for sustained expansion, but the path forward is nuanced. Success in 2026 and beyond will belong to those who can navigate the complexities of technology selection, regulatory compliance, and competitive positioning with precision. PW Consulting's Worldwide 5G NR Antenna Market research provides the comprehensive framework necessary to make these decisions with confidence. By transforming raw data into strategic insights, this report empowers stakeholders to capitalize on growth opportunities while mitigating risks associated with market concentration, infrastructure costs, and evolving standards.
To access the full breadth of our analysis, including detailed segmentation data, regional breakdowns, and exhaustive competitive profiles, we invite you to explore the complete report. The depth of information contained within is designed to serve as a foundational resource for your strategic planning, ensuring that your organization remains at the forefront of the 5G NR antenna revolution.
For detailed analysis of this topic, please visit the official page: Worldwide 5G NR Antenna Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Breathable Waterproof Fabrics Market to Hit USD 12,874 Million by 2032 at 7.5% CAGR
By pmarketresearch, 2026-09-16
Strategic Imperatives in the Evolving Breathable Waterproof Fabrics Market: A 2026 Decision-Making Framework
The global landscape for breathable waterproof fabrics is undergoing a structural transformation driven by simultaneous pressures from regulatory compliance, raw material volatility, and shifting consumer expectations around sustainability. For enterprise leaders navigating product roadmaps, supply chain strategy, and capital allocation in 2026, understanding the trajectory of this sector requires more than headline numbers. It demands a granular, data-grounded view of how material science, geographic demand centers, and application-specific performance requirements are converging to reshape competitive advantage.
The Worldwide Breathable Waterproof Fabrics Market study provides exactly that vantage point. Built on historical performance tracking from 2020 through 2025 and extending forecast visibility through 2032, the analysis translates macro growth signals into actionable intelligence for product planners, procurement directors, and corporate development teams. The market expanded from approximately USD 5,420.5 million in 2020 to an estimated USD 7,760.11 million in 2025, and the projected trajectory points toward sustained expansion at a compound annual growth rate of 7.5 percent. By 2032, the global revenue base is expected to approach the USD 12,874.4 million threshold, reflecting a market that is maturing in scale while simultaneously fragmenting in technological and regulatory complexity.
Worldwide Breathable Waterproof Fabrics Market
This publication is designed not as a static reference document but as a decision-support instrument. Below, we outline the analytical architecture, the competitive intelligence embedded within, and the operational insights that make this research directly relevant to 2026 strategic planning.
Macroeconomic Trajectory and the Case for Forward-Looking Intelligence
Growth in breathable waterproof fabrics is no longer a simple function of outdoor apparel demand cycles. The sector is being re-shaped by durable structural forces: tightening chemical restrictions on fluorinated compounds, the commercialization of PFAS-minimized and PFAS-free membrane technologies, material cost fluctuations tied to regional industrial demand, and the expansion of performance textiles into adjacent verticals. Companies that treat these shifts as isolated events risk misaligning product specifications, supplier partnerships, and margin models.
The historical dataset within the report captures the market’s resilience through recent years of macroeconomic uncertainty. Revenue progression from 2020 to 2025 demonstrates an uninterrupted upward path, with the 2025 estimate of USD 7,760.11 million setting the baseline for the 2026 forecast year at USD 8,446.27 million. Importantly, the forecast horizon does not assume a straight-line continuation. The analysis incorporates variable growth rates across the projection window, reflecting how regulatory timelines, material substitution adoption curves, and application mix shifts will alter the pace of expansion year by year. Decision-makers using this framework can stress-test product introduction timing, capacity planning, and regional prioritization against a range of plausible near-term scenarios rather than relying on a single deterministic forecast.
Regulatory Dynamics and Material Substitution Pressure Points
Regulatory developments are now a primary driver of product development cadence and supplier selection logic. Effective from January 2025, California and New York prohibited the sale of new apparel containing intentionally added PFAS, and bluesign certification similarly restricted intentionally added PFAS from the same date, subject to limited exceptions. In Europe, France enacted Law No. 2025-188, which bans the manufacture, import, export, and sale of PFAS-containing clothing textiles and footwear beginning January 2026, with certain exemptions and a broader textile prohibition scheduled for 2030. These measures are not confined to compliance checklists; they are accelerating the commercial relevance of alternative membrane chemistries and compelling brands to re-evaluate laminate specifications across existing and future collections.
For procurement and R&D teams, the implication is clear: material decisions made today will carry regulatory exposure well into the back half of the decade. The report maps these regulatory timelines against material categories and application requirements, enabling readers to anticipate where substitution pressure will be most acute and where transitional formulations may remain viable. This is particularly critical for enterprises operating across multiple jurisdictions, where a specification acceptable in one market may become a liability in another.
Material Cost Volatility and Supply Chain Implications
Raw material pricing is another dimension where strategic foresight pays direct dividends. Polyurethane prices in Europe reached USD 3.43 per kilogram in December 2025, reflecting a modest 2.8 percent decline from September 2025 amid softer demand in construction and automotive end markets. Meanwhile, fluoropolymer prices in North America decreased 1.45 percent quarter-over-quarter in Q4 2025 due to mild oversupply. However, the broader cost picture is uneven: China’s 2025 tightening of fluorspar export licensing raised costs for Western converters by an estimated 12 to 18 percent, reshaping the economics of PTFE-based supply chains outside Asia.
Compounding these dynamics, the U.S. EPA TSCA 2024 Rule will prohibit the distribution in U.S. commerce of articles containing phenol, isopropylated phosphate (3:1) [PIP (3:1)] beginning October 31, 2026, affecting certain textile manufacturing equipment and materials. These intersecting cost and compliance variables create a complex procurement environment. The market study integrates material cost movements and regulatory milestones into a cohesive operational narrative, helping readers assess supplier diversification strategies, regional sourcing trade-offs, and inventory timing without relying on fragmented intelligence.
Segmentation Architecture: Where Value Creation Is Shifting
A defining feature of this research is its segmentation architecture, which connects material innovation, application demand, and regional consumption patterns to the broader market trajectory. Rather than treating these dimensions in isolation, the report structures them to reveal how technology adoption accelerates or slows in different use cases, and how regional supply ecosystems influence competitive positioning.
Worldwide Breathable Membranes Market
On the material side, ePTFE-based membranes continue to anchor a substantial share of performance-oriented applications, while polyurethane and polyester-based systems are gaining relevance as manufacturers pursue recyclability, cost efficiency, and PFAS-reduced or PFAS-free formulations. This is not a simplistic substitution story. Each material class carries distinct trade-offs in breathability, durability, processability, and end-of-life characteristics, and the report examines how these trade-offs play out across major application verticals. Sportswear and activewear remain a dominant demand center, but protective clothing, medical and hygiene applications, and automotive and industrial uses each present different performance thresholds and procurement dynamics that influence both product design and supplier selection.
Regionally, the market reflects a multi-polar demand structure rather than a single dominant geography. Asia Pacific represents the largest consumption base, supported by broad manufacturing capacity and growing domestic demand for performance textiles. North America and Europe continue to function as high-value demand centers with particular sensitivity to regulatory standards and premium performance specifications. Latin America and the Middle East and Africa constitute smaller but strategically relevant markets where cost structure, supplier proximity, and application mix can differ meaningfully from the major regions. The study provides the analytical spine to evaluate these regional profiles without reducing them to simplistic rankings, giving readers the context needed to align product launches, distribution strategies, and partnership models with local market realities.
Because the report’s full segmentation detail—including region-level revenue allocations, material-category breakdowns, and application-specific market sizes—contains precisely the kind of granular intelligence that supports forecasting, pricing strategy, and competitive benchmarking, it is reserved for the complete publication. This deliberate structure ensures that enterprise teams can evaluate the strategic shape of the market here while accessing the quantitative depth required for operational planning through the source report.
Competitive Landscape: Incumbents, Specialists, and Disruption Vectors
The competitive field in breathable waterproof fabrics is characterized by a mix of established membrane specialists, material innovators, and integrated sportswear producers that have moved upstream into proprietary fabric development. Concentration metrics indicate a moderately consolidated environment, with the top three players accounting for an estimated 38.5 percent of market revenue and the top five approaching 52.2 percent. That level of concentration suggests both the presence of scale advantages and the continued room for specialized entrants that can differentiate on technology, sustainability credentials, or application-specific performance.
W. L. Gore & Associates remains a central reference point, with its GORE-TEX ePTFE-based waterproof breathable membranes and laminates widely deployed across outdoor apparel, footwear, and protective gear. Gore’s recent introduction of next-generation GORE-TEX Pro with an ePE membrane illustrates the broader industry pivot toward minimizing intentionally added PFAS while preserving durability for demanding use cases. Toray Industries supplies polyurethane and TPU-based systems through platforms such as Dermizax, supporting both performance apparel and industrial applications. SympaTex Technologies has built a distinct position around recyclable polyester-based membranes, while schoeller Textil AG continues to develop high-performance waterproof breathable textiles for outdoor and workwear segments. Polartec contributes NeoShell and related laminates integrated into performance fabrics, and eVent Fabrics has focused on direct-venting membrane architectures, including recent collaboration on moisture-managing systems.
The competitive frontier is also expanding through emerging technology providers and vertically integrated sportswear brands. FORMOSA TAFFETA operates at large scale in coated and laminated waterproof breathable fabrics for apparel and technical textiles, and HeiQ Materials supplies functional treatments and membrane-enhancing technologies. In Switzerland, dimpora has advanced PFAS-free CoreLayer Technology membranes with a circularity focus, while ANTA Sports Products has pushed commercialization through the launch of AEROVENT ZERO, a mass-produced PFAS-free bio-based waterproof breathable membrane integrated into next-generation storm jackets, with projected sales exceeding 500,000 units by 2026.
Recent corporate activity underscores how quickly the competitive baseline is moving. In August 2025, ANTA and Donghua University announced the global launch of AEROVENT ZERO as China’s first independently developed high-performance PFAS-free bio-based waterproof-breathable membrane. In September 2025, Gore updated its portfolio with the ePE-based GORE-TEX Pro launch. By March 2026, Surforce Technology Group reported a major advance in functional nanofiber nonwoven materials, addressing long-standing limitations of traditional PTFE and TPU membranes in breathability and elasticity, supported by a ten-million-meter-scale nanofiber factory. That same month, eVent Fabrics partnered with ALLIED Feather + Down to debut a moisture-managing system combining eVent’s 2-layer stormburstLT laminate with ExpeDRY down at Performance Days Munich.
These developments are not isolated press items; they are signals of where value is migrating. The study profiles these companies and contextualizes their moves within technology roadmaps, regulatory exposure, and application expansion. Readers gain a structured view of who is competing on scale, who is competing on material architecture, and who is attempting to disrupt through bio-based or PFAS-free approaches with different performance and cost profiles.
Strategic Applications for 2026 Decision-Making
For executives planning 2026 initiatives, the research is designed to support several interconnected decision domains. Product strategy teams can use the forecast and segmentation framework to prioritize development resources toward applications where performance demand, regulatory tailwinds, or pricing power are most favorable. Procurement and supply chain leaders can align supplier negotiations with material cost trajectories, regional cost differentials, and anticipated compliance constraints. Corporate development and M&A teams can identify technology partnerships and acquisition targets based on membrane chemistry, sustainability positioning, and geographic footprint. Brand and marketing leaders can calibrate claims and collection planning around the evolving regulatory environment, particularly as PFAS restrictions broaden and certification regimes tighten.
The report’s value lies in combining a macro growth narrative with the operational detail that makes growth actionable. It does not simply describe that the market is expanding; it clarifies where expansion is being generated, what material and regulatory shifts are shaping that expansion, and how leading companies are positioning themselves to capture it.
What the Full Study Delivers
Beyond the strategic framework summarized here, the complete Worldwide Breathable Waterproof Fabrics Market report provides a comprehensive analytical toolkit. It includes historical and forecast market sizing with year-by-year projections, a detailed segmentation structure that connects materials, applications, and regions to revenue flows, and a competitive landscape section that profiles key companies, their core offerings, and recent strategic developments. The study also integrates regulatory timelines, raw material pricing movements, and technology milestones into a unified market context, enabling readers to assess both opportunities and risk exposures in a single reference framework.
Operational users will find value in the way the report connects demand drivers to supply-side realities. Rather than presenting segmentation as an abstract taxonomy, the analysis shows how material categories interact with application requirements, how regional demand profiles are shaped by local manufacturing capacity and regulatory regimes, and how competitive dynamics differ across market segments. This makes the document suitable for cross-functional use, from product planning and procurement to market entry strategy and investor communications.
Conclusion: Positioning for a Market in Transition
The breathable waterproof fabrics market in 2026 is defined by the intersection of durable growth, regulatory redirection, and material innovation. The macro trajectory points toward continued expansion, but the more strategically important story is how that growth is being redistributed across technologies, applications, and geographies as companies respond to PFAS restrictions, cost volatility, and consumer expectations around sustainability and performance.
Organizations that base their 2026 decisions on a structured, forward-looking view of these dynamics will be better positioned to manage supplier risk, time product introductions, and allocate innovation investment effectively. The Worldwide Breathable Waterproof Fabrics Market research is built to support that effort, offering both the strategic narrative and the segmentation intelligence required to move from awareness to action.
To access the complete dataset, company profiles, segmentation detail, forecast tables, and the full set of strategic recommendations, please visit the source page for the Worldwide Breathable Waterproof Fabrics Market study.
For detailed analysis of this topic, please visit the official page: Worldwide Breathable Waterproof Fabrics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com