

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: SPECT Camera Market Hits $2,195M in 2025, Projected to Reach $3,305M by 2032 with 6.02% CAGR

Strategic Horizon 2026: Unlocking Value in the Global SPECT Camera Market
Executive Summary
The global landscape for Single Photon Emission Computed Tomography (SPECT) imaging is undergoing a transformative shift. As healthcare systems worldwide pivot toward precision medicine and value-based care, the demand for advanced molecular imaging solutions has never been more critical. Our latest Worldwide SPECT Camera Market research provides a comprehensive roadmap for navigating this evolution through 2032. For strategic decision-makers operating in 2026, understanding the trajectory of this market is not merely an academic exercise; it is a prerequisite for capital allocation, product development, and competitive positioning.
This report synthesizes historical performance from 2020 through 2025 with robust forecasts extending to 2032. The analysis reveals a sector characterized by steady growth, technological consolidation, and shifting regulatory dynamics. With the total market valuation reflecting significant expansion over the past half-decade, stakeholders must look beyond surface-level metrics to understand the underlying drivers of revenue. This article serves as a primer to the full study, highlighting the strategic imperatives that will define success in the coming years.
Market Trajectory and Growth Vectors
The historical data indicates a resilient market that has rebounded strongly following global disruptions. From 2020 to 2025, the industry demonstrated a clear upward trend, culminating in a baseline valuation that sets the stage for the forecast period. The growth is not linear; it is propelled by specific technological adoptions and clinical shifts that vary across segments. Our analysis projects a Compound Annual Growth Rate (CAGR) of 6.02 percent throughout the forecast period ending in 2032. This figure suggests a maturing market that is still capable of substantial expansion, driven by the replacement cycle of legacy equipment and the introduction of high-sensitivity systems.
Revenue projections indicate that the market will continue to scale significantly, moving from recent valuations toward higher thresholds by the early 2030s. However, the aggregate numbers only tell part of the story. The real value for strategists lies in understanding the velocity of adoption across different system types and clinical applications. The shift from standalone systems to hybrid SPECT/CT configurations represents a fundamental change in procurement behavior among hospitals and imaging centers. This transition is influencing not only hardware sales but also the ecosystem of consumables and software services that accompany these installations.
Technological Divergence and System Segmentation
The market is currently defined by a divergence in technology platforms, each catering to specific clinical needs and operational constraints. Hybrid SPECT/CT Systems dominate the revenue share, reflecting the industry consensus that anatomical correlation enhances diagnostic confidence. These systems are becoming the standard for oncology and complex cardiology cases where precise localization is paramount. The integration of computed tomography with nuclear medicine data has streamlined workflow, reducing the time required for diagnosis and improving patient throughput.
Conversely, Standalone SPECT Systems maintain a presence, particularly in cost-sensitive environments or specialized facilities where CT infrastructure is already available or unnecessary for the specific clinical question. While their share is smaller compared to hybrid units, they remain vital for basic perfusion studies and regions where budget constraints dictate procurement. Additionally, Dedicated Cardiac SPECT systems represent a niche but critical segment. Given the prevalence of cardiovascular disease globally, these specialized units offer optimized protocols for myocardial perfusion imaging, balancing cost efficiency with high diagnostic accuracy for heart disease.
Strategists must pay close attention to the technological arms race between manufacturers. The differentiation is no longer just about resolution; it is about workflow integration, dose reduction, and scan speed. Companies that can demonstrate tangible improvements in patient experience—such as reduced scan times or lower radiation exposure—are gaining traction in competitive tenders. This technological premium is a key factor in the pricing structures observed across different regions and hospital networks.
Clinical Applications Driving Demand
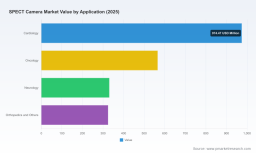
The application landscape is equally pivotal in understanding market dynamics. Cardiology remains the primary driver of SPECT imaging volume. Myocardial perfusion imaging continues to be a cornerstone in the diagnosis and management of coronary artery disease. As the global burden of cardiovascular conditions rises, the reliance on nuclear cardiology for risk stratification ensures steady demand for both equipment and radiotracers. The integration of AI-enabled quantification tools is further enhancing the utility of cardiac SPECT, allowing for more precise assessment of blood flow and myocardial viability.
Oncology represents a rapidly growing application segment. The use of SPECT for tumor imaging, bone scans, and the localization of specific receptors is expanding alongside the growth of personalized oncology. Hybrid systems are particularly valuable here, enabling clinicians to correlate functional metabolic data with anatomical structures. This synergy supports better staging, treatment planning, and follow-up monitoring. As new radiopharmaceuticals gain approval, the versatility of SPECT technology positions it as a complementary tool to PET imaging in many healthcare settings.
Neurology and Orthopedics also contribute significantly to the market footprint. In neurology, SPECT is utilized for evaluating dementia, epilepsy, and cerebrovascular diseases. While the volume may not match cardiology, the complexity of these cases often requires high-resolution imaging capabilities. In orthopedics and other specialties, the technology aids in detecting infections, fractures, and bone metabolism disorders. A diversified application base provides stability to the market, insulating it from fluctuations in any single clinical area.
Competitive Landscape and Strategic Positioning
The market concentration is notable, with the top three players commanding a significant portion of the revenue. This concentration indicates high barriers to entry regarding regulatory compliance, distribution networks, and technological R&D. However, regional players and specialized innovators are carving out niches by focusing on specific technologies such as CZT detectors or digital imaging platforms.
GE HealthCare remains a dominant force, leveraging its extensive installed base and continuous innovation in SPECT/CT systems. Their recent clearances for evolution models highlight a focus on AI-enabled quantification, particularly for cardiology. Siemens Healthineers is equally aggressive, integrating intelligent imaging features into their Symbia family to optimize workflow. Their recent FDA clearances underscore a commitment to AI-driven process optimization, which appeals to high-volume centers looking to reduce staffing burdens.
Philips Healthcare continues to compete with systems optimized for low-dose applications, addressing the growing concern over radiation exposure. Meanwhile, Spectrum Dynamics Medical is disrupting the market with CZT-based technology, promising higher resolution and faster scans. This technological differentiation allows them to challenge incumbents in specific high-end segments. United Imaging Healthcare represents the rising influence of manufacturers from Asia, offering digital detectors and whole-body imaging capabilities that compete on performance and value. Mediso rounds out the competitive field with a focus on both preclinical and clinical molecular imaging, providing flexibility for research hospitals and specialized clinics.
Strategic partnerships and regulatory milestones are key indicators of future market share. Recent FDA clearances for systems like the Symbia Pro.Spect AI and the VERITON-CT scanner demonstrate the regulatory pathway active in 2024 and 2025. These approvals are not just compliance checkboxes; they are market access enablers that allow manufacturers to expand their footprint in key regions like the United States. Companies that navigate the 510(k) process efficiently gain a first-mover advantage in deploying next-generation technology.
Regulatory and Reimbursement Dynamics
Navigating the regulatory environment is a critical component of market strategy. SPECT cameras are classified as Class II devices, requiring 510(k) premarket notification in the United States. This regulatory framework ensures safety and efficacy but also imposes timelines and costs that influence product launch strategies. Compliance with standards such as IEC 61223-3-1 for evaluation and routine testing is mandatory for acceptance and quality control, affecting both manufacturers and end-users.
Reimbursement policies directly impact the adoption rate of imaging procedures. CPT codes covering myocardial perfusion SPECT imaging dictate the revenue cycle for providers. Variations in reimbursement rates by payer can influence which procedures are prioritized within a hospital system. Furthermore, bundled payments under DRG groups for acute myocardial infarction include SPECT procedures, creating incentives for efficient diagnosis to manage overall episode costs. Understanding the interplay between procedure codes, payer policies, and hospital budget cycles is essential for forecasting demand accurately.
Professional societies also play a role in shaping market standards. Guidelines such as the SNMMI Procedure Standard outline minimum performance specifications for general SPECT imaging systems. Adherence to these standards ensures consistency in image quality and diagnostic reliability, which indirectly supports the demand for high-quality equipment that meets these specifications. Manufacturers must align their product development with these evolving standards to maintain credibility and market access.
PET and SPECT Scanners Market
Regional Insights and Market Heterogeneity
While global aggregates provide a top-down view, regional heterogeneity dictates tactical execution. Market maturity, healthcare infrastructure, and reimbursement landscapes vary significantly across geographies. In North America, the market is characterized by high adoption rates of advanced hybrid systems and a strong focus on technological upgrades. The presence of major manufacturers and established distribution channels supports a robust ecosystem.
Europe presents a mixed landscape where national health systems and private providers coexist. Regulatory harmonization within the region facilitates cross-border equipment deployment, but reimbursement variations between countries can affect pricing strategies. Asia Pacific represents a growth frontier, driven by expanding healthcare access and increasing prevalence of lifestyle-related diseases. The demand here is often value-conscious, yet the volume potential is substantial for manufacturers who can offer scalable solutions.
Latin America and the Middle East and Africa regions operate with different dynamics, often influenced by procurement budgets and infrastructure development. In these markets, reliability and service support are often as critical as initial purchase price. Understanding the specific procurement cycles and regulatory requirements in these regions is vital for companies looking to expand their global footprint. The distribution of revenue across these regions highlights where investment and sales efforts should be prioritized over the forecast period.
Strategic Imperatives for 2026 and Beyond
For corporate strategists, the implications of this market analysis are clear. First, investment in hybrid technology should be a priority, as the shift toward integrated SPECT/CT continues to dominate procurement trends. Second, differentiation through software and AI capabilities is becoming a key battleground. Hardware specifications are converging, but workflow solutions that reduce time and improve accuracy offer a unique value proposition.
Third, monitoring regulatory and reimbursement changes is non-negotiable. Shifts in policy can alter the economic viability of certain procedures overnight. Companies must maintain agile compliance teams and active dialogue with payers and policymakers. Fourth, regional customization is essential. A one-size-fits-all approach fails in a market where clinical needs and economic constraints vary so widely.
Finally, the competitive intensity suggests that mergers, acquisitions, or strategic partnerships may accelerate as companies seek to fill technology gaps or expand geographic reach. The high concentration among top firms indicates that scale matters, but niche players with superior technology can still disrupt established relationships. Stakeholders should assess their supply chain resilience and R&D pipelines against these competitive pressures.
Conclusion and Next Steps
The Worldwide SPECT Camera Market is on a defined growth path, underpinned by clinical necessity and technological advancement. The data from 2020 to 2032 paints a picture of an industry that is expanding steadily while undergoing significant structural change. The 6.02 percent CAGR reflects confidence in the modality's long-term relevance, even as new imaging technologies emerge.
However, aggregate data alone is insufficient for precise planning. The nuances of segmentation, regional pricing, competitor roadmaps, and specific regulatory hurdles require deeper examination. Our full market research report provides the granular intelligence needed to translate these high-level trends into actionable strategies. It includes detailed breakdowns of market sizes, competitive profiling, and scenario analyses that go beyond the summary provided here.
Worldwide SPECT Camera Market
To access the complete dataset, including specific revenue figures by region and application type, as well as comprehensive profiles of all key market participants, we invite you to explore the full report. Equip your organization with the precise intelligence needed to navigate the complexities of the SPECT camera market through 2032. Contact our research team or visit the product page to secure your copy of the full study.
For detailed analysis of this topic, please visit the official page: Worldwide SPECT Camera Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com