

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Turbocharger Bearing Market Hits $2.15B in 2025, Expand to $3.08B by 2032 at 5.25% CAGR

Strategic Intelligence for Executive Decision-Making: The Worldwide Turbocharger Bearing Market Outlook 2026-2032
As the global automotive and industrial sectors navigate a profound transformation driven by electrification, emission regulations, and supply chain realignments, component-level intelligence has become a cornerstone of resilient strategy. Turbocharger bearings, once viewed as commoditized mechanical parts, now sit at the critical intersection of thermal management, fuel efficiency mandates, and performance optimization. PW Consulting's latest Worldwide Turbocharger Bearing Market study delivers a comprehensive, data-backed blueprint designed specifically to equip C-suite leaders, R&D directors, and procurement strategists with the actionable intelligence required to navigate the 2026 commercial landscape and beyond.
Worldwide Turbocharger Bearing Market
Why This Research Matters for 2026 Strategic Planning
The turbocharger bearing ecosystem is experiencing structural shifts that render legacy forecasting models obsolete. Regulatory pressure from Euro 7 standards and EPA Phase 3 heavy-duty engine requirements is forcing original equipment manufacturers to pursue measurable gains in turbo efficiency, directly translating into demand for advanced low-friction bearing architectures. Simultaneously, macroeconomic volatility has reshaped input cost trajectories, with high-strength alloy steel prices climbing sharply in recent cycles due to persistent global supply chain friction. Copper-dependent bronze journal bearings have faced acute cost escalation, compelling manufacturers to reassess material sourcing, supplier contracts, and product portfolio pricing strategies.
In this environment, intuition-driven procurement and reactive capacity planning are no longer viable. Decision-makers require forward-looking visibility into demand inflection points, competitive positioning, and segment-level growth vectors. Our study was engineered to provide exactly that clarity. By anchoring analysis in verified historical data from 2020 through the base year of 2025 and projecting through 2032, the report transforms fragmented market signals into a coherent strategic narrative. It answers the critical questions that boardrooms and operational leaders are asking right now: Where is the market heading, which structural drivers will dominate the next cycle, and how should enterprises position their portfolios to capture durable share?
Macro Trajectory and Growth Architecture
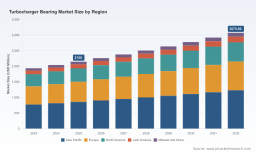
The worldwide turbocharger bearing market has demonstrated consistent expansion over the past half-decade, reflecting both steady vehicle production recovery and incremental technological upgrades across powertrain architectures. Measured in millions of US dollars, the market progressed from 1940.0 in 2023 to 2042.0 in 2024, reaching 2150.0 in 2025. Looking ahead, the forecast period extends from 2026 through 2032, with market size expected to advance to 2262.88 in 2026, continuing its upward trajectory to 3075.89 by 2032. This path reflects a compound annual growth rate of 5.25 percent, signaling a market that is neither stagnant nor explosively speculative, but steadily compounding through technological adoption, regulatory compliance cycles, and sustained demand from both passenger and commercial transport segments.
Such growth is rarely uniform across all operational dimensions. The structural composition of the market reveals a nuanced picture. In terms of bearing technology, journal-based configurations and ball-based architectures represent the two dominant technology pathways, each catering to distinct performance requirements around load capacity, rotational speed, thermal tolerance, and lubrication regimes. Application-wise, the demand base spans passenger vehicles, commercial vehicles, and industrial and heavy-duty engines, with each segment responding to different regulatory timelines, duty cycles, and engineering optimization priorities. Geographic distribution further shapes competitive dynamics, with regional manufacturing footprints, local content requirements, trade policy environments, and logistics networks influencing where capacity is built, where sourcing occurs, and which customer relationships yield the highest strategic returns.
For strategic planners, the core insight is that growth is increasingly driven by structural upgrades rather than pure volume expansion. The push toward downsized engines, hybrid powertrains, and electrified auxiliary systems is reshaping performance benchmarks, while emission mandates are accelerating the adoption of bearing solutions that deliver reduced friction, enhanced durability, and superior thermal stability. Understanding how these segments interact, where substitution risk exists, and which applications will command premium pricing requires a granular view that goes well beyond headline figures.
Competitive Landscape and Strategic Positioning
The turbocharger bearing market is characterized by a moderately concentrated competitive structure, with the top three players commanding approximately 48.5 percent of total market share and the top five extending that reach to roughly 62.2 percent. This concentration signals a landscape where scale, technological differentiation, and long-term customer integration heavily influence commercial outcomes. At the same time, a broader field of specialized manufacturers continues to compete through niche engineering strengths, regional service capabilities, and targeted material innovations.
Among the leading organizations shaping this ecosystem, the Schaeffler Group has established itself as a prominent supplier of journal and foil air bearings across automotive and commercial vehicle applications. Its recent showcase of next-generation foil bearings for electric turbochargers underscores how incumbent players are reinvesting in next-wave architectures as electrification redefines boosting requirements. SKF AB has reinforced its differentiation through hybrid ceramic and air foil bearing solutions optimized for high-speed turbocharger operations, notably introducing hybrid turbocharger bearings with extended durability designed specifically for heavy-duty engines. These product moves reflect a broader trend where bearing longevity and operating envelope expansion are becoming decisive commercial differentiators.
Japanese manufacturers continue to play a central role in the competitive matrix. NTN Corporation manufactures full complement roller and ball bearings for turbochargers deployed in passenger cars and heavy-duty engines, and has emphasized low-friction bearing technologies for downsized turbocharger platforms at major industry exhibitions. NSK Ltd. develops high-temperature angular contact ball bearings engineered for turbocharger shafts, addressing the thermal and load challenges that intensify as combustion and post-combustion systems operate under tighter efficiency tolerances. JTEKT Corporation contributes through its Koyo-brand needle roller and ball bearings tailored for turbocharger applications, reinforcing the breadth of engineering options available to tier suppliers and OEMs seeking optimized shaft support and rotation stability.
North American and European specialists add further depth to the competitive field. The Timken Company offers tapered roller and super precision bearings serving both industrial and automotive turbocharger applications, leveraging its broader precision bearing heritage to address demanding operational environments. RBC Bearings Incorporated specializes in foil air bearings and thrust bearings for turbochargers across aerospace and automotive sectors, demonstrating how bearing expertise in high-performance rotating machinery translates across end markets. Waukesha Bearings Corporation supplies hydrodynamic journal and tilt pad bearings for turbochargers in power generation and marine uses, highlighting how heavy-duty and stationary power applications remain a meaningful demand pillar alongside mobile transport. Taken together, these players illustrate a market where technology leadership, application specialization, and cross-industry capability transfer are all viable pathways to competitive advantage.
Industry Dynamics, Cost Pressures, and Regulatory Forces
Navigating 2026 and the subsequent forecast window requires a clear understanding of the forces that will compress margins, accelerate innovation, or create new barriers to entry. Regulatory frameworks represent one of the most powerful structural drivers. Euro 7 emission standards mandate improved turbo efficiency, directly stimulating demand for advanced low-friction bearings that can support tighter combustion controls and higher boost responsiveness without compromising durability. On the other side of the Atlantic, EPA Phase 3 heavy-duty engine standards require a 25 percent nitrogen oxide reduction by 2027, further boosting turbocharger bearing upgrades as engine manufacturers work to meet stringent output and emissions targets simultaneously. These regulations do more than influence product specifications; they reshape procurement priorities by shifting demand toward higher-performance bearing generations and incentivizing early adoption of engineered solutions that align with compliance timelines.
Raw material dynamics add a parallel layer of strategic complexity. High-strength alloy steel prices for bearings increased by 8 percent in 2023 due to global supply chain disruptions, while copper content in bronze journal bearings faced a 12 percent price hike from mining shortages. These input cost pressures interact directly with pricing architecture, inventory strategy, and supplier diversification planning. Enterprises that rely on single-source supply or rigid contract structures face heightened exposure, whereas organizations that integrate forward-looking material forecasting, alternative alloy evaluation, and multi-region sourcing frameworks are better positioned to protect margins without sacrificing performance. At the same time, trade policy remains a persistent variable. US-China tariffs on automotive components have increased bearing import costs, altering regional cost competitiveness and prompting both suppliers and end users to reevaluate manufacturing footprints, cross-border logistics, and regional substitution strategies.
Turbocharger Market
What the Study Delivers for Strategic Teams
PW Consulting's Worldwide Turbocharger Bearing Market research is structured to move beyond descriptive market sizing and deliver operational intelligence that can be embedded directly into planning cycles. The report provides a detailed examination of market segmentation across technology types, application categories, and regional distributions, allowing teams to benchmark demand concentrations, identify where growth is accumulating, and understand the practical implications for product roadmaps and commercial strategy. The analysis is anchored in verified historical performance and a forward-looking forecast architecture, enabling scenario planning rather than static target setting.
Beyond segmentation, the study delivers a competitive assessment that maps out the strategic behaviors of leading manufacturers, including their product focus, regional presence, and recent commercial developments. It examines how companies are responding to performance requirements through material innovation, design optimization, and targeted exhibition and product launch activity. The research also integrates regulatory, macroeconomic, and supply-side dynamics so that strategic readers can connect market growth with the operational realities that shape execution, such as material cost exposure, compliance-driven specification upgrades, and trade-related cost redistribution.
For procurement and supply chain leaders, the findings provide context for sourcing decisions, supplier evaluation frameworks, and inventory planning in an environment where input volatility and regulatory shifts can quickly alter the cost-performance equation. For product strategy and engineering teams, the report offers insight into technology migration patterns, application-specific performance demands, and the operational implications of bearing architecture choices. For commercial and corporate development professionals, it supports competitive positioning assessments, partnership evaluation, and market entry or expansion planning by clarifying where share is evolving and which capabilities are most closely associated with durable competitive advantage.
Translating Market Intelligence into 2026 Advantage
The strategic value of this research lies in its ability to connect macroeconomic indicators, technology trends, and competitive behavior into a coherent decision-support framework. A 5.25 percent compound annual growth trajectory over a seven-year forecast period is not merely a number; it is a signal about the pace of structural adoption, the timing of capital allocation, and the window of opportunity for organizations that align their portfolios with emerging demand. Market size progression from 2150.0 in 2025 to projected levels above 3000.0 by 2032 reflects a market where incremental performance gains, regulatory compliance, and application expansion will continue to drive commercial activity. Recognizing which applications, technologies, and geographies will carry the greatest strategic weight requires the depth and segmentation detail that this study provides.
Leaders who act on this intelligence can better calibrate product development priorities, anticipate competitive pressure points, and structure supplier relationships to reduce exposure to input cost volatility and trade disruptions. They can evaluate whether their current bearing portfolios align with the trajectory of emission mandates and powertrain evolution, and they can identify where differentiation is likely to shift from cost competition to engineering performance and reliability. In a market with meaningful concentration at the top and active competition across specialized niches, timing and positioning matter as much as scale.
Access the Full Strategic Blueprint
This overview outlines the strategic context, competitive architecture, and operational dynamics that make the Worldwide Turbocharger Bearing Market a critical focus area for 2026 planning. Yet many of the most valuable insights, including detailed segmentation trajectories, regional and application-level demand patterns, specific competitive positioning metrics, and forward-looking scenario frameworks, are developed in full within the complete research document. For executive teams that need granular data, comparative benchmarks, and actionable recommendations tailored to real operating decisions, the full report provides the depth required to move from strategic awareness to execution-ready intelligence.
To obtain the complete Worldwide Turbocharger Bearing Market study and integrate its findings into your 2026 strategic planning, procurement models, and portfolio decisions, access the full report through PW Consulting's official research portal and secure the comprehensive market intelligence your organization needs to compete with precision in the years ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Turbocharger Bearing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com