

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Smart Thermometer Patch Market Hits $812.45M in 2025, Projects 10.45% CAGR Through 2032

Global Smart Thermometer Patch Market: Strategic Intelligence for 2026 Decision-Makers
Market Trajectory and the Case for Deep-Dive Intelligence
The global smart thermometer patch market has transitioned from a niche innovation to a structurally significant segment of the digital health and continuous remote monitoring ecosystem. Between 2020 and 2025, cumulative revenue expanded from approximately 495.2 million USD to 812.45 million USD, reflecting sustained commercialization momentum across both disposable and reusable product architectures. As we enter the 2026-2032 forecast horizon, the market is projected to scale to roughly 1.63 billion USD by 2032, supported by a compound annual growth rate of 10.45 percent. This trajectory is not merely a function of incremental demand, but of converging clinical workflows, regulatory pathway maturity, and patient-centric care models that increasingly prioritize continuous axillary temperature tracking over intermittent manual measurement.
For executives, investors, and product strategists, the critical question for 2026 is no longer whether smart thermometer patches will gain share, but how to position operations, supply chains, and commercial roadmaps against a landscape defined by fragmented application use cases, geographically uneven adoption, and an increasingly scrutinized regulatory environment. This research briefing is designed to move procurement, clinical affairs, and market development teams past headline-level awareness and into a structured, decision-ready intelligence framework. The following narrative previews the analytical dimensions covered in the full Worldwide Smart Thermometer Patch Market study, helping leadership assess where actionable intelligence will most materially influence capital allocation, partnership strategy, and product positioning in the coming planning cycle.
The macro trajectory underscores a market that has consistently compounded its valuation across the 2020-2025 historical window, with year-over-year expansion that signals durable end-user pull rather than one-off pandemic-era adoption. The 2026 baseline of approximately 870 million USD serves as the launch point for a forecast curve that accelerates through the latter half of the decade. Strategic planners evaluating expansion, R&D prioritization, or channel build-out must recognize that this growth is distributed unevenly across product formats, clinical and consumer applications, and regional ecosystems. Decoding that distribution, the operational constraints attached to it, and the competitive responses shaping it is the core purpose of the full report.
Structural Segmentation and the Strategic Implications of Product, Application, and Regional Architecture
Understanding where value concentrates, and why, begins with a disciplined examination of the market's structural layers. The full study decomposes the landscape across three interdependent segmentation axes: product type, application end-use, and geographic region. At the product level, the commercial ecosystem is anchored by single-use patches and reusable patches, each with distinct cost structures, clinical adoption drivers, replacement cycles, and supply chain considerations. Single-use architectures typically emphasize streamlined hospital and home-care deployment, reduced sterilization or reprocessing burden, and predictable unit economics tied to episodic monitoring or short-duration admission pathways. Reusable architectures, by contrast, are built around longer operational lifespans, rechargeable or extended-battery designs, and recurring value propositions tied to remote patient monitoring programs and chronic or longitudinal care. The strategic tension between these two formats is not simply about unit price; it is about reimbursement alignment, clinical workflow fit, waste and sustainability considerations, and the degree to which procurement organizations prefer consumable procurement versus capital-audited device programs.
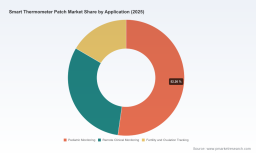
The application layer adds another level of strategic complexity. Pediatric monitoring continues to represent a highly sensitive end-use environment, where caregiver anxiety, fever escalation risk, and the need for contactless or low-friction monitoring drive adoption. Remote clinical monitoring reflects a broader shift toward decentralized care and hospital-to-home transitions, where continuous temperature data is integrated into broader vitals dashboards and used to support early intervention logic. Fertility and ovulation tracking introduces a more consumer-facing, longitudinal use case, where temperature trends serve as an informational signal within broader reproductive health workflows. Each application pathway carries different purchase decision dynamics, user experience expectations, evidence requirements, and channel strategies. A product engineered for pediatric fever detection will face fundamentally different commercial and regulatory demands than one optimized for remote clinical deployment or consumer fertility tracking, even if the underlying sensing technology shares common foundations.
Regionally, the market reflects distinct maturity curves, reimbursement pressures, and healthcare infrastructure realities. North America remains a central anchor of commercial activity and regulatory precedent, supported by established hospital procurement mechanisms, growing home-care programs, and clearDevice classification pathways. Europe operates under a different compliance architecture, where quality management rigor and regional device regulation shape market entry and ongoing commercialization. Asia Pacific presents a structurally large and rapidly evolving opportunity set, characterized by expanding manufacturing capability, growing domestic demand, and varied regional adoption speeds across different healthcare systems. Latin America and the Middle East and Africa collectively represent smaller but strategically meaningful volumes, often shaped by import dynamics, pilot-based procurement, and the pace at which local care delivery models integrate continuous monitoring tools. The full report examines how these regional profiles interact with product format and application mix to shape where commercial traction is achieved, where scaling is constrained, and where competitive displacement risk is most pronounced.
Application-Layer Dynamics and Decision-Making Divergence
- Pediatric monitoring environments require designs that balance caregiver ease-of-use with clinically credible fever detection, often reinforcing disposable or short-duration patch adoption in domestic and outpatient contexts.
- Remote clinical monitoring pathways favor reusable or extended-life architectures that support integrated care teams, continuous data flow, and operational efficiency across hospital-to-home transitions.
- Fertility and ovulation tracking depends heavily on longitudinal trend interpretation, app experience, and consumer trust, creating differentiation opportunities beyond raw temperature accuracy alone.
- Each application layer imposes distinct evidence expectations, pricing assumptions, and partner ecosystems, meaning that a single product strategy rarely fits all commercial scenarios.
Competitive Landscape and the Emerging Battlegrounds
The market's competitive fabric is defined by a mid-tier concentration structure in which a limited set of established and emerging players collectively shape category standards, dissemination patterns, and procurement expectations. Concentration metrics indicate that the top three participants capture roughly 38.5 percent of market revenue, while the top five account for approximately 52.3 percent. This structure suggests a market that is not yet dominated by a single consolidated incumbent, but is nevertheless moving toward an environment where credible clinical endorsements, regulatory clearances, and workflow integration capabilities increasingly separate scaled participants from narrower niche offerings.
Worldwide Smart Thermometer Patch Market
Blue Spark Technologies has built its positioning around a Class II, FDA-cleared, disposable wireless continuous monitoring patch designed for extended axillary monitoring with Bluetooth connectivity. Its commercial narrative emphasizes early fever detection in hospital and home-care settings, aligning with institutional buyers seeking reliable, low-friction temperature surveillance for at-risk patient populations. VivaLNK Inc. has pursued a reusable, rechargeable axillary patch path, holding FDA clearance, CE marking, and NMPA approval, with an emphasis on IoT integration and extended battery life supporting remote patient monitoring across longer deployment cycles. SteadySense GmbH has oriented its offering around medical-grade, NFC-enabled measurement accuracy and compliance with quality management and regional device regulations, targeting both clinical and home use with a strong precision positioning. iWEECARE Co., Ltd. has entered the space with a compact Bluetooth patch cleared for continuous axillary temperature monitoring, addressing fever tracking, fertility, and remote patient monitoring use cases through a compact, connectivity-focused design. Guangdong Genial Technology Co., Ltd. has advanced a reusable Bluetooth-enabled axillary patch with app connectivity, and its recent regulatory clearance underscores how quickly the competitive field is being reshaped by new market entrants securing clearance pathways for continuous monitoring formats. Helyxon Healthcare Solutions Pvt Ltd has focused on a continuous Bluetooth temperature monitoring system with app-based real-time alerts, emphasizing pediatric and hospital use and reinforcing how regional players are targeting both institutional and caregiver-facing demand.
From a strategic standpoint, the competitive dynamics are less about who offers the highest specification on paper and more about who can convert clinical-grade accuracy, clearance status, and connectivity into procurement-ready value propositions. The differentiators that matter in 2026 include the durability of regulatory positioning, the practicality of deployment at scale, the integration footprint with existing monitoring or EHR-adjacent workflows, battery or consumable economics, and the credibility of clinical and real-world evidence supporting fever detection, remote monitoring workflows, and longitudinal temperature trend interpretation. The full report provides a deeper company-by-company assessment that maps these positioning choices against specific product architectures, application targeting, and the likely pressure points each competitor faces as adoption broadens.
Key Competitive Pressure Points
- Regulatory clearance breadth and maintenance capability increasingly determine which players can access institutional procurement and cross-border commercialization.
- Disposable versus reusable economics shape not only unit pricing, but also procurement category treatment, waste management expectations, and total cost of ownership calculations.
- Connectivity and data integration readiness influence whether a patch is adopted as a standalone device or as part of a broader remote monitoring program.
- Clinical accuracy, reliability, and ease of use remain the non-negotiable floor, but differentiation is increasingly earned through workflow fit and evidence depth.
Regulatory Dynamics, Technical Standards, and Market Access Realities
Regulatory classification and standards compliance form the operational backbone of market access in this category. Smart thermometer patches are generally classified as Class II clinical electronic thermometers under applicable regulatory frameworks governing continuous axillary temperature monitoring, requiring demonstration of substantial equivalence through appropriate premarket clearance pathways. This classification creates a baseline expectation: product developers and commercializing firms must navigate clearance requirements, maintain documentation discipline, and ensure that performance claims align with cleared indications. Accuracy expectations are closely tied to recognized clinical electronic thermometer standards, with the field increasingly oriented toward measurement precision at or near ±0.1°C or ±0.2°F, depending on the applicable conformance requirement. Devices that meet these performance thresholds have a structural advantage in institutional procurement, where temperature reliability directly affects clinical confidence.
In European markets, the compliance conversation extends beyond accuracy alone to include quality management certification and alignment with regional medical device regulation. ISO 13485 certification and MDR-compliant documentation practices are increasingly expected components of commercial readiness and are often evaluated by procurement, clinical affairs, and quality assurance teams before adoption is authorized. These compliance layers do not simply represent administrative overhead; they shape the speed of market entry, the credibility of product positioning, and the operational resilience of manufacturers facing audits, post-market surveillance obligations, and cross-border distribution requirements. For organizations assessing partnership, supplier qualification, or in-house development pathways, understanding the compliance burden associated with each product format and target region is essential to realistic timeline planning and risk modeling.
The report's dynamics section examines these regulatory and technical realities as live commercial forces rather than abstract compliance items. It situates clearance status, accuracy conformance, and quality system maturity within the broader context of procurement decision-making, reimbursement sensitivity, and the practical question of how a patch moves from approved device to routinely deployed monitoring solution in a given care setting. This is especially relevant for 2026 planning, where market participants are likely to encounter both new entrants accelerating through clearance and established players tightening their evidence and post-market documentation to defend institutional relationships.
Connected Wearable Patches Market
Report Architecture: Operational Content Designed for Decision Use
The full Worldwide Smart Thermometer Patch Market study is constructed to support applied decision-making rather than passive information consumption. It combines a macro-level market trajectory review with detailed structural segmentation, enabling readers to trace how revenue flows across product types, application pathways, and regional markets without relying on top-line aggregates alone. The research is organized to support parallel workstreams: corporate strategy teams can use the segmentation and dynamics sections to assess where to compete and how to sequence entry or expansion; product and clinical teams can use the regulatory and competitive sections to benchmark clearance positioning, accuracy-oriented differentiation, and workflow integration opportunities; and commercial and supply chain teams can use the regional and application analysis to prioritize distribution models, channel partnerships, and procurement-aligned value propositions.
Beyond the segmentation and competitive mapping, the report provides forward-looking context for the 2026-2032 period, including the demand drivers most likely to shape procurement volume, the clinical and consumer scenarios expected to generate sustained patch utilization, and the operational constraints that may slow or accelerate adoption in specific regions or application verticals. It also includes recent market developments and clearance events that illustrate how quickly the category is evolving, helping readers distinguish between durable structural shifts and temporary competitive noise. The intention is to give leadership a working map of the market's value creation logic, not a static snapshot of where the market stands today.
Strategic Takeaways for 2026 Planning and How to Use This Intelligence
For organizations planning in 2026, the smart thermometer patch market presents a rare combination of category growth, segmentation diversity, and competitive flux. The projected trajectory toward a multi-billion-dollar scale by 2032 implies that early positioning choices, partnership decisions, and evidence-generation strategies will have long-lasting effects on market access and competitive defensibility. Teams that treat the category as a single product opportunity risk misreading where value is actually created. Teams that instead map the interplay between product format economics, application-specific purchase drivers, regional compliance realities, and competitor positioning will be better equipped to allocate resources, prioritize clinical evidence, and build commercially credible go-to-market narratives.
The complete study translates these strategic themes into a structured analytical foundation, enabling readers to identify the most consequential opportunities and risks for their specific context. Because the most actionable detail, including granular segmentation figures, company-level positioning assessments, and region-by-region commercial dynamics, is developed in depth within the full report, the most effective next step for decision-makers is to use this overview as a framing tool and then move to the detailed intelligence for quantification and scenario planning. The 2026 planning window rewards early clarity, and this research is designed to provide exactly that clarity at the point where market growth, clinical utility, and competitive pressure intersect.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Thermometer Patch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com