

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Niraparib Market Hits $1.18B in 2025, Set for $2.68B by 2032 at 12.43% CAGR

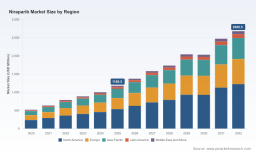
Navigating the Next Phase of Niraparib Growth: Strategic Intelligence for 2026 Decision-Makers
The Imperative for Precision Intelligence in Oncology Markets
The global landscape for poly (ADP-ribose) polymerase (PARP) inhibitors has entered a mature yet dynamically expanding phase, where competitive differentiation is increasingly defined by indication expansion, partnership structuring, and regulatory agility. As pharmaceutical leaders, investors, and market access strategists plan their portfolios for 2026, relying on fragmented secondary sources or legacy projections introduces significant strategic risk. This is precisely the gap our newly released Worldwide Niraparib Market research report is engineered to close. Designed as a decision-grade intelligence asset, the study translates multi-year epidemiological shifts, commercialization trajectories, and regulatory milestones into an actionable roadmap for enterprise planning.
Drawing on historical performance data spanning 2020 through 2025 and forward-looking projections through 2032, the report captures a market that has demonstrated remarkable compounding momentum. In 2020, global niraparib revenues stood at approximately $520.4 million, accelerating to $1.18 billion by 2025, with the trajectory projected to reach roughly $2.68 billion by 2032. This expansion reflects a compound annual growth rate of 12.43 percent, a figure that signals sustained commercial viability rather than transient momentum. For executives evaluating capital allocation, pipeline prioritization, or market entry timing, these macro indicators establish a foundational baseline. However, the true strategic value lies beyond the headline numbers. Our analysis isolates the structural drivers behind this growth, mapping how indication breadth, regional commercialization architectures, and formulation dynamics interact to shape revenue realization across different business models.
The report will be distributed and consumed as a comprehensive reference tool for strategy, business development, and market access teams. Rather than treating niraparib as a single-product narrative, we frame it within a multi-actor ecosystem where originator rights, territory-specific licensing, API supply chains, and companion diagnostics converge to determine market access and pricing leverage. For organizations preparing for 2026 and beyond, the study offers the analytical rigor required to anticipate shifts in competitive positioning, regulatory pathways, and reimbursement environments before they materialize in quarterly earnings calls or competitor press releases.
Decoding the Commercial Architecture: Indication Expansion and Dosage Dynamics
Niraparib's commercial story has evolved from a focused maintenance therapy in advanced ovarian, fallopian tube, and primary peritoneal cancers into a broader oncology asset with expanding therapeutic relevance. Our segmentation analysis provides granular visibility into how revenues are distributed across clinical indications, enabling stakeholders to assess where commercial gravity is concentrated and where incremental growth vectors are emerging. Ovarian cancer remains the dominant indication, reflecting niraparib's established positioning in maintenance treatment paradigms. Prostate cancer represents a structurally distinct and rapidly evolving revenue stream, driven by targeted combinations and molecularly defined patient populations. Additional solid tumor applications contribute a more specialized but strategically important share, often serving as platforms for clinical expansion and label broadening.
Equally critical to commercial planning is the dosage form architecture. The market reflects a clear preference for capsule-based formulations, which currently capture the majority of realized revenue, while tablet formats represent a meaningful complementary segment. For manufacturers, distributors, and market access teams, understanding formulation-level consumption patterns is essential for supply chain forecasting, packaging strategy, and payer negotiations. These dynamics are not static; they respond to clinical convenience, adherence considerations, and regulatory label evolution. Our report details how dosage form preferences intersect with patient population characteristics and prescribing behavior, giving commercial leaders a clearer view of where operational adjustments can protect or expand market share.
Worldwide Imbruvica Market
Importantly, the analysis does not stop at static segmentation snapshots. The study tracks how indication momentum and formulation adoption interact over the forecast horizon, enabling scenario-based planning for teams evaluating market penetration timelines, regional launch sequencing, or partnership structuring. By connecting clinical positioning to commercial outcomes, the report equips decision-makers with a more precise lens for evaluating which growth drivers are structural and which are contingent on regulatory or reimbursement developments.
Worldwide Niraparib Market
Competitive Ecosystem and the Strategic Role of Partnerships
Niraparib's market structure is highly concentrated, with a small number of players controlling the majority of commercial rights and supply pathways. This concentration shapes pricing behavior, launch timing, and the competitive intensity of indication expansion. At the core of the ecosystem, GlaxoSmithKline operates as the originator and primary marketer of ZEJULA, holding global commercialization rights outside specific partnered territories following its acquisition of Tesaro. GSK's leadership position is reinforced by continuous label optimization and strategic regulatory engagement, including recent prescribing information updates that refine dosage and administration guidance for maintenance treatment in ovarian cancer. These updates demonstrate how originator companies can sustain commercial relevance by aligning label language with evolving clinical practice.
Janssen Biotech, a Johnson & Johnson company, represents a strategically distinct contributor, holding exclusive rights outside Japan to niraparib in prostate cancer. This focused indication portfolio has enabled Janssen to build a differentiated commercial narrative, most notably through AKEEGA, a dual-action tablet combining niraparib with abiraterone acetate. Recent regulatory activity underscores the acceleration of this prostate cancer strategy: the U.S. FDA granted Priority Review for a supplemental new drug application for AKEEGA in BRCA-mutated metastatic castration-sensitive prostate cancer, followed by approval for expanded use in BRCA2-mutated metastatic castration-sensitive prostate cancer with prednisone. These milestones do more than expand indication coverage; they signal a broader shift toward molecularly targeted combination regimens in prostate oncology, where niraparib is positioned as a critical component of combination-based treatment architecture.
The commercial architecture is further shaped by territory-specific partners who localize execution and navigate regulatory and reimbursement complexities. Zai Lab Limited operates as GSK's commercialization partner for niraparib in Greater China under a licensing agreement, providing localized market access and distribution capabilities. Takeda Pharmaceutical holds exclusive rights to develop and commercialize niraparib in Japan through a legacy TESARO licensing agreement, reflecting how regional rights structures can preserve long-term market participation even when global originator control is consolidated elsewhere. These partnership models are central to understanding how niraparib reaches distinct patient populations while navigating varying healthcare system requirements.
Below the branded commercial layer, a network of API manufacturers supports supply chain resilience and regional formulation capacity. Companies such as Biophore India Pharmaceuticals, TAPI Technology & API Services, Sichuan Qingmu Pharmaceutical, Anhui Provincial, and Dr. Reddy's Laboratories operate as active suppliers within the niraparib API ecosystem, each with differing capabilities and market presence. For stakeholders evaluating supply security, cost structures, or potential generic entry timelines, mapping these upstream participants is essential. The report provides a structured view of this supplier landscape, helping procurement, business development, and competitive intelligence teams distinguish between manufacturing capability and commercial market impact.
Regulatory Catalysts, Diagnostic Integration, and Reimbursement Intelligence
Market performance in oncology therapeutics is increasingly inseparable from regulatory timing, diagnostic availability, and access negotiations. Niraparib's recent trajectory illustrates how closely these forces interact. In March 2026, the FDA approved Myriad Genetics' MyChoice CDx test as a companion diagnostic for niraparib in HRD-positive advanced ovarian cancer patients. The approval of a companion diagnostic is not merely a clinical milestone; it defines the eligible patient universe, influences testing adoption pathways, and shapes the economics of prescriber behavior. For market access strategists, diagnostic integration introduces both opportunity and complexity, because reimbursement for testing can directly affect therapy uptake and treatment sequencing.
On the regulatory front, GSK's June 2025 label update for ZEJULA demonstrates how ongoing engagement with prescribing information can reinforce clinical clarity and support appropriate use. Meanwhile, Janssen's late-2025 regulatory activity surrounding AKEEGA reflects the growing importance of combination product pathways in competitive oncology markets. The approval of AKEEGA for BRCA2-mutated metastatic castration-sensitive prostate cancer under Priority Review, alongside the earlier Priority Review filing, indicates that regulators are actively creating pathways for molecularly defined prostate cancer populations. These developments matter for forecasting because indication approvals can restructure competitive positioning, expand addressable populations, and shift payer expectations around value demonstration.
Reimbursement and access dynamics add another layer of strategic complexity. GSK's reported global net revenues for ZEJULA in 2025 reached approximately $1.8 billion, a figure that highlights the commercial scale already achieved while also underscoring the importance of sustained access performance across major markets. At the same time, patent protection remains a central variable in long-term market planning. Core U.S. patents for ZEJULA extend to March 2038 for compositions and January 2039 for formulations, and as of April 2026, no generic versions have been approved. This patent posture influences the timing of competitive entry, the durability of pricing power, and the strategic calculus for both originator teams and potential market entrants.
Our report integrates these regulatory, diagnostic, and access variables into a cohesive view of market dynamics. Instead of treating them as isolated news items, the analysis maps how they compound over time, affecting launch sequencing, patient identification, reimbursement negotiations, and competitive response. For organizations building 2026 plans, this integrated perspective reduces uncertainty and supports more resilient assumptions about uptake curves, pricing environments, and competitive pressure points.
Strategic Takeaways for 2026 and Beyond
For executives and analysts operating in the niraparib space, the 2026 planning environment demands more than aggregate market size estimates. It requires a clear understanding of how indication strategy, territory partnerships, dosage form dynamics, API supply structures, and regulatory momentum intersect to create competitive advantage. The Worldwide Niraparib Market research report is designed to deliver that integrated view. By combining historical performance through 2025 with a detailed forecast horizon through 2032, the study enables stakeholders to stress-test commercial assumptions, evaluate partnership opportunities, and anticipate the strategic implications of regulatory and diagnostic developments.
Several themes stand out as especially relevant for decision-makers. First, the market's 12.43 percent CAGR through 2032 reflects durable demand expansion, but that expansion is unevenly distributed across indications, formulations, and geographies. Second, competitive concentration remains high, meaning that strategic moves by GSK and Janssen can have outsized effects on pricing, launch timing, and indication competition. Third, partnership architectures in China and Japan illustrate how localized execution can sustain market participation in complex healthcare environments. Fourth, the companion diagnostic approval and evolving prostate cancer combination strategy demonstrate that future growth will increasingly depend on molecular targeting and access to defined patient populations.
To fully act on these insights, stakeholders need the deeper segmentation detail, company-level profiles, and scenario-ready forecasts contained in the complete report. The publication goes beyond the headline trajectory to provide the operational intelligence required for concrete planning: regional commercialization pathways, indication-level revenue architecture, dosage form consumption context, competitor positioning, and the evolving regulatory and reimbursement landscape. For organizations that need to convert market visibility into executable strategy, this research offers a structured foundation for confident decision-making.
The full report is available now for teams preparing their 2026 strategic plans. Accessing the complete analysis will provide the comprehensive segmentation breakdowns, competitor profiles, and forward-looking scenario data necessary to move from broad market awareness to precise commercial execution.
For detailed analysis of this topic, please visit the official page: Worldwide Niraparib Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com