

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Breathable Waterproof Fabrics Market to Hit USD 12,874 Million by 2032 at 7.5% CAGR

Strategic Imperatives in the Evolving Breathable Waterproof Fabrics Market: A 2026 Decision-Making Framework
The global landscape for breathable waterproof fabrics is undergoing a structural transformation driven by simultaneous pressures from regulatory compliance, raw material volatility, and shifting consumer expectations around sustainability. For enterprise leaders navigating product roadmaps, supply chain strategy, and capital allocation in 2026, understanding the trajectory of this sector requires more than headline numbers. It demands a granular, data-grounded view of how material science, geographic demand centers, and application-specific performance requirements are converging to reshape competitive advantage.
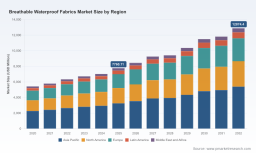
The Worldwide Breathable Waterproof Fabrics Market study provides exactly that vantage point. Built on historical performance tracking from 2020 through 2025 and extending forecast visibility through 2032, the analysis translates macro growth signals into actionable intelligence for product planners, procurement directors, and corporate development teams. The market expanded from approximately USD 5,420.5 million in 2020 to an estimated USD 7,760.11 million in 2025, and the projected trajectory points toward sustained expansion at a compound annual growth rate of 7.5 percent. By 2032, the global revenue base is expected to approach the USD 12,874.4 million threshold, reflecting a market that is maturing in scale while simultaneously fragmenting in technological and regulatory complexity.
Worldwide Breathable Waterproof Fabrics Market
This publication is designed not as a static reference document but as a decision-support instrument. Below, we outline the analytical architecture, the competitive intelligence embedded within, and the operational insights that make this research directly relevant to 2026 strategic planning.
Macroeconomic Trajectory and the Case for Forward-Looking Intelligence
Growth in breathable waterproof fabrics is no longer a simple function of outdoor apparel demand cycles. The sector is being re-shaped by durable structural forces: tightening chemical restrictions on fluorinated compounds, the commercialization of PFAS-minimized and PFAS-free membrane technologies, material cost fluctuations tied to regional industrial demand, and the expansion of performance textiles into adjacent verticals. Companies that treat these shifts as isolated events risk misaligning product specifications, supplier partnerships, and margin models.
The historical dataset within the report captures the market’s resilience through recent years of macroeconomic uncertainty. Revenue progression from 2020 to 2025 demonstrates an uninterrupted upward path, with the 2025 estimate of USD 7,760.11 million setting the baseline for the 2026 forecast year at USD 8,446.27 million. Importantly, the forecast horizon does not assume a straight-line continuation. The analysis incorporates variable growth rates across the projection window, reflecting how regulatory timelines, material substitution adoption curves, and application mix shifts will alter the pace of expansion year by year. Decision-makers using this framework can stress-test product introduction timing, capacity planning, and regional prioritization against a range of plausible near-term scenarios rather than relying on a single deterministic forecast.
Regulatory Dynamics and Material Substitution Pressure Points
Regulatory developments are now a primary driver of product development cadence and supplier selection logic. Effective from January 2025, California and New York prohibited the sale of new apparel containing intentionally added PFAS, and bluesign certification similarly restricted intentionally added PFAS from the same date, subject to limited exceptions. In Europe, France enacted Law No. 2025-188, which bans the manufacture, import, export, and sale of PFAS-containing clothing textiles and footwear beginning January 2026, with certain exemptions and a broader textile prohibition scheduled for 2030. These measures are not confined to compliance checklists; they are accelerating the commercial relevance of alternative membrane chemistries and compelling brands to re-evaluate laminate specifications across existing and future collections.
For procurement and R&D teams, the implication is clear: material decisions made today will carry regulatory exposure well into the back half of the decade. The report maps these regulatory timelines against material categories and application requirements, enabling readers to anticipate where substitution pressure will be most acute and where transitional formulations may remain viable. This is particularly critical for enterprises operating across multiple jurisdictions, where a specification acceptable in one market may become a liability in another.
Material Cost Volatility and Supply Chain Implications
Raw material pricing is another dimension where strategic foresight pays direct dividends. Polyurethane prices in Europe reached USD 3.43 per kilogram in December 2025, reflecting a modest 2.8 percent decline from September 2025 amid softer demand in construction and automotive end markets. Meanwhile, fluoropolymer prices in North America decreased 1.45 percent quarter-over-quarter in Q4 2025 due to mild oversupply. However, the broader cost picture is uneven: China’s 2025 tightening of fluorspar export licensing raised costs for Western converters by an estimated 12 to 18 percent, reshaping the economics of PTFE-based supply chains outside Asia.
Compounding these dynamics, the U.S. EPA TSCA 2024 Rule will prohibit the distribution in U.S. commerce of articles containing phenol, isopropylated phosphate (3:1) [PIP (3:1)] beginning October 31, 2026, affecting certain textile manufacturing equipment and materials. These intersecting cost and compliance variables create a complex procurement environment. The market study integrates material cost movements and regulatory milestones into a cohesive operational narrative, helping readers assess supplier diversification strategies, regional sourcing trade-offs, and inventory timing without relying on fragmented intelligence.
Segmentation Architecture: Where Value Creation Is Shifting
A defining feature of this research is its segmentation architecture, which connects material innovation, application demand, and regional consumption patterns to the broader market trajectory. Rather than treating these dimensions in isolation, the report structures them to reveal how technology adoption accelerates or slows in different use cases, and how regional supply ecosystems influence competitive positioning.
Worldwide Breathable Membranes Market
On the material side, ePTFE-based membranes continue to anchor a substantial share of performance-oriented applications, while polyurethane and polyester-based systems are gaining relevance as manufacturers pursue recyclability, cost efficiency, and PFAS-reduced or PFAS-free formulations. This is not a simplistic substitution story. Each material class carries distinct trade-offs in breathability, durability, processability, and end-of-life characteristics, and the report examines how these trade-offs play out across major application verticals. Sportswear and activewear remain a dominant demand center, but protective clothing, medical and hygiene applications, and automotive and industrial uses each present different performance thresholds and procurement dynamics that influence both product design and supplier selection.
Regionally, the market reflects a multi-polar demand structure rather than a single dominant geography. Asia Pacific represents the largest consumption base, supported by broad manufacturing capacity and growing domestic demand for performance textiles. North America and Europe continue to function as high-value demand centers with particular sensitivity to regulatory standards and premium performance specifications. Latin America and the Middle East and Africa constitute smaller but strategically relevant markets where cost structure, supplier proximity, and application mix can differ meaningfully from the major regions. The study provides the analytical spine to evaluate these regional profiles without reducing them to simplistic rankings, giving readers the context needed to align product launches, distribution strategies, and partnership models with local market realities.
Because the report’s full segmentation detail—including region-level revenue allocations, material-category breakdowns, and application-specific market sizes—contains precisely the kind of granular intelligence that supports forecasting, pricing strategy, and competitive benchmarking, it is reserved for the complete publication. This deliberate structure ensures that enterprise teams can evaluate the strategic shape of the market here while accessing the quantitative depth required for operational planning through the source report.
Competitive Landscape: Incumbents, Specialists, and Disruption Vectors
The competitive field in breathable waterproof fabrics is characterized by a mix of established membrane specialists, material innovators, and integrated sportswear producers that have moved upstream into proprietary fabric development. Concentration metrics indicate a moderately consolidated environment, with the top three players accounting for an estimated 38.5 percent of market revenue and the top five approaching 52.2 percent. That level of concentration suggests both the presence of scale advantages and the continued room for specialized entrants that can differentiate on technology, sustainability credentials, or application-specific performance.
W. L. Gore & Associates remains a central reference point, with its GORE-TEX ePTFE-based waterproof breathable membranes and laminates widely deployed across outdoor apparel, footwear, and protective gear. Gore’s recent introduction of next-generation GORE-TEX Pro with an ePE membrane illustrates the broader industry pivot toward minimizing intentionally added PFAS while preserving durability for demanding use cases. Toray Industries supplies polyurethane and TPU-based systems through platforms such as Dermizax, supporting both performance apparel and industrial applications. SympaTex Technologies has built a distinct position around recyclable polyester-based membranes, while schoeller Textil AG continues to develop high-performance waterproof breathable textiles for outdoor and workwear segments. Polartec contributes NeoShell and related laminates integrated into performance fabrics, and eVent Fabrics has focused on direct-venting membrane architectures, including recent collaboration on moisture-managing systems.
The competitive frontier is also expanding through emerging technology providers and vertically integrated sportswear brands. FORMOSA TAFFETA operates at large scale in coated and laminated waterproof breathable fabrics for apparel and technical textiles, and HeiQ Materials supplies functional treatments and membrane-enhancing technologies. In Switzerland, dimpora has advanced PFAS-free CoreLayer Technology membranes with a circularity focus, while ANTA Sports Products has pushed commercialization through the launch of AEROVENT ZERO, a mass-produced PFAS-free bio-based waterproof breathable membrane integrated into next-generation storm jackets, with projected sales exceeding 500,000 units by 2026.
Recent corporate activity underscores how quickly the competitive baseline is moving. In August 2025, ANTA and Donghua University announced the global launch of AEROVENT ZERO as China’s first independently developed high-performance PFAS-free bio-based waterproof-breathable membrane. In September 2025, Gore updated its portfolio with the ePE-based GORE-TEX Pro launch. By March 2026, Surforce Technology Group reported a major advance in functional nanofiber nonwoven materials, addressing long-standing limitations of traditional PTFE and TPU membranes in breathability and elasticity, supported by a ten-million-meter-scale nanofiber factory. That same month, eVent Fabrics partnered with ALLIED Feather + Down to debut a moisture-managing system combining eVent’s 2-layer stormburstLT laminate with ExpeDRY down at Performance Days Munich.
These developments are not isolated press items; they are signals of where value is migrating. The study profiles these companies and contextualizes their moves within technology roadmaps, regulatory exposure, and application expansion. Readers gain a structured view of who is competing on scale, who is competing on material architecture, and who is attempting to disrupt through bio-based or PFAS-free approaches with different performance and cost profiles.
Strategic Applications for 2026 Decision-Making
For executives planning 2026 initiatives, the research is designed to support several interconnected decision domains. Product strategy teams can use the forecast and segmentation framework to prioritize development resources toward applications where performance demand, regulatory tailwinds, or pricing power are most favorable. Procurement and supply chain leaders can align supplier negotiations with material cost trajectories, regional cost differentials, and anticipated compliance constraints. Corporate development and M&A teams can identify technology partnerships and acquisition targets based on membrane chemistry, sustainability positioning, and geographic footprint. Brand and marketing leaders can calibrate claims and collection planning around the evolving regulatory environment, particularly as PFAS restrictions broaden and certification regimes tighten.
The report’s value lies in combining a macro growth narrative with the operational detail that makes growth actionable. It does not simply describe that the market is expanding; it clarifies where expansion is being generated, what material and regulatory shifts are shaping that expansion, and how leading companies are positioning themselves to capture it.
What the Full Study Delivers
Beyond the strategic framework summarized here, the complete Worldwide Breathable Waterproof Fabrics Market report provides a comprehensive analytical toolkit. It includes historical and forecast market sizing with year-by-year projections, a detailed segmentation structure that connects materials, applications, and regions to revenue flows, and a competitive landscape section that profiles key companies, their core offerings, and recent strategic developments. The study also integrates regulatory timelines, raw material pricing movements, and technology milestones into a unified market context, enabling readers to assess both opportunities and risk exposures in a single reference framework.
Operational users will find value in the way the report connects demand drivers to supply-side realities. Rather than presenting segmentation as an abstract taxonomy, the analysis shows how material categories interact with application requirements, how regional demand profiles are shaped by local manufacturing capacity and regulatory regimes, and how competitive dynamics differ across market segments. This makes the document suitable for cross-functional use, from product planning and procurement to market entry strategy and investor communications.
Conclusion: Positioning for a Market in Transition
The breathable waterproof fabrics market in 2026 is defined by the intersection of durable growth, regulatory redirection, and material innovation. The macro trajectory points toward continued expansion, but the more strategically important story is how that growth is being redistributed across technologies, applications, and geographies as companies respond to PFAS restrictions, cost volatility, and consumer expectations around sustainability and performance.
Organizations that base their 2026 decisions on a structured, forward-looking view of these dynamics will be better positioned to manage supplier risk, time product introductions, and allocate innovation investment effectively. The Worldwide Breathable Waterproof Fabrics Market research is built to support that effort, offering both the strategic narrative and the segmentation intelligence required to move from awareness to action.
To access the complete dataset, company profiles, segmentation detail, forecast tables, and the full set of strategic recommendations, please visit the source page for the Worldwide Breathable Waterproof Fabrics Market study.
For detailed analysis of this topic, please visit the official page: Worldwide Breathable Waterproof Fabrics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com