

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Worldwide Agility Training Equipment Market: Why 3.95% CAGR and 2032 Expansion Reshape Strategy
By pmarketresearch, 2026-09-18
Navigating Growth and Transformation in the Global Agility Training Equipment Market
Market Overview: Current Landscape and Defining Challenges
The worldwide agility training equipment market has demonstrated steady expansion over the past five years, reaching an estimated $1.74 billion in 2025. Historical trajectory shows consistent momentum, with revenues climbing from $1.45 billion in 2020 before navigating a brief contraction in 2023, followed by renewed recovery. Projections indicate the market will surpass the $2.28 billion threshold by the end of the forecast window, supported by a compound annual growth rate of approximately 3.95%. While this growth profile reflects sustained demand across multiple end-use sectors, the underlying dynamics reveal a market navigating structural adjustments rather than experiencing uniform expansion.
One of the most pressing challenges shaping the sector is the evolving regulatory environment surrounding equipment safety and performance standards. Recent updates from major governing bodies have introduced stricter compliance requirements for course apparatus, including modifications to jump configurations, pause zones, and inspection protocols. These changes require manufacturers to redesign products, validate materials, and adapt labeling or certification processes. Companies that rely on legacy designs or operate with lean compliance infrastructure face margin compression and delayed time-to-market, while those that integrate safety engineering early in the development cycle are converting regulatory shifts into competitive differentiation.
Vocational Training Equipment Market
A second critical inflection point involves the bifurcation of demand across professional, institutional, and consumer segments. High-performance athletic programs and organized competition circuits continue to prioritize durability, precision calibration, and sport-specific specifications. At the same time, educational facilities and community fitness providers are placing greater emphasis on modular, cost-effective setups that support high throughput and rapid reconfiguration. Household users represent a smaller but growing share, driven by increased interest in at-home conditioning and pet-oriented training activities. Balancing product lines to serve these divergent requirements without diluting brand positioning or overcomplicating manufacturing is becoming a defining operational test.
Rugby Equipment Market
Supply chain normalization has also reshaped the market’s growth trajectory. After experiencing material volatility and logistics bottlenecks in earlier years, the industry has recalibrated sourcing strategies and production routing. However, raw material pricing for polymers, treated metals, and specialty rubber compounds remains sensitive to regional demand fluctuations and freight cost variability. This environment rewards manufacturers with diversified supplier networks and flexible production planning, while exposing those dependent on single-source components to pricing shocks and inventory uncertainty.
Key Drivers: Forces Reshaping Demand and Competitive Advantage
Technological innovation in material engineering and modular design is fundamentally altering how agility training equipment is built, deployed, and maintained. Manufacturers are increasingly integrating lightweight composite structures, impact-absorbing surfaces, and adjustable height mechanisms that reduce setup time while preserving performance integrity. These advancements address the dual imperatives of safety and versatility, allowing a single product platform to serve fast-twitch conditioning, sport-specific drills, and multi-sport practice environments. The shift toward engineered modularity also supports more efficient inventory management, as trainers and facility operators can scale capacity without purchasing entirely separate equipment suites.
Policy and regulatory developments are functioning as both a compliance requirement and a catalyst for product modernization. Updated standards from international bodies and sport-specific governing organizations have reinforced expectations around structural testing, impact resistance, and user safety across stationary training apparatus. In parallel, the publication of refreshed general safety specifications for fitness and training equipment has created a clearer benchmark for manufacturers seeking to validate product reliability across multiple jurisdictions. Companies that proactively align their design processes with these frameworks are reducing the risk of retrofit costs and gaining credibility with procurement teams that prioritize certified equipment for institutional and commercial installations.
PW Consulting
Demand-side behavior is shifting as training philosophies become more data-informed and cross-functional. Athletic programs, educational institutions, and fitness operators are increasingly designing drills that blend agility work with strength, coordination, and recovery components. This convergence is expanding the functional role of traditional equipment such as ladders, hurdles, markers, and poles, which are now being positioned as foundational tools within broader conditioning ecosystems rather than isolated practice items. Simultaneously, consumer interest in structured home routines and pet-oriented activity programs has broadened the addressable audience for entry-level and mid-tier equipment, encouraging manufacturers to develop products that balance ease of use with sufficient durability for repeated practice sessions.
Cost structure and sourcing strategies are also redefining competitive positioning. The market has moved from an era of acute supply disruption to one characterized by selective regionalization and supplier diversification. Leading producers are investing in production flexibility, balancing cost-efficient sourcing with proximity to key end markets to reduce lead times and improve responsiveness. This shift is particularly relevant for distributors and private-label operators, who are evaluating manufacturing partnerships that can accommodate variable order volumes, seasonal demand swings, and region-specific certification requirements without sacrificing consistency. The result is a market where operational agility is becoming as valuable as product performance in determining long-term resilience.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The competitive environment in agility training equipment is characterized by a broad field of specialized manufacturers, diversified sports-supply firms, and channel-focused distributors. Market concentration remains relatively moderate, with the top players collectively holding a limited share of total revenue. This fragmented structure reflects the diversity of end applications, ranging from competition-grade dog agility courses and professional athletic conditioning to institutional physical education programs and general fitness usage. Within this landscape, successful companies are distinguishing themselves through product reliability, application-specific engineering, and the ability to serve distinct customer segments with clearly defined value propositions.
Regional manufacturing presence continues to influence competitive positioning. Several leading suppliers based in the United States emphasize domestic production, durability, and close alignment with sport-specific training standards. These companies often compete by offering equipment tailored to organized trials, coaching environments, and commercial training facilities where equipment turnover, safety expectations, and performance consistency are closely scrutinized. In contrast, producers operating from export-oriented manufacturing hubs are leaning into scalability, broad product catalogs, and competitive pricing to serve institutional buyers, team programs, and multi-site distributors. Both models can be viable, but they require different operating priorities: one centers on application precision and trust within regulated competition ecosystems, while the other emphasizes breadth, cost control, and distribution reach.
Product differentiation is increasingly tied to versatility and safety engineering rather than basic equipment availability. Suppliers that offer integrated ranges of ladders, hurdles, rings, poles, cones, and training accessories are better positioned to meet the needs of buyers seeking unified procurement and consistent training aesthetics across facilities. At the same time, companies that focus on specialized segments, such as canine agility systems or performance-oriented athletic drills, are building defensible niches by refining equipment geometry, material choices, and user feedback loops. The presence of both broad-line and niche players indicates a market that supports multiple strategic paths, provided each company maintains clarity about its target user and procurement context.
The market structure appears poised for continued evolution through selective consolidation, partnership formation, and the entry of new brands that bring fresh product concepts or digital-enabled purchasing experiences. Larger distributors and diversified sports-equipment portfolios may pursue acquisitions or private-label agreements to expand category coverage and strengthen regional fulfillment. At the same time, emerging entrants with focused product lines, improved material specifications, or streamlined setup mechanisms can capture attention in segments where buyers are actively seeking upgrades from older equipment generations. The most consequential trend is not simply the number of competitors, but the growing importance of compliance readiness, modularity, and segment-specific credibility as barriers to sustained growth.
Future Outlook: Strategic Trends and Emerging Risks
Over the next three to five years, one of the most important trends will be the continued alignment of equipment design with updated safety and performance expectations across both human athletic training and animal agility applications. As inspection protocols, course design practices, and general equipment safety specifications mature, buyers will increasingly favor products that can demonstrate consistent compliance and reduced setup risk. This creates an opportunity for manufacturers that invest in validated design processes, transparent documentation, and training support materials that help end users implement equipment correctly. Anticipated course-design refinements and equipment-requirement adjustments are likely to make reliability and adaptability central purchasing criteria rather than secondary considerations.
A second trend is the growing preference for modular, multi-purpose equipment that supports faster course construction, flexible drill programming, and space-efficient storage. Facilities operating under constrained floor space or rotating usage schedules will favor systems that can be reconfigured quickly and withstand frequent rearrangement. This shift opens opportunities for suppliers that combine durable construction with adjustable components, standardized connection points, and clear instructional guidance. The commercial appeal of such systems extends beyond elite programs, as schools, community sports organizations, and home users look for equipment that can serve multiple activities without requiring separate dedicated inventory.
A third development to watch is the gradual broadening of target segments through intersectional demand. Conditioning programs are increasingly incorporating agility work into broader athletic development plans, while pet-related training continues to gain visibility among household consumers and specialized service providers. These overlapping demand streams may encourage manufacturers to create product families that span multiple user groups without fragmenting brand identity. The opportunity lies in designing tiered offerings that retain professional-grade options for high-intensity use while delivering accessible, low-maintenance variants for lighter or intermittent applications.
Potential risks include persistent sensitivity in material and logistics costs, uneven adoption of newer safety expectations across regions, and the possibility that rapid product proliferation could reduce differentiation if competitors converge on similar feature sets. Companies that fail to monitor regulatory updates or rely on outdated specifications may face renegotiation pressure from procurement teams and event organizers. In addition, over-extension into too many unrelated segments can dilute manufacturing focus and weaken quality control. Balanced expansion, disciplined compliance integration, and clear customer targeting will be critical to navigating these uncertainties.
Strategic Recommendations for Decision-Makers
Manufacturers and product developers should prioritize safety-aligned design and modular versatility as core investment themes. Engineering teams can benefit from mapping upcoming regulatory expectations early, testing materials against broader usage scenarios, and developing product families that allow users to scale from basic training to higher-intensity applications. Clear documentation, consistent quality control, and straightforward setup mechanisms will strengthen acceptance among institutional buyers and event organizers who value predictable performance.
Investors and strategic partners should evaluate opportunities based on segment relevance, compliance readiness, and supply chain flexibility rather than top-line growth alone. Categories with recurring institutional procurement, multi-site distribution potential, and demand from both professional and educational environments may offer more durable revenue profiles. Due diligence should include an assessment of how well target companies can adapt product portfolios to evolving safety expectations and whether their manufacturing footprint supports stable lead times and regional responsiveness.
Procurement leaders and facility operators should treat equipment selection as a long-term operational decision rather than a short-term cost exercise. Prioritizing certified, durable, and reconfigurable equipment can reduce replacement frequency, simplify staffing training, and support more flexible programming across sports, fitness, and education settings. Buyers should also evaluate supplier support services, replacement part availability, and product roadmaps to ensure that current purchases remain aligned with future usage needs.
For organizations seeking detailed segmentation data, regional demand patterns, and customized scenario planning, a comprehensive market intelligence report can provide a more granular foundation for strategic planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Agility Training Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
HR Consulting Market: Why 5.25% CAGR and $66B by 2032 Signal a Strategic Shift
By pmarketresearch, 2026-09-18
The Worldwide HR Consulting Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The global HR consulting sector has demonstrated resilient expansion over the past half-decade, evolving from a traditional advisory function into a strategic capability that organizations treat as critical infrastructure. Total market revenue climbed from approximately USD 36,150 million in 2020 to an estimated USD 46,250 million in 2025, reflecting a compound annual growth rate of 5.25 percent across the historical window. The trajectory is expected to continue upward through the forecast period ending in 2032, with revenue projected to reach USD 66,170 million. This growth trajectory signals sustained demand for human capital advisory services, yet the pace of expansion masks underlying structural shifts that are reshaping competitive dynamics and value creation pathways.
Regional distribution reveals a mature core alongside rapidly scaling markets. North America continues to command the largest revenue share, reflecting the depth of enterprise consulting adoption and the concentration of global headquarters in the region. Europe maintains a substantial footprint, supported by established regulatory frameworks and corporate governance expectations that drive consulting engagement. Asia Pacific represents the most dynamic growth corridor, fueled by expanding multinational operations, rising labor costs, and accelerated digital transformation initiatives across both established economies and emerging markets. Latin America and the Middle East and Africa collectively contribute smaller but steadily increasing revenue streams, often tied to infrastructure investments, resource sector workforce planning, and public sector modernization programs.
Beneath the aggregate figures, the sector faces three pressing challenges that will define competitive positioning over the next several years. First, the integration of artificial intelligence into HR processes has moved from experimental pilots to operational expectations. Organizations now expect consulting providers to deliver not only strategic recommendations but also implementation roadmaps for AI-enabled recruitment, compensation modeling, workforce analytics, and employee experience design. Firms that cannot credibly bridge strategy and technology execution face growing pressure on their relevance and pricing power.
Second, regulatory and compliance complexity is intensifying across multiple jurisdictions. Data privacy requirements, emerging standards for responsible AI deployment, and evolving labor classification rules are complicating the delivery of HR advisory services. Consulting engagements now routinely require governance frameworks, audit readiness, and cross-border compliance coordination. This environment raises the bar for expertise and increases the operational cost of service delivery, particularly for firms managing global client portfolios.
Workday Human Capital Management Consulting Service Market
Third, talent itself has become the most constrained input. HR consulting firms are competing for the same scarce pool of professionals who combine domain expertise in human capital strategy with fluency in data analytics, technology implementation, and change management. The talent shortage affects both the supply side of the consulting industry and the demand side of client organizations, creating a dual pressure point. Clients are increasingly scrutinizing whether consulting engagements produce measurable improvements in workforce effectiveness rather than deferring action through prolonged advisory cycles.
Key Drivers of Market Change
Several interconnected forces are accelerating demand for HR consulting services and reshaping how value is delivered. Understanding these drivers is essential for executives evaluating partnership opportunities, investors assessing sector exposure, and service providers refining their go-to-market strategies.
Technology Innovation and AI Integration
The adoption of artificial intelligence across HR functions has reached a point where it is no longer a differentiator but a baseline expectation. Recent industry data indicates that a substantial majority of HR leaders are engaging with AI capabilities at some level, spanning talent acquisition screening, skills inference, compensation benchmarking, attrition risk modeling, and employee service automation. This broad participation is generating demand for specialized consulting support in AI strategy, workforce readiness, and ethical deployment. Organizations need help identifying where AI can improve decision quality, how to structure data and governance for responsible use, and how to redesign roles and workflows as automation absorbs routine tasks.
Technology-driven transformation is also expanding the scope of HR consulting beyond traditional advisory work. Implementation support for HR technology platforms, integration of analytics dashboards, and redesign of employee experience journeys are increasingly bundled into larger transformation engagements. Providers that combine domain expertise with demonstrated capability in technology enablement are capturing share in this expanding service perimeter. The emphasis is shifting from advising on what to do to helping organizations execute, measure, and iterate.
Regulatory and Compliance Pressures
The regulatory environment surrounding HR data, algorithmic decision-making, and workforce classification is becoming more demanding. Firms operating across multiple jurisdictions must navigate divergent privacy regimes, emerging certification expectations for AI systems, and evolving standards for transparency in automated HR processes. In response, consulting providers are building compliance-oriented service offerings that help clients establish governance structures, document decision logic, and align HR practices with responsible AI principles.
PW Consulting
Certification frameworks and audit readiness are gaining prominence as tangible signals of rigor. For example, the integration of AI into HR business processes is increasingly accompanied by governance measures designed to ensure compliance and human-centered outcomes. This trend benefits consulting firms that can offer structured methodologies for embedding governance into HR operations, as well as firms that can advise on cross-border data handling and regulatory alignment. The compliance dimension also raises the cost of entry for less mature providers, reinforcing the advantage of established players with global delivery capabilities and dedicated risk and compliance practices.
Demand-Side Shifts in Enterprise Behavior
Enterprise buyers are reevaluating how they allocate HR spending, with growing attention to total workforce costs and the efficiency of HR service delivery. Leadership teams are examining not only direct HR staff costs but also the expenditures associated with systems, chargebacks, and external service utilization. This more granular cost perspective is prompting organizations to seek consulting support for workforce optimization, outsourcing decisions, and the redesign of HR operating models. The objective is to improve value delivery while maintaining or enhancing employee experience and operational resilience.
At the same time, the strategic importance of talent management has intensified. Competition for skilled workers, particularly in technology, analytics, and specialized professional domains, is pushing organizations to invest more heavily in leadership development, succession planning, and skills-based talent architectures. Consulting engagements are increasingly focused on building internal capabilities for continuous learning, skill gap closure, and mobility programs that reduce dependency on external hiring. The shift from transactional HR support to strategic workforce planning reflects a broader recognition that human capital decisions are direct levers on competitive performance.
Cost Structure and Location Dynamics
Cost considerations continue to influence both the supply and demand sides of the HR consulting market. On the client side, location choices affect labor costs, recruiting expenses, and the economics of global HR operations. Organizations are weighing the trade-offs between centralized and distributed HR service delivery, often seeking consulting advice on how to structure shared services, offshore or nearshore components, and technology-enabled self-service models. On the provider side, consulting firms are managing their own cost structures by balancing senior advisor capacity with scalable delivery resources, including analysts, technologists, and implementation specialists.
This dynamic is encouraging a more modular approach to service delivery. Rather than offering monolithic advisory engagements, many providers are designing tiered offerings that allow clients to select the level of strategic depth, data analysis, and implementation support they require. The result is a broader accessible price point for mid-sized enterprises while preserving high-value strategic work for large, complex organizations. Cost transparency and delivery efficiency are becoming competitive differentiators in a market where buyers are increasingly sophisticated about what they are paying for.
Competitive Landscape and Leading Strategies
The HR consulting market is characterized by a diverse set of participants spanning global professional services networks, management consultancies with human capital practices, and specialized HR advisory firms. Market concentration remains moderate, with the top three firms accounting for a minority share of total revenue and the top five collectively representing roughly one-third of the market. This fragmentation reflects the breadth of service requirements and the continued presence of regional and niche players that compete on specialization, local relationships, and cost effectiveness.
Several strategic archetypes are evident among leading participants. Global professional services organizations offer comprehensive human capital capabilities integrated with broader consulting, technology, and risk advisory portfolios. Their scale, global delivery footprint, and ability to combine workforce strategy with technology implementation and compliance support position them well for large, multi-jurisdiction engagements. These firms are increasingly emphasizing workforce transformation, HR technology adoption, and organizational design as interconnected workstreams rather than standalone advisory projects.
Management Consulting Services Market
Management consultancies bring a strong orientation toward organizational performance, leadership development, and human capital strategy as part of enterprise-wide transformation. Their value proposition often centers on aligning people strategy with business strategy, improving operating model design, and building leadership pipelines that support growth and change. These firms compete on strategic depth, executive relationships, and the ability to connect workforce decisions to financial and operational outcomes.
Specialized HR and human capital firms focus deeply on talent management, executive search, compensation and benefits, retirement, health, and workforce analytics. Their differentiation comes from domain depth, proprietary data and benchmarks, and established reputations in specific capability areas. For clients with concentrated needs—such as benefits restructuring, executive assessment, or compensation strategy—these specialists can offer credibility and precision that broader consultancies may not match without partner ecosystems.
Technology-forward providers are gaining traction by combining consulting with implementation and platform capabilities. The launch of AI-powered workforce solutions in partnership with technology vendors illustrates the trend toward embedding intelligence into HR processes and offering clients a more complete path from strategy to deployment. This model is appealing to organizations that want to reduce the friction between advisory recommendations and operational execution.
Recent developments highlight how leading firms are responding to these dynamics. Major consultancies continue to publish large-scale workforce and human capital trends research, using data from thousands of leaders across numerous countries to frame the strategic conversation around work, workforce, and workplace change. Such research serves both to establish thought leadership and to inform consulting propositions. In parallel, acquisitions and capability expansions are being used to deepen expertise in fiduciary, tax-related HR services, and AI-driven workforce solutions. These moves reflect a strategic push to broaden service perimeters, strengthen compliance and risk capabilities, and embed technology more directly into consulting delivery.
The competitive landscape is evolving along multiple axes. Consolidation is occurring through acquisition as larger firms absorb specialized capabilities and expand their foothold in adjacent service areas. Differentiation is intensifying as firms compete on AI readiness, data assets, implementation depth, and regional expertise. New entrants and technology companies are also pressing into the space, particularly where HR technology platforms offer embedded advisory features or partner ecosystems that blur the line between software and consulting. For buyers, this evolution creates more options but also greater complexity in evaluating which provider model best fits a given need.
Forward Outlook: Key Trends and Commercial Implications
Looking ahead to the 2026–2032 period, several trends are likely to shape the direction of the HR consulting market and create distinct commercial opportunities.
The first trend is the maturation of AI-enabled HR consulting from experimentation to operational integration. As organizations move beyond pilot projects, demand will grow for structured programs that embed AI into recruitment, workforce planning, compensation analysis, and employee experience design while maintaining governance and human oversight. Consulting firms that can provide end-to-end support—strategy, data readiness, model selection, change management, and continuous measurement—will capture premium engagements. The opportunity lies not only in advising on AI adoption but in helping clients build the organizational capabilities required to sustain it.
The second trend is the continued shift toward total workforce cost optimization and HR operating model redesign. Enterprises are increasingly treating HR as a value-delivery function that must justify its cost structure and demonstrate efficiency. This creates demand for consulting support in shared services design, outsourcing strategy, technology consolidation, and the reallocation of HR resources toward higher-impact activities. Providers that can combine cost analysis with employee experience and compliance considerations will be better positioned to deliver recommendations that are both financially and operationally credible.
The third trend is the growing importance of skills-based talent architectures and internal mobility. As external hiring becomes more competitive and expensive in key domains, organizations are investing in reskilling, internal talent marketplaces, and dynamic workforce planning. Consulting engagements will increasingly focus on designing skill taxonomies, identifying capability gaps, and building programs that move talent to where it is needed. This trend aligns with broader digital transformation efforts and offers a pathway to reduce reliance on costly external recruitment while improving retention and engagement.
Strategic Recommendations for Decision Makers
For enterprise leaders and strategy teams, the priority is to treat HR consulting as a strategic lever rather than a reactive support function. Engage providers with clear scope definitions that link workforce objectives to measurable business outcomes, and insist on roadmaps that include implementation, governance, and performance tracking. Evaluating partners on their ability to combine strategy, data, and technology execution will reduce the risk of recommendations that are difficult to operationalize.
For investors assessing exposure to the HR consulting sector, differentiate between business models. Firms with strong AI and technology integration capabilities, scalable delivery platforms, and comprehensive compliance support are likely to benefit from the shift toward AI-enabled, governance-aware HR services. Specialized firms with deep domain expertise and proprietary benchmarks can command premium positioning in focused segments. Monitoring deal activity, capability expansions, and research output can provide early signals of where competitive advantage is being built.
For procurement and sourcing leaders, the expanding menu of provider models calls for more nuanced evaluation criteria. Consider whether a single global provider, a specialized partner, or a combined ecosystem best matches the organization's needs across strategy, implementation, and ongoing support. Request transparent cost structures, delivery models, and evidence of measurable impact. Given the pace of change in technology, regulation, and workforce expectations, timely access to detailed segment data and customized advisory input can materially improve sourcing decisions and reduce implementation risk.
Detailed segmentation data, regional revenue estimates, service-type breakdowns, industry-vertical analysis, and company-level profiles are available in the full research report, supporting deeper due diligence and tailored strategy development.
For detailed analysis of this topic, please visit the official page: Worldwide HR Consulting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Vise Grips Market 2026: Why 4.25% CAGR Reshapes Industry Dynamics
By pmarketresearch, 2026-09-18
Worldwide Vise Grips Market: Strategic Shifts and Commercial Opportunities in a Consolidating Landscape
Market Snapshot: Scale, Trajectory, and Core Headwinds
The global market for vise grips and locking pliers has established itself as a mature yet steadily expanding segment within the broader hand tool industry. Anchored by a base-year valuation in 2025 and projected to grow at a compound annual rate of approximately 4.25 percent through 2032, the market reflects a baseline trajectory shaped by steady industrial demand, replacement cycles in professional trades, and sustained interest from do-it-yourself consumers. From 2020 to 2025, the segment navigated post-pandemic supply disruptions, raw material volatility, and shifting end-use spending patterns, ultimately settling into a phase of moderate but consistent expansion. The forward-looking period through 2032 indicates that growth will remain incremental rather than explosive, with revenue compounding as manufacturers refine product lines, expand distribution reach, and capture share in specialized applications where secure clamping and high gripping force remain non-negotiable.
PW Consulting
Despite this constructive outlook, the industry stands at a series of operational and strategic crossroads. First, cost volatility in primary input materials has become a recurring pressure point. The price environment for hot-rolled coil steel, the foundational material for forged locking pliers jaws and bodies, has fluctuated within a range that directly influences manufacturing margins and pricing strategies. When steel costs climb, producers must decide whether to absorb the impact, pass it downstream, or accelerate redesigns and process efficiencies to offset material intensity. This dynamic is particularly acute for mid-tier manufacturers who lack the scale to hedge raw material exposure or the premium positioning to justify rapid price adjustments without risking volume erosion.
Grippers Market
Second, the competitive landscape is tightening around concentration and differentiation. A relatively small group of established players accounts for a substantial share of total market revenue, signaling that scale, brand recognition, and distribution leverage matter more than ever. For newer entrants or regional specialists, this concentration creates a barrier to rapid expansion unless they can deliver clear functional advantages, niche application fit, or localized service models that larger multinationals cannot easily replicate. At the same time, consolidation pressures are reshaping how products move from factory to end user, with distributors and professional retailers increasingly favoring suppliers who can offer consistent quality, broad catalog depth, and reliable lead times across multiple markets.
Tension Hand Grip Market
Third, the sector is grappling with a subtle but important regulatory and safety expectation shift. Locking pliers used in industrial, automotive, and welding-adjacent applications are expected to meet evolving material strength, durability, and ergonomic standards. While these requirements do not radically alter the core product category, they raise the compliance burden for manufacturers and create an uneven playing field where brands that have already aligned their design and quality assurance processes with recognized international guidelines can move faster and with less friction. The net effect is a market that rewards operational discipline and penalizes reactive product development.
Key Drivers Reshaping the Vise Grips Landscape
Market evolution in this segment is being propelled by a combination of product innovation, changing end-user expectations, regulatory alignment, and cost structure pressures. Each driver carries distinct implications for how companies should position their portfolios and manage growth.
Functional Innovation and Design Refinement
The most visible driver is continuous product refinement aimed at improving grip performance, accessibility, and corrosion resistance. Locking pliers have moved beyond basic jaw configurations into more application-specific designs that address real-world workspace constraints. Recent releases have emphasized aggressive tooth patterns for stronger bite in demanding material conditions, extended nose geometries for improved reach in confined spaces, and protective coatings that extend service life in environments where moisture, welding spatter, or chemical exposure can accelerate wear. These enhancements matter because they convert a mature product category into a still-evolving one, allowing manufacturers to justify premium positioning while retaining relevance with professional users who depend on tool reliability every day.
For manufacturers, this innovation cycle is not merely cosmetic. It reshapes purchasing criteria among professional buyers, who increasingly evaluate locking pliers based on usable reach, jaw articulation, grip retention under load, and resistance to corrosion after repeated use. Companies that can translate workshop pain points into tangible design upgrades are better positioned to retain share in high-value professional segments, while those relying on generic iterations risk being undersold or replaced by specialty alternatives.
Professional Demand and Application Persistence
On the demand side, the durability of the vise grips market is closely tied to the persistence of core application areas. Automotive repair, construction and renovation, and metal fabrication continue to generate reliable demand because these environments require secure clamping, adjustable holding force, and tools that can withstand repeated professional use. Unlike consumer-electronics categories that can be disrupted by new technologies, locking pliers benefit from being embedded in workflows where mechanical clamping remains indispensable. This structural demand provides a floor under market growth and explains why revenue has held up even through periods of broader economic uncertainty.
At the same time, demand patterns are shifting within these application pools. Professional automotive and industrial users are increasingly favoring tools that offer a balance of high gripping force and maneuverability, especially in modern repair contexts where engine bays and assembly spaces are more densely packed. In construction and renovation, project-based purchasing is favoring suppliers that can deliver consistent availability across popular sizes and configurations. For DIY and home maintenance segments, the growth path is more price-sensitive and education-driven, requiring clearer communication about tool function, sizing, and safe use. The practical takeaway is that application persistence does not guarantee uniform growth; it rewards segmentation discipline and messaging precision.
Regulatory Expectations and Compliance as Differentiation
Regulatory and standards-based expectations are becoming a more meaningful differentiator rather than a mere compliance checkbox. Locking pliers used in industrial and welding-adjacent settings must align with general hand tool safety expectations, including material strength, structural integrity, and ergonomic considerations. While these are baseline requirements, they create a competitive tilt toward manufacturers that already operate mature quality systems and can demonstrate conformance with recognized ISO and ANSI-aligned guidelines. Compliance, in practice, reduces downstream friction for distributors and professional buyers who want to minimize liability and ensure tool reliability across fleets and job sites.
This dynamic is nudging the market toward a higher quality baseline. It also raises the stakes for smaller producers who may lack formal testing infrastructure or consistent documentation processes. In the near term, alignment with recognized standards is increasingly tied to procurement eligibility in professional and institutional environments, making it a commercial lever as much as a technical one.
Raw Material Economics and Supply Chain Discipline
Cost structure remains a critical driver because the economics of forged locking pliers are closely tied to steel availability and pricing. Hot-rolled coil prices have occupied a volatile band in recent periods, with notable regional variation between North American and global benchmarks. When input costs rise, the impact is felt across tooling, forging, heat treatment, and logistics, forcing manufacturers to manage not only unit cost but also inventory timing, order cadence, and supplier relationships. Companies with stronger procurement planning, flexible sourcing, and efficient forging workflows can protect margins more effectively than those relying on ad hoc purchasing or rigid cost structures.
The broader implication is that supply chain discipline is no longer a back-office function; it is a strategic variable that influences pricing power, product availability, and responsiveness to demand spikes. In a market where differentiation is increasingly subtle, cost management and production reliability can become the deciding factors in whether a manufacturer can sustain profitability while investing in product development.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The competitive environment in the vise grips market is defined by a core group of established manufacturers with strong brand equity, broad professional distribution, and distinct design philosophies. Market concentration is meaningful enough that scale advantages in procurement, manufacturing, and channel reach matter, but it is not so extreme that niche specialists cannot compete on performance, specialization, or regional fit. The result is a landscape where positioning choices are becoming more deliberate and where product storytelling must rest on functional credibility rather than generic claims.
Among the leading players, Irwin Tools stands out as a long-recognized anchor in the locking pliers category, with a portfolio that spans curved jaw, straight jaw, long nose, fast-release, and specialty configurations. Its strategy centers on broad application coverage across industrial, automotive, and construction use cases, reinforced by familiar brand recognition and deep channel presence. Snap-on occupies a premium professional tier, emphasizing aggressive tooth design, longer nose architectures for tighter access, and variants associated with U.S. manufacturing for segments that value provenance and high-end performance. Grip-on Tools brings a specialist orientation from Europe, combining a wide professional range of locking pliers and C-clamps with corrosion-resistant innovations such as epoxy resin coatings, an approach that aligns well with users exposed to harsh working conditions. Knipex maintains a reputation rooted in precision and durability, targeting professional trade and industrial users with grip pliers and locking-style tools that prioritize fit, feel, and consistent performance. Klein Tools positions around professional sets and high-torque models tailored to electrical, construction, and maintenance professionals, leveraging its strong association with trade-quality hand tools. Bahco contributes a European professional hand tool perspective under a larger regional group structure, with straight-jaw and other variants aimed at industrial and maintenance users. Toptul represents a Taiwan-based manufacturing and supply presence that supports professional and industrial tool markets with jaw locking pliers, illustrating how regional producers can remain relevant by serving both local demand and export channels.
The strategic differentiation among these companies is not simply about catalog size. It is about which value proposition resonates with the buyer in front of them. For high-end professional users, the purchase decision often hinges on perceived durability, biting performance, ergonomic comfort, and availability of trusted service support. For broader industrial procurement, consistency across reorder cycles, quality documentation, and predictable lead times can be equally important. For more price-conscious or project-based buyers, the question is whether the tool offers dependable performance at a defensible cost. Companies that understand which lever matters most in each channel are better equipped to avoid price-only competition and protect margin.
Recent product activity reinforces this positioning race. New catalog expansions have highlighted wider ranges, corrosion-resistant coatings, and welding-related clamp variants, while introductions of aggressive teeth and longer nose profiles reflect a focused effort to improve accessibility and grip in constrained work environments. Updates to grip pliers sizing and catalog breadth show that manufacturers are still investing in practical variations that help them cover more professional use cases without abandoning their core identity. This is a sign of a market that is maturing in product philosophy: rather than attempting radical reinvention, leaders are refining the details that matter most in daily use, which tends to be a more sustainable growth path for a mature hand tool category.
Looking at market evolution, the most likely trajectory is a combination of consolidation pressure and selective fragmentation. Larger multinationals will continue to leverage scale, global distribution, and cross-brand portfolio strength, while specialized European and Asia-based manufacturers will compete by emphasizing corrosion resistance, specialized clamping styles, and regional service relationships. The middle ground is where the competition will be sharpest, because that is where mid-tier players must prove that they can match the reliability expectations of professional buyers while remaining cost-competitive. New entrants will likely find the most traction not by competing head-on with top-tier brands across all segments, but by targeting underserved applications, regional distribution gaps, or specific user groups that value specialized features enough to pay a premium or switch suppliers.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
The market's next phase is likely to be shaped by incremental but strategically meaningful trends rather than sudden disruption. The most consequential will be the continued elevation of product specialization as a growth lever. As professional users face tighter workspaces, more varied materials, and higher expectations for corrosion resistance and ergonomic comfort, locking pliers portfolios will keep expanding in targeted variants rather than in undifferentiated breadth. This trend favors companies that can map design improvements directly to application needs and communicate those benefits clearly to buyers who may otherwise default to familiar legacy products.
A second trend is the growing importance of compliance and quality assurance as commercial enablers. As procurement processes in industrial, automotive, and institutional settings become more rigorous, documented conformance to recognized safety and durability expectations will increasingly influence supplier selection. This does not mean regulation will dominate market growth, but it will reinforce a quality floor and reward manufacturers who can demonstrate consistent performance, reliable materials, and traceable production practices. Over time, this may narrow the gap between premium brands and competent mid-tier competitors, provided the latter can match the documentation and testing rigor buyers now expect.
A third trend is the ongoing tension between raw material cost pressure and margin resilience. Steel price fluctuations will continue to test production economics, but the upside is that companies with disciplined sourcing, efficient forging, and clear product tiering can use cost variability as a catalyst for process improvement rather than simply a margin threat. The practical opportunity lies in designing portfolios that balance premium variants with high-volume workhorse models, allowing manufacturers to capture professional willingness to pay while preserving volume in price-sensitive channels. The main risk is complacency: if manufacturers treat input cost swings as temporary rather than structural, they may underinvest in efficiency and lose competitiveness when pricing environments normalize.
Across these trends, the clearest commercial opportunity is to align product development, channel strategy, and procurement readiness with the specific requirements of professional applications where secure clamping remains essential. Markets that stay anchored in durable application demand can still generate meaningful growth, but only if companies treat specialization, compliance readiness, and cost discipline as integrated strategic choices rather than separate functions.
Strategic Actions for Decision Makers
For manufacturers, the priority is to sharpen portfolio segmentation so that each product tier serves a clear application and channel fit. Expanding catalog breadth should be paired with documented functional advantages, especially around grip performance, reach, and corrosion resistance, because these are the attributes that professional buyers use to justify repurchase and fleet standardization. Equally important is building procurement and quality documentation into the product story, since compliance readiness is increasingly part of how suppliers win and retain professional accounts.
For investors, the most durable value creation in this market is likely to come from companies that combine steady application demand with disciplined cost control and credible product differentiation. The segment is not a high-growth story in the volatile sense, but it can offer predictable compounding for players that manage steel exposure well, maintain channel strength, and invest in practical innovations that reinforce repeat purchase behavior. Due diligence should weigh not just brand recognition but also production efficiency, regional sourcing flexibility, and the ability to expand into application-specific variants without diluting core margins.
For procurement leaders and professional buyers, the decision framework should shift from lowest unit price to total cost of reliable use. Evaluating locking pliers by jaw performance, ergonomic fit, corrosion resilience, and supply consistency can reduce downtime and replacement frequency over time. Sourcing from manufacturers with established quality processes and clear standards alignment can also lower procurement risk in environments where tool failure creates safety or workflow disruptions.
For stakeholders who need to move quickly across these dimensions, detailed segmentation data, regional breakdowns, and company-level scenario analysis can substantially improve planning accuracy. A comprehensive research report can provide the deeper cuts needed to compare product tier economics, map competitive positioning by channel, and evaluate which application segments offer the best near-term expansion potential. Access to that level of detail makes it easier to convert broad market visibility into specific product, pricing, and sourcing decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Vise Grips Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Soil Fumigant Market at $865M in 2026: True Growth Engines & Regional Dynamics
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Soil Fumigant Market
Market Context and Core Challenges
The global soil fumigant market has demonstrated sustained expansion, with total industry revenue progressing from approximately 672.4 million USD in 2020 to an estimated 842.5 million USD by 2025. Forward projections indicate continued growth through 2032, driven by consistent annual increases that point toward a market surpassing the 1.15 billion USD threshold by the end of the forecast period. The compound annual growth rate across this trajectory underscores a steady, rather than explosive, expansion pattern. This measured pace reflects an industry navigating both persistent agricultural demand and intensifying regulatory and environmental scrutiny.
Several structural challenges define the current inflection point for soil fumigant suppliers, distributors, and end-users. First, regulatory frameworks continue to tighten around application protocols, buffer zone requirements, and exposure mitigation measures. Jurisdictions such as the United States maintain reregistration eligibility decisions that establish baseline safety parameters for active ingredients including chloropicrin, metam sodium, and 1,3-dichloropropene. Regional authorities have introduced time-of-day restrictions and additional mitigation mandates, particularly in high-value crop regions where residential proximity and environmental sensitivity heighten compliance complexity. These evolving requirements reshape operational workflows and increase the cost of compliant application.
Second, the phase-down of methyl bromide under international environmental agreements has permanently altered the product mix available to growers. While limited critical use exemptions and quarantine applications persist in select regions, the broader unavailability of this once widely deployed fumigant has accelerated the transition toward alternative chemistries and integrated pest management approaches. Suppliers and distributors must continuously adapt product portfolios to match shifting compliance landscapes while ensuring effective soil-borne pest control.
Third, supply chain dynamics and raw material availability introduce volatility into cost structures. Fumigant production depends on upstream chemical intermediates whose pricing and supply consistency are influenced by broader specialty chemical manufacturing conditions. Fluctuations in precursor availability can affect formulation stability, delivery timelines, and ultimately the economics of both manufacturers and end-users. Organizations that lack diversified sourcing strategies or inventory flexibility face heightened exposure to these input-side disruptions.
Taken together, these challenges create a market environment where operational agility, regulatory literacy, and product diversification determine competitive resilience. Companies that treat compliance and supply chain management as strategic capabilities rather than administrative burdens are better positioned to sustain growth through the forecast period.
Paraquat Market
Key Drivers Shaping Market Trajectory
Technological innovation continues to reshape how soil fumigants are formulated, applied, and integrated into broader crop protection programs. Advances in delivery methods, including drip and shank application systems, enable more precise placement and reduced off-target exposure. Formulations that combine multiple active ingredients or integrate complementary modes of action address the growing need for broad-spectrum control against nematodes, weeds, and soil pathogens. These innovations respond directly to the operational constraints imposed by tighter application windows and heightened safety requirements. Manufacturers investing in application-compatible formulations and technically supported service models gain a distinct advantage in markets where performance consistency and regulatory compliance must be delivered simultaneously.
Policy and regulatory evolution operates as both a constraint and a catalyst. Reregistration programs, buffer zone mandates, and region-specific application restrictions define the operational boundaries within which fumigants can be deployed. In key agricultural states, new regulations affecting 1,3-D use and time-of-day application limits for chloropicrin and metam sodium have already altered field practices. At the same time, regulatory pressure accelerates the adoption of alternative chemistries and encourages investment in products that meet stricter exposure reduction standards. The regulatory environment therefore filters out less adaptable offerings while creating demand for solutions that align with contemporary safety and environmental expectations. Companies that maintain proactive regulatory monitoring and engage early in compliance-driven product development are better equipped to capture shifting demand.
Demand-side behavior reflects changing grower priorities driven by crop intensity, soil health considerations, and the economic imperative of yield protection. High-value fruit and vegetable production, cereals and grains, oilseeds and pulses, and turf and ornamental sectors all rely on pre-plant soil treatment to manage soil-borne threats that can undermine establishment and productivity. As rotational intensity increases and land use becomes more optimized, the need for reliable soil pest control remains stable even as product preferences evolve. Growers increasingly seek solutions that fit within integrated management programs, reduce application risk, and support consistent crop outcomes. This demand profile favors suppliers that can provide technical guidance, formulation flexibility, and regionally appropriate product recommendations rather than commoditized chemical supply alone.
Cost structure and supply chain organization represent a fourth critical driver. The reliance on specialty chemical intermediates means that feedstock availability, production capacity, and logistics performance directly influence product pricing and market responsiveness. Recent corporate activity illustrates how the industry is adapting to these dynamics. In May 2025, Dow Inc. completed the sale of its Telone soil fumigation product line to TriCal Soil Solutions, Inc., a transaction that realigned product ownership within a distribution and application-focused business model. Such moves highlight a broader trend in which manufacturers, distributors, and applicators reorganize to improve market access, streamline compliance management, and strengthen regional service capabilities. Organizations that integrate production, distribution, and application expertise can better absorb input volatility and deliver consistent value to end-users.
These drivers interact continuously. Regulatory changes influence which technologies gain traction, demand patterns determine where innovation is most needed, and supply chain structure shapes which companies can scale effectively. The market is moving toward a configuration in which technical performance, compliance readiness, and service integration are jointly evaluated by buyers, rather than price or product name acting as the primary decision factor.
Competitive Landscape and Leading Strategies
The competitive field features a mix of global crop protection companies, specialty chemical producers, and regionally focused distributors and applicators. Each group pursues a distinct strategic positioning that reflects its capabilities, regulatory footprint, and market access model.
Global Crop Protection and Specialty Chemical Players
Large multinational providers leverage broad agricultural portfolios, established regulatory affairs functions, and global manufacturing scale. Their soil fumigant offerings are typically positioned within integrated crop protection programs that combine chemical control with agronomic guidance. Companies such as Corteva Agriscience, BASF SE, Syngenta AG, FMC Corporation, and ADAMA Agricultural Solutions operate in this segment, emphasizing nematode, weed, and pathogen management through chloropicrin, metam sodium, and related formulations. Their advantage lies in the ability to support customers across multiple crop systems, maintain compliance documentation across jurisdictions, and integrate fumigant use with broader pest and disease management strategies.
PW Consulting
Specialty chemistry-focused organizations bring differentiated product technologies to the market. Arkema S.A., for example, offers DMDS-based fumigants designed for drip or shank applications in fruits, vegetables, and horticultural crops, emphasizing broad-spectrum control and application flexibility. LANXESS AG and Detia Degesch GmbH contribute through fumigant intermediates and specialty products that support formulation diversity and supply chain resilience. These players often compete on technical specificity, application compatibility, and the ability to meet particular regulatory or agronomic requirements that broader portfolios may address less directly.
Distribution and Application-Focused Operators
Distributors and applicators represent a critical layer of the market, particularly in regions where product stewardship, application compliance, and local agronomic support determine adoption. TriEst Ag Group and TriCal Group have strengthened their position through targeted acquisitions, including the 2025 acquisition of Dow's Telone product line, which expanded their soil solution capabilities and reinforced their role as both distributor and applicator. AMVAC Chemical Corporation, Gowan Company, UPL Ltd., Tessenderlo Group, Trinity Manufacturing, and Draslovka Services operate across varying combinations of manufacturing, distribution, and regional service models. Their strategic value derives from proximity to end-users, application expertise, and the ability to navigate local regulatory conditions while maintaining product availability and performance consistency.
Strategic Differentiation and Market Evolution
Leading companies differentiate through a combination of portfolio breadth, application support, regulatory readiness, and regional execution capability. Some prioritize integrated crop protection positioning that connects soil fumigation to broader agronomic outcomes. Others emphasize formulation technology and application method compatibility to meet specific compliance and performance demands. A third group focuses on distribution and application integration, ensuring that products reach the field with the technical support necessary for safe and effective use.
Greenhouse Soil Market
The market structure is evolving through selective consolidation and the realignment of product ownership. Transactions such as the divestiture of product lines to specialized distributors reflect a trend in which manufacturing assets and application-focused businesses reconfigure to capture value more efficiently. At the same time, new entrants and regional operators continue to establish niches wherever local crop systems, regulatory conditions, or supply gaps create opportunity. The overall effect is a landscape that is neither fully consolidated nor highly fragmented, but rather organized around clusters of capability that match specific market needs. Competition increasingly centers on reliability, compliance assurance, and the quality of technical support delivered alongside the product itself.
Future Outlook and Emerging Opportunities
Over the next three to five years, the soil fumigant market is likely to be shaped by three interconnected developments. First, regulatory refinement will continue to define where and how fumigants can be applied, with incremental restrictions, updated buffer requirements, and tighter application timing likely to persist in sensitive regions. This will reward companies that already operate with strong compliance infrastructure and penalize those that rely on reactive adjustment. Second, application technology and formulation innovation will gain relative importance as growers seek to maintain efficacy within narrower operational windows. Drip-compatible products, controlled-release approaches, and integrated treatment programs that combine chemical and non-chemical tactics will become more central to purchasing decisions. Third, supply chain reorganization will likely continue, with further portfolio adjustments, regional capacity realignment, and partnership models emerging to manage raw material exposure and improve delivery reliability.
These trends translate into concrete commercial opportunities. Manufacturers and formulators can expand value by developing products that align with prevailing application methods and compliance requirements, reducing the friction associated with adoption. Distributors and applicators can deepen their role as regional solutions providers, combining product selection, application scheduling, and stewardship support to build customer loyalty and differentiate from commodity supply models. Investors and strategic buyers can look for assets that enhance application capabilities, strengthen regulatory readiness, or fill supply gaps in high-demand crop regions. At the same time, uncertainty remains. Regulatory trajectories can shift with policy changes, raw material volatility can compress margins, and regional demand patterns can diverge as crop economics and land use evolve. Organizations that treat these variables as manageable risks through diversification, technical investment, and close market monitoring will be better positioned to capture the upside while limiting exposure to disruption.
Strategic Actions for Decision-Makers
For manufacturers and formulators, the priority is to align product development with the operational realities of modern application and compliance. Investing in formulations that support drip and shank applications, maintaining clear regulatory documentation, and building reliable access to key intermediates can strengthen market position and reduce vulnerability to input-side shocks. Differentiation through technical service, not just product names, is increasingly essential.
For investors and strategic acquirers, attention should focus on businesses that combine distribution reach with application expertise, regulatory competence, and stable supply relationships. Transactions that improve regional execution or secure product lines with established demand can create durable value, provided they are supported by capable stewardship and compliance operations. Due diligence should weigh regulatory exposure, raw material dependencies, and the quality of customer support infrastructure alongside financial metrics.
For growers, distributors, and procurement teams, the most effective approach is to evaluate suppliers on the basis of application compatibility, compliance assurance, and technical support, rather than unit price alone. Selecting partners that can provide regionally appropriate recommendations, monitor regulatory updates, and maintain consistent product availability reduces operational risk and improves field outcomes. Staying informed about evolving application restrictions and ingredient availability is a practical necessity, not a passive concern.
As the market continues to evolve, access to detailed segment-level data, regional regulatory tracking, and company-specific capability assessments becomes a strategic asset. Decision-makers who incorporate granular market intelligence into planning are better equipped to allocate resources, prioritize partnerships, and time commercial moves with confidence. Comprehensive research and customized analysis remain valuable tools for translating broad market dynamics into actionable strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Soil Fumigant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
D-Sub Mixed Contact Connector Market: Why 6.2% CAGR and Segmentation Shifts Redefine Growth to 2032
By pmarketresearch, 2026-09-18
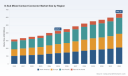
Navigating the Strategic Terrain of the Worldwide D-Sub Mixed Contact Connector Market
Market Landscape and Core Challenges
The global market for D-Sub mixed contact connectors has demonstrated steady, measurable growth throughout the 2020–2025 period, transitioning from a mature interconnect category into a more specialized solution space. Valued at approximately 315.4 million USD in 2020, the market expanded to 425.47 million USD by 2025. Forward-looking projections indicate continued expansion through the end of the decade, with a compound annual growth rate of 6.2 percent expected between 2026 and 2032. This trajectory signals that despite the prevalence of newer high-speed and miniature interconnect forms, mixed-contact D-Sub architectures remain strategically relevant for applications requiring simultaneous power delivery, signal integrity, and environmental resilience within a single envelope.
The category's resilience stems from its functional versatility. By integrating standard signal pins, high-current power contacts, coaxial terminations, and high-voltage configurations within a familiar D-Sub shell, these connectors address legacy redesign costs while meeting modern performance thresholds. However, this very versatility introduces operational complexity. Manufacturers and system integrators must navigate competing requirements around pin assignment, current-carrying capacity, impedance control, and mechanical retention, all while maintaining compatibility with established board-mount and cable-assembly workflows.
Several structural challenges currently define the market's inflection point. First, regulatory and compliance fragmentation has intensified. Mixed-layout designs frequently require adherence to multiple certification frameworks simultaneously, including ISO 9001 and AS9100 quality management expectations, MIL-DTL-24308 specifications for defense-destined variants, UL recognition for power-carrying contacts, and lead-free plating mandates for board-level and cable applications. Navigating these overlapping standards increases engineering validation timelines and raises the cost of qualification for custom configurations.
Second, material and trade policy dynamics are reshaping cost structures. Tariff measures on imported connectors and socket assemblies from China have combined with elevated duties on copper components, directly affecting raw material inputs for D-Sub mixed contact manufacturing. The intersection of trade policy volatility and commodity price sensitivity means that traditional volume-based sourcing models face renewed margin pressure, particularly for producers relying on imported copper stock or foreign-assembled cable harnesses.
Third, the market is encountering a design paradox. Engineers seek the spatial efficiency and single-cable simplification that mixed-contact D-Sub solutions offer, yet they also demand higher density, faster mating cycles, and stricter environmental sealing. Reconciling these requirements within the geometric constraints of the D-Sub footprint has become a central product development challenge, pushing suppliers to balance incremental improvements with more radical form-factor adaptations.
Worldwide Connector Backshells Market
Key Growth Drivers and Market Catalysts
The sustained expansion of the D-Sub mixed contact segment is being propelled by a convergence of technological, regulatory, demand-side, and supply chain forces. Each driver reinforces the others, creating a multi-layered growth environment that rewards suppliers capable of aligning product roadmaps with application-specific performance and compliance requirements.
Technological Innovation and Contact-Level Integration
One of the most significant catalysts has been the refinement of mixed-contact engineering. Manufacturers have progressively expanded the range of contact types that can coexist within a single D-Sub shell, enabling simultaneous routing of low-voltage signals, high-current power lines, coaxial references, and high-voltage isolation paths. This integration reduces harness complexity, minimizes connector count on PCBs, and simplifies field servicing. Advances in press-fit, surface-mount, and full-power termination technologies have further broadened deployment options, allowing mixed-layout D-Sub components to serve both legacy through-hole assemblies and modern high-density board architectures. High-reliability variants, including combo configurations with coaxial integration and non-magnetic or feed-through adaptations, illustrate how incremental contact-level innovation continues to unlock value in demanding environments.
A practical manifestation of this trajectory can be seen in recent product introductions that enhance installation efficiency without abandoning the mixed-contact principle. In May 2025, HARTING launched D-Sub PushPull housings compatible with mixed, standard, and high-density configurations, offering up to 50 percent time savings during installation and maintenance while supporting up to 36 coding variations. This was preceded by the Q1 2025 release of a PushPull locking system designed for classic D-Sub connectors, including mixed layouts, with the explicit goal of simplifying connections in industrial settings. These developments highlight a broader shift: the market is not only seeking functional mixed-contact capabilities, but also faster, more repeatable mating experiences that reduce assembly labor and field-service errors.
Policy, Compliance, and Standards as Design Enablers
Regulatory and standards-driven requirements are functioning less as barriers and more as design accelerators. Mixed-layout D-Sub connectors frequently undergo qualification against customer-specific environmental and performance expectations, with many product lines certified to ISO 9001 and AS9100 quality frameworks and MIL-DTL-24308 for defense-oriented applications. These frameworks create predictable performance baselines for aerospace, defense, and industrial buyers, reducing evaluation uncertainty and encouraging specification standardization. At the same time, compliance mandates such as UL recognition for power-carrying contacts and lead-free plating standards push manufacturers toward more disciplined material selection, plating processes, and traceability practices.
The effect is twofold. First, compliance maturity becomes a competitive differentiator, especially in sectors where qualification cycles are long and re-testing is costly. Second, standardized high-reliability families simplify cross-platform adoption, allowing system designers to reuse qualified connector families across multiple programs. In this way, regulation and certification, when managed proactively, help expand the addressable use cases for mixed-contact D-Sub components rather than constrain them.
Demand-Side Shifts Across Mission-Critical and Industrial End Use
Demand patterns are increasingly shaped by applications where power aggregation, signal fidelity, and ruggedization must coexist. Aerospace and defense programs continue to favor mixed-contact D-Sub architectures for their ability to consolidate high-reliability interconnects within weight- and space-constrained assemblies, particularly where custom pin assignments and specialized terminations are required. Industrial automation similarly benefits from mixed-contact solutions that simplify I/O consolidation on machinery, control cabinets, and fieldbus interfaces, especially when combined with sealing and mechanical robustness for harsh operating conditions. Medical electronics, meanwhile, leverages mixed-layout variants for equipment requiring integrated signal and power paths with strict reliability expectations, while telecommunications infrastructure uses combination connectors to reduce port density and cable bulk in switching, routing, and backhaul environments.
Across these sectors, the unifying theme is consolidation. Engineers are under pressure to reduce component count, simplify cable assemblies, and shorten deployment timelines without compromising performance. Mixed-contact D-Sub connectors align directly with these priorities, making them a practical choice in scenarios where redesigning around smaller or faster interconnect families would introduce disproportionate engineering, qualification, or supply risk.
Supply Chain Reconfiguration and Cost Dynamics
On the supply side, the market is navigating a more complex cost landscape. Trade policy developments have affected import costs for finished connectors and subcomponents, with duties on certain Chinese-origin connector products reaching combined levels that materially alter landed-cost calculations. At the same time, raw material pressures—most notably copper-related tariff impacts—have increased input costs for D-Sub mixed contact components and associated cable assemblies. These dynamics are prompting manufacturers to revisit supplier base strategies, evaluate regional sourcing alternatives, and refine cost pass-through models.
This environment is also accelerating a broader structural shift. Suppliers are increasingly emphasizing value-added configurations, application-specific terminations, and sealed or ruggedized variants that command stronger margins than commodity D-Sub lines. The trend favors manufacturers that can combine material cost discipline with engineering differentiation, rather than competing solely on catalog availability or unit price. In practice, this means mixed-contact D-Sub competitiveness is increasingly defined by the ability to offer predictable qualification outcomes, flexible contact mixing, and robust termination options that reduce downstream integration risk.
Competitive Dynamics and Strategic Positioning
The competitive landscape for D-Sub mixed contact connectors is characterized by a mix of broad-line interconnect leaders, high-reliability specialists, and regional manufacturing players. The market exhibits meaningful concentration, with a core group of established suppliers capturing a substantial share of mainstream and specification-driven demand. This concentration reflects the importance of qualification portfolios, engineering support, and long-term supply reliability in the D-Sub category, where buyers often prefer proven suppliers over lower-cost alternatives when performance and compliance are critical.
Amphenol maintains a broad footprint through its standard and mixed-power D-Sub offerings, spanning press-fit, SMT, full-power, and mixed-power versions with coaxial contacts for industrial, telecom, aerospace, and board/cable applications. Its portfolio includes combo-D and high-reliability variants, supported by the scale and breadth of a global interconnect platform. Within the Amphenol ecosystem, Positronic adds a focused high-reliability dimension, specializing in combo D-Sub configurations that combine signal, power, coax, high-voltage, and fiber optic contacts in both standard and high-density formats, often qualified to MIL specifications for aerospace and defense. This combination of breadth and specialization illustrates a common strategic pattern: use core manufacturing scale to anchor demand while layering on mission-critical variants to capture higher-value segments.
TE Connectivity approaches the market through its AMPLIMITE D-Subminiature line, offering mixed signal, power, and coax contacts with high-density options and MIL-DTL-24308 qualified versions. The portfolio also includes specialized non-magnetic and feed-through configurations for aerospace, defense, and industrial use, reinforcing a positioning centered on qualified performance and application adaptability. Molex complements this landscape with mixed-layout D-Sub connectors and cable assemblies that support high-current, high-voltage, pneumatic, and coaxial contacts within standard housings, addressing varied application requirements through flexible contact mixing and assembly options.
PW Consulting
A second strategic cluster is defined by ruggedization, sealing, and combo specialization. NorComp distinguishes itself with combo and mixed-contact D-Sub designs that combine signal contacts in the 5A range with power contacts rated in the 20–40A band inside the same shell, including IP67-rated versions and custom rugged I/O solutions. CONEC provides combination and mixed-layout D-Sub connectors with signal, power, and high-density options, offering IP67 sealed and crimp termination variants for automation, telecom, and industrial use. HARTING contributes a modular approach that supports nearly unlimited variants with signal, power, and other contacts for industrial PCB and harsh-environment applications, including THR and SMT mounting choices. Signal Origin focuses on waterproof IP68 D-Sub mixed contact connectors with power and coaxial combinations for industrial and harsh environments, while AUK Connector supplies mixed-contact variants through precision manufacturing for global OEM and ODM supply. Together, these players emphasize durability, sealing, and customized pin assignments as the basis for differentiation.
A third layer of competition comes from high-reliability and defense-oriented specialists. ITT Cannon extends its legacy and high-reliability interconnect portfolio into D-Sub mixed contact configurations for defense, industrial, and harsh environments. Glenair produces high-reliability D-Sub mixed contact connectors and accessories, often tailored for aerospace, defense, and severe operating conditions with custom and MIL-spec options. EDAC broadens the catalog side of the market with its D-Sub+ family, offering mixed configurations in standard and high-density formats, including stacked and dual-port options with varied termination, plating, and mounting choices. Phoenix Contact integrates D-Sub mixed contact connectors into its wider industrial connectivity portfolio, with variants suited to automation and control systems. This multi-tiered structure ensures that while a few large suppliers anchor mainstream demand, specialized manufacturers continue to capture segments where qualification, environment, and customization weigh more heavily than volume economics.
The competitive evolution is moving along three axes. First, consolidation is increasing among application-focused product lines as suppliers bundle mixed-contact options into broader industrial, defense, and telecom portfolios, reducing the number of standalone purchasing decisions for system designers. Second, differentiation is shifting from basic connector availability toward faster mating systems, sealed performance, contact-level flexibility, and qualification support. HARTING's recent PushPull initiatives illustrate this direction, using coding variation and installation speed to compete on integration efficiency rather than shell geometry alone. Third, new and regional entrants are carving out niches through sealing, pricing, and customized configurations, particularly where regional supply resilience or application-specific requirements create room to bypass established catalog routes. The result is a market that is neither purely commoditized nor fully fragmented, but increasingly segmented by performance class, qualification status, and service model.
Forward Outlook: Three Trends Shaping the Next 3–5 Years
The next several years are likely to be defined by an interplay of integration, qualification discipline, and supply chain adaptation. Three trends stand out as particularly consequential.
The first trend is the continued expansion of mixed-contact functionality within increasingly compact and service-friendly mechanical designs. As installation efficiency gains importance, suppliers will keep investing in locking mechanisms, coding variations, and termination options that reduce assembly time and field-service complexity. Mixed-contact D-Sub connectors that combine high-current, coaxial, and signal paths with faster mating and improved sealing will see growing adoption in industrial automation, mission-critical control systems, and telecom infrastructure where downtime and handling errors carry significant cost. The commercial opportunity here lies in bundling mechanical convenience with electrical performance: designs that shorten integration cycles while preserving qualification integrity can command stronger attachment rates in specification-driven projects.
The second trend is the deepening importance of compliance and reliability as purchasing criteria. With overlapping environmental, quality, and performance requirements becoming standard in aerospace, defense, medical, and industrial applications, qualification maturity will increasingly determine supplier selection. Mixed-layout designs that are pre-qualified to recognized standards and offer traceable material and plating processes will benefit from shorter approval cycles and broader cross-program reuse. For manufacturers, this creates an opportunity to move beyond connector sales toward qualification support and documentation services, helping customers navigate UL recognition, lead-free requirements, and MIL-DTL-24308 expectations with less internal burden. The associated risk is that compliance timelines can compress product launch windows if engineering and testing processes are not streamlined early in development.
The third trend is supply chain adaptation in response to material and trade pressures. Tariff-related cost increases and copper input volatility will continue to influence sourcing strategies, encouraging regionalization, dual-sourcing, and more disciplined bill-of-materials planning. This shift will likely favor suppliers that can provide stable availability, predictable pricing structures, and flexible configuration options, especially for customers seeking to reduce exposure to single-region dependency. At the same time, the risk of input cost swings and policy uncertainty means that margin management will remain a central concern, and over-reliance on commodity-grade mixed-contact lines may limit resilience. Companies that can align cost discipline with differentiated contact mixing, sealing, and qualification support will be better positioned to absorb these pressures without ceding competitive ground.
Actionable Implications for Decision-Makers
For manufacturers, the most effective path is to treat mixed-contact D-Sub strategies as application-centric rather than catalog-centric. Product roadmaps should prioritize contact-level flexibility, faster mating systems, and qualified high-reliability variants where demand is concentrated in aerospace, defense, industrial automation, and medical electronics. Aligning termination options, sealing levels, and plating compliance with the expectations of target sectors can reduce qualification friction and improve win rates in specification-driven procurements.
For investors, the opportunity lies in identifying suppliers that combine steady mainstream demand with stronger-margin specialty offerings. Portfolios that balance standard mixed-layout volumes with combo, sealed, high-voltage, or MIL-qualified variants tend to offer more resilient economics in an environment shaped by tariffs and raw material pressure. Monitoring the pace of product launches that improve installation speed and coding flexibility can also provide early signals of where competitive advantage is forming, particularly when paired with broadening qualification support and application-specific assembly solutions.
For procurement and engineering leaders, the priority is to evaluate mixed-contact D-Sub solutions against total integration cost, not unit price alone. Connector families that simplify pin assignment, reduce harness count, and streamline field servicing can lower downstream labor and maintenance burdens, while pre-qualified lines can shorten approval cycles and reduce project risk. Where possible, standardizing on mixed-contact families with documented UL recognition, lead-free compliance, and relevant quality or MIL qualifications can improve supply predictability and reduce re-validation overhead across multiple programs.
Worldwide Data XLR Connector Market
Strategic clarity in this market increasingly depends on detailed, segment-level intelligence that connects product architecture, qualification requirements, regional sourcing realities, and application demand patterns. In a category where mechanical convenience, electrical performance, and compliance maturity intersect, decision-makers benefit from a precise view of where mixed-contact D-Sub value is being created and where competitive pressure is intensifying. For a fuller breakdown of segment trajectories, regional dynamics, and supplier-level positioning, the comprehensive PW Consulting market report provides the expanded analysis and structured data needed to translate these trends into actionable planning.
For detailed analysis of this topic, please visit the official page: Worldwide D-Sub Mixed Contact Connector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global IP Outsourcing Market 2032 Outlook: How 12% CAGR Redefines Growth
By pmarketresearch, 2026-09-18
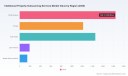
Strategic Shifts and Commercial Opportunities in the Global IP Outsourcing Services Market
The worldwide market for intellectual property outsourcing services has matured into a multi-billion-dollar ecosystem that now touches nearly every sector of the innovation economy. Over the past five years, the industry has scaled from a modest base to a valuation approaching five billion dollars, and forward projections indicate sustained expansion through the early 2030s. This trajectory reflects more than temporary demand; it signals a structural realignment in how enterprises and law firms manage patents, trademarks, and related IP workflows. As organizations seek to stretch internal resources while maintaining rigorous compliance standards, specialized external providers have become integral partners rather than auxiliary vendors. The sector’s momentum is underpinned by consistent compound annual growth, suggesting that outsourcing is transitioning from a cost-saving alternative to a strategic capability embedded in core IP operations.
Despite the favorable headline numbers, the market sits at a critical inflection point. Three interconnected challenges are reshaping how providers differentiate themselves and how buyers evaluate outsourcing relationships. First, the regulatory environment around data protection and cross-border information transfer has tightened considerably. Sensitive patent filings, unpublished invention disclosures, and portfolio administration records now require robust security frameworks, and outsourcing agreements must explicitly address IP ownership, invention assignment, and confidentiality to remain enforceable across jurisdictions. Second, the cost advantage that historically drove volume-based outsourcing is evolving. While administrative cost reductions of up to 40 percent remain achievable for U.S. firms that partner with specialized providers, organizations now demand more than efficiency; they require faster turnaround, deeper technical comprehension, and analytics that inform portfolio strategy. Providers that cannot demonstrate measurable improvements in quality, speed, or insight generation are losing competitive ground. Third, the dispute landscape has intensified significantly. WIPO administered over 1,400 IP disputes in 2025, marking a record year with demand growth of roughly 70 percent, which translates into heightened demand for specialized resolution support and more sophisticated portfolio documentation. Service providers that can integrate dispute preparedness, evidence tracking, and jurisdiction-specific know-how into their offerings are gaining a distinct edge.
A deeper look at the forces propelling this market reveals four core drivers that are reshaping demand patterns and service models.
Worldwide IT Infrastructure Outsourcing Service Market
Technology Innovation and the Emergence of AI-Enhanced Workflows
The integration of artificial intelligence and automation into intellectual property operations represents one of the most consequential shifts in the sector. Traditionally, patent drafting, prior-art searching, docketing, and renewal management relied heavily on manual review and linear processes. Today, AI-assisted tools accelerate search workflows, identify prior-art clusters with greater precision, automate docketing alerts, and streamline IDS management. Opposing counsel and corporate IP teams alike are beginning to rely on AI-enhanced platforms to reduce administrative burden while maintaining attorney oversight. Providers such as Black Hills AI exemplify this transition, delivering attorney-led outsourcing services that combine paralegal and docketing support with AI-enhanced tools. The strategic advantage is no longer limited to speed; it lies in the ability to surface insights that inform filing decisions, portfolio pruning, and competitive monitoring. Firms that embed these capabilities into their service offerings are positioning themselves as knowledge partners rather than transactional processors.
Policy and Regulatory Environment
Regulatory dynamics continue to shape both the supply and demand sides of IP outsourcing. Stricter data protection laws have elevated the importance of security architecture, encryption protocols, and compliance documentation for any provider handling sensitive patent and portfolio data. Cross-border outsourcing arrangements face additional scrutiny, as legal frameworks increasingly require clear definitions around IP ownership, assignment of inventions, and confidentiality obligations to ensure enforceability under local laws. These requirements create both friction and opportunity: they raise the barrier to entry for providers lacking mature compliance infrastructure, while rewarding established players with proven track records and standardized contractual vehicles. Additionally, WIPO administered a record number of IP disputes in 2025, reflecting a broader trend toward heightened enforcement and more complex jurisdictional interactions. As organizations navigate this environment, they are seeking outsourcing partners that can not only administer portfolios but also anticipate compliance risks and reinforce documentation standards that stand up in contested proceedings.
Demand-Side Shifts in Corporate and Law Firm Behavior
On the demand side, organizational behavior is shifting from reactive administration to proactive portfolio strategy. Global patent applications reached 3.7 million in 2024, up 4.9 percent, which has sustained demand for prosecution support, docketing, and portfolio administration. Yet the underlying driver is not volume alone; it is the increasing complexity of maintaining and monetizing IP assets across multiple jurisdictions. Enterprises are treating IP portfolios as strategic capital, and they expect outsourcing providers to contribute to decisions about where to file, when to abandon, how to defend, and how to leverage assets in partnerships or litigation. Law firms, meanwhile, face capacity constraints and are increasingly turning to external support to handle prosecution assistance, prior-art searches, and administrative workflows so their attorneys can focus on high-value advisory work. This behavioral shift creates opportunities for providers that can deliver more than transactional support; it rewards those that offer portfolio landscaping, analytics, and strategic recommendations aligned with business objectives.
Supply Chain and Cost Structure Evolution
The economics of IP outsourcing are being redefined by geographic specialization and service-model innovation. Traditional cost arbitrage remains relevant, but the value proposition has expanded to include access to specialized talent pools, multilingual prosecution expertise, and jurisdiction-specific knowledge that is difficult to replicate in-house. Providers operating from India and other specialized hubs have demonstrated the ability to deliver cost-effective patent drafting, searches, filing support, and portfolio management for international clients, while firms with strong European and North American footprints emphasize full-service lifecycle management and analytics. The supply-side evolution is also visible in partnerships that extend reach into specific markets. For example, recent strategic collaborations have strengthened capabilities in China and enhanced IP office management, enabling providers to offer more seamless cross-border administration. These developments indicate that cost remains important, but the decisive factor is the ability to combine efficiency with jurisdictional depth and workflow flexibility.
Competitive Landscape and Leading Strategies
The market features a diverse set of players spanning mature global platforms, specialized boutique firms, and technology-forward entrants. Leading organizations have carved out distinct strategic positions by emphasizing breadth of service, depth of analytics, and integration of software-enabled workflows. Providers that offer comprehensive IP management software alongside outsourcing services have gained traction because they reduce handoff friction and create unified environments for portfolio management, docketing, renewals, and analytics. This combination is particularly valuable for corporations and law firms seeking to standardize processes across multiple jurisdictions. Players focused on full-service portfolio administration, including filing coordination, renewals, and annuity payments, have positioned themselves as reliable administrators with strong cross-border capabilities. Meanwhile, firms emphasizing IP research, prior-art search, patent landscaping, and analytics support are competing on insight generation, helping clients make evidence-based decisions about filing strategies and portfolio optimization. The landscape also includes cost-competitive providers that serve international clients with practical, high-volume support, as well as attorney-led services that blend human expertise with AI-enhanced tools for docketing, paralegal support, and IDS management. The presence of multiple models reflects a market that is simultaneously consolidating around integrated platforms and fragmenting as niche specialists emerge to address specific pain points.
Market Evolution Trajectories
Three evolutionary patterns are shaping the competitive environment. First, integration is accelerating as larger platforms expand their service portfolios and pursue partnerships that broaden geographic reach and domain coverage. Strategic collaborations are increasingly used to strengthen capabilities in key markets, enhance office management services, and align offerings with client demand for seamless cross-border administration. Second, differentiation is intensifying around quality, analytics, and compliance infrastructure. Providers that can demonstrate measurable improvements in turnaround, accuracy, and strategic insight are outperforming those that compete primarily on price. Third, new entrants are gaining footholds by targeting underserved segments or regions, bringing software-enabled workflows, specialized talent, or AI-assisted tools to bear on specific tasks such as docketing, prior-art search, or prosecution support. This combination of consolidation and specialization suggests a market in which scale advantages matter, but adaptability and depth in specific verticals or geographies can also generate durable positions.
Future Trends and Their Commercial Implications
Looking ahead three to five years, several trends are likely to define the next phase of market development. The first is the deepening integration of AI and automation into core IP workflows. As AI tools mature, they will shift from augmenting discrete tasks to enabling more holistic portfolio management, predictive analytics, and automated compliance checks. This trend will favor providers that invest in robust data pipelines, domain-trained models, and attorney-in-the-loop architectures that preserve quality and accountability. The commercial opportunity lies in offering scalable, insight-rich services that reduce cycle times while improving decision quality for filing, prosecution, and defense strategies.
Intellectual Property Translation Services Market
The second trend is the continued rise of compliance-centric outsourcing. With data protection laws tightening and cross-border enforcement growing, organizations will increasingly require providers that can demonstrate rigorous security, clear contractual governance, and jurisdiction-specific expertise. Service agreements that explicitly address data handling, IP ownership, and confidentiality will become standard expectations rather than special provisions. Providers that build compliance into their operating model and transparently communicate governance standards will gain trust and win larger, longer-term engagements.
The third trend is the expanding role of analytics in portfolio strategy. As patent applications continue to grow and dispute activity intensifies, clients will demand more sophisticated landscaping, competitive monitoring, and risk assessment. Analytics-driven outsourcing will enable enterprises to identify white spaces, prune underperforming assets, and strengthen defenses in contested environments. This shift creates opportunities for providers that combine research depth with actionable reporting, enabling clients to translate IP data into business decisions. Potential risks include over-reliance on automation without adequate expert oversight, variability in jurisdiction-specific knowledge, and the possibility that cost pressure could push providers toward lower-quality models. Organizations evaluating partners should weigh these risks against the benefits of scale, speed, and strategic insight.
Strategic Recommendations for Decision-Makers
Manufacturers and R&D-intensive enterprises should view IP outsourcing as a strategic lever rather than a back-office function. Prioritize partners that offer jurisdiction-specific prosecution support, robust docketing, and analytics that inform filing decisions across markets. Evaluate providers not only on cost but on turnaround reliability, quality controls, and the ability to scale as global filing volume increases. Build contractual clarity around data handling, IP ownership, and confidentiality to protect sensitive portfolio information and ensure enforceability in cross-border contexts.
Investors assessing the sector should focus on providers that demonstrate a credible combination of technology-enabled workflows, compliance maturity, and geographic or vertical specialization. Scalable platforms with integrated software and service offerings are well positioned to capture demand as organizations seek to reduce fragmentation and standardize IP operations. Monitor signs of consolidation and partnership activity, as these often indicate where scale advantages and market access are being strengthened.
PW Consulting
Procurement teams and IP function leaders should adopt a structured evaluation framework that balances efficiency, quality, and strategic value. Define clear service-level expectations for docketing, renewals, prior-art search, and portfolio administration, and require evidence of attorney-led oversight where appropriate. Prioritize vendors that can articulate how they manage data security, cross-border compliance, and dispute readiness. As market dynamics continue to evolve, maintaining access to detailed, up-to-date segmentation data and scenario analysis will help organizations align outsourcing decisions with long-term portfolio strategy. Readers seeking deeper breakdowns by service type, industry vertical, and region, along with customized recommendations, can explore the full research report for comprehensive detail and actionable guidance.
For detailed analysis of this topic, please visit the official page: Worldwide Intellectual Property Outsourcing Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Rehabilitation Retractor Market: The 5.85% CAGR Driver Reshaping Future Growth
By pmarketresearch, 2026-09-18
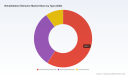
Strategic Trends and Commercial Opportunities in the Worldwide Rehabilitation Retractor Market
Market Landscape and Core Challenges
The worldwide rehabilitation retractor market, encompassing devices utilized for spinal rehabilitation treatment to relieve pain and improve function through adjustable traction force, time, and angle, is navigating a period of steady expansion. Valued at approximately USD 545.6 million in 2025, the sector is projected to grow at a compound annual growth rate of 5.85% through 2032. This growth trajectory reflects a maturing market that is transitioning from basic mechanical tools to sophisticated electronic systems capable of supporting static or intermittent modes for cervical, lumbar, or multifunctional applications in rehabilitation centers or household use.
Despite the positive revenue outlook, the industry stands at a critical juncture defined by several structural challenges. One primary hurdle is the differentiation between clinical-grade equipment and consumer-grade devices. As the definition of rehabilitation retractors broadens to include home-use solutions, manufacturers face the complexity of meeting stringent medical device classifications while competing on cost and usability in the consumer space. Devices such as powered traction units are often classified as Class II medical devices under relevant regulatory frameworks, imposing specific compliance burdens that can stifle innovation among smaller players lacking regulatory expertise.
Secondly, supply chain stability remains a concern. The precision required for calibrated traction systems means that disruptions in electronic component manufacturing or specialized material sourcing can delay product launches and inflate costs. This vulnerability is particularly acute for companies relying on complex powered mechanisms rather than simple manual designs.
Finally, market concentration indicates a moderately consolidated environment, where a handful of established players hold significant sway. With the top three companies accounting for a notable share of revenue, new entrants must offer compelling technological advantages or niche specializations to gain traction. This concentration creates a barrier to entry but also signals stability for investors looking at the incumbent leaders. The challenge lies in balancing the need for regulatory compliance and supply chain resilience with the demand for affordable, accessible rehabilitation solutions.
Key Drivers of Market Change
Several interconnected factors are propelling the rehabilitation retractor market forward, reshaping how products are developed, regulated, and adopted.
Technological Innovation and Automation
The shift from manual to powered traction units represents the most significant technological driver. Modern devices are increasingly incorporating automatic calibration and multiple traction modes, including intermittent, static, and progressive settings. This technological leap allows for more precise treatment protocols tailored to individual patient needs. For instance, advanced units now feature safety controls that monitor traction force and angle in real-time, reducing the risk of injury during spinal rehabilitation. This move towards automation not only improves clinical outcomes but also enhances the value proposition for home-care settings, where professional supervision may be limited. The integration of digital interfaces and data logging capabilities is further enabling clinicians to track patient progress remotely, aligning with the broader trend of digital health integration.
Worldwide Urethral Dilator Market
Regulatory Frameworks and Safety Standards
The regulatory environment is tightening, particularly regarding the classification of traction devices. As noted in recent policy discussions, certain powered traction units are classified as Class II medical devices. This classification necessitates rigorous testing for safety and efficacy before market entry. While this adds a layer of complexity for manufacturers, it also serves as a quality filter that benefits established companies with robust compliance infrastructures. Regulatory clarity helps standardize treatment protocols and builds trust among healthcare providers and patients. Consequently, companies that proactively invest in regulatory affairs and quality assurance are better positioned to secure approvals and expand their market reach across different regions with varying compliance requirements.
Demand-Side Shifts Towards Non-Invasive Care
There is a growing preference among patients and healthcare providers for non-invasive rehabilitation treatments over surgical interventions where possible. Spinal issues related to aging, sedentary lifestyles, and sports injuries are driving demand for conservative management techniques. Rehabilitation retractors offer a non-surgical option to relieve pain and improve function, making them an attractive component of comprehensive rehabilitation product lines for musculoskeletal and spinal treatment. Furthermore, the aging global population is increasing the prevalence of degenerative spinal conditions, directly expanding the addressable market. Patients are seeking solutions that allow for faster recovery times and reduced hospital stays, fueling demand for devices that can be used in outpatient clinics or at home.
Supply Chain and Cost Structure Evolution
Cost structures are evolving as manufacturers seek to balance performance with affordability. The demand for household-use devices is pushing companies to design cost-effective models without compromising essential safety features. Simultaneously, supply chain localization efforts are gaining traction to mitigate risks associated with global logistics disruptions. Companies that can optimize their manufacturing processes to reduce dependencies on single-source components while maintaining high precision in traction force adjustment will gain a competitive edge. This dynamic is encouraging innovation in material science and manufacturing techniques that lower production costs while enhancing durability and reliability.
Competitive Landscape and Leading Strategies
The competitive environment in the rehabilitation retractor market is characterized by a mix of large multinational corporations and specialized regional manufacturers. The market is moderately consolidated, with leading players leveraging diverse product portfolios and technological expertise to maintain their positions.
Rehabilitation Robotics Market
Major western companies often dominate through comprehensive rehabilitation product lines. For example, Chattanooga (Enovis), based in the United States, offers traction and decompression equipment as part of its extensive rehabilitation product line for musculoskeletal and spinal treatment, including Saunders Cervical Traction systems. Their strategy relies on brand recognition and integration within broader clinical ecosystems. Similarly, Mettler Electronics, also based in the United States, is known for electrotherapy and traction devices used in physical rehabilitation, leveraging decades of experience in physical therapy equipment to maintain market relevance.
In contrast, Japanese manufacturers are focusing on precision engineering and advanced feature sets. ITO Co., Ltd. develops powered traction units like the TM-400 with automatic calibration and multiple traction modes for cervical and lumbar rehabilitation. Their emphasis on technical sophistication appeals to clinical settings requiring high precision. OG Wellness Technologies Co., Ltd. also manufactures physiotherapy traction equipment, including ORTHO TRAC cervical traction units with multi-step traction modes, catering to the specific needs of rehabilitation treatment in structured clinical environments. MINATO Medical Science supplies rehabilitation equipment including traction systems, further strengthening the presence of Japanese engineering in this sector.
Emerging players and regional specialists are carving out niches through targeted solutions. V2U Healthcare, with a regional focus in Malaysia and the Philippines, provides traction decompression systems such as V2U TRAC TDM and TRAC PRO for cervical and lumbar spinal rehabilitation. These devices feature static, intermittent, and cyclic modes with safety controls, addressing specific regional needs and price points. Enraf-Nonius, based in the Netherlands, supplies the Eltrac 471 traction therapy device designed for precise lumbar and cervical traction with continuous and intermittent protocols in physiotherapy settings, emphasizing clinical efficacy.
European manufacturers like Elettronica Pagani and Fisiotech, based in Italy, remain active in the rehabilitation retracter and traction equipment market, often focusing on specific physiotherapy applications. Meanwhile, companies like Huntex Corporation in Taiwan manufacture rehabilitation traction and retractor devices, contributing to the global supply diversity. Other entities such as Bilt-Rite Mastex Health and EVERYWAY MEDICAL offer products in the household and clinical rehabilitation retracter segment, indicating a trend towards diversifying end-use applications. Meditrac and SIRIUSMED also provide rehabilitation retracter and traction solutions, adding to the breadth of available options.
The market landscape is evolving through a combination of consolidation and specialization. Larger entities may seek to acquire smaller innovators to integrate advanced technologies like automatic calibration or digital connectivity into their portfolios. Simultaneously, new entrants are likely to emerge from regions with growing healthcare infrastructure, offering cost-effective alternatives. Strategic differentiation will increasingly depend on the ability to offer versatile devices that can switch between static and intermittent modes, ensuring safety controls are robust, and providing support for both clinical and home use cases. Companies that fail to adapt to the demand for multifunctional rehabilitation retractors risk losing share to more agile competitors.
PW Consulting
Future Trends and Predictions
Looking ahead to the next three to five years, the rehabilitation retractor market is expected to evolve along several key trajectories that will define commercial opportunities.
First, the convergence of rehabilitation retractors with broader digital health ecosystems will accelerate. Devices will not merely apply traction but will likely incorporate data analytics to monitor patient compliance and treatment efficacy. This shift creates opportunities for manufacturers to offer subscription-based services or software-linked hardware that adds ongoing value beyond the initial sale. The ability to remotely adjust parameters or receive alerts on device usage could become a standard expectation for clinical buyers.
Second, the market for home-based rehabilitation devices is poised for significant growth. As healthcare systems seek to reduce costs and hospital burden, there will be increased support for devices that patients can use safely at home under remote supervision. This trend favors companies that can design intuitive, user-friendly interfaces and ensure devices meet safety standards for non-professional operation. The segmentation between clinical and household use may blur further, with high-end home devices approaching clinical capabilities.
Third, regional dynamics will shift as healthcare infrastructure develops in emerging markets. Areas previously underserved by advanced rehabilitation technology may see increased adoption due to rising healthcare expenditure and awareness. However, this expansion comes with risks. Regulatory divergence between regions could complicate global product launches. Additionally, economic volatility may impact procurement budgets in public healthcare systems, potentially slowing growth in certain segments. Manufacturers must remain agile, adapting their product offerings and pricing strategies to local economic conditions while maintaining quality standards. The potential for supply chain disruptions remains a constant threat, requiring robust contingency planning.
Strategic Recommendations for Decision Makers
For manufacturers, the priority should be investing in R&D that enhances usability and connectivity without escalating costs disproportionately. Focusing on automatic calibration and safety controls can differentiate products in a crowded market. Exploring partnerships for digital integration could unlock new revenue models and strengthen customer loyalty.
Investors should look for companies with strong regulatory compliance records and diversified product portfolios that span both clinical and home-care segments. Firms that demonstrate resilience in supply chain management and have a clear strategy for emerging markets may offer better risk-adjusted returns. Evaluating the technological moat of potential targets, specifically regarding proprietary traction modes or calibration technology, is essential.
Procurement teams and healthcare providers should evaluate devices based on total cost of ownership and clinical outcomes rather than just initial purchase price. Selecting equipment that supports multiple traction modes and offers reliable safety features can reduce long-term operational risks. Keeping abreast of changing regulatory classifications is crucial to ensure continued compliance and avoid disruptions in service delivery. Engaging with suppliers who provide comprehensive training and support for both clinical and home-use scenarios will maximize the utility of the equipment.
For stakeholders seeking detailed segmentation data and customized strategic advice, accessing comprehensive market intelligence reports provides a clearer picture of regional nuances and competitive moves. Deep-dive analyses can reveal specific growth pockets and potential partnership opportunities that are not visible at the aggregate level.
For detailed analysis of this topic, please visit the official page: Worldwide Rehabilitation Retractor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Industrial Press Machine Market: Strategic Shifts Beyond 5.18% CAGR to 2032
By pmarketresearch, 2026-09-18
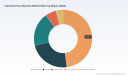
Global Industrial Press Machine Market: Strategic Trends and Commercial Opportunities Through 2032
Market Snapshot and Core Challenges
The worldwide industrial press machine sector has demonstrated resilient expansion, with total market revenue projected to reach approximately USD 15,256 million in 2025. The landscape reflects a steady upward trajectory, driven by sustained demand across metal forming, stamping, and forging operations. Historical growth from 2020 through 2025 reveals a market that has consistently navigated cyclical pressures while maintaining structural momentum, positioning the sector at roughly USD 15.3 billion as the current baseline. Looking ahead, the forecast period from 2026 to 2032 points toward continued expansion, with compound annual growth expected at 5.18 percent, ultimately reaching an estimated USD 21,726 million by 2032. This growth trajectory underscores the enduring role of industrial presses as foundational equipment in manufacturing ecosystems, while also signaling shifting demand patterns that will reshape competitive priorities.
Several structural challenges and inflection points define the current market environment. First, raw material cost volatility continues to pressure margins and pricing strategies. Steel inputs, which form the backbone of press frames and critical components, have experienced significant fluctuations. U.S. steel prices stabilized in the low-to-mid $800s per short ton during mid-2025, with the Bureau of Labor Statistics Steel Mill Products Producer Price Index recorded at 308.1 in July 2025. This stabilization offers temporary relief, but the global steel market faces structural overcapacity and weak demand from China, with subdued price recovery projected through 2026 and only a modest upturn anticipated from 2027 onward. Manufacturers must therefore navigate a prolonged period of cost uncertainty that directly impacts equipment pricing and project profitability.
Second, trade policy shifts are reshaping supply chain dynamics and regional competitiveness. The increase of U.S. Section 232 steel tariffs to 50 percent, effective June 2025 with certain exceptions, supports domestic steel producers supplying industrial press manufacturers while simultaneously raising input costs for importers. This policy environment creates a bifurcated market where regional sourcing strategies and localized production capabilities become decisive competitive advantages. Companies reliant on imported components face margin compression, while those with established domestic supply chains can leverage tariff structures to strengthen their positioning.
Third, the industry stands at a technological inflection point where traditional mechanical and hydraulic platforms increasingly compete with digitally integrated servo-electric solutions. The transition is not merely a product substitution dynamic but a fundamental shift in how press operations are designed, monitored, and optimized. Enterprises that fail to adapt their product portfolios and service models to accommodate automation-ready, energy-efficient configurations risk ceding share to competitors offering integrated Industry 4.0 capabilities.
Key Demand Drivers Shaping the Market
Technology Innovation and the Servo-Electric Transition
The most transformative driver in the industrial press machine market is the accelerating adoption of servo press technology alongside continued advancements in hydraulic and mechanical platforms. Servo presses offer programmable stroke profiles, higher precision, reduced energy consumption, and seamless integration with advanced manufacturing execution systems. These attributes align directly with the broader manufacturing emphasis on flexibility, repeatability, and data-driven process control. As production environments increasingly demand shorter changeover times and tighter tolerance requirements, the value proposition of servo-driven equipment strengthens considerably.
Industry context confirms that ongoing automation and servo press adoption is being driven by needs for higher precision, energy efficiency, and integration with Industry 4.0 systems in metal forming operations. This push is visible across company product portfolios and industry association overviews throughout 2025, reflecting a consensus that the next generation of press equipment must function as connected assets rather than standalone machines. The implications extend beyond hardware specifications. Manufacturers are investing in control architecture, sensor integration, and predictive maintenance capabilities that enable real-time optimization of force, speed, and dwell time. These features reduce waste, improve throughput, and support the transition toward high-mix, low-volume production models that characterize advanced manufacturing facilities.
Policy and Regulatory Dynamics Reshaping Sourcing Strategies
Regulatory and trade policy developments are exerting a direct influence on market structure and competitive positioning. The escalation of U.S. Section 232 steel tariffs to 50 percent, effective June 2025 with specific exceptions, fundamentally alters the economics of imported steel components used in press manufacturing. Domestic steel producers benefit from enhanced protection, while importers face elevated input costs that cascade through equipment pricing. This dynamic encourages regionalization of supply chains and incentivizes press manufacturers to secure long-term agreements with domestic material suppliers or to redesign components to reduce steel intensity without compromising structural performance.
Trade policy is not operating in isolation. The broader regulatory environment increasingly emphasizes energy efficiency, emissions reduction, and operational transparency. Press manufacturers that proactively align their equipment designs with these expectations position themselves favorably for public procurement, regulated industry applications, and customers pursuing sustainability mandates. The intersection of trade protectionism and environmental compliance creates a complex but navigable landscape for firms that integrate policy intelligence into product development and sourcing decisions.
Demand-Side Shifts Across End-Use Industries
Demand patterns across application verticals continue to evolve in ways that reshape equipment specifications and volume expectations. Automotive manufacturing remains a central demand driver, supported by ongoing stamping and forming requirements for vehicle bodies, structural components, and electrification-related parts. General machinery applications sustain steady demand, while aerospace and defense sectors contribute higher-specification orders that emphasize precision and material performance. Electronics and electrical manufacturing adds incremental demand tied to precision forming and specialized component production.
These demand-side dynamics are not static. Automotive production volumes fluctuate with model cycles and regional assembly footprints, requiring press suppliers to offer scalable solutions that can accommodate both high-volume lines and flexible multi-part operations. Aerospace and defense applications pull demand toward higher-tolerance, higher-reliability equipment with extended validation and certification requirements. Meanwhile, electronics and electrical end-use segments increasingly favor compact, precision-controlled presses that integrate cleanly into automated assembly environments. The net effect is a more diversified demand profile that rewards manufacturers with broad application expertise and the ability to tailor equipment configurations to specific operational constraints.
Hydraulic Press Market
Supply Chain and Cost Structure Evolution
Supply chain considerations have moved from operational concern to strategic priority. The combination of steel price volatility, tariff adjustments, and prolonged weak demand from China has introduced significant uncertainty into input cost forecasting. Structural overcapacity in the global steel market is expected to keep price recovery subdued through 2026, with only a modest upturn projected from 2027. This timeline suggests that press manufacturers must plan for an extended period of cost moderation rather than anticipating a rapid rebound that would simplify procurement strategies.
Cost structures are also being influenced by the growing emphasis on automation integration and digital service offerings. While these capabilities command premium positioning, they also require investment in engineering talent, software development, and after-sales support infrastructure. Companies that balance hardware profitability with recurring service revenue streams gain a more resilient financial profile. The shift toward integrated solutions, where presses are delivered alongside tooling, automation cells, and monitoring systems, elevates the strategic importance of partnerships and vertical integration.
Competitive Landscape and Leading Strategies
Regional Anchors and Product Differentiation
The competitive environment features a mix of established multinational manufacturers and specialized regional players, each pursuing distinct strategic positioning. Schuler Group, headquartered in Göppingen, Germany, offers a comprehensive range of mechanical, hydraulic, and servo presses for metal forming, stamping, and forging across automotive, appliance, and industrial applications worldwide. Its broad portfolio and global footprint enable it to serve large-scale tier-one customers with integrated line solutions and aftermarket support. AIDA Engineering, based in Japan, specializes in high-precision mechanical and servo presses for high-speed stamping and progressive die operations in the automotive and electronics sectors, emphasizing precision and throughput for fast-cycle production environments.
Amada, also based in Japan, provides turret punch presses, press brakes, and related sheet metal forming equipment with a focus on precision and automation for industrial manufacturing. Its product breadth and strong automation integration capabilities position it well for customers seeking compact, flexible forming solutions. Komatsu Press, another Japanese manufacturer, produces mechanical and hydraulic presses for metal stamping, forging, and heavy industrial applications, integrated with automation solutions that extend its value proposition beyond the press itself. In North America, Beckwood Press Company in St. Louis, Missouri, custom-engineers hydraulic and servo-electric presses for compression molding, forming, and specialized industrial processes, appealing to customers with unique application requirements that benefit from tailored engineering.
Additional players strengthen the competitive mosaic. Pacific Press Technologies, based in the USA, builds hydraulic presses, C-frame, straight-side, and press brakes for metal forming and fabrication in North America, reinforcing regional service and support capabilities. Macrodyne Press, operating across Canada and North America, designs and manufactures custom heavy-duty hydraulic presses for forging, deep draw, hydroforming, and large-scale industrial applications, targeting high-force requirements and specialized forming challenges. French Oil Mill Machinery Co., operating out of Ohio, USA, has delivered custom hydraulic presses since 1900 for compression molding, rubber, and various industrial pressing operations, leveraging long-standing expertise in niche compression applications. Ermaksan, based in Turkey, produces CNC hydraulic and servo turret punch presses along with press brakes for sheet metal fabrication, expanding its presence in cost-competitive European and Middle Eastern markets.
Fagor Arrasate, headquartered in Spain, supplies mechanical and hydraulic presses, stamping lines, and turnkey solutions for automotive and appliance manufacturing, differentiating through integrated line delivery. In the United States, Sutherland Presses operates as a family-owned manufacturer of mechanical and hydraulic presses for precision metal stamping and forming, while Stamtec offers mechanical, servo, and forging presses manufactured in the US for high-volume stamping operations. These firms reflect a enduring pattern in the market: large multinational platforms compete on global scale, integrated solutions, and broad application coverage, while regional and specialized manufacturers compete on customization, responsiveness, and deep domain expertise.
Strategic Positioning and Divergence in Competitive Approaches
Leading companies are pursuing differentiation through several overlapping strategies. One prominent approach centers on servo-electric and hybrid press development that reduces energy consumption, improves control precision, and enables integration with digital manufacturing ecosystems. This trajectory aligns with end-user demands for efficiency and flexibility, while also supporting compliance with tightening energy and emissions expectations. A second strategy emphasizes turnkey and integrated line delivery, where presses are supplied alongside automation, tooling, and process control systems. This model deepens customer relationships, increases switching costs, and creates recurring revenue opportunities through service and upgrades.
A third strategic thread involves regional localization to mitigate trade policy risk and improve responsiveness. Manufacturers with established production and service networks in key markets can offer shorter lead times, faster troubleshooting, and greater assurance around input sourcing, which is particularly valuable amid tariff volatility and steel price uncertainty. A fourth approach leverages long-standing reputation and niche application expertise to defend and expand in specialized segments such as compression molding, rubber processing, hydroforming, and high-force forging. These segments often exhibit lower price sensitivity and higher emphasis on proven reliability, creating defensible positioning for experienced manufacturers.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The market structure reflects moderate concentration, with the top three firms accounting for approximately 22.45 percent of revenue and the top five capturing around 34.8 percent. This concentration level suggests a competitive landscape that is neither dominated by a few global players nor highly fragmented. Instead, it supports a dynamic environment where scale advantages coexist with room for specialized and regional operators to thrive. Over the forecast horizon, several evolution patterns are likely to shape the landscape.
Consolidation may accelerate in segments where integrated line delivery, digital service platforms, and global service networks create scale benefits that smaller standalone players struggle to match. Conversely, fragmentation pressures may persist in customized, low-to-medium volume applications where flexibility, engineering responsiveness, and domain-specific knowledge outweigh pure scale considerations. New entrants and expanding regional manufacturers are likely to pursue targeted positioning, focusing on specific geographies, application verticals, or technology niches such as servo-electric conversion, compact precision presses, or specialized forming solutions. Recent industry activity reinforces the importance of visibility and direct customer engagement. For example, in January 2026, Isgec Heavy Engineering's Machine Building Division participated in the International Machine Tool and Manufacturing Technology Exhibition, showcasing metal forming presses and related equipment. Such trade show participation highlights how manufacturers use direct market presence to reinforce product visibility, gather customer feedback, and sustain pipeline development in a competitive environment.
Press Machine Market
Future Outlook: Trends and Commercial Opportunities
Over the next three to five years, the industrial press machine market is expected to be shaped by three interconnected trends. First, servo-electric and hybrid press adoption will continue to expand as manufacturers prioritize precision, energy efficiency, and digital integration. This trend creates opportunities for equipment suppliers that can offer seamless control architecture, sensor-based monitoring, and compatibility with manufacturing execution and analytics platforms. Companies that package presses as connected, 업그레이드able assets will be positioned to capture share in applications where throughput optimization and data transparency are critical.
PW Consulting
Second, regionalization of supply chains will intensify as trade policy, input cost volatility, and service responsiveness considerations push manufacturers toward localized sourcing and production. This dynamic favors firms with established regional manufacturing footprints, domestic material partnerships, and localized service networks. The commercial opportunity lies in designing cost-competitive equipment that leverages regional inputs while maintaining performance standards, and in building service infrastructures that reduce downtime and strengthen customer retention.
Third, application-specific specialization will remain a durable growth path, particularly in sectors such as aerospace and defense, electronics and electrical manufacturing, and niche compression or forming processes. These segments reward engineering depth, validation capability, and the ability to meet stringent performance and compliance requirements. Suppliers that develop focused application expertise and tailored solutions can command premium positioning and build long-term customer relationships that are less susceptible to price-based competition.
Potential risks and uncertainties warrant attention. Steel price trajectories remain uncertain, with structural overcapacity and weak Chinese demand expected to suppress recovery through 2026 and produce only a modest upturn from 2027. Tariff structures could shift, altering relative cost advantages between domestic and imported inputs. Demand cycles in automotive and broader industrial production may introduce volume volatility, especially where model changes, electrification transitions, or regional assembly reallocations influence stamping and forming requirements. Finally, the pace of servo-electric adoption and digital integration may vary across regions and end-use segments, creating uneven growth patterns that require flexible commercial strategies.
Strategic Recommendations for Decision-Makers
For manufacturers and equipment suppliers, the priority is to align product portfolios with the dual imperatives of precision automation and regional supply chain resilience. Investing in servo-electric and hybrid capabilities, strengthening digital integration features, and securing reliable domestic or regional material sources will support competitive positioning amid tariff volatility and steel cost uncertainty. Equally important is expanding service and upgrade offerings that create recurring revenue and deepen customer relationships, particularly where presses are deployed in high-utilization, precision-critical environments.
For investors, the market presents selective opportunities in companies that combine technology differentiation with verified regional manufacturing and service capabilities. Evaluating exposure to servo-electric transition trends, application specialization in higher-margin segments such as aerospace and defense or electronics and electrical forming, and the ability to manage input cost risk through sourcing strategies can help identify resilient investment targets. Monitoring trade policy developments and steel market dynamics will also be essential for anticipating margin trajectories and competitive shifts.
For procurement and operations leaders, the focus should be on total cost of ownership, integration readiness, and supplier stability. Evaluating press options through the lens of energy efficiency, automation compatibility, service responsiveness, and long-term parts availability can reduce operational risk and support production flexibility. Engaging suppliers with demonstrated regional presence and the ability to deliver tailored solutions for specific forming or stamping requirements will help balance performance objectives with cost and supply assurance.
Detailed segmentation data, company-level revenue estimates, regional demand profiles, and customized strategic scenarios can support more granular planning. Exploring the full research report provides access to deeper breakdowns across type, application, and region, along with tailored guidance for specific business contexts and investment theses.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Press Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com