

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Industrial Press Machine Market: Strategic Shifts Beyond 5.18% CAGR to 2032

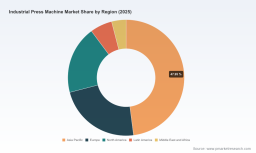
Global Industrial Press Machine Market: Strategic Trends and Commercial Opportunities Through 2032
Market Snapshot and Core Challenges
The worldwide industrial press machine sector has demonstrated resilient expansion, with total market revenue projected to reach approximately USD 15,256 million in 2025. The landscape reflects a steady upward trajectory, driven by sustained demand across metal forming, stamping, and forging operations. Historical growth from 2020 through 2025 reveals a market that has consistently navigated cyclical pressures while maintaining structural momentum, positioning the sector at roughly USD 15.3 billion as the current baseline. Looking ahead, the forecast period from 2026 to 2032 points toward continued expansion, with compound annual growth expected at 5.18 percent, ultimately reaching an estimated USD 21,726 million by 2032. This growth trajectory underscores the enduring role of industrial presses as foundational equipment in manufacturing ecosystems, while also signaling shifting demand patterns that will reshape competitive priorities.
Several structural challenges and inflection points define the current market environment. First, raw material cost volatility continues to pressure margins and pricing strategies. Steel inputs, which form the backbone of press frames and critical components, have experienced significant fluctuations. U.S. steel prices stabilized in the low-to-mid $800s per short ton during mid-2025, with the Bureau of Labor Statistics Steel Mill Products Producer Price Index recorded at 308.1 in July 2025. This stabilization offers temporary relief, but the global steel market faces structural overcapacity and weak demand from China, with subdued price recovery projected through 2026 and only a modest upturn anticipated from 2027 onward. Manufacturers must therefore navigate a prolonged period of cost uncertainty that directly impacts equipment pricing and project profitability.
Second, trade policy shifts are reshaping supply chain dynamics and regional competitiveness. The increase of U.S. Section 232 steel tariffs to 50 percent, effective June 2025 with certain exceptions, supports domestic steel producers supplying industrial press manufacturers while simultaneously raising input costs for importers. This policy environment creates a bifurcated market where regional sourcing strategies and localized production capabilities become decisive competitive advantages. Companies reliant on imported components face margin compression, while those with established domestic supply chains can leverage tariff structures to strengthen their positioning.
Third, the industry stands at a technological inflection point where traditional mechanical and hydraulic platforms increasingly compete with digitally integrated servo-electric solutions. The transition is not merely a product substitution dynamic but a fundamental shift in how press operations are designed, monitored, and optimized. Enterprises that fail to adapt their product portfolios and service models to accommodate automation-ready, energy-efficient configurations risk ceding share to competitors offering integrated Industry 4.0 capabilities.
Key Demand Drivers Shaping the Market
Technology Innovation and the Servo-Electric Transition
The most transformative driver in the industrial press machine market is the accelerating adoption of servo press technology alongside continued advancements in hydraulic and mechanical platforms. Servo presses offer programmable stroke profiles, higher precision, reduced energy consumption, and seamless integration with advanced manufacturing execution systems. These attributes align directly with the broader manufacturing emphasis on flexibility, repeatability, and data-driven process control. As production environments increasingly demand shorter changeover times and tighter tolerance requirements, the value proposition of servo-driven equipment strengthens considerably.
Industry context confirms that ongoing automation and servo press adoption is being driven by needs for higher precision, energy efficiency, and integration with Industry 4.0 systems in metal forming operations. This push is visible across company product portfolios and industry association overviews throughout 2025, reflecting a consensus that the next generation of press equipment must function as connected assets rather than standalone machines. The implications extend beyond hardware specifications. Manufacturers are investing in control architecture, sensor integration, and predictive maintenance capabilities that enable real-time optimization of force, speed, and dwell time. These features reduce waste, improve throughput, and support the transition toward high-mix, low-volume production models that characterize advanced manufacturing facilities.
Policy and Regulatory Dynamics Reshaping Sourcing Strategies
Regulatory and trade policy developments are exerting a direct influence on market structure and competitive positioning. The escalation of U.S. Section 232 steel tariffs to 50 percent, effective June 2025 with specific exceptions, fundamentally alters the economics of imported steel components used in press manufacturing. Domestic steel producers benefit from enhanced protection, while importers face elevated input costs that cascade through equipment pricing. This dynamic encourages regionalization of supply chains and incentivizes press manufacturers to secure long-term agreements with domestic material suppliers or to redesign components to reduce steel intensity without compromising structural performance.
Trade policy is not operating in isolation. The broader regulatory environment increasingly emphasizes energy efficiency, emissions reduction, and operational transparency. Press manufacturers that proactively align their equipment designs with these expectations position themselves favorably for public procurement, regulated industry applications, and customers pursuing sustainability mandates. The intersection of trade protectionism and environmental compliance creates a complex but navigable landscape for firms that integrate policy intelligence into product development and sourcing decisions.
Demand-Side Shifts Across End-Use Industries
Demand patterns across application verticals continue to evolve in ways that reshape equipment specifications and volume expectations. Automotive manufacturing remains a central demand driver, supported by ongoing stamping and forming requirements for vehicle bodies, structural components, and electrification-related parts. General machinery applications sustain steady demand, while aerospace and defense sectors contribute higher-specification orders that emphasize precision and material performance. Electronics and electrical manufacturing adds incremental demand tied to precision forming and specialized component production.
These demand-side dynamics are not static. Automotive production volumes fluctuate with model cycles and regional assembly footprints, requiring press suppliers to offer scalable solutions that can accommodate both high-volume lines and flexible multi-part operations. Aerospace and defense applications pull demand toward higher-tolerance, higher-reliability equipment with extended validation and certification requirements. Meanwhile, electronics and electrical end-use segments increasingly favor compact, precision-controlled presses that integrate cleanly into automated assembly environments. The net effect is a more diversified demand profile that rewards manufacturers with broad application expertise and the ability to tailor equipment configurations to specific operational constraints.
Hydraulic Press Market
Supply Chain and Cost Structure Evolution
Supply chain considerations have moved from operational concern to strategic priority. The combination of steel price volatility, tariff adjustments, and prolonged weak demand from China has introduced significant uncertainty into input cost forecasting. Structural overcapacity in the global steel market is expected to keep price recovery subdued through 2026, with only a modest upturn projected from 2027. This timeline suggests that press manufacturers must plan for an extended period of cost moderation rather than anticipating a rapid rebound that would simplify procurement strategies.
Cost structures are also being influenced by the growing emphasis on automation integration and digital service offerings. While these capabilities command premium positioning, they also require investment in engineering talent, software development, and after-sales support infrastructure. Companies that balance hardware profitability with recurring service revenue streams gain a more resilient financial profile. The shift toward integrated solutions, where presses are delivered alongside tooling, automation cells, and monitoring systems, elevates the strategic importance of partnerships and vertical integration.
Competitive Landscape and Leading Strategies
Regional Anchors and Product Differentiation
The competitive environment features a mix of established multinational manufacturers and specialized regional players, each pursuing distinct strategic positioning. Schuler Group, headquartered in Göppingen, Germany, offers a comprehensive range of mechanical, hydraulic, and servo presses for metal forming, stamping, and forging across automotive, appliance, and industrial applications worldwide. Its broad portfolio and global footprint enable it to serve large-scale tier-one customers with integrated line solutions and aftermarket support. AIDA Engineering, based in Japan, specializes in high-precision mechanical and servo presses for high-speed stamping and progressive die operations in the automotive and electronics sectors, emphasizing precision and throughput for fast-cycle production environments.
Amada, also based in Japan, provides turret punch presses, press brakes, and related sheet metal forming equipment with a focus on precision and automation for industrial manufacturing. Its product breadth and strong automation integration capabilities position it well for customers seeking compact, flexible forming solutions. Komatsu Press, another Japanese manufacturer, produces mechanical and hydraulic presses for metal stamping, forging, and heavy industrial applications, integrated with automation solutions that extend its value proposition beyond the press itself. In North America, Beckwood Press Company in St. Louis, Missouri, custom-engineers hydraulic and servo-electric presses for compression molding, forming, and specialized industrial processes, appealing to customers with unique application requirements that benefit from tailored engineering.
Additional players strengthen the competitive mosaic. Pacific Press Technologies, based in the USA, builds hydraulic presses, C-frame, straight-side, and press brakes for metal forming and fabrication in North America, reinforcing regional service and support capabilities. Macrodyne Press, operating across Canada and North America, designs and manufactures custom heavy-duty hydraulic presses for forging, deep draw, hydroforming, and large-scale industrial applications, targeting high-force requirements and specialized forming challenges. French Oil Mill Machinery Co., operating out of Ohio, USA, has delivered custom hydraulic presses since 1900 for compression molding, rubber, and various industrial pressing operations, leveraging long-standing expertise in niche compression applications. Ermaksan, based in Turkey, produces CNC hydraulic and servo turret punch presses along with press brakes for sheet metal fabrication, expanding its presence in cost-competitive European and Middle Eastern markets.
Fagor Arrasate, headquartered in Spain, supplies mechanical and hydraulic presses, stamping lines, and turnkey solutions for automotive and appliance manufacturing, differentiating through integrated line delivery. In the United States, Sutherland Presses operates as a family-owned manufacturer of mechanical and hydraulic presses for precision metal stamping and forming, while Stamtec offers mechanical, servo, and forging presses manufactured in the US for high-volume stamping operations. These firms reflect a enduring pattern in the market: large multinational platforms compete on global scale, integrated solutions, and broad application coverage, while regional and specialized manufacturers compete on customization, responsiveness, and deep domain expertise.
Strategic Positioning and Divergence in Competitive Approaches
Leading companies are pursuing differentiation through several overlapping strategies. One prominent approach centers on servo-electric and hybrid press development that reduces energy consumption, improves control precision, and enables integration with digital manufacturing ecosystems. This trajectory aligns with end-user demands for efficiency and flexibility, while also supporting compliance with tightening energy and emissions expectations. A second strategy emphasizes turnkey and integrated line delivery, where presses are supplied alongside automation, tooling, and process control systems. This model deepens customer relationships, increases switching costs, and creates recurring revenue opportunities through service and upgrades.
A third strategic thread involves regional localization to mitigate trade policy risk and improve responsiveness. Manufacturers with established production and service networks in key markets can offer shorter lead times, faster troubleshooting, and greater assurance around input sourcing, which is particularly valuable amid tariff volatility and steel price uncertainty. A fourth approach leverages long-standing reputation and niche application expertise to defend and expand in specialized segments such as compression molding, rubber processing, hydroforming, and high-force forging. These segments often exhibit lower price sensitivity and higher emphasis on proven reliability, creating defensible positioning for experienced manufacturers.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The market structure reflects moderate concentration, with the top three firms accounting for approximately 22.45 percent of revenue and the top five capturing around 34.8 percent. This concentration level suggests a competitive landscape that is neither dominated by a few global players nor highly fragmented. Instead, it supports a dynamic environment where scale advantages coexist with room for specialized and regional operators to thrive. Over the forecast horizon, several evolution patterns are likely to shape the landscape.
Consolidation may accelerate in segments where integrated line delivery, digital service platforms, and global service networks create scale benefits that smaller standalone players struggle to match. Conversely, fragmentation pressures may persist in customized, low-to-medium volume applications where flexibility, engineering responsiveness, and domain-specific knowledge outweigh pure scale considerations. New entrants and expanding regional manufacturers are likely to pursue targeted positioning, focusing on specific geographies, application verticals, or technology niches such as servo-electric conversion, compact precision presses, or specialized forming solutions. Recent industry activity reinforces the importance of visibility and direct customer engagement. For example, in January 2026, Isgec Heavy Engineering's Machine Building Division participated in the International Machine Tool and Manufacturing Technology Exhibition, showcasing metal forming presses and related equipment. Such trade show participation highlights how manufacturers use direct market presence to reinforce product visibility, gather customer feedback, and sustain pipeline development in a competitive environment.
Press Machine Market
Future Outlook: Trends and Commercial Opportunities
Over the next three to five years, the industrial press machine market is expected to be shaped by three interconnected trends. First, servo-electric and hybrid press adoption will continue to expand as manufacturers prioritize precision, energy efficiency, and digital integration. This trend creates opportunities for equipment suppliers that can offer seamless control architecture, sensor-based monitoring, and compatibility with manufacturing execution and analytics platforms. Companies that package presses as connected, 업그레이드able assets will be positioned to capture share in applications where throughput optimization and data transparency are critical.
PW Consulting
Second, regionalization of supply chains will intensify as trade policy, input cost volatility, and service responsiveness considerations push manufacturers toward localized sourcing and production. This dynamic favors firms with established regional manufacturing footprints, domestic material partnerships, and localized service networks. The commercial opportunity lies in designing cost-competitive equipment that leverages regional inputs while maintaining performance standards, and in building service infrastructures that reduce downtime and strengthen customer retention.
Third, application-specific specialization will remain a durable growth path, particularly in sectors such as aerospace and defense, electronics and electrical manufacturing, and niche compression or forming processes. These segments reward engineering depth, validation capability, and the ability to meet stringent performance and compliance requirements. Suppliers that develop focused application expertise and tailored solutions can command premium positioning and build long-term customer relationships that are less susceptible to price-based competition.
Potential risks and uncertainties warrant attention. Steel price trajectories remain uncertain, with structural overcapacity and weak Chinese demand expected to suppress recovery through 2026 and produce only a modest upturn from 2027. Tariff structures could shift, altering relative cost advantages between domestic and imported inputs. Demand cycles in automotive and broader industrial production may introduce volume volatility, especially where model changes, electrification transitions, or regional assembly reallocations influence stamping and forming requirements. Finally, the pace of servo-electric adoption and digital integration may vary across regions and end-use segments, creating uneven growth patterns that require flexible commercial strategies.
Strategic Recommendations for Decision-Makers
For manufacturers and equipment suppliers, the priority is to align product portfolios with the dual imperatives of precision automation and regional supply chain resilience. Investing in servo-electric and hybrid capabilities, strengthening digital integration features, and securing reliable domestic or regional material sources will support competitive positioning amid tariff volatility and steel cost uncertainty. Equally important is expanding service and upgrade offerings that create recurring revenue and deepen customer relationships, particularly where presses are deployed in high-utilization, precision-critical environments.
For investors, the market presents selective opportunities in companies that combine technology differentiation with verified regional manufacturing and service capabilities. Evaluating exposure to servo-electric transition trends, application specialization in higher-margin segments such as aerospace and defense or electronics and electrical forming, and the ability to manage input cost risk through sourcing strategies can help identify resilient investment targets. Monitoring trade policy developments and steel market dynamics will also be essential for anticipating margin trajectories and competitive shifts.
For procurement and operations leaders, the focus should be on total cost of ownership, integration readiness, and supplier stability. Evaluating press options through the lens of energy efficiency, automation compatibility, service responsiveness, and long-term parts availability can reduce operational risk and support production flexibility. Engaging suppliers with demonstrated regional presence and the ability to deliver tailored solutions for specific forming or stamping requirements will help balance performance objectives with cost and supply assurance.
Detailed segmentation data, company-level revenue estimates, regional demand profiles, and customized strategic scenarios can support more granular planning. Exploring the full research report provides access to deeper breakdowns across type, application, and region, along with tailored guidance for specific business contexts and investment theses.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Press Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com