

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Agility Training Equipment Market: Why 3.95% CAGR and 2032 Expansion Reshape Strategy

Navigating Growth and Transformation in the Global Agility Training Equipment Market
Market Overview: Current Landscape and Defining Challenges
The worldwide agility training equipment market has demonstrated steady expansion over the past five years, reaching an estimated $1.74 billion in 2025. Historical trajectory shows consistent momentum, with revenues climbing from $1.45 billion in 2020 before navigating a brief contraction in 2023, followed by renewed recovery. Projections indicate the market will surpass the $2.28 billion threshold by the end of the forecast window, supported by a compound annual growth rate of approximately 3.95%. While this growth profile reflects sustained demand across multiple end-use sectors, the underlying dynamics reveal a market navigating structural adjustments rather than experiencing uniform expansion.
One of the most pressing challenges shaping the sector is the evolving regulatory environment surrounding equipment safety and performance standards. Recent updates from major governing bodies have introduced stricter compliance requirements for course apparatus, including modifications to jump configurations, pause zones, and inspection protocols. These changes require manufacturers to redesign products, validate materials, and adapt labeling or certification processes. Companies that rely on legacy designs or operate with lean compliance infrastructure face margin compression and delayed time-to-market, while those that integrate safety engineering early in the development cycle are converting regulatory shifts into competitive differentiation.
Vocational Training Equipment Market
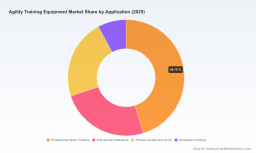
A second critical inflection point involves the bifurcation of demand across professional, institutional, and consumer segments. High-performance athletic programs and organized competition circuits continue to prioritize durability, precision calibration, and sport-specific specifications. At the same time, educational facilities and community fitness providers are placing greater emphasis on modular, cost-effective setups that support high throughput and rapid reconfiguration. Household users represent a smaller but growing share, driven by increased interest in at-home conditioning and pet-oriented training activities. Balancing product lines to serve these divergent requirements without diluting brand positioning or overcomplicating manufacturing is becoming a defining operational test.
Rugby Equipment Market
Supply chain normalization has also reshaped the market’s growth trajectory. After experiencing material volatility and logistics bottlenecks in earlier years, the industry has recalibrated sourcing strategies and production routing. However, raw material pricing for polymers, treated metals, and specialty rubber compounds remains sensitive to regional demand fluctuations and freight cost variability. This environment rewards manufacturers with diversified supplier networks and flexible production planning, while exposing those dependent on single-source components to pricing shocks and inventory uncertainty.
Key Drivers: Forces Reshaping Demand and Competitive Advantage
Technological innovation in material engineering and modular design is fundamentally altering how agility training equipment is built, deployed, and maintained. Manufacturers are increasingly integrating lightweight composite structures, impact-absorbing surfaces, and adjustable height mechanisms that reduce setup time while preserving performance integrity. These advancements address the dual imperatives of safety and versatility, allowing a single product platform to serve fast-twitch conditioning, sport-specific drills, and multi-sport practice environments. The shift toward engineered modularity also supports more efficient inventory management, as trainers and facility operators can scale capacity without purchasing entirely separate equipment suites.
Policy and regulatory developments are functioning as both a compliance requirement and a catalyst for product modernization. Updated standards from international bodies and sport-specific governing organizations have reinforced expectations around structural testing, impact resistance, and user safety across stationary training apparatus. In parallel, the publication of refreshed general safety specifications for fitness and training equipment has created a clearer benchmark for manufacturers seeking to validate product reliability across multiple jurisdictions. Companies that proactively align their design processes with these frameworks are reducing the risk of retrofit costs and gaining credibility with procurement teams that prioritize certified equipment for institutional and commercial installations.
PW Consulting
Demand-side behavior is shifting as training philosophies become more data-informed and cross-functional. Athletic programs, educational institutions, and fitness operators are increasingly designing drills that blend agility work with strength, coordination, and recovery components. This convergence is expanding the functional role of traditional equipment such as ladders, hurdles, markers, and poles, which are now being positioned as foundational tools within broader conditioning ecosystems rather than isolated practice items. Simultaneously, consumer interest in structured home routines and pet-oriented activity programs has broadened the addressable audience for entry-level and mid-tier equipment, encouraging manufacturers to develop products that balance ease of use with sufficient durability for repeated practice sessions.
Cost structure and sourcing strategies are also redefining competitive positioning. The market has moved from an era of acute supply disruption to one characterized by selective regionalization and supplier diversification. Leading producers are investing in production flexibility, balancing cost-efficient sourcing with proximity to key end markets to reduce lead times and improve responsiveness. This shift is particularly relevant for distributors and private-label operators, who are evaluating manufacturing partnerships that can accommodate variable order volumes, seasonal demand swings, and region-specific certification requirements without sacrificing consistency. The result is a market where operational agility is becoming as valuable as product performance in determining long-term resilience.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The competitive environment in agility training equipment is characterized by a broad field of specialized manufacturers, diversified sports-supply firms, and channel-focused distributors. Market concentration remains relatively moderate, with the top players collectively holding a limited share of total revenue. This fragmented structure reflects the diversity of end applications, ranging from competition-grade dog agility courses and professional athletic conditioning to institutional physical education programs and general fitness usage. Within this landscape, successful companies are distinguishing themselves through product reliability, application-specific engineering, and the ability to serve distinct customer segments with clearly defined value propositions.
Regional manufacturing presence continues to influence competitive positioning. Several leading suppliers based in the United States emphasize domestic production, durability, and close alignment with sport-specific training standards. These companies often compete by offering equipment tailored to organized trials, coaching environments, and commercial training facilities where equipment turnover, safety expectations, and performance consistency are closely scrutinized. In contrast, producers operating from export-oriented manufacturing hubs are leaning into scalability, broad product catalogs, and competitive pricing to serve institutional buyers, team programs, and multi-site distributors. Both models can be viable, but they require different operating priorities: one centers on application precision and trust within regulated competition ecosystems, while the other emphasizes breadth, cost control, and distribution reach.
Product differentiation is increasingly tied to versatility and safety engineering rather than basic equipment availability. Suppliers that offer integrated ranges of ladders, hurdles, rings, poles, cones, and training accessories are better positioned to meet the needs of buyers seeking unified procurement and consistent training aesthetics across facilities. At the same time, companies that focus on specialized segments, such as canine agility systems or performance-oriented athletic drills, are building defensible niches by refining equipment geometry, material choices, and user feedback loops. The presence of both broad-line and niche players indicates a market that supports multiple strategic paths, provided each company maintains clarity about its target user and procurement context.
The market structure appears poised for continued evolution through selective consolidation, partnership formation, and the entry of new brands that bring fresh product concepts or digital-enabled purchasing experiences. Larger distributors and diversified sports-equipment portfolios may pursue acquisitions or private-label agreements to expand category coverage and strengthen regional fulfillment. At the same time, emerging entrants with focused product lines, improved material specifications, or streamlined setup mechanisms can capture attention in segments where buyers are actively seeking upgrades from older equipment generations. The most consequential trend is not simply the number of competitors, but the growing importance of compliance readiness, modularity, and segment-specific credibility as barriers to sustained growth.
Future Outlook: Strategic Trends and Emerging Risks
Over the next three to five years, one of the most important trends will be the continued alignment of equipment design with updated safety and performance expectations across both human athletic training and animal agility applications. As inspection protocols, course design practices, and general equipment safety specifications mature, buyers will increasingly favor products that can demonstrate consistent compliance and reduced setup risk. This creates an opportunity for manufacturers that invest in validated design processes, transparent documentation, and training support materials that help end users implement equipment correctly. Anticipated course-design refinements and equipment-requirement adjustments are likely to make reliability and adaptability central purchasing criteria rather than secondary considerations.
A second trend is the growing preference for modular, multi-purpose equipment that supports faster course construction, flexible drill programming, and space-efficient storage. Facilities operating under constrained floor space or rotating usage schedules will favor systems that can be reconfigured quickly and withstand frequent rearrangement. This shift opens opportunities for suppliers that combine durable construction with adjustable components, standardized connection points, and clear instructional guidance. The commercial appeal of such systems extends beyond elite programs, as schools, community sports organizations, and home users look for equipment that can serve multiple activities without requiring separate dedicated inventory.
A third development to watch is the gradual broadening of target segments through intersectional demand. Conditioning programs are increasingly incorporating agility work into broader athletic development plans, while pet-related training continues to gain visibility among household consumers and specialized service providers. These overlapping demand streams may encourage manufacturers to create product families that span multiple user groups without fragmenting brand identity. The opportunity lies in designing tiered offerings that retain professional-grade options for high-intensity use while delivering accessible, low-maintenance variants for lighter or intermittent applications.
Potential risks include persistent sensitivity in material and logistics costs, uneven adoption of newer safety expectations across regions, and the possibility that rapid product proliferation could reduce differentiation if competitors converge on similar feature sets. Companies that fail to monitor regulatory updates or rely on outdated specifications may face renegotiation pressure from procurement teams and event organizers. In addition, over-extension into too many unrelated segments can dilute manufacturing focus and weaken quality control. Balanced expansion, disciplined compliance integration, and clear customer targeting will be critical to navigating these uncertainties.
Strategic Recommendations for Decision-Makers
Manufacturers and product developers should prioritize safety-aligned design and modular versatility as core investment themes. Engineering teams can benefit from mapping upcoming regulatory expectations early, testing materials against broader usage scenarios, and developing product families that allow users to scale from basic training to higher-intensity applications. Clear documentation, consistent quality control, and straightforward setup mechanisms will strengthen acceptance among institutional buyers and event organizers who value predictable performance.
Investors and strategic partners should evaluate opportunities based on segment relevance, compliance readiness, and supply chain flexibility rather than top-line growth alone. Categories with recurring institutional procurement, multi-site distribution potential, and demand from both professional and educational environments may offer more durable revenue profiles. Due diligence should include an assessment of how well target companies can adapt product portfolios to evolving safety expectations and whether their manufacturing footprint supports stable lead times and regional responsiveness.
Procurement leaders and facility operators should treat equipment selection as a long-term operational decision rather than a short-term cost exercise. Prioritizing certified, durable, and reconfigurable equipment can reduce replacement frequency, simplify staffing training, and support more flexible programming across sports, fitness, and education settings. Buyers should also evaluate supplier support services, replacement part availability, and product roadmaps to ensure that current purchases remain aligned with future usage needs.
For organizations seeking detailed segmentation data, regional demand patterns, and customized scenario planning, a comprehensive market intelligence report can provide a more granular foundation for strategic planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Agility Training Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com