

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Global Vise Grips Market 2026: Why 4.25% CAGR Reshapes Industry Dynamics

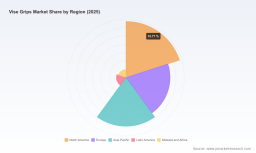
Worldwide Vise Grips Market: Strategic Shifts and Commercial Opportunities in a Consolidating Landscape
Market Snapshot: Scale, Trajectory, and Core Headwinds
The global market for vise grips and locking pliers has established itself as a mature yet steadily expanding segment within the broader hand tool industry. Anchored by a base-year valuation in 2025 and projected to grow at a compound annual rate of approximately 4.25 percent through 2032, the market reflects a baseline trajectory shaped by steady industrial demand, replacement cycles in professional trades, and sustained interest from do-it-yourself consumers. From 2020 to 2025, the segment navigated post-pandemic supply disruptions, raw material volatility, and shifting end-use spending patterns, ultimately settling into a phase of moderate but consistent expansion. The forward-looking period through 2032 indicates that growth will remain incremental rather than explosive, with revenue compounding as manufacturers refine product lines, expand distribution reach, and capture share in specialized applications where secure clamping and high gripping force remain non-negotiable.
PW Consulting
Despite this constructive outlook, the industry stands at a series of operational and strategic crossroads. First, cost volatility in primary input materials has become a recurring pressure point. The price environment for hot-rolled coil steel, the foundational material for forged locking pliers jaws and bodies, has fluctuated within a range that directly influences manufacturing margins and pricing strategies. When steel costs climb, producers must decide whether to absorb the impact, pass it downstream, or accelerate redesigns and process efficiencies to offset material intensity. This dynamic is particularly acute for mid-tier manufacturers who lack the scale to hedge raw material exposure or the premium positioning to justify rapid price adjustments without risking volume erosion.
Grippers Market
Second, the competitive landscape is tightening around concentration and differentiation. A relatively small group of established players accounts for a substantial share of total market revenue, signaling that scale, brand recognition, and distribution leverage matter more than ever. For newer entrants or regional specialists, this concentration creates a barrier to rapid expansion unless they can deliver clear functional advantages, niche application fit, or localized service models that larger multinationals cannot easily replicate. At the same time, consolidation pressures are reshaping how products move from factory to end user, with distributors and professional retailers increasingly favoring suppliers who can offer consistent quality, broad catalog depth, and reliable lead times across multiple markets.
Tension Hand Grip Market
Third, the sector is grappling with a subtle but important regulatory and safety expectation shift. Locking pliers used in industrial, automotive, and welding-adjacent applications are expected to meet evolving material strength, durability, and ergonomic standards. While these requirements do not radically alter the core product category, they raise the compliance burden for manufacturers and create an uneven playing field where brands that have already aligned their design and quality assurance processes with recognized international guidelines can move faster and with less friction. The net effect is a market that rewards operational discipline and penalizes reactive product development.
Key Drivers Reshaping the Vise Grips Landscape
Market evolution in this segment is being propelled by a combination of product innovation, changing end-user expectations, regulatory alignment, and cost structure pressures. Each driver carries distinct implications for how companies should position their portfolios and manage growth.
Functional Innovation and Design Refinement
The most visible driver is continuous product refinement aimed at improving grip performance, accessibility, and corrosion resistance. Locking pliers have moved beyond basic jaw configurations into more application-specific designs that address real-world workspace constraints. Recent releases have emphasized aggressive tooth patterns for stronger bite in demanding material conditions, extended nose geometries for improved reach in confined spaces, and protective coatings that extend service life in environments where moisture, welding spatter, or chemical exposure can accelerate wear. These enhancements matter because they convert a mature product category into a still-evolving one, allowing manufacturers to justify premium positioning while retaining relevance with professional users who depend on tool reliability every day.
For manufacturers, this innovation cycle is not merely cosmetic. It reshapes purchasing criteria among professional buyers, who increasingly evaluate locking pliers based on usable reach, jaw articulation, grip retention under load, and resistance to corrosion after repeated use. Companies that can translate workshop pain points into tangible design upgrades are better positioned to retain share in high-value professional segments, while those relying on generic iterations risk being undersold or replaced by specialty alternatives.
Professional Demand and Application Persistence
On the demand side, the durability of the vise grips market is closely tied to the persistence of core application areas. Automotive repair, construction and renovation, and metal fabrication continue to generate reliable demand because these environments require secure clamping, adjustable holding force, and tools that can withstand repeated professional use. Unlike consumer-electronics categories that can be disrupted by new technologies, locking pliers benefit from being embedded in workflows where mechanical clamping remains indispensable. This structural demand provides a floor under market growth and explains why revenue has held up even through periods of broader economic uncertainty.
At the same time, demand patterns are shifting within these application pools. Professional automotive and industrial users are increasingly favoring tools that offer a balance of high gripping force and maneuverability, especially in modern repair contexts where engine bays and assembly spaces are more densely packed. In construction and renovation, project-based purchasing is favoring suppliers that can deliver consistent availability across popular sizes and configurations. For DIY and home maintenance segments, the growth path is more price-sensitive and education-driven, requiring clearer communication about tool function, sizing, and safe use. The practical takeaway is that application persistence does not guarantee uniform growth; it rewards segmentation discipline and messaging precision.
Regulatory Expectations and Compliance as Differentiation
Regulatory and standards-based expectations are becoming a more meaningful differentiator rather than a mere compliance checkbox. Locking pliers used in industrial and welding-adjacent settings must align with general hand tool safety expectations, including material strength, structural integrity, and ergonomic considerations. While these are baseline requirements, they create a competitive tilt toward manufacturers that already operate mature quality systems and can demonstrate conformance with recognized ISO and ANSI-aligned guidelines. Compliance, in practice, reduces downstream friction for distributors and professional buyers who want to minimize liability and ensure tool reliability across fleets and job sites.
This dynamic is nudging the market toward a higher quality baseline. It also raises the stakes for smaller producers who may lack formal testing infrastructure or consistent documentation processes. In the near term, alignment with recognized standards is increasingly tied to procurement eligibility in professional and institutional environments, making it a commercial lever as much as a technical one.
Raw Material Economics and Supply Chain Discipline
Cost structure remains a critical driver because the economics of forged locking pliers are closely tied to steel availability and pricing. Hot-rolled coil prices have occupied a volatile band in recent periods, with notable regional variation between North American and global benchmarks. When input costs rise, the impact is felt across tooling, forging, heat treatment, and logistics, forcing manufacturers to manage not only unit cost but also inventory timing, order cadence, and supplier relationships. Companies with stronger procurement planning, flexible sourcing, and efficient forging workflows can protect margins more effectively than those relying on ad hoc purchasing or rigid cost structures.
The broader implication is that supply chain discipline is no longer a back-office function; it is a strategic variable that influences pricing power, product availability, and responsiveness to demand spikes. In a market where differentiation is increasingly subtle, cost management and production reliability can become the deciding factors in whether a manufacturer can sustain profitability while investing in product development.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The competitive environment in the vise grips market is defined by a core group of established manufacturers with strong brand equity, broad professional distribution, and distinct design philosophies. Market concentration is meaningful enough that scale advantages in procurement, manufacturing, and channel reach matter, but it is not so extreme that niche specialists cannot compete on performance, specialization, or regional fit. The result is a landscape where positioning choices are becoming more deliberate and where product storytelling must rest on functional credibility rather than generic claims.
Among the leading players, Irwin Tools stands out as a long-recognized anchor in the locking pliers category, with a portfolio that spans curved jaw, straight jaw, long nose, fast-release, and specialty configurations. Its strategy centers on broad application coverage across industrial, automotive, and construction use cases, reinforced by familiar brand recognition and deep channel presence. Snap-on occupies a premium professional tier, emphasizing aggressive tooth design, longer nose architectures for tighter access, and variants associated with U.S. manufacturing for segments that value provenance and high-end performance. Grip-on Tools brings a specialist orientation from Europe, combining a wide professional range of locking pliers and C-clamps with corrosion-resistant innovations such as epoxy resin coatings, an approach that aligns well with users exposed to harsh working conditions. Knipex maintains a reputation rooted in precision and durability, targeting professional trade and industrial users with grip pliers and locking-style tools that prioritize fit, feel, and consistent performance. Klein Tools positions around professional sets and high-torque models tailored to electrical, construction, and maintenance professionals, leveraging its strong association with trade-quality hand tools. Bahco contributes a European professional hand tool perspective under a larger regional group structure, with straight-jaw and other variants aimed at industrial and maintenance users. Toptul represents a Taiwan-based manufacturing and supply presence that supports professional and industrial tool markets with jaw locking pliers, illustrating how regional producers can remain relevant by serving both local demand and export channels.
The strategic differentiation among these companies is not simply about catalog size. It is about which value proposition resonates with the buyer in front of them. For high-end professional users, the purchase decision often hinges on perceived durability, biting performance, ergonomic comfort, and availability of trusted service support. For broader industrial procurement, consistency across reorder cycles, quality documentation, and predictable lead times can be equally important. For more price-conscious or project-based buyers, the question is whether the tool offers dependable performance at a defensible cost. Companies that understand which lever matters most in each channel are better equipped to avoid price-only competition and protect margin.
Recent product activity reinforces this positioning race. New catalog expansions have highlighted wider ranges, corrosion-resistant coatings, and welding-related clamp variants, while introductions of aggressive teeth and longer nose profiles reflect a focused effort to improve accessibility and grip in constrained work environments. Updates to grip pliers sizing and catalog breadth show that manufacturers are still investing in practical variations that help them cover more professional use cases without abandoning their core identity. This is a sign of a market that is maturing in product philosophy: rather than attempting radical reinvention, leaders are refining the details that matter most in daily use, which tends to be a more sustainable growth path for a mature hand tool category.
Looking at market evolution, the most likely trajectory is a combination of consolidation pressure and selective fragmentation. Larger multinationals will continue to leverage scale, global distribution, and cross-brand portfolio strength, while specialized European and Asia-based manufacturers will compete by emphasizing corrosion resistance, specialized clamping styles, and regional service relationships. The middle ground is where the competition will be sharpest, because that is where mid-tier players must prove that they can match the reliability expectations of professional buyers while remaining cost-competitive. New entrants will likely find the most traction not by competing head-on with top-tier brands across all segments, but by targeting underserved applications, regional distribution gaps, or specific user groups that value specialized features enough to pay a premium or switch suppliers.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
The market's next phase is likely to be shaped by incremental but strategically meaningful trends rather than sudden disruption. The most consequential will be the continued elevation of product specialization as a growth lever. As professional users face tighter workspaces, more varied materials, and higher expectations for corrosion resistance and ergonomic comfort, locking pliers portfolios will keep expanding in targeted variants rather than in undifferentiated breadth. This trend favors companies that can map design improvements directly to application needs and communicate those benefits clearly to buyers who may otherwise default to familiar legacy products.
A second trend is the growing importance of compliance and quality assurance as commercial enablers. As procurement processes in industrial, automotive, and institutional settings become more rigorous, documented conformance to recognized safety and durability expectations will increasingly influence supplier selection. This does not mean regulation will dominate market growth, but it will reinforce a quality floor and reward manufacturers who can demonstrate consistent performance, reliable materials, and traceable production practices. Over time, this may narrow the gap between premium brands and competent mid-tier competitors, provided the latter can match the documentation and testing rigor buyers now expect.
A third trend is the ongoing tension between raw material cost pressure and margin resilience. Steel price fluctuations will continue to test production economics, but the upside is that companies with disciplined sourcing, efficient forging, and clear product tiering can use cost variability as a catalyst for process improvement rather than simply a margin threat. The practical opportunity lies in designing portfolios that balance premium variants with high-volume workhorse models, allowing manufacturers to capture professional willingness to pay while preserving volume in price-sensitive channels. The main risk is complacency: if manufacturers treat input cost swings as temporary rather than structural, they may underinvest in efficiency and lose competitiveness when pricing environments normalize.
Across these trends, the clearest commercial opportunity is to align product development, channel strategy, and procurement readiness with the specific requirements of professional applications where secure clamping remains essential. Markets that stay anchored in durable application demand can still generate meaningful growth, but only if companies treat specialization, compliance readiness, and cost discipline as integrated strategic choices rather than separate functions.
Strategic Actions for Decision Makers
For manufacturers, the priority is to sharpen portfolio segmentation so that each product tier serves a clear application and channel fit. Expanding catalog breadth should be paired with documented functional advantages, especially around grip performance, reach, and corrosion resistance, because these are the attributes that professional buyers use to justify repurchase and fleet standardization. Equally important is building procurement and quality documentation into the product story, since compliance readiness is increasingly part of how suppliers win and retain professional accounts.
For investors, the most durable value creation in this market is likely to come from companies that combine steady application demand with disciplined cost control and credible product differentiation. The segment is not a high-growth story in the volatile sense, but it can offer predictable compounding for players that manage steel exposure well, maintain channel strength, and invest in practical innovations that reinforce repeat purchase behavior. Due diligence should weigh not just brand recognition but also production efficiency, regional sourcing flexibility, and the ability to expand into application-specific variants without diluting core margins.
For procurement leaders and professional buyers, the decision framework should shift from lowest unit price to total cost of reliable use. Evaluating locking pliers by jaw performance, ergonomic fit, corrosion resilience, and supply consistency can reduce downtime and replacement frequency over time. Sourcing from manufacturers with established quality processes and clear standards alignment can also lower procurement risk in environments where tool failure creates safety or workflow disruptions.
For stakeholders who need to move quickly across these dimensions, detailed segmentation data, regional breakdowns, and company-level scenario analysis can substantially improve planning accuracy. A comprehensive research report can provide the deeper cuts needed to compare product tier economics, map competitive positioning by channel, and evaluate which application segments offer the best near-term expansion potential. Access to that level of detail makes it easier to convert broad market visibility into specific product, pricing, and sourcing decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Vise Grips Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com