

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Worldwide Disposable Color Contact Lenses Market: How 8.7% CAGR and Cosmetic Demand Reshape Growth
By pmarketresearch, 2026-09-18
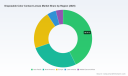
Strategic Horizons: Navigating Growth in the Global Disposable Color Contact Lenses Market
Market Overview & Core Challenges
The global market for disposable color contact lenses has entered a phase of sustained expansion, driven by a convergence of aesthetic demand and advancements in lens technology. Valued at approximately USD 3.45 billion in 2025, the market reflects a robust upward trajectory from its 2020 baseline. Projections indicate that revenue will continue to climb steadily, reaching an estimated USD 6.19 billion by 2032, supported by a compound annual growth rate of 8.7%. This performance underscores the sector's resilience and its transition from a niche segment to a significant pillar within the broader vision care industry.
Throughout the historical period from 2020 to 2025, the market demonstrated consistent momentum, overcoming initial disruptions and adapting to shifting consumer preferences. The forecast period extending to 2032 suggests that this growth is not merely cyclical but structural, fueled by changing lifestyles and increased acceptance of colored lenses for both vision correction and cosmetic enhancement. The revenue streams are diversifying, with significant contributions coming from various replacement cycles and application types, indicating a mature yet evolving ecosystem.
Despite the positive outlook, the industry faces critical challenges that require strategic attention. One pivotal issue is the regulatory complexity surrounding safety and classification. Colored lenses, even those used purely for cosmetic purposes, are increasingly scrutinized as medical devices. This shift demands rigorous biocompatibility testing and sterility assurance, raising barriers to entry and operational costs. Companies must navigate varying international standards while maintaining speed to market, creating a tension between innovation and compliance.
Another significant concern is market concentration. A substantial portion of the market value is held by a few dominant players, creating a landscape where new entrants must differentiate sharply to gain traction. This concentration can lead to pricing pressure on smaller manufacturers and limit distribution access for emerging brands. As the market expands, the balance of power between established giants and agile niche players will define competitive dynamics, requiring stakeholders to constantly reassess their positioning.
Additionally, supply chain volatility and raw material costs pose ongoing risks. The production of disposable lenses involves specialized polymers and moisture-retaining technologies, the availability and pricing of which can fluctuate. Ensuring consistent quality while managing costs is a delicate balance, particularly as manufacturers scale up to meet growing demand in diverse geographic regions. These structural challenges highlight the need for robust operational strategies to sustain growth in a competitive environment.
Key Growth Drivers
Technological Innovation in Materials and Comfort
Advancements in lens materials are fundamentally reshaping the disposable color contact lens market. The shift toward silicone hydrogel and high-water content polymers has addressed long-standing concerns about comfort and oxygen permeability. These innovations allow for extended wear times and reduced dryness, making colored lenses more viable for daily use rather than occasional cosmetic application. Manufacturers are increasingly integrating moisture-locking technologies and UV protection into their product lines, enhancing the value proposition for consumers who prioritize eye health alongside aesthetics.
Recent product launches illustrate this trend. For instance, the introduction of toric color variants in 2025 marked a significant step forward, enabling individuals with astigmatism to access color enhancement without compromising visual clarity. Such developments expand the addressable market by catering to specific vision needs that were previously underserved in the colored lens category. The focus on multi-tone gradation and natural-looking shades further drives adoption, as consumers seek subtle enhancements rather than dramatic transformations, aligning with broader beauty trends favoring authenticity.
Regulatory Frameworks and Safety Standards
The regulatory environment plays a dual role as both a barrier and a driver of quality. With colored and decorative lenses classified as Class II medical devices in major markets, the requirement for 510(k) premarket clearance and adherence to ISO 10993 biocompatibility standards ensures a baseline of safety. This classification elevates consumer confidence, particularly in regions where awareness of eye health is growing. Compliance with these standards also serves as a competitive differentiator, signaling reliability and commitment to user safety.
However, regulatory harmonization remains a work in progress. Variations in approval processes and labeling requirements across regions can complicate global expansion strategies. The recent focus on sterilization validation and shelf-life stability testing underscores the industry's emphasis on product integrity. Manufacturers that proactively align with these rigorous standards can mitigate risk and build trust, while those lagging behind face potential market access restrictions. The regulatory landscape thus incentivizes investment in quality systems and technical expertise.
Evolving Consumer Preferences and Social Influence
Consumer behavior is a primary catalyst for market expansion. The normalization of colored lenses as a fashion accessory, amplified by social media and influencer culture, has broadened their appeal beyond traditional vision correction users. Younger demographics, in particular, view lenses as an extension of personal style, driving demand for a wide array of colors, patterns, and effects. This trend is supported by the rise of direct-to-consumer models, which allow brands to engage users through digital channels and offer personalized experiences.
There is also a growing preference for daily disposables due to their convenience and hygiene benefits. Users appreciate the elimination of cleaning routines and the reduced risk of contamination, which aligns with heightened health consciousness post-pandemic. This shift influences purchasing decisions, with many consumers willing to pay a premium for the ease and safety of disposable options. As lifestyle patterns continue to evolve, the demand for versatile, low-maintenance vision solutions is expected to remain strong.
Contact Lenses Market
Supply Chain Dynamics and Cost Structures
Supply chain resilience has become a critical factor in sustaining market growth. The reliance on specialized raw materials and manufacturing technologies requires stable sourcing strategies. Companies are increasingly diversifying their supplier base and investing in vertical integration to control quality and reduce dependency on external partners. These moves help mitigate the impact of raw material price volatility and logistics disruptions, ensuring consistent production capacity.
Smart Contact Lenses Market
Cost structures are also influenced by economies of scale. As production volumes increase, manufacturers can optimize per-unit costs, making premium products more accessible. At the same time, the demand for certified products and compliance with international standards adds to operational expenses. Balancing these factors requires efficient process design and strategic inventory management. Firms that succeed in optimizing their supply chains can offer competitive pricing while maintaining margins, strengthening their position in a price-sensitive market.
Competitive Landscape & Strategic Positioning
The competitive arena is characterized by a mix of global giants and specialized regional players, each pursuing distinct strategies to capture market share. Alcon Inc. and Johnson & Johnson Vision Care stand out as leaders, leveraging their extensive distribution networks and brand recognition. Their portfolios often feature advanced daily disposable options with proprietary technologies, such as moisture retention and UV protection, appealing to health-conscious consumers. These companies benefit from scale advantages and the ability to invest heavily in research and development, ensuring their products meet high performance standards.
Regional specialists are carving out niches through innovation and targeted offerings. Menicon Co., Ltd. has strengthened its position by launching toric color variants, addressing a specific unmet need and differentiating from standard cosmetic lenses. Similarly, Interojo Co., Ltd. has gained traction with FDA-cleared daily wear options, highlighting the importance of regulatory approval in building credibility. Maxvue Vision and Solotica demonstrate the power of global distribution and diverse product ranges, catering to varied consumer preferences across multiple countries. Their ability to adapt to local tastes while maintaining certification standards enables them to compete effectively in diverse markets.
PW Consulting
Strategic differentiation is increasingly focused on technology and user experience. Companies are investing in lens designs that enhance natural eye appearance, using multi-tone gradation and high opacity to achieve realistic results. The integration of features like blue light filtering and moisture technologies adds value beyond aesthetics, attracting users who seek functional benefits. Furthermore, collaborations with eye care professionals and digital engagement strategies are becoming essential tools for building brand loyalty and driving trial.
The market structure shows tendencies toward both consolidation and fragmentation. Large players continue to acquire capabilities or expand portfolios to cover broader segments, while new entrants emerge with innovative materials or business models. Regulatory approvals act as gatekeepers, favoring companies with established quality systems. As the market matures, the ability to navigate compliance, innovate rapidly, and connect with consumers through multiple channels will determine long-term success. Stakeholders must remain agile to respond to shifting dynamics and capitalize on emerging opportunities.
Future Trends & Opportunities
The market is poised to see accelerated adoption of daily disposable color lenses over the next few years. The convenience and hygiene benefits align with consumer preferences for low-maintenance products, driving volume growth. This trend presents opportunities for manufacturers to expand their daily disposable ranges and for retailers to optimize inventory for high-turnover items. Expect increased competition in this segment, with brands emphasizing comfort, safety, and aesthetic variety to attract users.
Another emerging trend is the convergence of vision correction and cosmetic enhancement. As more products offer prescription options in color designs, the addressable market expands to include individuals who require vision correction but also desire aesthetic customization. This integration requires advanced manufacturing capabilities and regulatory compliance, creating barriers that favor established players. Companies that can deliver high-quality toric and multifocal color lenses will capture significant value in this growing segment.
Digital engagement and e-commerce will continue to shape distribution strategies. Online channels offer direct access to consumers, enabling personalized marketing and rapid feedback loops. Brands that invest in robust digital platforms and data analytics can better understand user preferences and tailor their offerings. However, the reliance on online sales also introduces challenges related to fitting guidance and professional oversight. Opportunities exist for hybrid models that combine digital convenience with professional support, ensuring safe and informed usage.
Potential risks include regulatory tightening and supply chain disruptions. Stricter safety requirements could increase costs and delay product launches, impacting profitability. Fluctuations in raw material availability may affect production stability. Additionally, market saturation in certain segments could lead to margin pressure. Stakeholders should monitor these factors and develop contingency plans to mitigate risks while pursuing growth.
Strategic Recommendations for Decision Makers
For manufacturers, prioritizing innovation in materials and lens designs is essential to differentiate in a crowded market. Investing in toric and multifocal color options can unlock new customer segments, while enhancing comfort features supports retention. Ensuring robust compliance with evolving regulations will safeguard market access and build trust. Companies should also evaluate supply chain resilience, diversifying sources and optimizing production to manage costs effectively.
Investors should focus on companies with strong regulatory credentials and scalable product portfolios. Look for firms that demonstrate agility in adopting new technologies and expanding into high-growth segments like daily disposables. Assessing distribution capabilities and digital engagement strategies can provide insights into long-term competitiveness. Diversification across regions and product types can mitigate concentration risks and capture broader market trends.
Buyers and procurement teams should prioritize suppliers with proven quality systems and certification compliance. Evaluating product ranges for comfort, safety, and aesthetic variety ensures alignment with consumer demand. Building relationships with multiple suppliers can mitigate supply chain risks and provide flexibility in sourcing. Staying informed about regulatory changes and market developments will support informed purchasing decisions and strategic planning.
Access to detailed, up-to-date intelligence is critical for navigating this dynamic landscape. Comprehensive data on segmentation, competitive moves, and regional dynamics enables precise strategy formulation. Stakeholders seeking deeper insights can explore full industry reports to gain granular visibility and tailored recommendations for their specific context.
For detailed analysis of this topic, please visit the official page: Worldwide Disposable Color Contact Lenses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Aluminum Dimethyl Isopropoxide Market: Why 43.59% Asia Pacific Share Reshapes Growth Beyond 6.12% CAGR
By pmarketresearch, 2026-09-18
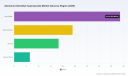
Strategic Trends and Commercial Opportunities in the Worldwide Aluminum Dimethyl Isopropoxide Market
Market Status and Core Challenges
The global market for aluminum dimethyl isopropoxide (ADIP) has entered a phase of measured but steady expansion, driven primarily by its specialized role in advanced materials processing. Valued at approximately USD 68.42 million in 2020, the market has grown to USD 92.45 million in 2025, reflecting a compound annual growth rate of 6.12 percent through 2032. This trajectory indicates a market transitioning from niche industrial supply to a strategically positioned enabler of high-purity thin-film deposition and catalytic processes. Revenue generation remains concentrated within a handful of established participants, with the top three holding roughly 58.4 percent of total market share and the top five approaching 74 percent. Such concentration underscores the technical barriers to entry, stringent purity requirements, and the specialized logistics networks necessary to handle reactive organometallic compounds safely.
The current landscape is defined by a clear bifurcation in demand patterns. High-purity specifications dominate revenue streams, particularly those meeting electronic-grade thresholds above 99.999 percent. This split reflects the material's evolving application profile, where precision-engineered deposition processes require consistent batch-to-batch reproducibility and minimal particulate contamination. Industrial-grade volumes continue to serve broader chemical synthesis and polymerization catalysis needs, but growth momentum has increasingly tilted toward applications requiring sub-micron film control and thermal stability. Geographic distribution reveals a strong pull toward Asia Pacific, North America, and Europe, with the remainder of the market developing at a slower pace tied to localized manufacturing capacity and regulatory maturity. The hierarchy of demand is further shaped by application intensity: semiconductor layer deposition represents the largest utilization channel, followed by polymerization catalysis and glass/ceramic coating formulations.
Despite constructive demand signals, the industry faces structural challenges that will shape near-term strategy. First, the regulatory and safety burden associated with handling water-reactive, highly flammable organoaluminum compounds creates friction across procurement, logistics, and operational compliance. Transport restrictions and specialized storage requirements elevate total cost of ownership for downstream users, particularly smaller fabrication facilities or research laboratories operating under tight compliance budgets. Second, supply chain consistency for upstream organometallic feedstocks introduces volatility into production planning. Manufacturers must manage complex synthesis routes while navigating impurity control and batch certification processes that are integral to maintaining purity thresholds demanded by advanced deposition processes. Third, market participants are navigating a consolidation pressure as high-purity capacity expansion becomes capital-intensive and technically differentiated. Firms that cannot invest in controlled synthesis environments or certified quality management frameworks risk marginalization, while new entrants must contend with both technical credibility and established distribution relationships. These dynamics create a pivotal moment for companies to decide whether to deepen specialization, pursue strategic partnerships, or reposition toward adjacent high-margin segments.
Key Drivers of Market Change
Technological innovation remains a primary engine of growth, particularly as deposition techniques evolve toward tighter process control and lower defect densities. Aluminum dimethyl isopropoxide has gained relevance as a nonpyrophoric alternative precursor to trimethylaluminum in plasma-enhanced atomic layer deposition of aluminum oxide thin films. This shift matters because plasma-enhanced atomic layer deposition enables conformal coating on complex geometries and high-aspect-ratio structures commonly found in advanced semiconductor packaging and device architectures. The move toward safer handling profiles, while maintaining deposition efficiency and film quality, reduces process risk for manufacturers and can lower downstream operational costs related to fire suppression, inert atmosphere controls, and emergency response planning. As device nodes shrink and material specifications tighten, precursor selection increasingly balances reactivity, thermal stability, and impurity tolerance. That balance favors compounds that can deliver consistent stoichiometry without introducing metal contaminants exceeding parts-per-billion thresholds. Consequently, research and commercial scale efforts are converging on formulations and process recipes that optimize film uniformity while reducing variability across wafer lots.
Regulatory and compliance frameworks are simultaneously reshaping the commercial environment. The compound's classification as a highly flammable liquid and vapor with water-reactive properties places it under stringent handling, labeling, and transport requirements across international regulatory regimes. Compliance with road and rail transport standards, alignment with hazardous material handling protocols, and adherence to regional safety directives create both cost and capability implications. For established suppliers, robust compliance infrastructure can become a competitive differentiator, signaling reliability to customers in highly regulated sectors. For procurement teams and end users, these requirements influence supplier selection, location strategy for production sites, and inventory management practices. Companies that proactively align with harmonized safety standards and invest in certified packaging, traceability, and documentation systems can reduce lead-time uncertainty and improve resilience during supply disruptions. In practice, the regulatory environment is steering the market toward suppliers with demonstrated operational discipline, particularly where materials are destined for electronic applications with additional quality and contamination controls.
Demand-side behavior is shifting as end-use industries pursue advanced materials with greater urgency. Semiconductor manufacturing continues to expand in both mature and advanced nodes, with layer deposition processes demanding precursors that can meet increasingly exacting specifications. Beyond front-end processing, secondary growth channels are gaining traction in catalysis and coatings, where aluminum-based organometallic compounds support polymerization reactions and functional surface treatments. In catalysis, the material's role in aluminum precursor chemistry contributes to catalyst design for polymer production, reflecting persistent demand for high-performance plastics and engineered composites. In glass and ceramic coatings, deposition and surface modification applications benefit from aluminum oxide-related chemistry that enhances barrier properties, thermal resistance, and mechanical durability. These demand patterns are not evenly distributed; they concentrate around regions with strong electronics manufacturing ecosystems and established specialty chemical supply chains. As a result, procurement strategies are moving toward multi-source arrangements, technical qualification processes, and long-term supply agreements that balance purity assurance with cost predictability.
PW Consulting
Supply chain and cost structure dynamics further influence how the market evolves. The reliance on upstream organoaluminum feedstocks, particularly trimethylaluminum as a primary synthesis input, introduces sensitivity to raw material availability, pricing fluctuations, and synthesis route optimization. Manufacturers that can stabilize precursor sourcing, improve yield through process refinement, and maintain purity without excessive rework will be better positioned to manage margins. Logistics costs and safety-related handling requirements add another layer of complexity, especially for international distribution and just-in-time delivery expectations. In response, supply strategies are shifting toward regional production footprints, strategic inventory buffers for high-value customers, and closer collaboration between precursor suppliers and deposition process engineers. These adjustments aim to reduce variability, shorten qualification cycles, and improve responsiveness to specification changes. The combined effect is a market in which technical capability and operational reliability increasingly determine commercial success, beyond price considerations alone.
Worldwide Aluminium Tert Butoxide Market
Competitive Landscape and Leading Strategies
The competitive structure of the market is characterized by a small group of specialty manufacturers and distributors with distinct strategic emphases. Several U.S.-based firms occupy prominent positions, each reinforcing credibility through product-grade focus, application alignment, and distribution reach. One specialized manufacturer emphasizes high-purity aluminum dimethyl isopropoxide for atomic layer deposition and metal-organic chemical vapor deposition applications, serving both research and commercial quantities. This positioning reflects a deliberate focus on process-critical customers who require consistent precursor performance and technical support for deposition recipes. Another established supplier offers a high-purity grade intended for atomic layer deposition precursor use, highlighting purity levels that align with electronic-grade expectations. Its approach underscores the importance of certified grade definitions and traceable product information in sectors where material variability can affect yield and device reliability. A global manufacturer and supplier provides commercial and research quantities, broadening accessibility and reinforcing a product portfolio that spans multiple organometallic specialties. This wider scope can support cross-selling and customer consolidation, particularly for procurement teams seeking a single qualified source for multiple materials.
Additional participants bring regional and application-specific differentiation. A South Korean producer focuses on dimethylaluminum isopropoxide as an aluminum precursor specifically for metal-organic chemical vapor deposition and atomic layer deposition applications, aligning closely with the semiconductor materials ecosystem in Asia Pacific. Such regional specialization can improve proximity to end users, reduce lead times, and strengthen technical collaboration with local fabrication and research institutions. A supplier offering the dimeric form of dimethylaluminum isopropoxide for semiconductor and thin-film deposition processes illustrates how molecular form and packaging can become differentiating factors when customers require specific handling characteristics or process compatibility. A global distributor supplements these offerings by supplying the compound as part of a broader specialty chemicals portfolio, enabling customers to consolidate sourcing and benefit from established logistics networks. This distribution role is particularly valuable for smaller research groups, pilot-line operations, and procurement functions seeking flexible order quantities and multi-product supply relationships.
Leading firms differentiate through a combination of purity assurance, application alignment, and operational reliability. High-purity grades command premium positioning because they reduce qualification risk for electronic applications and support reproducibility across production batches. Suppliers that invest in controlled synthesis environments, robust analytical verification, and clear grade definitions can build trust with customers who operate under stringent contamination limits. Application-specific positioning also matters: companies that communicate clearly how their materials fit into deposition processes, catalyst formulations, or coating workflows can shorten evaluation cycles and enhance customer retention. Operational reliability, including packaging integrity, transport compliance, and batch traceability, further reinforces commercial credibility in a market where material handling risk and quality consistency are central concerns. Strategic differentiation is therefore less about volume scale and more about precision, certification, and the ability to support customers through technical evaluation and long-term supply.
Market evolution points toward gradual consolidation among high-purity specialists and continued fragmentation within broader distribution channels. Larger integrated players may pursue partnerships or selective acquisitions to strengthen capacity, broaden geographic coverage, or deepen application support. At the same time, regional producers can capture value by aligning with local electronics ecosystems and responding quickly to specification changes in nearby fabrication hubs. New entrants face meaningful hurdles, including purity certification, safety compliance, and the need to establish technical trust with demanding end users. As a result, the landscape is likely to remain concentrated at the top while specialized niches persist around dimer forms, regional supply, and multi-product distribution. Companies that can combine technical credibility with dependable logistics and clear application messaging are best positioned to expand share without engaging in undifferentiated price competition.
Future Trends and Outlook
Over the next three to five years, one of the most consequential trends will be the continued migration toward safer and more controllable precursor chemistries in advanced deposition processes. As plasma-enhanced atomic layer deposition and related techniques become more widely adopted for complex device structures, demand for precursors that reduce pyrophoric risk while maintaining film quality is likely to strengthen. This trend creates opportunities for suppliers that can demonstrate consistent purity, reliable batch performance, and strong technical documentation. Manufacturers that invest in process recipes, qualification support, and application notes will be better positioned to convert technical adoption into recurring supply relationships. End users, in turn, may favor arrangements that reduce process variability and simplify compliance, even if unit pricing is not the lowest in the market.
A second trend will be regional capacity alignment with electronics manufacturing growth. Demand concentration in Asia Pacific, North America, and Europe will encourage producers to consider localized supply footprints, strategic inventory placement, and closer technical collaboration with regional customers. Proximity can shorten qualification cycles, improve responsiveness to specification updates, and reduce logistics-related risk for highly sensitive materials. For investors, this suggests that capacity expansion decisions will increasingly be evaluated against regional demand visibility, regulatory maturity, and the ability to serve qualified customer pipelines rather than purely on broad global volume assumptions. Regional specialization may also encourage partnerships between precursor suppliers and equipment or process engineering firms, creating integrated value propositions around deposition performance and material reliability.
Worldwide Aluminum Alkyls Market
A third trend involves heightened scrutiny of supply chain resilience and upstream feedstock stability. Because synthesis depends on organoaluminum inputs and tightly controlled reactive chemistry, producers and buyers alike will likely place greater emphasis on sourcing transparency, contingency planning, and quality verification across the value chain. Companies that can mitigate feedstock disruption risks, maintain consistent purity through process optimization, and provide clear documentation for regulatory and quality audits will gain a structural advantage. At the same time, uncertainty remains around regulatory evolution, regional compliance divergence, and the potential for demand volatility if electronics cycles or catalyst demand patterns shift. These risks do not negate growth, but they reinforce the importance of flexible supply strategies and disciplined qualification processes.
Recommendations for Decision-Makers
For manufacturers, the priority should be reinforcing technical differentiation and operational reliability rather than competing primarily on volume or price. Investing in purity consistency, analytical verification, and clear grade definitions can strengthen qualification outcomes with electronic-grade customers. Equally important is building robust safety and logistics capability, since handling and transport compliance directly affects customer trust and total cost of ownership. Companies should also evaluate whether to deepen application support through technical documentation, recipe collaboration, and regional proximity to high-demand customers. Firms that align capacity decisions with verified demand pipelines and regional compliance readiness will be better positioned to capture value from the market's gradual shift toward safer precursors and tighter film specifications.
For investors, due diligence should focus on the durability of high-purity demand, the stability of upstream feedstock access, and the credibility of quality systems rather than on generic growth narratives. Indications of long-term supply agreements, qualified customer relationships, and investment in controlled synthesis and compliance infrastructure can signal stronger commercial resilience. Portfolio exposure may be more attractive where producers demonstrate regional alignment with electronics ecosystems or where distribution partners offer multi-product reach and flexible order structures. At the same time, risk assessment should account for regulatory complexity, concentration in a small number of buyers and suppliers, and sensitivity to electronics cycle fluctuations.
For procurement and sourcing leaders, the practical emphasis should be on qualification discipline, supply continuity, and total cost of ownership. Evaluating suppliers on purity consistency, batch traceability, packaging integrity, and transport compliance can reduce downstream risk in deposition and catalysis applications. Multi-source strategies, clear specification alignment, and technical collaboration with suppliers can improve resilience without sacrificing quality. Given the pace of change in precursor selection and process requirements, access to current market intelligence on grade definitions, application trends, and regional supply dynamics can support more informed sourcing decisions. The complete research report provides detailed segmentation, regional and application-specific data, and customized guidance for organizations seeking a deeper basis for strategic planning.
For detailed analysis of this topic, please visit the official page: Worldwide Aluminum Dimethyl Isopropoxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide X-ray Phosphor Market: Why 6.8% CAGR and Medical Imaging Redefine 2026 Growth
By pmarketresearch, 2026-09-18
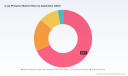
Global X-ray Phosphor Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview: Navigating Growth Amid Transformation
The worldwide market for X-ray phosphors has entered a phase of steady expansion, driven by the broader transition from analog film-based radiography to digital imaging ecosystems. Valued at approximately 565.4 million USD in 2020, the market reached an estimated 762.24 million USD by 2025. Projections indicate continued growth through the end of the decade, with revenues anticipated to approach 1.2 billion USD by 2032, supported by a compound annual growth rate of 6.8 percent. This trajectory reflects the ongoing modernization of diagnostic imaging infrastructure, the expansion of non-destructive testing requirements in advanced manufacturing, and the steady modernization of security screening systems at transportation and facility checkpoints.
Despite the favorable growth outlook, the industry is navigating several structural shifts that will define competitive positioning over the next several years. One of the most significant challenges lies in the materials transition between established phosphor chemistries and next-generation scintillator formulations. While certain rare-earth based phosphors have delivered substantial improvements in X-ray-to-light conversion efficiency, alternative columnar scintillator materials are gaining ground in applications demanding higher spatial resolution and faster readout speeds. Manufacturers and end-users must evaluate performance trade-offs, long-term reliability, and total cost of ownership rather than focusing solely on conversion efficiency metrics.
A second challenge centers on regulatory complexity and the pace of clinical and industrial adoption. Imaging devices that incorporate phosphor-based detectors increasingly require formal clearance processes, with regulatory bodies scrutinizing image enhancement algorithms, dose reduction claims, and equivalence to predicate systems. These requirements extend product development timelines and raise compliance costs, particularly for vendors introducing innovative scintillator architectures or hybrid detector designs. At the same time, procurement cycles in healthcare and industrial sectors are becoming more value-driven, with hospitals, service providers, and manufacturing firms demanding demonstrable improvements in workflow efficiency, durability, and lifecycle economics.
A third inflection point involves supply chain resilience and raw material availability. The production of high-performance phosphors depends on specialized rare-earth elements and precision coating or deposition processes. Geopolitical dynamics, export controls, and fluctuations in upstream material pricing can compress margins and create bottlenecks for downstream detector manufacturers. Companies that have relied on single-source procurement or limited regional supply networks are now reevaluating their sourcing strategies, inventory buffers, and qualification pathways to reduce exposure to disruption.
Key Drivers Shaping Market Direction
Several interconnected forces are accelerating demand for advanced phosphors and reshaping how value is created across the imaging value chain. Understanding these drivers is essential for manufacturers, investors, and procurement leaders who need to anticipate where demand will concentrate and which product attributes will command premium positioning.
Technological innovation remains the most visible catalyst. The push toward higher-resolution digital detectors, faster image acquisition, and dose-efficient imaging protocols has intensified the focus on scintillator performance. Conventional phosphor screens are being supplemented or replaced by structured scintillator layers that improve light guide efficiency and reduce blur, particularly in applications where fine detail matters. Flexible and conformable scintillator formats are also expanding design options for detectors used in non-standard form factors, enabling integration into portable systems, curved surfaces, and specialized industrial inspection setups. At the same time, advancements in phosphor powder morphology, particle size control, and substrate adhesion are improving uniformity and consistency across production batches, which is critical for high-volume medical and industrial manufacturing.
Policy and regulatory developments are reinforcing demand for dose-efficient and diagnostically reliable imaging solutions. Authorities and clinical institutions are increasingly prioritizing technologies that reduce patient exposure while maintaining image quality, especially in high-volume diagnostic settings and screening programs. This emphasis favors phosphors that improve conversion efficiency and support lower-dose protocols. Regulatory pathways for imaging devices continue to evolve, with clearance requirements extending beyond hardware performance to include software-driven image processing and system-level equivalence. For phosphor suppliers, this environment rewards established materials with well-characterized performance profiles as well as new formulations that can demonstrate clear benefits in validation and clearance processes.
Demand-side behavior is shifting as end-users adopt a more comprehensive view of imaging economics. In medical diagnostics, healthcare providers are balancing capital expenditure constraints with the need to expand imaging capacity, improve throughput, and support aging populations and chronic disease management. This has increased interest in detector technologies that integrate efficiently with existing digital workflows and reduce re-examination rates. In industrial non-destructive testing, the growth of advanced manufacturing, aerospace component verification, and infrastructure inspection is expanding the use of X-ray imaging for quality assurance. Meanwhile, security and screening applications continue to modernize as facilities seek faster throughput, improved material discrimination, and more adaptable screening architectures. Across these segments, buyers are prioritizing solutions that combine performance with robustness, serviceability, and predictable operating costs.
Supply chain and cost dynamics are also reshaping competitive dynamics. The cost structure of phosphor production is influenced by raw material availability, precision manufacturing requirements, and the cost of qualifying new materials for regulated applications. Firms that can stabilize input costs, maintain tight process control, and scale production without sacrificing performance gain an advantage in price-sensitive segments. Conversely, premium niches are emerging for specialized scintillators that deliver measurable gains in resolution, speed, or mechanical flexibility. This bifurcation is encouraging companies to segment their portfolios more deliberately, aligning product lines with distinct application requirements rather than competing on a single performance dimension.
Competitive Landscape and Leadership Strategies
The X-ray phosphor market is characterized by a mix of specialized scintillator producers, established imaging materials suppliers, and larger healthcare technology companies with deep integration into detector ecosystems. Competitive advantage is increasingly defined not only by material performance but also by the ability to support downstream customers through application engineering, qualification support, and supply reliability.
Scintacor has built a recognized position in phosphor-based scintillators and X-ray screens for medical imaging, with product families designed to balance brightness and resolution for radiography and digital systems. Its recent introduction of a high-brightness, flexible caesium iodide scintillator illustrates a broader industry move toward form factors that enable new detector designs and application flexibility. By expanding into flexible scintillator options, Scintacor is targeting use cases where traditional rigid screens are less suitable, including portable and specialized imaging configurations. This product direction signals how material suppliers are seeking growth beyond standard intensifying screen applications by addressing detector design constraints directly.
Rare Earth Phosphors Market
Mitsubishi Chemical Corporation continues to strengthen its presence through gadolinium oxysulfide-based scintillator screens used in medical diagnostics, baggage inspection, and industrial applications. Its emphasis on stability and cost performance reflects the importance of reliable operation in high-volume environments where downtime and replacement frequency directly affect total cost of ownership. In indirect conversion digital detectors, such phosphor technologies are valued for consistent long-term behavior, an attribute that can be as decisive as peak conversion efficiency for operators managing large installed bases.
Carestream Health offers rare-earth intensifying screens designed to convert X-ray energy into visible light more efficiently than conventional alternatives, supporting dose reduction in medical and industrial radiography. This value proposition aligns with the broader clinical and operational priority of achieving diagnostic quality while minimizing exposure and improving throughput. Agfa HealthCare brings historical depth in photostimulable storage phosphors and green-emitting intensifying screens, reinforcing the continued relevance of computed radiography pathways and specialized screen technologies in settings where digital detector upgrade cycles vary by region and facility type.
Hamamatsu Photonics contributes a broad portfolio of high-performance scintillators on diverse substrates, including fiber optic plates, amorphous carbon, and flexible sheet formats. This substrate breadth enables tailored solutions for medical and industrial detectors that require specific mechanical, optical, or geometric characteristics. Boston Applied Technologies focuses on phosphor powders for intensifying screens and imaging devices, supporting manufacturers that integrate phosphors into their own detector architectures. Niterra Materials, formerly Toshiba Materials, supplies sheet-type scintillators across multiple phosphor families, including gadolinium-based and barium-based formulations for medical and high-speed applications, underscoring the continued segmentation between general diagnostic use and speed-sensitive imaging requirements.
The competitive landscape is evolving along several axes. First, consolidation pressure is building as larger imaging technology providers seek to secure reliable phosphor supply and reduce qualification risk, while specialized manufacturers look to expand their application reach through product diversification. Second, differentiation is shifting from material-only competition to system-relevant performance, including flexibility, durability, substrate compatibility, and support for dose-efficient workflows. Third, new entrants and technology spin-offs are exploring niche opportunities in flexible scintillators, specialized phosphor formulations, and application-specific detector integration, particularly where existing solutions do not fully address form-factor or performance constraints. For incumbents, the strategic imperative is to combine material expertise with customer-facing engineering support and resilient supply operations. For newer players, the opportunity lies in solving clear design limitations that are difficult for broader portfolios to address quickly.
Forward Outlook: Trends and Commercial Implications
Over the next three to five years, the market is likely to be shaped by the continued migration toward dose-efficient, high-resolution digital imaging and by the broadening use of X-ray inspection beyond traditional medical settings. One key trend is the growing importance of scintillator architectures that balance resolution, brightness, and mechanical adaptability. As portable imaging, specialized industrial inspection, and non-standard detector geometries become more common, demand will increasingly reward phosphors that can be integrated into flexible or custom-form-factor devices without sacrificing consistent performance.
PW Consulting
A second trend is the rising emphasis on lifecycle value and regulatory readiness. End-users are expected to favor materials and detector configurations that simplify qualification, support stable long-term operation, and align with dose-reduction goals. This will strengthen the position of established phosphor families in high-volume applications while creating openings for differentiated products in segments where speed, flexibility, or resolution provide measurable operational benefits.
A third trend involves supply chain diversification and material risk management. Organizations that depend on concentrated sourcing for critical phosphor inputs will continue to explore multi-region procurement, alternative material pathways, and qualification strategies that reduce single-point vulnerability. The commercial opportunity here lies in providing customers with predictable availability, transparent quality documentation, and application support that accelerates integration and reduces time to deployment.
These trends also carry uncertainty. Regulatory requirements may become more demanding as imaging systems incorporate advanced enhancement functions and hybrid detection methods. Raw material costs and geopolitical factors could affect pricing stability. In addition, the pace of adoption for newer scintillator formats will depend on clinical and industrial validation, service infrastructure, and the willingness of end-users to modify established workflows. Companies that plan for these variables rather than assuming linear adoption will be better positioned to capture value.
Strategic Recommendations for Decision-Makers
Manufacturers should align product roadmaps with application-specific performance needs rather than competing solely on generic efficiency metrics. Prioritizing flexible or specialized scintillator options, strengthening substrate and coating process control, and investing in qualification support can differentiate offerings in both premium and volume segments. Building resilient sourcing and clear documentation for material consistency will also help reduce friction in regulated and high-volume deployment environments.
Investors should evaluate opportunities based on how well companies can connect material performance to downstream customer value, including workflow efficiency, dose management, and total cost of ownership. Attention to supply chain robustness, regulatory readiness, and the ability to serve both established and emerging application areas will be critical indicators of long-term competitiveness. Segments where phosphor design directly addresses a measurable detector limitation may offer particularly attractive differentiation potential.
X-ray Detectors Market
Procurement and operations leaders should look beyond unit price and assess the full performance and reliability profile of phosphor solutions. Prioritizing suppliers that can demonstrate stable quality, application engineering support, and practical pathways for integration will reduce implementation risk and improve long-term operating outcomes. As requirements vary widely across medical, industrial, and security applications, tailored evaluations that consider form factor, throughput, durability, and compliance alignment will yield better decisions than one-size-fits-all purchasing criteria.
For organizations seeking detailed segmentation data, regional breakdowns, and customized strategic recommendations, the full PW Consulting market study provides deeper analysis across product types, application areas, and competitive dynamics.
For detailed analysis of this topic, please visit the official page: Worldwide X-ray Phosphor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Gas-Insulated Transformers Market: Where 6.25% CAGR Meets Regional Shifts
By pmarketresearch, 2026-09-18
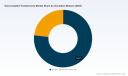
Navigating the Global Gas-Insulated Transformer Market: Strategic Trends & Commercial Opportunities
Market Overview & Core Challenges
The global gas-insulated transformer (GIT) market has demonstrated steady expansion over the past half-decade, with total revenue climbing from approximately USD 1.58 billion in 2020 to a projected USD 2.14 billion in 2025. Looking toward the end of the forecast window in 2032, market valuation is expected to approach USD 3.27 billion. This trajectory implies a compound annual growth rate of 6.25 percent from 2025 through 2032, signaling a market that is scaling at a pace driven by structural electrification needs rather than cyclical demand spikes. The consistency of this growth curve reflects a fundamental shift in how utilities, industrial operators, and urban planners approach high-voltage infrastructure, particularly in environments where spatial constraints, safety requirements, or atmospheric conditions make traditional air-insulated solutions impractical.
Despite the favorable headline trajectory, the sector faces three interconnected challenges that are reshaping investment decisions and product roadmaps. First, the environmental profile of sulfur hexafluoride (SF6) remains the most prominent friction point. Regulatory scrutiny has intensified across multiple jurisdictions, with updated reporting mandates in the United States requiring facilities meeting specific emission thresholds to disclose SF6 and perfluorocarbon emissions through the Greenhouse Gas Reporting Program, effective January 2025. This regulatory pivot moves away from nameplate capacity benchmarks toward actual emission volumes, placing greater compliance burdens on operators and manufacturers alike. Second, the supply chain for industrial-grade SF6 has experienced volatility, with global pricing averaging between USD 4 and 9 per kilogram and power-sector procurement hovering around USD 6.5 per kilogram. Cost variability, combined with tightening availability expectations, forces procurement teams to weigh insulation performance against long-term input cost exposure. Third, the market is navigating an accelerating transition toward alternative and green insulating gases, which introduces both engineering complexity and capital reallocation pressures. Manufacturers must balance proven SF6-based designs with next-generation formulations that meet safety and dielectric standards without compromising reliability or extending time-to-market.
These challenges do not threaten the market's expansion but rather redefine where value accrues. Companies that treat environmental compliance as a design parameter rather than a retrospective adjustment are positioning themselves to capture premium segments, while operators evaluating GIT procurement are increasingly factoring total cost of ownership, emission liability, and future-proofing into their specifications.
Key Drivers of Market Change
Technological innovation continues to act as a primary catalyst for GIT adoption, with engineering advances focusing on compact footprint, enhanced thermal management, and integrated grid compatibility. Urbanization and the densification of power networks have made space-constrained substations a defining requirement, pushing manufacturers to refine gas-insulated enclosures that deliver higher power density without sacrificing breakdown voltage or operational stability. Recent project deployments illustrate this trajectory: in June 2024, seven GIT units from Toshiba Energy Systems & Solutions entered commercial operation at the Haram 2 and Haram 3 substations serving Makkah, Saudi Arabia, where high-safety, non-flammable designs were prioritized for dense urban settings. This example underscores how performance requirements in congested environments are directly translating into procurement decisions, particularly when public safety and operational continuity are non-negotiable.
Worldwide Environmentally Friendly Gas Insulated Switchgear Market
Policy and regulatory dynamics are simultaneously reshaping the competitive landscape. The electrical transmission and distribution sector remains a significant contributor to SF6 emissions, with U.S. reporting indicating that roughly 67 percent of national SF6 emissions in 2022 originated from this segment. Such exposure has accelerated regulatory momentum and voluntary industry commitments aimed at reducing reliance on high-global-warming-potential gases. The result is a dual-track environment: established SF6-based systems continue to serve high-voltage applications where dielectric performance is paramount, while a growing cohort of buyers is evaluating SF6-free alternatives for specific voltage classes and deployment contexts. Regulatory shifts are therefore not simply compliance events; they are influencing product portfolios, R&D prioritization, and the relative attractiveness of different insulation mediums across the voltage spectrum.
Demand-side behavior is evolving as utilities and industrial operators reconsider lifecycle economics. The push toward grid modernization, increased integration of distributed generation, and the need for resilient transmission infrastructure are expanding the use cases for gas-insulated equipment beyond traditional utility deployments. Industrial facilities operating in harsh or confined environments are increasingly specifying GITs for their non-flammable characteristics and reduced maintenance footprints, while large-scale urban infrastructure projects favor compact designs that minimize civil works and land acquisition costs. This broadening demand base is creating cross-sector pull that reinforces volume growth even as individual procurement criteria diverge.
Supply chain and cost structures remain a critical variable. SF6 pricing fluctuations introduce margin sensitivity for manufacturers and total-cost uncertainty for buyers, particularly when insulation medium selection is tied to long-term service agreements or multi-year infrastructure programs. At the same time, the emergence of alternative gas formulations is altering cost calculus over the asset lifecycle. While some green alternatives may carry different procurement or processing considerations, they can reduce exposure to emissions-related reporting, potential future pricing penalties, and reputational risk. The interplay between raw material economics, regulatory exposure, and engineering trade-offs is becoming a central factor in both product design and procurement strategy.
Competitive Landscape & Leading Strategies
The market structure reflects a moderately concentrated field, with the top three participants accounting for approximately 55.5 percent of revenue and the top five representing roughly 72.8 percent. This concentration indicates that scale, technology depth, and global service networks confer meaningful advantages, yet it also leaves room for specialized players to compete on voltage range, regional presence, or application-specific engineering. Hitachi Energy, headquartered in Zurich, operates GIT offerings as part of broader high-voltage transmission solutions, emphasizing reliability, compact design for space-limited applications, and integration with grid infrastructure. The company has been actively expanding transformer manufacturing capacity, signaling a strategy centered on capturing volume growth while reinforcing supply assurance. Siemens Energy, based in Munich, positions its GIT portfolio within an integrated energy equipment framework, targeting efficient high-voltage transmission for utilities and industrial users. Its approach emphasizes system-level compatibility and operational efficiency across demanding service environments.
GE Vernova's Grid Solutions unit, located in Cambridge, Massachusetts, supplies GITs and related grid solutions with a focus on reliable power delivery in utility and high-demand sectors. Its competitive positioning leans on brand recognition, global project execution experience, and the ability to align transformer specifications with broader grid modernization initiatives. Mitsubishi Electric, headquartered in Tokyo, manufactures GITs with an emphasis on high-performance energy systems and has been advancing SF6-free alternatives for sustainable grid applications. This dual focus on performance and environmental alignment reflects a strategy that anticipates regulatory and buyer preferences without retreating from proven high-voltage capability. Toshiba Energy Systems & Solutions, also based in Tokyo, specializes in GITs engineered for challenging environments, offering non-flammable, high-safety designs up to 500 kV, and has demonstrated execution in dense urban substation projects. Its emphasis on safety-critical design differentiates its offering in applications where public proximity and operational risk are primary concerns.
Beyond these larger players, the competitive field includes strong regional and application-focused contributors. Hyundai Electric, based in South Korea, produces gas-insulated equipment optimized for compact installation and high reliability in transmission and distribution networks. Arteche Group, headquartered in Spain, supplies gas-insulated voltage and instrument transformers for GIS substations up to 525 kV, concentrating on measurement, protection, and auxiliary services within shielded environments. Fuji Electric, also in Tokyo, offers gas-insulated switchgear and related transformer technologies with modular, compact designs for high-voltage applications. Hyosung Heavy Industries, another South Korean participant, provides GITs within its power equipment lineup, emphasizing reliability and environmental considerations in energy systems. Meidensha Corporation, based in Tokyo, manufactures GITs for power transmission and distribution, supporting utility and industrial sectors with application-tailored solutions.
PW Consulting
The competitive dynamics are evolving along two axes. On one hand, scale players are investing in capacity and system integration to secure share in large transmission and urban substation programs, effectively competing on delivery certainty, global reach, and portfolio breadth. On the other hand, differentiation is increasingly tied to insulation medium strategy, safety credentials, and modularity. Companies that can offer SF6-free or low-emission options without compromising dielectric performance are opening new discussion points with procurement teams sensitive to compliance and lifecycle emissions. At the same time, specialized manufacturers are carving out positions in high-voltage niche applications, measurement and protection ecosystems, and modular deployments that reduce installation complexity. The net effect is a landscape where consolidation pressure exists at the top, but segmentation by voltage class, insulation approach, and geographic execution capability continues to create targeted opportunities.
Forward-Looking Trends & Commercial Opportunities
Over the next three to five years, the GIT market is likely to be shaped by three interrelated trends. The first is the broadening commercialization of alternative and green insulating gases across select voltage classes. As engineering validation deepens and standardization efforts advance, a wider set of projects will evaluate SF6-free options, particularly where regulatory exposure, procurement policies, or sustainability commitments influence specification decisions. For manufacturers, this creates an opportunity to lead with differentiated product lines, secure early reference projects, and build expertise that becomes a barrier to entry for slower-moving competitors. For buyers, it introduces more choice in balancing dielectric performance, emissions profile, and long-term compliance risk.
The second trend is the continued intensifying of urban and space-constrained deployments. As cities expand electrical capacity to support economic growth, electrification of transport and industry, and resilience requirements, compact gas-insulated solutions will remain highly relevant. This trend favors suppliers that can deliver high power density, rapid installation, and safety-oriented designs, while also creating opportunities for modular and repeatable substation configurations that reduce civil engineering overhead. Projects in high-density environments will increasingly reward proven safety credentials and localized execution capability, making track record and site-specific engineering critical differentiators.
The third trend involves regulatory and reporting frameworks becoming more operationalized. Updates such as the U.S. EPA Greenhouse Gas Reporting Program shift toward emission-volume thresholds will expand visibility into SF6 usage and leakage across the transmission and distribution sector. This increased transparency is likely to sharpen buyer focus on leak prevention, service practices, and end-of-life handling, while also accelerating preference for designs that reduce emission exposure over the asset's life. Commercial opportunities will emerge for suppliers that integrate monitoring, maintenance, and decommissioning considerations into their value proposition, and for buyers who align procurement with emission-management roadmaps rather than treating compliance as a separate function.
Potential risks and uncertainties should be acknowledged. Alternative gas technologies may face varying acceptance curves across regions and voltage classes, and performance validation in extreme conditions can extend adoption timelines. Cost dynamics for both SF6 and newer insulation mediums may fluctuate with industrial demand, logistics constraints, and regulatory interventions, complicating long-term budgeting. In addition, supply chain capacity expansions by major vendors could alter lead-time expectations and negotiate leverage for large programs, while localized content expectations in certain markets may affect sourcing strategies. These variables do not invalidate the growth outlook but do require scenario-aware planning.
Strategic Recommendations for Decision-Makers
For manufacturers and technology providers, the priority is to align product development with the dual demands of performance and environmental alignment. Investing in SF6-free or low-emission alternatives should be paired with rigorous validation across target voltage classes and environments, so that differentiation is grounded in proven reliability rather than aspirational claims. At the same time, capacity and supply chain planning should account for the possibility that procurement teams will increasingly weigh insulation medium choice alongside delivery certainty, service coverage, and total cost of ownership. Companies that can articulate a clear roadmap across insulation mediums, voltage segments, and deployment contexts will be better positioned to participate in both legacy SF6 programs and next-generation specifications.
Cast Resin Transformers Market
For investors evaluating exposure to this market, the relevant question is not whether growth will continue, but where value will concentrate. Interest should focus on participants with credible insulation-medium strategies, demonstrated execution in safety-critical or space-constrained projects, and the ability to serve multiple voltage classes without over-reliance on a single regional market. Portfolio considerations should also include exposure to service, retrofit, and lifecycle management capabilities, since reporting and emission-management expectations are likely to increase the commercial importance of long-term support relationships. Monitoring regulatory developments and raw material cost trends will remain essential for timing commitments and assessing margin resilience.
For procurement and infrastructure planners, the operative need is to broaden evaluation criteria beyond initial unit cost. Specifications should incorporate insulation medium implications, emission reporting exposure, safety requirements for the deployment environment, and compatibility with grid integration plans. Where projects are long-lived, scenario planning around alternative gases and regulatory evolution can reduce future rework risk and provide negotiating leverage. Early engagement with suppliers that offer modular designs, strong safety credentials, and clear service frameworks can improve delivery predictability and reduce lifecycle friction, particularly in dense urban or high-reliability settings.
For stakeholders seeking a more detailed view of segmentation dynamics, regional nuance, voltage-class outlooks, insulation-medium splits, and company-specific positioning, a comprehensive research report provides the depth required to translate these strategic themes into procurement specifications, investment theses, and product planning decisions. Detailed breakdowns of market size paths, competitive benchmarks, and scenario analysis can support more precise go-to-market and sourcing choices across the forecast horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Gas-insulated Transformers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Passenger Vehicle Window Regulator Market: The 5.71% CAGR Shift
By pmarketresearch, 2026-09-18
Strategic Shifts and Commercial Opportunities in the Global Passenger Vehicle Window Regulator Mechanism Market
Market Current State and Core Challenges
The global market for passenger vehicle window regulator mechanisms continues to demonstrate steady expansion, reflecting broader trends in automotive manufacturing and consumer preferences. From 2020 to 2025, the market grew from approximately USD 11,250 million to USD 14,854 million, establishing a solid foundation for the projection period of 2026 through 2032. Forecasts indicate a compound annual growth rate of 5.71 percent, which suggests that the sector will sustain momentum despite macroeconomic fluctuations and periodic supply chain disruptions. This trajectory is not merely a function of rising vehicle production volumes but also signals a structural transition in how window regulators are designed, integrated, and valued within the passenger vehicle ecosystem.
As the market approaches the mid-twenties, several inflection points are reshaping competitive dynamics and forcing suppliers to reconsider their operational and strategic postures. The first critical challenge lies in balancing cost efficiency with escalating performance expectations. Traditional mechanical and cable-driven mechanisms are being pressured by demands for smoother operation, faster response times, and seamless integration into increasingly complex door assemblies. Suppliers that fail to upgrade their manufacturing processes or redesign components for scalability risk margin erosion as OEMs push for unit cost reductions while maintaining or improving quality thresholds.
A second major challenge stems from the tightening regulatory environment across key automotive markets. Safety mandates now require anti-pinch technology, electronic monitoring, and one-touch operation features as standard elements in power window systems. These requirements impose additional design complexity, testing burdens, and component costs. Companies that rely on legacy mechanical designs without electronic integration face a widening gap between regulatory compliance and market expectations. The transition toward electronic controls also demands changes in talent acquisition, validation protocols, and supplier qualification processes, which can strain organizations that are not prepared for this shift.
The third challenge is the growing importance of lightweighting and material substitution. Weight reduction has become a strategic priority for OEMs seeking to improve fuel efficiency and support emissions targets, particularly as electrification gains traction across multiple vehicle segments. This trend places pressure on component suppliers to replace conventional steel-based structures with aluminum or engineering plastics. However, raw material price volatility introduces uncertainty into manufacturing margins, and switching materials requires extensive revalidation, tooling investment, and long-term supplier agreements. Navigating this transition requires disciplined execution rather than reactive adjustments.
At the same time, integration is accelerating. Window regulators are no longer viewed as isolated components but as modules embedded within broader door systems that include motors, wiring harnesses, and electronic control functions. This shift simplifies OEM assembly, reduces overall vehicle weight, and creates new opportunities for differentiation. Suppliers that can deliver fully integrated, validated door closure solutions are gaining a structural advantage, while those competing solely on standalone component pricing are seeing their strategic relevance diminish.
Key Drivers Analysis
Technological Innovation and Intelligent Integration
One of the most significant forces shaping the market is the evolution from purely mechanical window regulators to intelligent, electronically controlled systems. Anti-pinch functionality, automatic window positioning, and personalized settings are increasingly expected by consumers, particularly in mid-to-premium vehicle segments. The push toward digitized comfort features has encouraged suppliers to embed sensors, control logic, and communication interfaces directly into window mechanisms. A notable example of this direction is the debut of an intelligent window regulator featuring electrification, personalized light dimming, and privacy settings, which was introduced for global rollout following a China-focused initiative. Such developments signal that window regulators are becoming part of a broader user experience narrative rather than remaining purely functional hardware.
Beyond comfort, integration into complete door modules has emerged as a powerful design driver. Combining motors, regulators, wiring, and electronic components into unified assemblies reduces the number of discrete parts, streamlines OEM assembly, and supports weight reduction goals. Suppliers that have invested in modular architectures and door-level integration capabilities are better positioned to win long-term OEM contracts, especially as vehicle architectures move toward more consolidated and software-defined approaches.
Policy and Regulatory Influence
Regulatory requirements continue to exert a strong influence on product design and market adoption. Mandatory anti-pinch technology and one-touch operation standards across North America, Europe, and other major markets have effectively shifted the baseline for power window systems. These regulations are not static; they continue to evolve, and manufacturers must anticipate future revisions related to child safety, electronic validation, and system reliability. Compliance is no longer optional, and companies that treat safety as a minimum requirement rather than a design foundation risk losing credibility with OEMs that are under increasing scrutiny from regulators and consumers alike.
Safety-driven requirements also create a feedback loop with technology development. The need to meet anti-pinch standards has accelerated investment in electronic controls, motor controllers, and sensor-based feedback loops. This, in turn, raises the barrier to entry for low-complexity, low-cost players and reinforces the position of suppliers with stronger engineering capabilities and established validation processes.
Demand-Side Behavior and Electrification
Consumer expectations are changing the value proposition of window regulators. In many markets, power windows and associated comfort features are no longer premium add-ons but baseline expectations for a wide range of passenger vehicles. As consumers become accustomed to smooth, quiet, and responsive window operation, automakers face mounting pressure to maintain consistent quality across model lines. This is especially relevant in emerging and mid-tier segments, where cost constraints must be balanced with feature parity.
Electrification adds another layer of demand-side influence. As vehicle platforms shift toward electric architectures, weight and energy efficiency considerations become more pronounced. While window regulators are individually low-load components, their cumulative contribution to vehicle mass matters in the context of battery range optimization. This reinforces the push toward lightweight designs and materials that can deliver durability without adding unnecessary weight. Demand is therefore being shaped not only by comfort expectations but also by the broader efficiency logic of modern vehicle design.
Supply Chain and Cost Structure Dynamics
Material composition and pricing volatility form another critical driver influencing margins and sourcing strategies. Window regulators primarily rely on steel for durability in high-stress applications, yet there is growing adoption of aluminum and engineering plastics to reduce weight and meet efficiency targets. This creates a dual pressure: suppliers must manage the cost implications of raw material fluctuations while also investing in material innovation and manufacturing flexibility.
Worldwide Automotive Stabilizer Bar Link Market
Price volatility in steel, aluminum, and plastics can quickly compress margins for components that depend heavily on these inputs, especially for cable, scissor, and frame structures. Companies that maintain rigid cost models or single-source procurement strategies risk exposure when input prices move unexpectedly. In contrast, suppliers that diversify materials, negotiate flexible contracts, and incorporate value engineering into their design cycles are better able to protect profitability. The transition toward new materials also requires reevaluation of production lines, testing protocols, and supplier relationships, which can be both an operational burden and a competitive differentiator.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a concentrated group of established players alongside a broad set of specialized suppliers that compete on niche capabilities, regional strength, or customization. The market structure reflects meaningful concentration at the top, with leading firms holding substantial shares of global demand. This concentration indicates that scale, engineering depth, and long-term OEM relationships remain powerful advantages in a market where validation cycles are long and switching costs can be high.
Brose Fahrzeugteile SE & Co. KG stands out for its focus on mechatronic door systems and intelligent window regulator functions. Its recent activities illustrate a dual strategy of product innovation and regional expansion. The debut of an intelligent window regulator with electrification, personalized light dimming, and privacy settings was positioned for global rollout following a China-oriented initiative. In parallel, the company showcased door and window regulator solutions under a theme emphasizing experience and modular design, while highlighting three decades of development in China. This approach reflects an effort to combine advanced functionality with localized presence and modular architectures that can be adapted across programs.
Valeo SA offers OE-quality window regulator mechanisms, including Bowden and cable types, with comfort functions and anti-pinch features for passenger cars and light commercial vehicles. Its strength lies in broad coverage of European and global manufacturers, which provides scale and the ability to respond to varied OEM requirements. The emphasis on comfort functions and anti-pinch integration aligns well with regulatory demands and consumer expectations, supporting a position based on proven compliance and wide application coverage.
Automotive Power Window Motor Market
HI-LEX Corporation has built a strong production footprint, manufacturing more than ten million window regulators annually using in-house molded components. This vertical approach supports reliability and cost efficiency, giving the company a durable edge in passenger vehicle applications where consistency and unit economics matter. The scale of output also implies a level of manufacturing maturity that can be attractive to OEMs seeking dependable supply continuity.
Magna International Inc., through its closures business, focuses on window regulators and integrated closure systems with an emphasis on lightweight design and complete door modules. This integration-oriented strategy matches the broader industry direction toward simplified assembly and weight reduction. By offering door-level solutions rather than standalone parts, Magna positions itself to capture more value from system-level requirements and to participate in early design discussions with OEMs.
Grupo Antolin Irausa S.A. provides window regulator mechanisms within interior and closure systems for passenger cars, emphasizing smart and lightweight solutions. This positioning reflects the growing expectation that window regulators must contribute to overall vehicle comfort, packaging efficiency, and mass optimization. Companies that treat window regulation as part of a broader interior and closure strategy can generate more integrated value propositions for customers.
Several Japanese suppliers, including Aisin Corporation, Shiroki Corporation, Denso Corporation, and others, continue to play important roles in power window regulators, lift motors, and associated components. Their strengths often lie in manufacturing discipline, application breadth across Asian, domestic, and European programs, and established relationships with major automakers. Robert Bosch GmbH contributes to the ecosystem through window lift motors and regulator components embedded in power window systems, often for premium OEM models. This reinforces the value of motor and electronic integration capabilities as a strategic differentiator.
Smaller and more specialized participants also shape the market in distinctive ways. MarchantCain Automotive designs and manufactures custom window regulators for mid- and low-volume passenger vehicle manufacturers, offering flexibility that can be attractive for niche or specialty applications. Politecnica 80 manufactures electrical window regulators and lifter kits across a broad model range for passenger cars, commercial vehicles, and industrial vehicles, with a large share of components produced in Italy. Han Yale, an IATF 16949-certified manufacturer, focuses on aftermarket and OE-style regulators and motors with a wide SKU coverage for major passenger vehicle brands. These players illustrate that while scale matters, there remain viable paths based on customization, regional sourcing, and aftermarket breadth.
The competitive landscape is evolving along several axes. Integration and module-level supply are becoming more important, favoring suppliers that can deliver door-ready solutions rather than isolated components. At the same time, regional dynamics matter: strong local presence can support faster responsiveness, program alignment, and cost competitiveness, especially in markets where OEMs prioritize sourcing flexibility. Market concentration at the top indicates that leadership is increasingly tied to engineering sophistication, compliance capability, and integration expertise, while fragmentation persists in specialized niches, aftermarket channels, and lower-volume applications.
Future Trends Forecast
Looking ahead to the next three to five years, several trends are likely to define the direction of the market. The first is the continued shift toward intelligent window regulation functions. As consumer expectations around comfort, privacy, and personalization rise, window mechanisms will increasingly incorporate electronic controls, customizable settings, and interaction with broader vehicle systems. This opens opportunities for suppliers that can deliver not only reliable mechanical performance but also software-compatible, function-rich solutions that support differentiated cabin experiences.
The second trend is the acceleration of lightweighting through material innovation and module integration. As efficiency targets tighten and electrified platforms expand, the incentive to reduce component mass will remain strong. Adoption of aluminum and engineering plastics is expected to grow where durability and cost allow, and suppliers capable of validated material transitions will benefit. Integration into door modules will also deepen, since consolidated assemblies can reduce part counts, simplify assembly, and support weight and packaging goals simultaneously.
The third trend involves ongoing regulatory pressure and standardization of safety features. Anti-pinch technology, one-touch operation, and related electronic controls are likely to remain baseline requirements across major markets, and future updates may impose additional validation or functional expectations. The commercial opportunity here lies in making compliance a source of competitive advantage rather than a cost burden. Suppliers that design for reliability, test thoroughly, and demonstrate consistent performance can use safety capability as a trust signal to OEMs.
Potential risks and uncertainties should not be overlooked. Raw material price volatility can compress margins if not managed proactively. The transition to new materials and integrated architectures may require significant investment and revalidation, creating execution risk for some players. There is also the risk that cost pressures from OEMs could limit pricing flexibility, particularly in high-volume segments. Finally, regional trade dynamics and supply chain disruptions could affect sourcing strategies, lead times, and inventory planning, making resilience a key capability for the forecast period.
Actionable Insights for Decision Makers
For manufacturers, the priority is to strengthen integration capabilities and electronic expertise. Investment in anti-pinch technology, door module integration, and lightweight material strategies should be assessed against near-term program pipelines and long-term platform roadmaps. Companies that can demonstrate modular, validated, and weight-efficient solutions will be better positioned to secure OEM commitments and defend margins in a competitive environment. At the same time, supply chain flexibility around materials and supplier diversification should be treated as a strategic safeguard rather than a tactical concern.
For investors, due diligence should focus on companies with proven compliance capabilities, scalable manufacturing, and a clear route to intelligent, integrated solutions. Scale and concentration at the top of the market suggest that durable advantages will accrue to firms that combine engineering depth with regional reach and application breadth. It is also worth evaluating exposure to material volatility and the ability to transition to aluminum or engineering plastics without sacrificing quality or profitability. Companies that can balance cost discipline with product sophistication are likely to generate more resilient value over the forecast period.
PW Consulting
For procurement and sourcing teams, the strategic emphasis should be on partnering with suppliers that can support integration, validation, and material flexibility rather than selecting solely on unit price. As window regulators increasingly become part of broader door systems, the cost of poor integration, rework, or compliance gaps can outweigh apparent savings. Building relationships with suppliers that offer modular designs, strong safety credentials, and reliable production capacity can reduce downstream risk and improve program execution. Given the speed of technological and regulatory change, access to current, segmented market intelligence can help teams anticipate shifts in demand, pricing, and competitive positioning before they affect sourcing decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Passenger Vehicle Window Regulator Mechanism Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Circuit Breakers for New Energy Power Generation: The 8.25% CAGR Redefining Market Dynamics
By pmarketresearch, 2026-09-18
Circuit Breakers for New Energy Power Generation: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The global market for circuit breakers dedicated to new energy power generation has entered a period of accelerated, structurally driven expansion. Valued at approximately $2.05 billion in 2020, the market crossed the $3.1 billion threshold by 2025, reflecting a compound annual growth rate of 8.25 percent through 2032. By the end of the forecast horizon, total market revenue is projected to surpass $5.4 billion. This trajectory is not merely a reflection of broader renewable capacity additions; it signals a fundamental shift in how electrical protection systems are specified, engineered, and integrated into modern power generation architectures.
Despite the robust expansion, the sector faces several structural inflection points that will dictate competitive outcomes over the next half-decade. First, the transition toward inverter-based and DC-coupled generation assets is outpacing legacy protection paradigms. Traditional alternating-current circuit breaker frameworks, while mature, are increasingly mismatched with the fault behavior, response timing, and interconnection requirements of solar arrays, wind farms, and battery energy storage systems. Engineers and project developers must navigate a fragmented standards landscape while balancing reliability, switching speed, and system efficiency.
Second, material cost volatility has introduced sustained pressure on manufacturing margins and pricing predictability. The surge in industrial metal benchmarks during early 2026, including sharp year-over-year increases in copper, aluminum, and steel mill products, directly translates into higher input costs for wiring, contact assemblies, and structural housings. Suppliers that lack agile procurement frameworks or pricing pass-through mechanisms are facing compressed profitability, particularly in mid-voltage segment where competition remains intense.
Third, regulatory recalibration in key demand regions is reshaping project economics and procurement timelines. In the United States, recent legislative adjustments have altered the incentive architecture for solar and wind deployments, tightening placed-in-service requirements and expanding foreign entity restrictions. These changes do not eliminate demand, but they compress development windows, shift procurement toward compliant supply chains, and elevate the importance of equipment that can accelerate interconnection approvals and reduce commissioning risk.
Key Drivers Shaping Market Dynamics
Technological Innovation and Protection Architecture Evolution
The most consequential force reshaping the market is the rapid evolution of protection technologies tailored to new energy topologies. Manufacturers are moving beyond incremental improvements in interrupting capacity and are rearchitecting breakers for hybrid AC/DC environments, high-frequency inverter interfaces, and modular storage configurations. Vacuum-based solutions continue to dominate where high reliability and minimal maintenance are priorities, while air-blast and specialized contact designs are being optimized for higher current ratings and faster arc extinguishment in wind and utility-scale solar applications.
PW Consulting Chemical & Energy Research Center
A notable shift is the accelerated development of DC-rated and hybrid-switching solutions. Collaborative engineering efforts between major equipment suppliers are producing specification frameworks for multi-terminal high-voltage direct current systems, directly enabling large-scale renewable integration and offshore wind aggregation. These initiatives are not isolated R&D exercises; they are translating into commercially viable product roadmaps that address the unique fault currents and commutation challenges inherent to DC-coupled generation and storage assets.
Policy, Regulation, and Grid Modernization Mandates
Regulatory frameworks and grid code requirements are acting as powerful demand amplifiers, particularly where transmission constraints and interconnection backlogs are pressing policymakers to streamline approvals. Regions that have tied renewable portfolio standards or clean energy targets to grid readiness are seeing heightened specification requirements for protection equipment that can satisfy both utility compliance and fast-response operational profiles.
At the same time, environmental and emission-related expectations are influencing technology selection. The broader industry movement toward reducing reliance on high-global-warming-potential gases has spurred the commercial introduction of SF6-free breaker families and alternative insulating media. Utilities and developers increasingly factor sustainability credentials into procurement decisions, especially for public-sector tenders and projects with corporate offtake commitments that require alignment with decarbonization goals.
DC Circuit Breaker Market
Demand-Side Shifts and Application Diversification
On the demand side, the convergence of generation and storage is altering specification patterns. Solar installations continue to drive substantial volume, but wind power and energy storage systems are expanding the addressable base for specialized protection components. Storage deployments, in particular, introduce bidirectional power flow, rapid cycling, and hybrid AC/DC interfaces that require breakers capable of handling diverse operational modes without compromising safety or service life.
Corporate procurement behavior is also evolving. Developers and independent power producers are prioritizing equipment that reduces integration complexity, supports remote monitoring, and minimizes field commissioning time. This has elevated the value of digitally enabled interfaces and modular designs that can be scaled across project portfolios, from distributed solar to utility-scale hybrid plants.
Supply Chain Reconfiguration and Cost Structure Pressures
Supply chain dynamics remain a critical driver of both risk and opportunity. The recent spike in base metal prices has rippled through component manufacturing, affecting everything from conductive elements to mechanical assemblies. Suppliers that operate with vertically integrated production, long-term raw material contracts, or diversified sourcing networks are better positioned to stabilize output costs. Conversely, reliance on spot-market procurement is exposing manufacturers to margin erosion and delivery uncertainty.
Simultaneously, geopolitical and compliance considerations are reshaping sourcing strategies for North American and European projects. Equipment that aligns with localization expectations, transparent supply chain documentation, and evolving foreign entity restrictions is gaining preference in tenders where project financing and permitting depend on demonstrable compliance. This dynamic is encouraging both incumbent suppliers and regional manufacturers to reinforce domestic or nearshore production capabilities.
Worldwide Classified Circuit Breaker Market
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a moderately concentrated field of global incumbents, specialized regional players, and emerging niche suppliers. The top three competitors collectively account for slightly more than one-third of market revenue, while the top five approach just above half, leaving substantial room for differentiated positioning and regional share gains. This structure favors players that can combine scale, technical specialization, and responsive localization rather than those competing solely on price.
Strategic Positioning and Differentiation Levers
Leading participants are pursuing distinct differentiation pathways. Global manufacturers with broad switchgear portfolios are emphasizing high-current ratings, generator-protection specialization, and end-to-end integration for renewable and gas-based generation assets. Recent product launches targeting next-generation wind turbines and refurbished power plants illustrate a strategy centered on expanding the operational envelope of breaker families, enabling them to serve both new capacity and modernization programs.
A second group is concentrating on sustainability-driven innovation and grid-modernization alignment. Suppliers offering SF6-free interrupting technologies, digitalized medium-voltage switchgear, and IoT-enabled protection devices are positioning their products as enablers of lower-emission operations and predictive maintenance workflows. These offerings resonate with utilities and developers seeking to meet environmental targets while improving asset visibility across distributed portfolios.
A third cohort, often originating in Asia, is focusing on application-specific DC protection, solar PV interfaces, and battery energy storage compatibility. These companies have built credibility around specialized photovoltaic DC switchgear and storage-oriented protection components, frequently competing on application fit, cost efficiency, and rapid adaptation to regional project requirements. Their growth reflects the broader shift toward distributed and hybrid installations where tailored protection solutions can command premium positioning.
Market Evolution: Consolidation, Specialization, and New Entrants
The landscape is evolving along two parallel tracks. Large incumbents are deepening their capabilities through collaboration and targeted product expansion, pairing AC protection expertise with DC switching development to address transmission-scale renewable integration. These partnerships are accelerating specification maturity for multi-terminal systems and creating cross-licensing opportunities that broaden technology access without requiring every player to build every capability internally.
At the same time, market fragmentation persists at the application and regional levels. New and expanding entrants are carving out positions in solar DC protection, storage switchgear, and medium-voltage solutions for renewable facilities. This specialization creates a dynamic environment where incumbents must defend broad-platform advantages while remaining responsive to niche demands that can rapidly scale into significant volume pools. The net effect is a market in which success depends on balancing portfolio breadth with deep application engineering, localized supply resilience, and the ability to align product roadmaps with evolving grid codes and procurement criteria.
Future Outlook for 2027 to 2032
Over the next three to five years, the market is likely to be shaped by three interlocking trends. First, DC and hybrid protection architectures will move from emerging to mainstream in a growing share of solar-plus-storage and offshore wind projects. As inverter-based resources and storage systems become more tightly integrated, demand for breakers designed for bidirectional flow, fast fault response, and DC commutation will expand beyond specialized deployments into broader project specifications. Commercial opportunities will accrue to suppliers that can offer tested, code-aligned DC solutions with clear interoperability pathways and field-service support.
Second, sustainability requirements and digital integration will increasingly function as procurement gatekeepers rather than optional enhancements. SF6-free product lines, lower-emission manufacturing practices, and connected protection devices capable of remote diagnostics will become standard expectations in utility tenders and corporate-backed developments. This creates opportunities for suppliers to bundle hardware with service-oriented value propositions, including monitoring platforms, predictive maintenance tools, and lifecycle support contracts that improve total-cost-of-ownership outcomes.
Third, regional supply realignment will continue as project developers navigate incentive uncertainty, interconnection delays, and compliance requirements. Markets with strong renewable deployment pipelines but challenged transmission timelines will favor equipment that accelerates commissioning, reduces interconnection risk, and aligns with localization expectations. Suppliers that can demonstrate reliable delivery, documentation transparency, and adaptability to shifting regulatory parameters will be better positioned to capture share, particularly where project economics are sensitive to schedule compression.
The principal uncertainties tempering this outlook include ongoing raw material price swings, the pace at which DC protection standards mature across jurisdictions, and the potential for incentive recalibration to alter project pipelines in key regions. These variables do not negate long-term growth, but they reward flexibility. Companies that can adjust product mix, secure resilient input channels, and align engineering roadmaps with evolving grid and regulatory conditions will be best equipped to convert market expansion into durable commercial gains.
Strategic Implications for Decision Makers
For manufacturers, the priority is to align product roadmaps with the convergence of DC integration, sustainability expectations, and digital service demands. Developing modular, application-specific protection platforms and pairing them with monitoring or maintenance capabilities can differentiate offerings in a market where hardware specifications are increasingly table stakes. Equally important is securing supply chain resilience through diversified sourcing, long-term material contracts, or localized production to mitigate input-cost volatility.
For investors, the opportunity lies in identifying companies with clear technological adjacencies, particularly those bridging AC protection expertise with DC switching development or those expanding into storage and hybrid plant interfaces. Suppliers with strong application engineering, credible sustainability roadmaps, and the ability to serve both utility-scale and distributed segments offer broader exposure to the structural growth trajectory. Attention to regional compliance readiness and supply chain transparency will be critical when evaluating near-term scalability.
For procurement teams and project developers, equipment selection should extend beyond interrupting ratings and price. Evaluating compatibility with DC-coupled architectures, SF6-free options, digital integration capabilities, and supplier localization profiles can reduce interconnection risk, accelerate commissioning, and support long-term sustainability commitments. In an environment where project timelines and regulatory parameters are shifting, partnering with suppliers that offer specification flexibility and reliable delivery can materially improve project outcomes.
Detailed segmentation data, regional volume breakdowns, company-level positioning maps, and scenario-based forecasts are available in the full research report for teams that require granular inputs for portfolio planning, investment evaluation, or procurement strategy.
For detailed analysis of this topic, please visit the official page: Circuit Breakers for New Energy Power Generation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Meat Membrane Skinner Market: How 4.85% CAGR and Europe’s 186M Share Reshape Meat Processing Strategy
By pmarketresearch, 2026-09-18
Navigating the Global Meat Membrane Skinner Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The worldwide meat membrane skinner market is undergoing a measured but meaningful transformation, characterized by steady expansion and evolving processing requirements. Valued at approximately USD 418.4 million in 2020, the market has grown consistently to reach USD 532.5 million in 2025. The trajectory reflects a compound annual growth rate of 4.85 percent across the 2026-2032 forecast period, with revenue projected to approach USD 741.8 million by 2032. This expansion is not accidental; it is the result of sustained capital investment in meat processing infrastructure, shifting operational priorities among processors, and the gradual replacement of labor-intensive manual methods with mechanized solutions that deliver higher yield consistency.
Despite the favorable growth baseline, the industry stands at an inflection point shaped by several structural challenges. Labor availability and cost remain perennial pressures. Many processing facilities operate with lean staffing models, and the physical demands of membrane removal have made manual and semi-automatic approaches increasingly difficult to scale without compromising throughput or worker safety. At the same time, yield optimization has become a critical margin lever. Membrane skinning directly affects usable meat recovery, and even marginal improvements in precision translate into meaningful cost savings across high-volume operations. Processors are therefore seeking equipment that balances throughput with minimal product damage and reduced post-processing intervention.
A second challenge lies in the divergence between regional operating environments. Mature markets in Europe and North America are characterized by established hygiene frameworks, high automation expectations, and processors that prioritize integration with broader line architectures. Growth markets in Asia Pacific, Latin America, and the Middle East and Africa present different dynamics, including varying capital intensity, different facility scales, and more diverse product mixes. Equipment suppliers must navigate these differences without oversimplifying their offerings, as a solution that performs well in a highly automated European plant may not align with the operational realities of a developing processing hub.
The third challenge is material and compliance sensitivity. Food-grade processing equipment increasingly demands corrosion-resistant construction, straightforward sanitation, and designs that minimize contamination risk. Stainless steel has become the default material for membrane skinners, and this requirement ties equipment procurement to broader raw material dynamics. Fluctuations in stainless steel supply, pricing, and lead times can influence both equipment cost structures and project timelines. For processors planning capacity expansions or replacement cycles, these inputs add a layer of uncertainty that must be managed alongside equipment performance requirements.
Taken together, these challenges are reshaping purchasing behavior. The market is moving away from isolated machine purchases toward solutions that support line efficiency, sanitation efficiency, and consistent yield outcomes. Companies that can demonstrate reliable performance across these dimensions are positioned to capture a larger share of processing budgets, while those that fail to address the practical constraints of modern facilities risk being sidelined in competitive 입찰 and replacement cycles.
Key Growth Drivers: Technology, Regulation, Demand, and Cost Structure
Technological innovation is the most visible driver of market momentum. The membrane skinning segment has benefited from incremental improvements in blade geometry, feed mechanisms, and control logic that enable more consistent removal of silver skin and connective tissue while preserving underlying muscle. Automatic membrane skinners now represent a substantial share of market revenue, reflecting an industry-wide shift toward equipment that reduces manual handling and supports repeatable output. Open-top and compact models have expanded the addressable range for small-to-medium processors, while higher-capacity systems continue to serve large-scale beef and pork operations. The emphasis has moved beyond simple mechanization toward precision, yield retention, and ease of integration into existing lines.
Regulatory and hygiene expectations reinforce this technological trajectory. Food safety standards and sanitation requirements effectively shape equipment design, favoring stainless steel construction, accessible cleaning surfaces, and configurations that reduce product accumulation in hard-to-reach areas. These requirements are not merely compliance checkboxes; they influence total cost of ownership by affecting changeover time, sanitation labor, and downtime. Equipment that supports faster cleaning cycles and more predictable hygiene performance is increasingly favored in procurement evaluations, especially in facilities where throughput targets leave little margin for extended downtime.
On the demand side, processor behavior is being reshaped by labor scarcity and margin sensitivity. Automation in meat processing has gained traction as a response to workforce constraints, and membrane skinners are a logical target for automation because they address a repetitive, physically demanding task with direct implications for yield. Operators are looking for machines that reduce manual intervention without sacrificing flexibility for different cut sizes or product types. This is particularly relevant for beef, pork, and poultry operations, where product dimensions and membrane characteristics can vary significantly. The commercial logic is straightforward: if a machine can improve yield consistency while reducing labor intensity and post-processing rework, it contributes to both operational efficiency and cost control.
Supply chain and cost structure dynamics add further complexity. The reliance on food-grade stainless steel connects membrane skinner manufacturing to broader industrial material markets, where pricing and availability can shift with broader demand patterns. At the same time, manufacturers are under pressure to manage component sourcing, build durability, and keep lead times acceptable for processors planning facility upgrades. This environment rewards suppliers that can maintain production stability, offer clear specifications, and demonstrate that their equipment can withstand continuous use in demanding processing conditions. The broader stainless steel market's growth trajectory suggests that demand for corrosion-resistant processing equipment will remain supported, but it also underscores the importance of cost discipline and supply resilience.
Recent product and exhibition activity illustrates how these drivers are playing out in practice. Compact automatic models have been introduced to serve processors that need high-yield skinning without the footprint or cost of larger systems. Trade show demonstrations have highlighted integrated trimming and skinning solutions, signaling a broader move toward consolidated processing functions and platform-based equipment offerings. These developments point to a market that is not only expanding in volume but also becoming more attentive to practical deployment considerations such as sanitation, footprint, and compatibility with existing workflows.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a mix of established European manufacturers, North American equipment providers, and increasingly cost-competitive OEM suppliers. Market concentration indicates that a limited group of players accounts for a significant share of revenue, but the landscape is not static. Differentiation is emerging along several axes: precision and yield performance, mechanical robustness, integration capability, service and support, and pricing flexibility for different facility scales.
PW Consulting
European manufacturers have built reputations around precision engineering and durable construction. Their product portfolios often span open-top and automatic models, with emphasis on consistent membrane removal and low yield loss across beef, pork, and veal applications. Strong construction standards and familiarity with demanding processing environments give these suppliers credibility in markets where hygiene, repeatability, and long service life are central procurement criteria. Their strategic positioning often extends beyond individual machines to include compatibility with broader automated processing lines, which reinforces their role as part of a larger operational ecosystem rather than a standalone equipment vendor.
North American players contribute a complementary set of strengths, particularly around practical deployment in varied facility sizes and responsive support structures. Compact automatic models have opened opportunities among small-to-medium processors that need reliable skinning capability without the scale or cost of large-line systems. Demonstrations at industry exhibitions have further emphasized yield optimization, durability, and ease of sanitation, reflecting a market that values equipment capable of performing in day-to-day production conditions as much as in controlled specifications. Some providers have also explored platform-based approaches, linking skinning technologies with adjacent trimming and processing functions to offer more consolidated solutions.
Italian manufacturers have carved out a position centered on high-yield derinding and membrane skinning for pork, poultry, and delicate cuts. Their offerings often include single- and dual-blade configurations designed to handle varied product characteristics while maintaining safe and precise operation. Distribution partnerships in key regions, including North America, extend their reach and allow them to compete in markets where local support and service availability influence purchasing decisions.
The competitive picture is further shaped by the presence of lower-cost OEM suppliers, particularly from China, that target cost-sensitive industrial applications. These manufacturers often focus on automatic skinning functionality with adjustable parameters, appealing to processors seeking affordable entry points or replacement units. While their value proposition can be compelling on price, competitive success in the broader market increasingly depends on reliability, sanitation compatibility, and the ability to support consistent yield outcomes over repeated use. Price alone is rarely sufficient when procurement teams weigh total cost of ownership, downtime risk, and integration requirements.
Recent developments highlight the direction of competition. Product launches have targeted compact, lower-cost models that expand accessibility for smaller processors while maintaining durable construction and sanitation-friendly design. Exhibition activity has showcased both standalone skinning machines and broader platform demonstrations, suggesting that suppliers are increasingly thinking in terms of integrated value rather than isolated hardware. This pattern indicates a market in which differentiation is becoming more nuanced: instead of competing only on capacity or price, suppliers are aligning their offerings with specific operational needs, from small-footprint facilities to high-volume automated lines.
Looking ahead, the landscape is likely to evolve through a combination of consolidation, specialization, and new entry. Larger players with broad portfolios may strengthen their position by linking skinning equipment to wider processing systems and service networks. Specialist manufacturers may continue to compete on precision, application fit, and regional support. New entrants will need to establish credibility through consistent quality, clear specifications, and demonstrable performance in real processing conditions. The net effect is a market where strategic positioning matters as much as product capability, and where long-term advantage will depend on how well suppliers match equipment design to the practical constraints of modern meat processing.
Future Outlook: Trends Shaping the Next Three to Five Years
One clear trend is the continued migration toward higher automation in membrane skinning, driven by labor constraints and the desire for consistent yield. Over the next few years, procurement is likely to favor machines that reduce manual intervention while preserving flexibility for different cut sizes and product types. This does not necessarily mean uniform adoption of large-scale automatic systems across all facilities. Instead, the market will probably see a more layered adoption pattern: large processors expanding automated lines, mid-sized operations selecting compact automatic or semi-automatic solutions, and smaller facilities adopting practical, lower-footprint equipment where full automation is not yet justified. The commercial opportunity lies in matching equipment scale to facility reality while still capturing the yield and labor benefits that motivate the transition.
Slitter Market
A second trend is the growing importance of hygiene-enabled design and integration-ready architecture. As sanitation expectations remain elevated and processors seek to minimize downtime, equipment that supports quick cleaning, accessible surfaces, and compatibility with surrounding line components will become more valuable. This trend favors suppliers that can demonstrate not only skinning performance but also how their machines fit into broader operational workflows. It also creates openings for platform-oriented offerings that combine skinning with adjacent trimming or processing functions, reducing the number of separate changeovers and simplifying maintenance planning.
A third trend is the widening gap between premium and value-oriented supply options. As stainless steel and other material inputs remain central to equipment construction, cost structures will continue to matter. However, the market will likely distinguish more clearly between low-cost machines that meet basic functional needs and higher-value systems that offer stronger durability, more predictable yield outcomes, and better integration support. Processors making capital decisions will increasingly weigh total cost of ownership rather than purchase price alone, which could pressure purely price-based competition and reward suppliers that can show reliable long-term performance.
These trends carry both opportunity and uncertainty. Demand for membrane skinning equipment should remain supported by ongoing capacity investment, yield-focused operations, and automation adoption. Yet external variables, including raw material pricing, regional economic conditions, and shifts in processing volumes, can affect purchasing timing and equipment specifications. Suppliers and buyers alike will need to manage flexibility carefully, ensuring that procurement decisions account for both current requirements and the possibility of changing line configurations, product mixes, and labor availability in the years ahead.
Worldwide Pellicle Market
Strategic Actions for Decision-Makers
For equipment manufacturers, the priority is to align product development with practical processing needs rather than abstract specifications. That means continuing to refine precision and yield performance while also emphasizing sanitation-friendly design, durability, and compatibility with different facility scales. Suppliers that can offer a credible range from compact models to higher-capacity automatic systems, supported by clear service and parts availability, will be better positioned to compete across diverse buyer segments. Differentiation should be anchored in measurable operational value, including ease of cleaning, consistent output, and integration fit.
For investors and strategic planners, the market signals a sector with steady baseline growth and selective upside tied to automation adoption and integration-oriented offerings. Attention should focus on companies that demonstrate strong product reliability, clear regional support, and the ability to serve both mature and growth markets without compromising quality or compliance expectations. Investment theses that assume uniform expansion across all segments are likely to overlook the reality that procurement behavior is becoming more segmented, with different facility types prioritizing different combinations of cost, performance, and support.
For processors and procurement teams, the practical task is to evaluate membrane skinning equipment as part of a broader operational strategy rather than as an isolated purchase. Decisions should weigh yield impact, labor reduction, sanitation efficiency, integration with existing lines, and long-term service support alongside upfront cost. Selecting equipment that matches current facility conditions while leaving room for future line adjustments can reduce the risk of under- or over-specifying capacity. As product options expand and competitive positioning becomes more nuanced, access to detailed segmentation data and customized procurement insights can help narrow choices more efficiently and avoid costly mismatches between equipment capabilities and operational requirements.
For detailed analysis of this topic, please visit the official page: Worldwide Meat Membrane Skinner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
3-Phase Distribution Boards Market: Why Asia Pacific's Growth Trajectory Drives 5.85% CAGR Through 2032
By pmarketresearch, 2026-09-18
Global 3-Phase Distribution Boards Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The worldwide market for 3-phase distribution boards has demonstrated consistent expansion over the past half-decade, with revenues climbing from approximately $5.58 billion in 2020 to $7.42 billion in 2025. Projections indicate the market will continue its upward trajectory, reaching roughly $11.05 billion by 2032, representing a compound annual growth rate of 5.85% across the forecast horizon. This growth trajectory reflects the foundational role that low-voltage switchgear assemblies play in modern electrical infrastructure, where reliable power distribution is non-negotiable for industrial operations, commercial facilities, and increasingly complex residential installations.
Despite the positive momentum, the industry navigates several structural challenges that will shape competitive dynamics and investment decisions over the coming years. First, supply chain volatility for critical raw materials has introduced significant cost uncertainty. Copper busbars, which form the conductive backbone of distribution boards, experienced price fluctuations that averaged $8,800 per metric ton in late 2023, while hot-rolled coil steel for enclosures hovered around $650 per metric ton in early 2024. These material cost swings compress margins for manufacturers and create pricing friction in bid-based procurement environments. Companies that lack hedging strategies or vertical integration in material sourcing face disproportionate exposure.
Second, the regulatory landscape is tightening around safety, efficiency, and interoperability. Compliance with IEC 61439-1:2020 has become a baseline expectation for low-voltage switchgear assemblies, demanding form 4b segregation and rigorous testing protocols. In North America, the NEC 2023 Edition introduced enhanced labeling requirements for 3-phase systems under Article 408, compelling manufacturers to update documentation, labeling processes, and training for installation partners. Meanwhile, the EU Ecodesign Directive continues to push minimum efficiency thresholds for integrated power distribution transformers, forcing product redesigns that balance performance with environmental compliance. These regulatory shifts raise the barrier to entry for smaller players and reward organizations with mature quality management systems and proactive standards engagement.
Third, the market is experiencing a demand-side bifurcation. Industrial consumers increasingly prioritize arc flash protection, digital monitoring, and modularity that supports rapid reconfiguration as production lines evolve. Commercial building operators seek compact, aesthetically integrated solutions that minimize installation time and support energy management platforms. Residential demand, while smaller in absolute terms, is being reshaped by electrification trends such as heat pumps, EV charging infrastructure, and solar-plus-storage systems that require robust 3-phase capacity at the point of connection. Each segment carries distinct specification expectations, certification requirements, and procurement cycles, making one-size-fits-all product strategies increasingly ineffective.
Key Challenges at a Glance
- Raw material cost volatility for copper and steel components impacting margin stability and bid pricing
- Escalating compliance demands across IEC 61439, NEC 2023, and EU Ecodesign requirements raising engineering and certification costs
- Fragmented end-user specifications across industrial, commercial, and residential applications complicating product portfolio optimization
Key Drivers of Market Evolution
Technology innovation stands out as a primary catalyst reshaping product architectures and value propositions. Digital integration has moved from a differentiator to an expectation, particularly in industrial and commercial settings where operators demand visibility into load distribution, fault conditions, and energy consumption at the board level. Siemens showcased updated SIVACON 8MC cubicle systems with digital twin integration at Hannover Messe, signaling how physical distribution hardware is converging with simulation and asset management workflows. LS Electric has embedded smart monitoring features into Su2000 and Tablo panels rated up to 8000A, illustrating how advanced telemetry can be packaged into high-capacity 3-phase platforms. For manufacturers, the strategic implication is clear: hardware performance alone no longer defines competitive advantage. The ability to deliver data-rich, interoperable boards that slot into broader building or plant management ecosystems is becoming a decisive factor in specification wins.
Product innovation cycles are also accelerating around safety and modularity. Eaton launched the xEnergy Pa low-voltage air-insulated 3-phase distribution boards in March 2024, featuring enhanced arc-resistant design rated up to 250kA. This launch underscores how safety engineering is being pushed into higher-performance configurations that address stringent industrial risk profiles. ABB's November 2023 enhancements to the TruFit switchboard series targeted data center applications, where reliability, rapid deployment, and thermal management are paramount. Schneider Electric achieved UL certification for its PrismaStac RT modular 3-phase distribution boards in January 2024, expanding its Prisma P and PrismaSeT portfolio's reach in North American markets where certification is a prerequisite for large-scale project participation. These examples demonstrate that targeted certifications and application-specific engineering are unlocking segments that generic product lines struggle to serve.
Policy and regulatory momentum is reshaping both demand and compliance costs. IEC 61439-1:2020 remains the global touchstone for low-voltage switchgear assemblies, and its emphasis on form 4b segregation has elevated design complexity, especially for boards that must isolate different functional sections while maintaining compact footprints. In Europe, the Ecodesign Directive's efficiency mandates for integrated transformers are pushing manufacturers to evaluate loss characteristics earlier in the design phase, favoring topologies that balance upfront cost against lifecycle energy consumption. In the United States, NEC 2023's updated Article 408 requirements for enhanced 3-phase labeling are driving documentation and labeling process changes that affect not only manufacturers but also distributors, integrators, and commissioning teams. For suppliers, these regulatory dynamics create a dual reality: they increase development overhead, but they also reinforce the value of established compliance infrastructure and reduce the viability of low-cost, low-quality entrants in regulated markets.
Demand-side behavior is evolving as electrification and decentralization redefine power distribution needs. Industrial operators are investing in modernized facilities where modular distribution boards support phased plant expansions, reconfigurable production cells, and higher short-circuit withstand capabilities. Commercial segments, including data centers, healthcare, and logistics hubs, are prioritizing prefabricated solutions that reduce on-site installation risk and speed project timelines. The residential segment, while smaller, is absorbing new loads from heat pumps, EV chargers, and distributed generation, prompting electrical contractors to specify boards that accommodate future capacity upgrades without full replacement. This demand evolution favors suppliers that offer scalable architectures, clear upgrade paths, and application-specific documentation that helps specification engineers justify choices in competitive bid environments.
Cost structure dynamics are also influencing procurement strategies and supplier selection. Beyond raw material price swings, the industry is seeing pressure to reduce total installed cost rather than simply minimizing unit price. Prefabricated assemblies, plug-in technologies, and standardized busbar layouts can lower installation labor, reduce rework, and compress commissioning schedules. For buyers, this shifts the evaluation lens from sticker price to lifecycle and project-level economics. For manufacturers, it rewards engineering approaches that standardize modular components while preserving flexibility for custom ratings and configurations. Companies that can articulate and deliver measurable installation and operational savings are better positioned to defend pricing and win complex projects.
Competitive Landscape and Leading Strategies
The market is characterized by a moderately concentrated landscape, with the top three firms holding approximately 32.4% combined share and the top five accounting for about 46.8%. This concentration suggests that scale, brand trust, and global distribution networks confer meaningful advantages, but also that a long tail of capable regional and application-focused suppliers can compete effectively in specific niches. The competitive battleground is increasingly defined by differentiated product architectures, certification breadth, and the ability to align solutions with the operational priorities of industrial and commercial buyers.
European multinationals continue to anchor the high-end segment with strong emphasis on safety, modularity, and digital readiness. Schneider Electric's Prisma P and PrismaSeT ranges, compliant with IEC 61439 for applications up to 6300A, benefit from a broad commercial and industrial installed base and a modular philosophy that supports phased expansion. ABB's System pro M and ArTu series, rated up to 4000A with modular designs, target building and industrial power distribution where flexibility and serviceability matter. Siemens' SIVACON 8MC and Sentron 3WL integrated cubicle systems, rated up to 7500A, emphasize safety and digital integration, positioning the company well for customers pursuing connected plant strategies. Eaton's xEnergy and Power Xpert PX platforms, rated up to 7000A, highlight arc flash protection and prefabricated solutions, a combination that resonates with industrial sites where risk mitigation and deployment speed are priorities. Legrand's DMX³ and Equinox boards, up to 4000A with plug-in technology, are oriented toward commercial buildings where install efficiency and aesthetics influence specification. Hager Group's VSM and Powercap offerings, suitable for modular and fixed configurations up to 1600A, address a range of installation scenarios with pragmatic design choices. Rittal's Ri4Power systems, rated up to 5000A with perforated door technology for thermal management, appeal to environments where enclosure cooling and component protection are critical. Socomec's Delipower M and MPI modular boards, rated up to 5000A with high short-circuit withstand, cater to applications demanding robust fault tolerance.
Asian manufacturers are expanding their global footprint by combining high-current capabilities with cost-competitive engineering and regional certification expertise. Larsen & Toubro's L&T Power Distribution Boards, rated up to 6500A and tailored for Indian and export markets with IP ratings, illustrate how regional strength can be leveraged into export growth when paired with appropriate compliance packaging. Havells' Reo series, up to 3200A for industrial use and compliant with IS/IEC standards, reflects a focus on industrial customers where standard alignment and value pricing matter. CHINT Global's NQ series withdrawable 3-phase boards, rated up to 6600A for global markets, show how Chinese suppliers are scaling beyond domestic demand by offering broad-amperage ranges and international certifications. Mitsubishi Electric's WS/V series, up to 7000A for factory automation, and Fuji Electric's F-MCC and distribution boards, up to 5000A in industrial settings, underline Japan's continued strength in precision-engineered industrial power distribution. LS Electric's Su2000 and Tablo panels, up to 8000A with smart monitoring features, position the company at the intersection of high capacity and digital functionality, an increasingly attractive combination.
Strategic differentiation is converging around three themes. First, high-amperage, application-specific platforms that address arc flash, thermal management, and short-circuit withstand are becoming preferred choices in demanding industrial and data center contexts. Second, modular and prefabricated architectures are gaining traction as buyers seek to reduce installation risk, accelerate commissioning, and support future reconfiguration. Third, digital and certification readiness is serving as a gatekeeper in regulated markets, where UL recognition, IEC compliance, and integration with asset management platforms can determine whether a supplier appears on the finalist list. Recent developments reinforce this pattern: Eaton's arc-resistant xEnergy Pa launch, Siemens' digital twin-enabled SIVACON showcase, ABB's data center-focused TruFit enhancements, and Schneider Electric's UL certification for PrismaStac RT all point to a landscape where safety, digital linkage, and market-specific certification are central to winning complex projects.
Looking ahead, the competitive structure is likely to see selective consolidation among smaller players that lack the scale to absorb compliance costs or the engineering depth to compete on high-current, safety-critical platforms. At the same time, regional specialists with strong local service networks, certification portfolios, and application knowledge can thrive by focusing on segments where global scale is less decisive than responsiveness and specification support. New entrants will find the highest-probability opportunities in converged domains such as digitally enabled boards, prefabricated solutions for fast-track construction, and boards optimized for electrification-driven residential and commercial loads, rather than attempting head-on competition in established high-amperage industrial segments.
Worldwide Three Phase Recloser Market
Future Trends and Commercial Opportunities
Over the next three to five years, digitalization and connectivity will become standard expectations rather than optional upgrades. Distribution boards equipped with monitoring, diagnostics, and integration pathways into building and plant management systems will command preference in commercial and industrial tenders. The commercial opportunity lies in combining hardware with software services, predictive maintenance insights, and energy visibility that help operators optimize load balancing, reduce downtime, and support decarbonization reporting. Suppliers that can deliver interoperable telemetry without compromising safety certification or short-circuit performance will be well placed to capture specification share.
Prefabrication and modularization will continue to gain momentum as project delivery pressures intensify. Labor constraints, scheduling criticality, and the cost of on-site rework are pushing buyers toward engineered assemblies that arrive ready for installation with minimal customization. This trend creates opportunities for suppliers to standardize high-value modules, offer pre-tested configurations, and provide documentation that streamlines commissioning. For industrial customers, modularity also supports future expansions and reconfigurations, making boards that allow selective add-on or rebalancing more attractive over the asset lifecycle.
Three Phase Cast Resin Transformer Market
Electrification-driven load growth in commercial and residential settings will reshape specification patterns. Heat pumps, EV charging infrastructure, and distributed generation are increasing the need for robust 3-phase capacity at the connection point, even in buildings that previously relied on lighter electrical arrangements. This shift opens opportunities for boards designed with headroom, clear upgrade pathways, and compatibility with metering and monitoring requirements that facility managers increasingly demand. The risk is that rapid load growth can outpace existing infrastructure design assumptions, leading to retrofit cycles if early specifications do not anticipate future expansion. Suppliers and specifiers who plan for load scenarios beyond current baselines will reduce downstream friction and capture repeat business through upgrade programs.
These trends carry uncertainty. Raw material price swings can re-emerge quickly, influencing both cost structures and project economics. Regulatory updates may accelerate in response to safety incidents or efficiency targets, increasing certification and redesign burdens. Digital integration, while valuable, introduces cybersecurity and interoperability considerations that buyers will scrutinize more closely as connected systems proliferate. Organizations that proactively manage material exposure, maintain agile certification pathways, and design for both safety and cyber resilience will be better positioned to convert these uncertainties into durable competitive advantages.
Strategic Recommendations for Decision Makers
For manufacturers, the priority is to align product roadmaps with the convergence of safety, modularity, and digital readiness. Investing in arc-resistant designs, high short-circuit withstand capabilities, and prefabricated architectures addresses the specifications that are winning complex industrial and commercial projects. Equally important is building certification breadth in target markets, including UL and IEC pathways, and developing documentation that helps specification engineers justify total installed cost rather than unit price alone. Standardizing modular building blocks while preserving flexibility for custom ratings can improve engineering efficiency and speed response to project-specific requirements.
PW Consulting
For investors, the market offers differentiated exposure across scale players, application specialists, and digital-integration-focused suppliers. Due diligence should assess certification portfolios, short-circuit and arc-flash engineering depth, thermal management innovations, and the ability to support prefabricated delivery models. Companies with strong positions in data center, industrial automation, and electrification-driven segments may offer more resilient growth profiles than those dependent on undifferentiated commodity boards. Monitoring raw material hedging practices and supply chain resilience is also prudent, given the historical sensitivity of copper and steel costs to broader market dynamics.
For procurement and specification teams, the focus should shift toward evaluating total project economics and lifecycle performance. Requesting detailed information on installation labor implications, commissioning support, modularity for future expansion, and monitoring integration can reveal value that unit-price comparisons obscure. Clarifying compliance status, labeling readiness under NEC 2023, and IEC 61439 alignment reduces downstream risk. Engaging suppliers early in the design phase to confirm upgrade paths, thermal requirements, and digital integration options helps avoid retrofit scenarios as loads evolve.
For stakeholders seeking a deeper, segment-level view of regional demand patterns, mounting-type preferences, end-user splits, and company-level benchmarking, the full research report provides detailed datasets and tailored strategic guidance to support procurement planning, product portfolio decisions, and investment prioritization.
For detailed analysis of this topic, please visit the official page: Worldwide 3-Phase Distribution Boards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com