

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
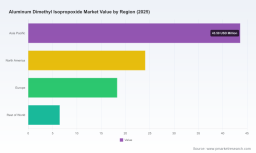
Aluminum Dimethyl Isopropoxide Market: Why 43.59% Asia Pacific Share Reshapes Growth Beyond 6.12% CAGR

Strategic Trends and Commercial Opportunities in the Worldwide Aluminum Dimethyl Isopropoxide Market
Market Status and Core Challenges
The global market for aluminum dimethyl isopropoxide (ADIP) has entered a phase of measured but steady expansion, driven primarily by its specialized role in advanced materials processing. Valued at approximately USD 68.42 million in 2020, the market has grown to USD 92.45 million in 2025, reflecting a compound annual growth rate of 6.12 percent through 2032. This trajectory indicates a market transitioning from niche industrial supply to a strategically positioned enabler of high-purity thin-film deposition and catalytic processes. Revenue generation remains concentrated within a handful of established participants, with the top three holding roughly 58.4 percent of total market share and the top five approaching 74 percent. Such concentration underscores the technical barriers to entry, stringent purity requirements, and the specialized logistics networks necessary to handle reactive organometallic compounds safely.
The current landscape is defined by a clear bifurcation in demand patterns. High-purity specifications dominate revenue streams, particularly those meeting electronic-grade thresholds above 99.999 percent. This split reflects the material's evolving application profile, where precision-engineered deposition processes require consistent batch-to-batch reproducibility and minimal particulate contamination. Industrial-grade volumes continue to serve broader chemical synthesis and polymerization catalysis needs, but growth momentum has increasingly tilted toward applications requiring sub-micron film control and thermal stability. Geographic distribution reveals a strong pull toward Asia Pacific, North America, and Europe, with the remainder of the market developing at a slower pace tied to localized manufacturing capacity and regulatory maturity. The hierarchy of demand is further shaped by application intensity: semiconductor layer deposition represents the largest utilization channel, followed by polymerization catalysis and glass/ceramic coating formulations.
Despite constructive demand signals, the industry faces structural challenges that will shape near-term strategy. First, the regulatory and safety burden associated with handling water-reactive, highly flammable organoaluminum compounds creates friction across procurement, logistics, and operational compliance. Transport restrictions and specialized storage requirements elevate total cost of ownership for downstream users, particularly smaller fabrication facilities or research laboratories operating under tight compliance budgets. Second, supply chain consistency for upstream organometallic feedstocks introduces volatility into production planning. Manufacturers must manage complex synthesis routes while navigating impurity control and batch certification processes that are integral to maintaining purity thresholds demanded by advanced deposition processes. Third, market participants are navigating a consolidation pressure as high-purity capacity expansion becomes capital-intensive and technically differentiated. Firms that cannot invest in controlled synthesis environments or certified quality management frameworks risk marginalization, while new entrants must contend with both technical credibility and established distribution relationships. These dynamics create a pivotal moment for companies to decide whether to deepen specialization, pursue strategic partnerships, or reposition toward adjacent high-margin segments.
Key Drivers of Market Change
Technological innovation remains a primary engine of growth, particularly as deposition techniques evolve toward tighter process control and lower defect densities. Aluminum dimethyl isopropoxide has gained relevance as a nonpyrophoric alternative precursor to trimethylaluminum in plasma-enhanced atomic layer deposition of aluminum oxide thin films. This shift matters because plasma-enhanced atomic layer deposition enables conformal coating on complex geometries and high-aspect-ratio structures commonly found in advanced semiconductor packaging and device architectures. The move toward safer handling profiles, while maintaining deposition efficiency and film quality, reduces process risk for manufacturers and can lower downstream operational costs related to fire suppression, inert atmosphere controls, and emergency response planning. As device nodes shrink and material specifications tighten, precursor selection increasingly balances reactivity, thermal stability, and impurity tolerance. That balance favors compounds that can deliver consistent stoichiometry without introducing metal contaminants exceeding parts-per-billion thresholds. Consequently, research and commercial scale efforts are converging on formulations and process recipes that optimize film uniformity while reducing variability across wafer lots.
Regulatory and compliance frameworks are simultaneously reshaping the commercial environment. The compound's classification as a highly flammable liquid and vapor with water-reactive properties places it under stringent handling, labeling, and transport requirements across international regulatory regimes. Compliance with road and rail transport standards, alignment with hazardous material handling protocols, and adherence to regional safety directives create both cost and capability implications. For established suppliers, robust compliance infrastructure can become a competitive differentiator, signaling reliability to customers in highly regulated sectors. For procurement teams and end users, these requirements influence supplier selection, location strategy for production sites, and inventory management practices. Companies that proactively align with harmonized safety standards and invest in certified packaging, traceability, and documentation systems can reduce lead-time uncertainty and improve resilience during supply disruptions. In practice, the regulatory environment is steering the market toward suppliers with demonstrated operational discipline, particularly where materials are destined for electronic applications with additional quality and contamination controls.
Demand-side behavior is shifting as end-use industries pursue advanced materials with greater urgency. Semiconductor manufacturing continues to expand in both mature and advanced nodes, with layer deposition processes demanding precursors that can meet increasingly exacting specifications. Beyond front-end processing, secondary growth channels are gaining traction in catalysis and coatings, where aluminum-based organometallic compounds support polymerization reactions and functional surface treatments. In catalysis, the material's role in aluminum precursor chemistry contributes to catalyst design for polymer production, reflecting persistent demand for high-performance plastics and engineered composites. In glass and ceramic coatings, deposition and surface modification applications benefit from aluminum oxide-related chemistry that enhances barrier properties, thermal resistance, and mechanical durability. These demand patterns are not evenly distributed; they concentrate around regions with strong electronics manufacturing ecosystems and established specialty chemical supply chains. As a result, procurement strategies are moving toward multi-source arrangements, technical qualification processes, and long-term supply agreements that balance purity assurance with cost predictability.
PW Consulting
Supply chain and cost structure dynamics further influence how the market evolves. The reliance on upstream organoaluminum feedstocks, particularly trimethylaluminum as a primary synthesis input, introduces sensitivity to raw material availability, pricing fluctuations, and synthesis route optimization. Manufacturers that can stabilize precursor sourcing, improve yield through process refinement, and maintain purity without excessive rework will be better positioned to manage margins. Logistics costs and safety-related handling requirements add another layer of complexity, especially for international distribution and just-in-time delivery expectations. In response, supply strategies are shifting toward regional production footprints, strategic inventory buffers for high-value customers, and closer collaboration between precursor suppliers and deposition process engineers. These adjustments aim to reduce variability, shorten qualification cycles, and improve responsiveness to specification changes. The combined effect is a market in which technical capability and operational reliability increasingly determine commercial success, beyond price considerations alone.
Worldwide Aluminium Tert Butoxide Market
Competitive Landscape and Leading Strategies
The competitive structure of the market is characterized by a small group of specialty manufacturers and distributors with distinct strategic emphases. Several U.S.-based firms occupy prominent positions, each reinforcing credibility through product-grade focus, application alignment, and distribution reach. One specialized manufacturer emphasizes high-purity aluminum dimethyl isopropoxide for atomic layer deposition and metal-organic chemical vapor deposition applications, serving both research and commercial quantities. This positioning reflects a deliberate focus on process-critical customers who require consistent precursor performance and technical support for deposition recipes. Another established supplier offers a high-purity grade intended for atomic layer deposition precursor use, highlighting purity levels that align with electronic-grade expectations. Its approach underscores the importance of certified grade definitions and traceable product information in sectors where material variability can affect yield and device reliability. A global manufacturer and supplier provides commercial and research quantities, broadening accessibility and reinforcing a product portfolio that spans multiple organometallic specialties. This wider scope can support cross-selling and customer consolidation, particularly for procurement teams seeking a single qualified source for multiple materials.
Additional participants bring regional and application-specific differentiation. A South Korean producer focuses on dimethylaluminum isopropoxide as an aluminum precursor specifically for metal-organic chemical vapor deposition and atomic layer deposition applications, aligning closely with the semiconductor materials ecosystem in Asia Pacific. Such regional specialization can improve proximity to end users, reduce lead times, and strengthen technical collaboration with local fabrication and research institutions. A supplier offering the dimeric form of dimethylaluminum isopropoxide for semiconductor and thin-film deposition processes illustrates how molecular form and packaging can become differentiating factors when customers require specific handling characteristics or process compatibility. A global distributor supplements these offerings by supplying the compound as part of a broader specialty chemicals portfolio, enabling customers to consolidate sourcing and benefit from established logistics networks. This distribution role is particularly valuable for smaller research groups, pilot-line operations, and procurement functions seeking flexible order quantities and multi-product supply relationships.
Leading firms differentiate through a combination of purity assurance, application alignment, and operational reliability. High-purity grades command premium positioning because they reduce qualification risk for electronic applications and support reproducibility across production batches. Suppliers that invest in controlled synthesis environments, robust analytical verification, and clear grade definitions can build trust with customers who operate under stringent contamination limits. Application-specific positioning also matters: companies that communicate clearly how their materials fit into deposition processes, catalyst formulations, or coating workflows can shorten evaluation cycles and enhance customer retention. Operational reliability, including packaging integrity, transport compliance, and batch traceability, further reinforces commercial credibility in a market where material handling risk and quality consistency are central concerns. Strategic differentiation is therefore less about volume scale and more about precision, certification, and the ability to support customers through technical evaluation and long-term supply.
Market evolution points toward gradual consolidation among high-purity specialists and continued fragmentation within broader distribution channels. Larger integrated players may pursue partnerships or selective acquisitions to strengthen capacity, broaden geographic coverage, or deepen application support. At the same time, regional producers can capture value by aligning with local electronics ecosystems and responding quickly to specification changes in nearby fabrication hubs. New entrants face meaningful hurdles, including purity certification, safety compliance, and the need to establish technical trust with demanding end users. As a result, the landscape is likely to remain concentrated at the top while specialized niches persist around dimer forms, regional supply, and multi-product distribution. Companies that can combine technical credibility with dependable logistics and clear application messaging are best positioned to expand share without engaging in undifferentiated price competition.
Future Trends and Outlook
Over the next three to five years, one of the most consequential trends will be the continued migration toward safer and more controllable precursor chemistries in advanced deposition processes. As plasma-enhanced atomic layer deposition and related techniques become more widely adopted for complex device structures, demand for precursors that reduce pyrophoric risk while maintaining film quality is likely to strengthen. This trend creates opportunities for suppliers that can demonstrate consistent purity, reliable batch performance, and strong technical documentation. Manufacturers that invest in process recipes, qualification support, and application notes will be better positioned to convert technical adoption into recurring supply relationships. End users, in turn, may favor arrangements that reduce process variability and simplify compliance, even if unit pricing is not the lowest in the market.
A second trend will be regional capacity alignment with electronics manufacturing growth. Demand concentration in Asia Pacific, North America, and Europe will encourage producers to consider localized supply footprints, strategic inventory placement, and closer technical collaboration with regional customers. Proximity can shorten qualification cycles, improve responsiveness to specification updates, and reduce logistics-related risk for highly sensitive materials. For investors, this suggests that capacity expansion decisions will increasingly be evaluated against regional demand visibility, regulatory maturity, and the ability to serve qualified customer pipelines rather than purely on broad global volume assumptions. Regional specialization may also encourage partnerships between precursor suppliers and equipment or process engineering firms, creating integrated value propositions around deposition performance and material reliability.
Worldwide Aluminum Alkyls Market
A third trend involves heightened scrutiny of supply chain resilience and upstream feedstock stability. Because synthesis depends on organoaluminum inputs and tightly controlled reactive chemistry, producers and buyers alike will likely place greater emphasis on sourcing transparency, contingency planning, and quality verification across the value chain. Companies that can mitigate feedstock disruption risks, maintain consistent purity through process optimization, and provide clear documentation for regulatory and quality audits will gain a structural advantage. At the same time, uncertainty remains around regulatory evolution, regional compliance divergence, and the potential for demand volatility if electronics cycles or catalyst demand patterns shift. These risks do not negate growth, but they reinforce the importance of flexible supply strategies and disciplined qualification processes.
Recommendations for Decision-Makers
For manufacturers, the priority should be reinforcing technical differentiation and operational reliability rather than competing primarily on volume or price. Investing in purity consistency, analytical verification, and clear grade definitions can strengthen qualification outcomes with electronic-grade customers. Equally important is building robust safety and logistics capability, since handling and transport compliance directly affects customer trust and total cost of ownership. Companies should also evaluate whether to deepen application support through technical documentation, recipe collaboration, and regional proximity to high-demand customers. Firms that align capacity decisions with verified demand pipelines and regional compliance readiness will be better positioned to capture value from the market's gradual shift toward safer precursors and tighter film specifications.
For investors, due diligence should focus on the durability of high-purity demand, the stability of upstream feedstock access, and the credibility of quality systems rather than on generic growth narratives. Indications of long-term supply agreements, qualified customer relationships, and investment in controlled synthesis and compliance infrastructure can signal stronger commercial resilience. Portfolio exposure may be more attractive where producers demonstrate regional alignment with electronics ecosystems or where distribution partners offer multi-product reach and flexible order structures. At the same time, risk assessment should account for regulatory complexity, concentration in a small number of buyers and suppliers, and sensitivity to electronics cycle fluctuations.
For procurement and sourcing leaders, the practical emphasis should be on qualification discipline, supply continuity, and total cost of ownership. Evaluating suppliers on purity consistency, batch traceability, packaging integrity, and transport compliance can reduce downstream risk in deposition and catalysis applications. Multi-source strategies, clear specification alignment, and technical collaboration with suppliers can improve resilience without sacrificing quality. Given the pace of change in precursor selection and process requirements, access to current market intelligence on grade definitions, application trends, and regional supply dynamics can support more informed sourcing decisions. The complete research report provides detailed segmentation, regional and application-specific data, and customized guidance for organizations seeking a deeper basis for strategic planning.
For detailed analysis of this topic, please visit the official page: Worldwide Aluminum Dimethyl Isopropoxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com