

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
3-Phase Distribution Boards Market: Why Asia Pacific's Growth Trajectory Drives 5.85% CAGR Through 2032

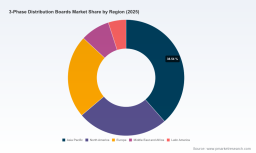
Global 3-Phase Distribution Boards Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The worldwide market for 3-phase distribution boards has demonstrated consistent expansion over the past half-decade, with revenues climbing from approximately $5.58 billion in 2020 to $7.42 billion in 2025. Projections indicate the market will continue its upward trajectory, reaching roughly $11.05 billion by 2032, representing a compound annual growth rate of 5.85% across the forecast horizon. This growth trajectory reflects the foundational role that low-voltage switchgear assemblies play in modern electrical infrastructure, where reliable power distribution is non-negotiable for industrial operations, commercial facilities, and increasingly complex residential installations.
Despite the positive momentum, the industry navigates several structural challenges that will shape competitive dynamics and investment decisions over the coming years. First, supply chain volatility for critical raw materials has introduced significant cost uncertainty. Copper busbars, which form the conductive backbone of distribution boards, experienced price fluctuations that averaged $8,800 per metric ton in late 2023, while hot-rolled coil steel for enclosures hovered around $650 per metric ton in early 2024. These material cost swings compress margins for manufacturers and create pricing friction in bid-based procurement environments. Companies that lack hedging strategies or vertical integration in material sourcing face disproportionate exposure.
Second, the regulatory landscape is tightening around safety, efficiency, and interoperability. Compliance with IEC 61439-1:2020 has become a baseline expectation for low-voltage switchgear assemblies, demanding form 4b segregation and rigorous testing protocols. In North America, the NEC 2023 Edition introduced enhanced labeling requirements for 3-phase systems under Article 408, compelling manufacturers to update documentation, labeling processes, and training for installation partners. Meanwhile, the EU Ecodesign Directive continues to push minimum efficiency thresholds for integrated power distribution transformers, forcing product redesigns that balance performance with environmental compliance. These regulatory shifts raise the barrier to entry for smaller players and reward organizations with mature quality management systems and proactive standards engagement.
Third, the market is experiencing a demand-side bifurcation. Industrial consumers increasingly prioritize arc flash protection, digital monitoring, and modularity that supports rapid reconfiguration as production lines evolve. Commercial building operators seek compact, aesthetically integrated solutions that minimize installation time and support energy management platforms. Residential demand, while smaller in absolute terms, is being reshaped by electrification trends such as heat pumps, EV charging infrastructure, and solar-plus-storage systems that require robust 3-phase capacity at the point of connection. Each segment carries distinct specification expectations, certification requirements, and procurement cycles, making one-size-fits-all product strategies increasingly ineffective.
Key Challenges at a Glance
- Raw material cost volatility for copper and steel components impacting margin stability and bid pricing
- Escalating compliance demands across IEC 61439, NEC 2023, and EU Ecodesign requirements raising engineering and certification costs
- Fragmented end-user specifications across industrial, commercial, and residential applications complicating product portfolio optimization
Key Drivers of Market Evolution
Technology innovation stands out as a primary catalyst reshaping product architectures and value propositions. Digital integration has moved from a differentiator to an expectation, particularly in industrial and commercial settings where operators demand visibility into load distribution, fault conditions, and energy consumption at the board level. Siemens showcased updated SIVACON 8MC cubicle systems with digital twin integration at Hannover Messe, signaling how physical distribution hardware is converging with simulation and asset management workflows. LS Electric has embedded smart monitoring features into Su2000 and Tablo panels rated up to 8000A, illustrating how advanced telemetry can be packaged into high-capacity 3-phase platforms. For manufacturers, the strategic implication is clear: hardware performance alone no longer defines competitive advantage. The ability to deliver data-rich, interoperable boards that slot into broader building or plant management ecosystems is becoming a decisive factor in specification wins.
Product innovation cycles are also accelerating around safety and modularity. Eaton launched the xEnergy Pa low-voltage air-insulated 3-phase distribution boards in March 2024, featuring enhanced arc-resistant design rated up to 250kA. This launch underscores how safety engineering is being pushed into higher-performance configurations that address stringent industrial risk profiles. ABB's November 2023 enhancements to the TruFit switchboard series targeted data center applications, where reliability, rapid deployment, and thermal management are paramount. Schneider Electric achieved UL certification for its PrismaStac RT modular 3-phase distribution boards in January 2024, expanding its Prisma P and PrismaSeT portfolio's reach in North American markets where certification is a prerequisite for large-scale project participation. These examples demonstrate that targeted certifications and application-specific engineering are unlocking segments that generic product lines struggle to serve.
Policy and regulatory momentum is reshaping both demand and compliance costs. IEC 61439-1:2020 remains the global touchstone for low-voltage switchgear assemblies, and its emphasis on form 4b segregation has elevated design complexity, especially for boards that must isolate different functional sections while maintaining compact footprints. In Europe, the Ecodesign Directive's efficiency mandates for integrated transformers are pushing manufacturers to evaluate loss characteristics earlier in the design phase, favoring topologies that balance upfront cost against lifecycle energy consumption. In the United States, NEC 2023's updated Article 408 requirements for enhanced 3-phase labeling are driving documentation and labeling process changes that affect not only manufacturers but also distributors, integrators, and commissioning teams. For suppliers, these regulatory dynamics create a dual reality: they increase development overhead, but they also reinforce the value of established compliance infrastructure and reduce the viability of low-cost, low-quality entrants in regulated markets.
Demand-side behavior is evolving as electrification and decentralization redefine power distribution needs. Industrial operators are investing in modernized facilities where modular distribution boards support phased plant expansions, reconfigurable production cells, and higher short-circuit withstand capabilities. Commercial segments, including data centers, healthcare, and logistics hubs, are prioritizing prefabricated solutions that reduce on-site installation risk and speed project timelines. The residential segment, while smaller, is absorbing new loads from heat pumps, EV chargers, and distributed generation, prompting electrical contractors to specify boards that accommodate future capacity upgrades without full replacement. This demand evolution favors suppliers that offer scalable architectures, clear upgrade paths, and application-specific documentation that helps specification engineers justify choices in competitive bid environments.
Cost structure dynamics are also influencing procurement strategies and supplier selection. Beyond raw material price swings, the industry is seeing pressure to reduce total installed cost rather than simply minimizing unit price. Prefabricated assemblies, plug-in technologies, and standardized busbar layouts can lower installation labor, reduce rework, and compress commissioning schedules. For buyers, this shifts the evaluation lens from sticker price to lifecycle and project-level economics. For manufacturers, it rewards engineering approaches that standardize modular components while preserving flexibility for custom ratings and configurations. Companies that can articulate and deliver measurable installation and operational savings are better positioned to defend pricing and win complex projects.
Competitive Landscape and Leading Strategies
The market is characterized by a moderately concentrated landscape, with the top three firms holding approximately 32.4% combined share and the top five accounting for about 46.8%. This concentration suggests that scale, brand trust, and global distribution networks confer meaningful advantages, but also that a long tail of capable regional and application-focused suppliers can compete effectively in specific niches. The competitive battleground is increasingly defined by differentiated product architectures, certification breadth, and the ability to align solutions with the operational priorities of industrial and commercial buyers.
European multinationals continue to anchor the high-end segment with strong emphasis on safety, modularity, and digital readiness. Schneider Electric's Prisma P and PrismaSeT ranges, compliant with IEC 61439 for applications up to 6300A, benefit from a broad commercial and industrial installed base and a modular philosophy that supports phased expansion. ABB's System pro M and ArTu series, rated up to 4000A with modular designs, target building and industrial power distribution where flexibility and serviceability matter. Siemens' SIVACON 8MC and Sentron 3WL integrated cubicle systems, rated up to 7500A, emphasize safety and digital integration, positioning the company well for customers pursuing connected plant strategies. Eaton's xEnergy and Power Xpert PX platforms, rated up to 7000A, highlight arc flash protection and prefabricated solutions, a combination that resonates with industrial sites where risk mitigation and deployment speed are priorities. Legrand's DMX³ and Equinox boards, up to 4000A with plug-in technology, are oriented toward commercial buildings where install efficiency and aesthetics influence specification. Hager Group's VSM and Powercap offerings, suitable for modular and fixed configurations up to 1600A, address a range of installation scenarios with pragmatic design choices. Rittal's Ri4Power systems, rated up to 5000A with perforated door technology for thermal management, appeal to environments where enclosure cooling and component protection are critical. Socomec's Delipower M and MPI modular boards, rated up to 5000A with high short-circuit withstand, cater to applications demanding robust fault tolerance.
Asian manufacturers are expanding their global footprint by combining high-current capabilities with cost-competitive engineering and regional certification expertise. Larsen & Toubro's L&T Power Distribution Boards, rated up to 6500A and tailored for Indian and export markets with IP ratings, illustrate how regional strength can be leveraged into export growth when paired with appropriate compliance packaging. Havells' Reo series, up to 3200A for industrial use and compliant with IS/IEC standards, reflects a focus on industrial customers where standard alignment and value pricing matter. CHINT Global's NQ series withdrawable 3-phase boards, rated up to 6600A for global markets, show how Chinese suppliers are scaling beyond domestic demand by offering broad-amperage ranges and international certifications. Mitsubishi Electric's WS/V series, up to 7000A for factory automation, and Fuji Electric's F-MCC and distribution boards, up to 5000A in industrial settings, underline Japan's continued strength in precision-engineered industrial power distribution. LS Electric's Su2000 and Tablo panels, up to 8000A with smart monitoring features, position the company at the intersection of high capacity and digital functionality, an increasingly attractive combination.
Strategic differentiation is converging around three themes. First, high-amperage, application-specific platforms that address arc flash, thermal management, and short-circuit withstand are becoming preferred choices in demanding industrial and data center contexts. Second, modular and prefabricated architectures are gaining traction as buyers seek to reduce installation risk, accelerate commissioning, and support future reconfiguration. Third, digital and certification readiness is serving as a gatekeeper in regulated markets, where UL recognition, IEC compliance, and integration with asset management platforms can determine whether a supplier appears on the finalist list. Recent developments reinforce this pattern: Eaton's arc-resistant xEnergy Pa launch, Siemens' digital twin-enabled SIVACON showcase, ABB's data center-focused TruFit enhancements, and Schneider Electric's UL certification for PrismaStac RT all point to a landscape where safety, digital linkage, and market-specific certification are central to winning complex projects.
Looking ahead, the competitive structure is likely to see selective consolidation among smaller players that lack the scale to absorb compliance costs or the engineering depth to compete on high-current, safety-critical platforms. At the same time, regional specialists with strong local service networks, certification portfolios, and application knowledge can thrive by focusing on segments where global scale is less decisive than responsiveness and specification support. New entrants will find the highest-probability opportunities in converged domains such as digitally enabled boards, prefabricated solutions for fast-track construction, and boards optimized for electrification-driven residential and commercial loads, rather than attempting head-on competition in established high-amperage industrial segments.
Worldwide Three Phase Recloser Market
Future Trends and Commercial Opportunities
Over the next three to five years, digitalization and connectivity will become standard expectations rather than optional upgrades. Distribution boards equipped with monitoring, diagnostics, and integration pathways into building and plant management systems will command preference in commercial and industrial tenders. The commercial opportunity lies in combining hardware with software services, predictive maintenance insights, and energy visibility that help operators optimize load balancing, reduce downtime, and support decarbonization reporting. Suppliers that can deliver interoperable telemetry without compromising safety certification or short-circuit performance will be well placed to capture specification share.
Prefabrication and modularization will continue to gain momentum as project delivery pressures intensify. Labor constraints, scheduling criticality, and the cost of on-site rework are pushing buyers toward engineered assemblies that arrive ready for installation with minimal customization. This trend creates opportunities for suppliers to standardize high-value modules, offer pre-tested configurations, and provide documentation that streamlines commissioning. For industrial customers, modularity also supports future expansions and reconfigurations, making boards that allow selective add-on or rebalancing more attractive over the asset lifecycle.
Three Phase Cast Resin Transformer Market
Electrification-driven load growth in commercial and residential settings will reshape specification patterns. Heat pumps, EV charging infrastructure, and distributed generation are increasing the need for robust 3-phase capacity at the connection point, even in buildings that previously relied on lighter electrical arrangements. This shift opens opportunities for boards designed with headroom, clear upgrade pathways, and compatibility with metering and monitoring requirements that facility managers increasingly demand. The risk is that rapid load growth can outpace existing infrastructure design assumptions, leading to retrofit cycles if early specifications do not anticipate future expansion. Suppliers and specifiers who plan for load scenarios beyond current baselines will reduce downstream friction and capture repeat business through upgrade programs.
These trends carry uncertainty. Raw material price swings can re-emerge quickly, influencing both cost structures and project economics. Regulatory updates may accelerate in response to safety incidents or efficiency targets, increasing certification and redesign burdens. Digital integration, while valuable, introduces cybersecurity and interoperability considerations that buyers will scrutinize more closely as connected systems proliferate. Organizations that proactively manage material exposure, maintain agile certification pathways, and design for both safety and cyber resilience will be better positioned to convert these uncertainties into durable competitive advantages.
Strategic Recommendations for Decision Makers
For manufacturers, the priority is to align product roadmaps with the convergence of safety, modularity, and digital readiness. Investing in arc-resistant designs, high short-circuit withstand capabilities, and prefabricated architectures addresses the specifications that are winning complex industrial and commercial projects. Equally important is building certification breadth in target markets, including UL and IEC pathways, and developing documentation that helps specification engineers justify total installed cost rather than unit price alone. Standardizing modular building blocks while preserving flexibility for custom ratings can improve engineering efficiency and speed response to project-specific requirements.
PW Consulting
For investors, the market offers differentiated exposure across scale players, application specialists, and digital-integration-focused suppliers. Due diligence should assess certification portfolios, short-circuit and arc-flash engineering depth, thermal management innovations, and the ability to support prefabricated delivery models. Companies with strong positions in data center, industrial automation, and electrification-driven segments may offer more resilient growth profiles than those dependent on undifferentiated commodity boards. Monitoring raw material hedging practices and supply chain resilience is also prudent, given the historical sensitivity of copper and steel costs to broader market dynamics.
For procurement and specification teams, the focus should shift toward evaluating total project economics and lifecycle performance. Requesting detailed information on installation labor implications, commissioning support, modularity for future expansion, and monitoring integration can reveal value that unit-price comparisons obscure. Clarifying compliance status, labeling readiness under NEC 2023, and IEC 61439 alignment reduces downstream risk. Engaging suppliers early in the design phase to confirm upgrade paths, thermal requirements, and digital integration options helps avoid retrofit scenarios as loads evolve.
For stakeholders seeking a deeper, segment-level view of regional demand patterns, mounting-type preferences, end-user splits, and company-level benchmarking, the full research report provides detailed datasets and tailored strategic guidance to support procurement planning, product portfolio decisions, and investment prioritization.
For detailed analysis of this topic, please visit the official page: Worldwide 3-Phase Distribution Boards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com