

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Passenger Vehicle Window Regulator Market: The 5.71% CAGR Shift

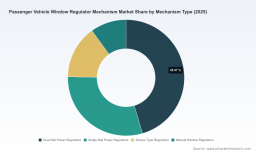
Strategic Shifts and Commercial Opportunities in the Global Passenger Vehicle Window Regulator Mechanism Market
Market Current State and Core Challenges
The global market for passenger vehicle window regulator mechanisms continues to demonstrate steady expansion, reflecting broader trends in automotive manufacturing and consumer preferences. From 2020 to 2025, the market grew from approximately USD 11,250 million to USD 14,854 million, establishing a solid foundation for the projection period of 2026 through 2032. Forecasts indicate a compound annual growth rate of 5.71 percent, which suggests that the sector will sustain momentum despite macroeconomic fluctuations and periodic supply chain disruptions. This trajectory is not merely a function of rising vehicle production volumes but also signals a structural transition in how window regulators are designed, integrated, and valued within the passenger vehicle ecosystem.
As the market approaches the mid-twenties, several inflection points are reshaping competitive dynamics and forcing suppliers to reconsider their operational and strategic postures. The first critical challenge lies in balancing cost efficiency with escalating performance expectations. Traditional mechanical and cable-driven mechanisms are being pressured by demands for smoother operation, faster response times, and seamless integration into increasingly complex door assemblies. Suppliers that fail to upgrade their manufacturing processes or redesign components for scalability risk margin erosion as OEMs push for unit cost reductions while maintaining or improving quality thresholds.
A second major challenge stems from the tightening regulatory environment across key automotive markets. Safety mandates now require anti-pinch technology, electronic monitoring, and one-touch operation features as standard elements in power window systems. These requirements impose additional design complexity, testing burdens, and component costs. Companies that rely on legacy mechanical designs without electronic integration face a widening gap between regulatory compliance and market expectations. The transition toward electronic controls also demands changes in talent acquisition, validation protocols, and supplier qualification processes, which can strain organizations that are not prepared for this shift.
The third challenge is the growing importance of lightweighting and material substitution. Weight reduction has become a strategic priority for OEMs seeking to improve fuel efficiency and support emissions targets, particularly as electrification gains traction across multiple vehicle segments. This trend places pressure on component suppliers to replace conventional steel-based structures with aluminum or engineering plastics. However, raw material price volatility introduces uncertainty into manufacturing margins, and switching materials requires extensive revalidation, tooling investment, and long-term supplier agreements. Navigating this transition requires disciplined execution rather than reactive adjustments.
At the same time, integration is accelerating. Window regulators are no longer viewed as isolated components but as modules embedded within broader door systems that include motors, wiring harnesses, and electronic control functions. This shift simplifies OEM assembly, reduces overall vehicle weight, and creates new opportunities for differentiation. Suppliers that can deliver fully integrated, validated door closure solutions are gaining a structural advantage, while those competing solely on standalone component pricing are seeing their strategic relevance diminish.
Key Drivers Analysis
Technological Innovation and Intelligent Integration
One of the most significant forces shaping the market is the evolution from purely mechanical window regulators to intelligent, electronically controlled systems. Anti-pinch functionality, automatic window positioning, and personalized settings are increasingly expected by consumers, particularly in mid-to-premium vehicle segments. The push toward digitized comfort features has encouraged suppliers to embed sensors, control logic, and communication interfaces directly into window mechanisms. A notable example of this direction is the debut of an intelligent window regulator featuring electrification, personalized light dimming, and privacy settings, which was introduced for global rollout following a China-focused initiative. Such developments signal that window regulators are becoming part of a broader user experience narrative rather than remaining purely functional hardware.
Beyond comfort, integration into complete door modules has emerged as a powerful design driver. Combining motors, regulators, wiring, and electronic components into unified assemblies reduces the number of discrete parts, streamlines OEM assembly, and supports weight reduction goals. Suppliers that have invested in modular architectures and door-level integration capabilities are better positioned to win long-term OEM contracts, especially as vehicle architectures move toward more consolidated and software-defined approaches.
Policy and Regulatory Influence
Regulatory requirements continue to exert a strong influence on product design and market adoption. Mandatory anti-pinch technology and one-touch operation standards across North America, Europe, and other major markets have effectively shifted the baseline for power window systems. These regulations are not static; they continue to evolve, and manufacturers must anticipate future revisions related to child safety, electronic validation, and system reliability. Compliance is no longer optional, and companies that treat safety as a minimum requirement rather than a design foundation risk losing credibility with OEMs that are under increasing scrutiny from regulators and consumers alike.
Safety-driven requirements also create a feedback loop with technology development. The need to meet anti-pinch standards has accelerated investment in electronic controls, motor controllers, and sensor-based feedback loops. This, in turn, raises the barrier to entry for low-complexity, low-cost players and reinforces the position of suppliers with stronger engineering capabilities and established validation processes.
Demand-Side Behavior and Electrification
Consumer expectations are changing the value proposition of window regulators. In many markets, power windows and associated comfort features are no longer premium add-ons but baseline expectations for a wide range of passenger vehicles. As consumers become accustomed to smooth, quiet, and responsive window operation, automakers face mounting pressure to maintain consistent quality across model lines. This is especially relevant in emerging and mid-tier segments, where cost constraints must be balanced with feature parity.
Electrification adds another layer of demand-side influence. As vehicle platforms shift toward electric architectures, weight and energy efficiency considerations become more pronounced. While window regulators are individually low-load components, their cumulative contribution to vehicle mass matters in the context of battery range optimization. This reinforces the push toward lightweight designs and materials that can deliver durability without adding unnecessary weight. Demand is therefore being shaped not only by comfort expectations but also by the broader efficiency logic of modern vehicle design.
Supply Chain and Cost Structure Dynamics
Material composition and pricing volatility form another critical driver influencing margins and sourcing strategies. Window regulators primarily rely on steel for durability in high-stress applications, yet there is growing adoption of aluminum and engineering plastics to reduce weight and meet efficiency targets. This creates a dual pressure: suppliers must manage the cost implications of raw material fluctuations while also investing in material innovation and manufacturing flexibility.
Worldwide Automotive Stabilizer Bar Link Market
Price volatility in steel, aluminum, and plastics can quickly compress margins for components that depend heavily on these inputs, especially for cable, scissor, and frame structures. Companies that maintain rigid cost models or single-source procurement strategies risk exposure when input prices move unexpectedly. In contrast, suppliers that diversify materials, negotiate flexible contracts, and incorporate value engineering into their design cycles are better able to protect profitability. The transition toward new materials also requires reevaluation of production lines, testing protocols, and supplier relationships, which can be both an operational burden and a competitive differentiator.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a concentrated group of established players alongside a broad set of specialized suppliers that compete on niche capabilities, regional strength, or customization. The market structure reflects meaningful concentration at the top, with leading firms holding substantial shares of global demand. This concentration indicates that scale, engineering depth, and long-term OEM relationships remain powerful advantages in a market where validation cycles are long and switching costs can be high.
Brose Fahrzeugteile SE & Co. KG stands out for its focus on mechatronic door systems and intelligent window regulator functions. Its recent activities illustrate a dual strategy of product innovation and regional expansion. The debut of an intelligent window regulator with electrification, personalized light dimming, and privacy settings was positioned for global rollout following a China-oriented initiative. In parallel, the company showcased door and window regulator solutions under a theme emphasizing experience and modular design, while highlighting three decades of development in China. This approach reflects an effort to combine advanced functionality with localized presence and modular architectures that can be adapted across programs.
Valeo SA offers OE-quality window regulator mechanisms, including Bowden and cable types, with comfort functions and anti-pinch features for passenger cars and light commercial vehicles. Its strength lies in broad coverage of European and global manufacturers, which provides scale and the ability to respond to varied OEM requirements. The emphasis on comfort functions and anti-pinch integration aligns well with regulatory demands and consumer expectations, supporting a position based on proven compliance and wide application coverage.
Automotive Power Window Motor Market
HI-LEX Corporation has built a strong production footprint, manufacturing more than ten million window regulators annually using in-house molded components. This vertical approach supports reliability and cost efficiency, giving the company a durable edge in passenger vehicle applications where consistency and unit economics matter. The scale of output also implies a level of manufacturing maturity that can be attractive to OEMs seeking dependable supply continuity.
Magna International Inc., through its closures business, focuses on window regulators and integrated closure systems with an emphasis on lightweight design and complete door modules. This integration-oriented strategy matches the broader industry direction toward simplified assembly and weight reduction. By offering door-level solutions rather than standalone parts, Magna positions itself to capture more value from system-level requirements and to participate in early design discussions with OEMs.
Grupo Antolin Irausa S.A. provides window regulator mechanisms within interior and closure systems for passenger cars, emphasizing smart and lightweight solutions. This positioning reflects the growing expectation that window regulators must contribute to overall vehicle comfort, packaging efficiency, and mass optimization. Companies that treat window regulation as part of a broader interior and closure strategy can generate more integrated value propositions for customers.
Several Japanese suppliers, including Aisin Corporation, Shiroki Corporation, Denso Corporation, and others, continue to play important roles in power window regulators, lift motors, and associated components. Their strengths often lie in manufacturing discipline, application breadth across Asian, domestic, and European programs, and established relationships with major automakers. Robert Bosch GmbH contributes to the ecosystem through window lift motors and regulator components embedded in power window systems, often for premium OEM models. This reinforces the value of motor and electronic integration capabilities as a strategic differentiator.
Smaller and more specialized participants also shape the market in distinctive ways. MarchantCain Automotive designs and manufactures custom window regulators for mid- and low-volume passenger vehicle manufacturers, offering flexibility that can be attractive for niche or specialty applications. Politecnica 80 manufactures electrical window regulators and lifter kits across a broad model range for passenger cars, commercial vehicles, and industrial vehicles, with a large share of components produced in Italy. Han Yale, an IATF 16949-certified manufacturer, focuses on aftermarket and OE-style regulators and motors with a wide SKU coverage for major passenger vehicle brands. These players illustrate that while scale matters, there remain viable paths based on customization, regional sourcing, and aftermarket breadth.
The competitive landscape is evolving along several axes. Integration and module-level supply are becoming more important, favoring suppliers that can deliver door-ready solutions rather than isolated components. At the same time, regional dynamics matter: strong local presence can support faster responsiveness, program alignment, and cost competitiveness, especially in markets where OEMs prioritize sourcing flexibility. Market concentration at the top indicates that leadership is increasingly tied to engineering sophistication, compliance capability, and integration expertise, while fragmentation persists in specialized niches, aftermarket channels, and lower-volume applications.
Future Trends Forecast
Looking ahead to the next three to five years, several trends are likely to define the direction of the market. The first is the continued shift toward intelligent window regulation functions. As consumer expectations around comfort, privacy, and personalization rise, window mechanisms will increasingly incorporate electronic controls, customizable settings, and interaction with broader vehicle systems. This opens opportunities for suppliers that can deliver not only reliable mechanical performance but also software-compatible, function-rich solutions that support differentiated cabin experiences.
The second trend is the acceleration of lightweighting through material innovation and module integration. As efficiency targets tighten and electrified platforms expand, the incentive to reduce component mass will remain strong. Adoption of aluminum and engineering plastics is expected to grow where durability and cost allow, and suppliers capable of validated material transitions will benefit. Integration into door modules will also deepen, since consolidated assemblies can reduce part counts, simplify assembly, and support weight and packaging goals simultaneously.
The third trend involves ongoing regulatory pressure and standardization of safety features. Anti-pinch technology, one-touch operation, and related electronic controls are likely to remain baseline requirements across major markets, and future updates may impose additional validation or functional expectations. The commercial opportunity here lies in making compliance a source of competitive advantage rather than a cost burden. Suppliers that design for reliability, test thoroughly, and demonstrate consistent performance can use safety capability as a trust signal to OEMs.
Potential risks and uncertainties should not be overlooked. Raw material price volatility can compress margins if not managed proactively. The transition to new materials and integrated architectures may require significant investment and revalidation, creating execution risk for some players. There is also the risk that cost pressures from OEMs could limit pricing flexibility, particularly in high-volume segments. Finally, regional trade dynamics and supply chain disruptions could affect sourcing strategies, lead times, and inventory planning, making resilience a key capability for the forecast period.
Actionable Insights for Decision Makers
For manufacturers, the priority is to strengthen integration capabilities and electronic expertise. Investment in anti-pinch technology, door module integration, and lightweight material strategies should be assessed against near-term program pipelines and long-term platform roadmaps. Companies that can demonstrate modular, validated, and weight-efficient solutions will be better positioned to secure OEM commitments and defend margins in a competitive environment. At the same time, supply chain flexibility around materials and supplier diversification should be treated as a strategic safeguard rather than a tactical concern.
For investors, due diligence should focus on companies with proven compliance capabilities, scalable manufacturing, and a clear route to intelligent, integrated solutions. Scale and concentration at the top of the market suggest that durable advantages will accrue to firms that combine engineering depth with regional reach and application breadth. It is also worth evaluating exposure to material volatility and the ability to transition to aluminum or engineering plastics without sacrificing quality or profitability. Companies that can balance cost discipline with product sophistication are likely to generate more resilient value over the forecast period.
PW Consulting
For procurement and sourcing teams, the strategic emphasis should be on partnering with suppliers that can support integration, validation, and material flexibility rather than selecting solely on unit price. As window regulators increasingly become part of broader door systems, the cost of poor integration, rework, or compliance gaps can outweigh apparent savings. Building relationships with suppliers that offer modular designs, strong safety credentials, and reliable production capacity can reduce downstream risk and improve program execution. Given the speed of technological and regulatory change, access to current, segmented market intelligence can help teams anticipate shifts in demand, pricing, and competitive positioning before they affect sourcing decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Passenger Vehicle Window Regulator Mechanism Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com