

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Gas-Insulated Transformers Market: Where 6.25% CAGR Meets Regional Shifts

Navigating the Global Gas-Insulated Transformer Market: Strategic Trends & Commercial Opportunities
Market Overview & Core Challenges
The global gas-insulated transformer (GIT) market has demonstrated steady expansion over the past half-decade, with total revenue climbing from approximately USD 1.58 billion in 2020 to a projected USD 2.14 billion in 2025. Looking toward the end of the forecast window in 2032, market valuation is expected to approach USD 3.27 billion. This trajectory implies a compound annual growth rate of 6.25 percent from 2025 through 2032, signaling a market that is scaling at a pace driven by structural electrification needs rather than cyclical demand spikes. The consistency of this growth curve reflects a fundamental shift in how utilities, industrial operators, and urban planners approach high-voltage infrastructure, particularly in environments where spatial constraints, safety requirements, or atmospheric conditions make traditional air-insulated solutions impractical.
Despite the favorable headline trajectory, the sector faces three interconnected challenges that are reshaping investment decisions and product roadmaps. First, the environmental profile of sulfur hexafluoride (SF6) remains the most prominent friction point. Regulatory scrutiny has intensified across multiple jurisdictions, with updated reporting mandates in the United States requiring facilities meeting specific emission thresholds to disclose SF6 and perfluorocarbon emissions through the Greenhouse Gas Reporting Program, effective January 2025. This regulatory pivot moves away from nameplate capacity benchmarks toward actual emission volumes, placing greater compliance burdens on operators and manufacturers alike. Second, the supply chain for industrial-grade SF6 has experienced volatility, with global pricing averaging between USD 4 and 9 per kilogram and power-sector procurement hovering around USD 6.5 per kilogram. Cost variability, combined with tightening availability expectations, forces procurement teams to weigh insulation performance against long-term input cost exposure. Third, the market is navigating an accelerating transition toward alternative and green insulating gases, which introduces both engineering complexity and capital reallocation pressures. Manufacturers must balance proven SF6-based designs with next-generation formulations that meet safety and dielectric standards without compromising reliability or extending time-to-market.
These challenges do not threaten the market's expansion but rather redefine where value accrues. Companies that treat environmental compliance as a design parameter rather than a retrospective adjustment are positioning themselves to capture premium segments, while operators evaluating GIT procurement are increasingly factoring total cost of ownership, emission liability, and future-proofing into their specifications.
Key Drivers of Market Change
Technological innovation continues to act as a primary catalyst for GIT adoption, with engineering advances focusing on compact footprint, enhanced thermal management, and integrated grid compatibility. Urbanization and the densification of power networks have made space-constrained substations a defining requirement, pushing manufacturers to refine gas-insulated enclosures that deliver higher power density without sacrificing breakdown voltage or operational stability. Recent project deployments illustrate this trajectory: in June 2024, seven GIT units from Toshiba Energy Systems & Solutions entered commercial operation at the Haram 2 and Haram 3 substations serving Makkah, Saudi Arabia, where high-safety, non-flammable designs were prioritized for dense urban settings. This example underscores how performance requirements in congested environments are directly translating into procurement decisions, particularly when public safety and operational continuity are non-negotiable.
Worldwide Environmentally Friendly Gas Insulated Switchgear Market
Policy and regulatory dynamics are simultaneously reshaping the competitive landscape. The electrical transmission and distribution sector remains a significant contributor to SF6 emissions, with U.S. reporting indicating that roughly 67 percent of national SF6 emissions in 2022 originated from this segment. Such exposure has accelerated regulatory momentum and voluntary industry commitments aimed at reducing reliance on high-global-warming-potential gases. The result is a dual-track environment: established SF6-based systems continue to serve high-voltage applications where dielectric performance is paramount, while a growing cohort of buyers is evaluating SF6-free alternatives for specific voltage classes and deployment contexts. Regulatory shifts are therefore not simply compliance events; they are influencing product portfolios, R&D prioritization, and the relative attractiveness of different insulation mediums across the voltage spectrum.
Demand-side behavior is evolving as utilities and industrial operators reconsider lifecycle economics. The push toward grid modernization, increased integration of distributed generation, and the need for resilient transmission infrastructure are expanding the use cases for gas-insulated equipment beyond traditional utility deployments. Industrial facilities operating in harsh or confined environments are increasingly specifying GITs for their non-flammable characteristics and reduced maintenance footprints, while large-scale urban infrastructure projects favor compact designs that minimize civil works and land acquisition costs. This broadening demand base is creating cross-sector pull that reinforces volume growth even as individual procurement criteria diverge.
Supply chain and cost structures remain a critical variable. SF6 pricing fluctuations introduce margin sensitivity for manufacturers and total-cost uncertainty for buyers, particularly when insulation medium selection is tied to long-term service agreements or multi-year infrastructure programs. At the same time, the emergence of alternative gas formulations is altering cost calculus over the asset lifecycle. While some green alternatives may carry different procurement or processing considerations, they can reduce exposure to emissions-related reporting, potential future pricing penalties, and reputational risk. The interplay between raw material economics, regulatory exposure, and engineering trade-offs is becoming a central factor in both product design and procurement strategy.
Competitive Landscape & Leading Strategies
The market structure reflects a moderately concentrated field, with the top three participants accounting for approximately 55.5 percent of revenue and the top five representing roughly 72.8 percent. This concentration indicates that scale, technology depth, and global service networks confer meaningful advantages, yet it also leaves room for specialized players to compete on voltage range, regional presence, or application-specific engineering. Hitachi Energy, headquartered in Zurich, operates GIT offerings as part of broader high-voltage transmission solutions, emphasizing reliability, compact design for space-limited applications, and integration with grid infrastructure. The company has been actively expanding transformer manufacturing capacity, signaling a strategy centered on capturing volume growth while reinforcing supply assurance. Siemens Energy, based in Munich, positions its GIT portfolio within an integrated energy equipment framework, targeting efficient high-voltage transmission for utilities and industrial users. Its approach emphasizes system-level compatibility and operational efficiency across demanding service environments.
GE Vernova's Grid Solutions unit, located in Cambridge, Massachusetts, supplies GITs and related grid solutions with a focus on reliable power delivery in utility and high-demand sectors. Its competitive positioning leans on brand recognition, global project execution experience, and the ability to align transformer specifications with broader grid modernization initiatives. Mitsubishi Electric, headquartered in Tokyo, manufactures GITs with an emphasis on high-performance energy systems and has been advancing SF6-free alternatives for sustainable grid applications. This dual focus on performance and environmental alignment reflects a strategy that anticipates regulatory and buyer preferences without retreating from proven high-voltage capability. Toshiba Energy Systems & Solutions, also based in Tokyo, specializes in GITs engineered for challenging environments, offering non-flammable, high-safety designs up to 500 kV, and has demonstrated execution in dense urban substation projects. Its emphasis on safety-critical design differentiates its offering in applications where public proximity and operational risk are primary concerns.
Beyond these larger players, the competitive field includes strong regional and application-focused contributors. Hyundai Electric, based in South Korea, produces gas-insulated equipment optimized for compact installation and high reliability in transmission and distribution networks. Arteche Group, headquartered in Spain, supplies gas-insulated voltage and instrument transformers for GIS substations up to 525 kV, concentrating on measurement, protection, and auxiliary services within shielded environments. Fuji Electric, also in Tokyo, offers gas-insulated switchgear and related transformer technologies with modular, compact designs for high-voltage applications. Hyosung Heavy Industries, another South Korean participant, provides GITs within its power equipment lineup, emphasizing reliability and environmental considerations in energy systems. Meidensha Corporation, based in Tokyo, manufactures GITs for power transmission and distribution, supporting utility and industrial sectors with application-tailored solutions.
PW Consulting
The competitive dynamics are evolving along two axes. On one hand, scale players are investing in capacity and system integration to secure share in large transmission and urban substation programs, effectively competing on delivery certainty, global reach, and portfolio breadth. On the other hand, differentiation is increasingly tied to insulation medium strategy, safety credentials, and modularity. Companies that can offer SF6-free or low-emission options without compromising dielectric performance are opening new discussion points with procurement teams sensitive to compliance and lifecycle emissions. At the same time, specialized manufacturers are carving out positions in high-voltage niche applications, measurement and protection ecosystems, and modular deployments that reduce installation complexity. The net effect is a landscape where consolidation pressure exists at the top, but segmentation by voltage class, insulation approach, and geographic execution capability continues to create targeted opportunities.
Forward-Looking Trends & Commercial Opportunities
Over the next three to five years, the GIT market is likely to be shaped by three interrelated trends. The first is the broadening commercialization of alternative and green insulating gases across select voltage classes. As engineering validation deepens and standardization efforts advance, a wider set of projects will evaluate SF6-free options, particularly where regulatory exposure, procurement policies, or sustainability commitments influence specification decisions. For manufacturers, this creates an opportunity to lead with differentiated product lines, secure early reference projects, and build expertise that becomes a barrier to entry for slower-moving competitors. For buyers, it introduces more choice in balancing dielectric performance, emissions profile, and long-term compliance risk.
The second trend is the continued intensifying of urban and space-constrained deployments. As cities expand electrical capacity to support economic growth, electrification of transport and industry, and resilience requirements, compact gas-insulated solutions will remain highly relevant. This trend favors suppliers that can deliver high power density, rapid installation, and safety-oriented designs, while also creating opportunities for modular and repeatable substation configurations that reduce civil engineering overhead. Projects in high-density environments will increasingly reward proven safety credentials and localized execution capability, making track record and site-specific engineering critical differentiators.
The third trend involves regulatory and reporting frameworks becoming more operationalized. Updates such as the U.S. EPA Greenhouse Gas Reporting Program shift toward emission-volume thresholds will expand visibility into SF6 usage and leakage across the transmission and distribution sector. This increased transparency is likely to sharpen buyer focus on leak prevention, service practices, and end-of-life handling, while also accelerating preference for designs that reduce emission exposure over the asset's life. Commercial opportunities will emerge for suppliers that integrate monitoring, maintenance, and decommissioning considerations into their value proposition, and for buyers who align procurement with emission-management roadmaps rather than treating compliance as a separate function.
Potential risks and uncertainties should be acknowledged. Alternative gas technologies may face varying acceptance curves across regions and voltage classes, and performance validation in extreme conditions can extend adoption timelines. Cost dynamics for both SF6 and newer insulation mediums may fluctuate with industrial demand, logistics constraints, and regulatory interventions, complicating long-term budgeting. In addition, supply chain capacity expansions by major vendors could alter lead-time expectations and negotiate leverage for large programs, while localized content expectations in certain markets may affect sourcing strategies. These variables do not invalidate the growth outlook but do require scenario-aware planning.
Strategic Recommendations for Decision-Makers
For manufacturers and technology providers, the priority is to align product development with the dual demands of performance and environmental alignment. Investing in SF6-free or low-emission alternatives should be paired with rigorous validation across target voltage classes and environments, so that differentiation is grounded in proven reliability rather than aspirational claims. At the same time, capacity and supply chain planning should account for the possibility that procurement teams will increasingly weigh insulation medium choice alongside delivery certainty, service coverage, and total cost of ownership. Companies that can articulate a clear roadmap across insulation mediums, voltage segments, and deployment contexts will be better positioned to participate in both legacy SF6 programs and next-generation specifications.
Cast Resin Transformers Market
For investors evaluating exposure to this market, the relevant question is not whether growth will continue, but where value will concentrate. Interest should focus on participants with credible insulation-medium strategies, demonstrated execution in safety-critical or space-constrained projects, and the ability to serve multiple voltage classes without over-reliance on a single regional market. Portfolio considerations should also include exposure to service, retrofit, and lifecycle management capabilities, since reporting and emission-management expectations are likely to increase the commercial importance of long-term support relationships. Monitoring regulatory developments and raw material cost trends will remain essential for timing commitments and assessing margin resilience.
For procurement and infrastructure planners, the operative need is to broaden evaluation criteria beyond initial unit cost. Specifications should incorporate insulation medium implications, emission reporting exposure, safety requirements for the deployment environment, and compatibility with grid integration plans. Where projects are long-lived, scenario planning around alternative gases and regulatory evolution can reduce future rework risk and provide negotiating leverage. Early engagement with suppliers that offer modular designs, strong safety credentials, and clear service frameworks can improve delivery predictability and reduce lifecycle friction, particularly in dense urban or high-reliability settings.
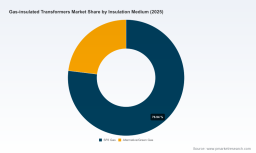
For stakeholders seeking a more detailed view of segmentation dynamics, regional nuance, voltage-class outlooks, insulation-medium splits, and company-specific positioning, a comprehensive research report provides the depth required to translate these strategic themes into procurement specifications, investment theses, and product planning decisions. Detailed breakdowns of market size paths, competitive benchmarks, and scenario analysis can support more precise go-to-market and sourcing choices across the forecast horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Gas-insulated Transformers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com