

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide X-ray Phosphor Market: Why 6.8% CAGR and Medical Imaging Redefine 2026 Growth

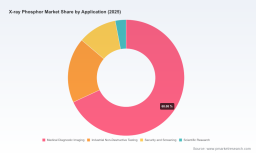
Global X-ray Phosphor Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview: Navigating Growth Amid Transformation
The worldwide market for X-ray phosphors has entered a phase of steady expansion, driven by the broader transition from analog film-based radiography to digital imaging ecosystems. Valued at approximately 565.4 million USD in 2020, the market reached an estimated 762.24 million USD by 2025. Projections indicate continued growth through the end of the decade, with revenues anticipated to approach 1.2 billion USD by 2032, supported by a compound annual growth rate of 6.8 percent. This trajectory reflects the ongoing modernization of diagnostic imaging infrastructure, the expansion of non-destructive testing requirements in advanced manufacturing, and the steady modernization of security screening systems at transportation and facility checkpoints.
Despite the favorable growth outlook, the industry is navigating several structural shifts that will define competitive positioning over the next several years. One of the most significant challenges lies in the materials transition between established phosphor chemistries and next-generation scintillator formulations. While certain rare-earth based phosphors have delivered substantial improvements in X-ray-to-light conversion efficiency, alternative columnar scintillator materials are gaining ground in applications demanding higher spatial resolution and faster readout speeds. Manufacturers and end-users must evaluate performance trade-offs, long-term reliability, and total cost of ownership rather than focusing solely on conversion efficiency metrics.
A second challenge centers on regulatory complexity and the pace of clinical and industrial adoption. Imaging devices that incorporate phosphor-based detectors increasingly require formal clearance processes, with regulatory bodies scrutinizing image enhancement algorithms, dose reduction claims, and equivalence to predicate systems. These requirements extend product development timelines and raise compliance costs, particularly for vendors introducing innovative scintillator architectures or hybrid detector designs. At the same time, procurement cycles in healthcare and industrial sectors are becoming more value-driven, with hospitals, service providers, and manufacturing firms demanding demonstrable improvements in workflow efficiency, durability, and lifecycle economics.
A third inflection point involves supply chain resilience and raw material availability. The production of high-performance phosphors depends on specialized rare-earth elements and precision coating or deposition processes. Geopolitical dynamics, export controls, and fluctuations in upstream material pricing can compress margins and create bottlenecks for downstream detector manufacturers. Companies that have relied on single-source procurement or limited regional supply networks are now reevaluating their sourcing strategies, inventory buffers, and qualification pathways to reduce exposure to disruption.
Key Drivers Shaping Market Direction
Several interconnected forces are accelerating demand for advanced phosphors and reshaping how value is created across the imaging value chain. Understanding these drivers is essential for manufacturers, investors, and procurement leaders who need to anticipate where demand will concentrate and which product attributes will command premium positioning.
Technological innovation remains the most visible catalyst. The push toward higher-resolution digital detectors, faster image acquisition, and dose-efficient imaging protocols has intensified the focus on scintillator performance. Conventional phosphor screens are being supplemented or replaced by structured scintillator layers that improve light guide efficiency and reduce blur, particularly in applications where fine detail matters. Flexible and conformable scintillator formats are also expanding design options for detectors used in non-standard form factors, enabling integration into portable systems, curved surfaces, and specialized industrial inspection setups. At the same time, advancements in phosphor powder morphology, particle size control, and substrate adhesion are improving uniformity and consistency across production batches, which is critical for high-volume medical and industrial manufacturing.
Policy and regulatory developments are reinforcing demand for dose-efficient and diagnostically reliable imaging solutions. Authorities and clinical institutions are increasingly prioritizing technologies that reduce patient exposure while maintaining image quality, especially in high-volume diagnostic settings and screening programs. This emphasis favors phosphors that improve conversion efficiency and support lower-dose protocols. Regulatory pathways for imaging devices continue to evolve, with clearance requirements extending beyond hardware performance to include software-driven image processing and system-level equivalence. For phosphor suppliers, this environment rewards established materials with well-characterized performance profiles as well as new formulations that can demonstrate clear benefits in validation and clearance processes.
Demand-side behavior is shifting as end-users adopt a more comprehensive view of imaging economics. In medical diagnostics, healthcare providers are balancing capital expenditure constraints with the need to expand imaging capacity, improve throughput, and support aging populations and chronic disease management. This has increased interest in detector technologies that integrate efficiently with existing digital workflows and reduce re-examination rates. In industrial non-destructive testing, the growth of advanced manufacturing, aerospace component verification, and infrastructure inspection is expanding the use of X-ray imaging for quality assurance. Meanwhile, security and screening applications continue to modernize as facilities seek faster throughput, improved material discrimination, and more adaptable screening architectures. Across these segments, buyers are prioritizing solutions that combine performance with robustness, serviceability, and predictable operating costs.
Supply chain and cost dynamics are also reshaping competitive dynamics. The cost structure of phosphor production is influenced by raw material availability, precision manufacturing requirements, and the cost of qualifying new materials for regulated applications. Firms that can stabilize input costs, maintain tight process control, and scale production without sacrificing performance gain an advantage in price-sensitive segments. Conversely, premium niches are emerging for specialized scintillators that deliver measurable gains in resolution, speed, or mechanical flexibility. This bifurcation is encouraging companies to segment their portfolios more deliberately, aligning product lines with distinct application requirements rather than competing on a single performance dimension.
Competitive Landscape and Leadership Strategies
The X-ray phosphor market is characterized by a mix of specialized scintillator producers, established imaging materials suppliers, and larger healthcare technology companies with deep integration into detector ecosystems. Competitive advantage is increasingly defined not only by material performance but also by the ability to support downstream customers through application engineering, qualification support, and supply reliability.
Scintacor has built a recognized position in phosphor-based scintillators and X-ray screens for medical imaging, with product families designed to balance brightness and resolution for radiography and digital systems. Its recent introduction of a high-brightness, flexible caesium iodide scintillator illustrates a broader industry move toward form factors that enable new detector designs and application flexibility. By expanding into flexible scintillator options, Scintacor is targeting use cases where traditional rigid screens are less suitable, including portable and specialized imaging configurations. This product direction signals how material suppliers are seeking growth beyond standard intensifying screen applications by addressing detector design constraints directly.
Rare Earth Phosphors Market
Mitsubishi Chemical Corporation continues to strengthen its presence through gadolinium oxysulfide-based scintillator screens used in medical diagnostics, baggage inspection, and industrial applications. Its emphasis on stability and cost performance reflects the importance of reliable operation in high-volume environments where downtime and replacement frequency directly affect total cost of ownership. In indirect conversion digital detectors, such phosphor technologies are valued for consistent long-term behavior, an attribute that can be as decisive as peak conversion efficiency for operators managing large installed bases.
Carestream Health offers rare-earth intensifying screens designed to convert X-ray energy into visible light more efficiently than conventional alternatives, supporting dose reduction in medical and industrial radiography. This value proposition aligns with the broader clinical and operational priority of achieving diagnostic quality while minimizing exposure and improving throughput. Agfa HealthCare brings historical depth in photostimulable storage phosphors and green-emitting intensifying screens, reinforcing the continued relevance of computed radiography pathways and specialized screen technologies in settings where digital detector upgrade cycles vary by region and facility type.
Hamamatsu Photonics contributes a broad portfolio of high-performance scintillators on diverse substrates, including fiber optic plates, amorphous carbon, and flexible sheet formats. This substrate breadth enables tailored solutions for medical and industrial detectors that require specific mechanical, optical, or geometric characteristics. Boston Applied Technologies focuses on phosphor powders for intensifying screens and imaging devices, supporting manufacturers that integrate phosphors into their own detector architectures. Niterra Materials, formerly Toshiba Materials, supplies sheet-type scintillators across multiple phosphor families, including gadolinium-based and barium-based formulations for medical and high-speed applications, underscoring the continued segmentation between general diagnostic use and speed-sensitive imaging requirements.
The competitive landscape is evolving along several axes. First, consolidation pressure is building as larger imaging technology providers seek to secure reliable phosphor supply and reduce qualification risk, while specialized manufacturers look to expand their application reach through product diversification. Second, differentiation is shifting from material-only competition to system-relevant performance, including flexibility, durability, substrate compatibility, and support for dose-efficient workflows. Third, new entrants and technology spin-offs are exploring niche opportunities in flexible scintillators, specialized phosphor formulations, and application-specific detector integration, particularly where existing solutions do not fully address form-factor or performance constraints. For incumbents, the strategic imperative is to combine material expertise with customer-facing engineering support and resilient supply operations. For newer players, the opportunity lies in solving clear design limitations that are difficult for broader portfolios to address quickly.
Forward Outlook: Trends and Commercial Implications
Over the next three to five years, the market is likely to be shaped by the continued migration toward dose-efficient, high-resolution digital imaging and by the broadening use of X-ray inspection beyond traditional medical settings. One key trend is the growing importance of scintillator architectures that balance resolution, brightness, and mechanical adaptability. As portable imaging, specialized industrial inspection, and non-standard detector geometries become more common, demand will increasingly reward phosphors that can be integrated into flexible or custom-form-factor devices without sacrificing consistent performance.
PW Consulting
A second trend is the rising emphasis on lifecycle value and regulatory readiness. End-users are expected to favor materials and detector configurations that simplify qualification, support stable long-term operation, and align with dose-reduction goals. This will strengthen the position of established phosphor families in high-volume applications while creating openings for differentiated products in segments where speed, flexibility, or resolution provide measurable operational benefits.
A third trend involves supply chain diversification and material risk management. Organizations that depend on concentrated sourcing for critical phosphor inputs will continue to explore multi-region procurement, alternative material pathways, and qualification strategies that reduce single-point vulnerability. The commercial opportunity here lies in providing customers with predictable availability, transparent quality documentation, and application support that accelerates integration and reduces time to deployment.
These trends also carry uncertainty. Regulatory requirements may become more demanding as imaging systems incorporate advanced enhancement functions and hybrid detection methods. Raw material costs and geopolitical factors could affect pricing stability. In addition, the pace of adoption for newer scintillator formats will depend on clinical and industrial validation, service infrastructure, and the willingness of end-users to modify established workflows. Companies that plan for these variables rather than assuming linear adoption will be better positioned to capture value.
Strategic Recommendations for Decision-Makers
Manufacturers should align product roadmaps with application-specific performance needs rather than competing solely on generic efficiency metrics. Prioritizing flexible or specialized scintillator options, strengthening substrate and coating process control, and investing in qualification support can differentiate offerings in both premium and volume segments. Building resilient sourcing and clear documentation for material consistency will also help reduce friction in regulated and high-volume deployment environments.
Investors should evaluate opportunities based on how well companies can connect material performance to downstream customer value, including workflow efficiency, dose management, and total cost of ownership. Attention to supply chain robustness, regulatory readiness, and the ability to serve both established and emerging application areas will be critical indicators of long-term competitiveness. Segments where phosphor design directly addresses a measurable detector limitation may offer particularly attractive differentiation potential.
X-ray Detectors Market
Procurement and operations leaders should look beyond unit price and assess the full performance and reliability profile of phosphor solutions. Prioritizing suppliers that can demonstrate stable quality, application engineering support, and practical pathways for integration will reduce implementation risk and improve long-term operating outcomes. As requirements vary widely across medical, industrial, and security applications, tailored evaluations that consider form factor, throughput, durability, and compliance alignment will yield better decisions than one-size-fits-all purchasing criteria.
For organizations seeking detailed segmentation data, regional breakdowns, and customized strategic recommendations, the full PW Consulting market study provides deeper analysis across product types, application areas, and competitive dynamics.
For detailed analysis of this topic, please visit the official page: Worldwide X-ray Phosphor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com