

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
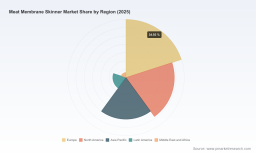
Meat Membrane Skinner Market: How 4.85% CAGR and Europe’s 186M Share Reshape Meat Processing Strategy

Navigating the Global Meat Membrane Skinner Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The worldwide meat membrane skinner market is undergoing a measured but meaningful transformation, characterized by steady expansion and evolving processing requirements. Valued at approximately USD 418.4 million in 2020, the market has grown consistently to reach USD 532.5 million in 2025. The trajectory reflects a compound annual growth rate of 4.85 percent across the 2026-2032 forecast period, with revenue projected to approach USD 741.8 million by 2032. This expansion is not accidental; it is the result of sustained capital investment in meat processing infrastructure, shifting operational priorities among processors, and the gradual replacement of labor-intensive manual methods with mechanized solutions that deliver higher yield consistency.
Despite the favorable growth baseline, the industry stands at an inflection point shaped by several structural challenges. Labor availability and cost remain perennial pressures. Many processing facilities operate with lean staffing models, and the physical demands of membrane removal have made manual and semi-automatic approaches increasingly difficult to scale without compromising throughput or worker safety. At the same time, yield optimization has become a critical margin lever. Membrane skinning directly affects usable meat recovery, and even marginal improvements in precision translate into meaningful cost savings across high-volume operations. Processors are therefore seeking equipment that balances throughput with minimal product damage and reduced post-processing intervention.
A second challenge lies in the divergence between regional operating environments. Mature markets in Europe and North America are characterized by established hygiene frameworks, high automation expectations, and processors that prioritize integration with broader line architectures. Growth markets in Asia Pacific, Latin America, and the Middle East and Africa present different dynamics, including varying capital intensity, different facility scales, and more diverse product mixes. Equipment suppliers must navigate these differences without oversimplifying their offerings, as a solution that performs well in a highly automated European plant may not align with the operational realities of a developing processing hub.
The third challenge is material and compliance sensitivity. Food-grade processing equipment increasingly demands corrosion-resistant construction, straightforward sanitation, and designs that minimize contamination risk. Stainless steel has become the default material for membrane skinners, and this requirement ties equipment procurement to broader raw material dynamics. Fluctuations in stainless steel supply, pricing, and lead times can influence both equipment cost structures and project timelines. For processors planning capacity expansions or replacement cycles, these inputs add a layer of uncertainty that must be managed alongside equipment performance requirements.
Taken together, these challenges are reshaping purchasing behavior. The market is moving away from isolated machine purchases toward solutions that support line efficiency, sanitation efficiency, and consistent yield outcomes. Companies that can demonstrate reliable performance across these dimensions are positioned to capture a larger share of processing budgets, while those that fail to address the practical constraints of modern facilities risk being sidelined in competitive 입찰 and replacement cycles.
Key Growth Drivers: Technology, Regulation, Demand, and Cost Structure
Technological innovation is the most visible driver of market momentum. The membrane skinning segment has benefited from incremental improvements in blade geometry, feed mechanisms, and control logic that enable more consistent removal of silver skin and connective tissue while preserving underlying muscle. Automatic membrane skinners now represent a substantial share of market revenue, reflecting an industry-wide shift toward equipment that reduces manual handling and supports repeatable output. Open-top and compact models have expanded the addressable range for small-to-medium processors, while higher-capacity systems continue to serve large-scale beef and pork operations. The emphasis has moved beyond simple mechanization toward precision, yield retention, and ease of integration into existing lines.
Regulatory and hygiene expectations reinforce this technological trajectory. Food safety standards and sanitation requirements effectively shape equipment design, favoring stainless steel construction, accessible cleaning surfaces, and configurations that reduce product accumulation in hard-to-reach areas. These requirements are not merely compliance checkboxes; they influence total cost of ownership by affecting changeover time, sanitation labor, and downtime. Equipment that supports faster cleaning cycles and more predictable hygiene performance is increasingly favored in procurement evaluations, especially in facilities where throughput targets leave little margin for extended downtime.
On the demand side, processor behavior is being reshaped by labor scarcity and margin sensitivity. Automation in meat processing has gained traction as a response to workforce constraints, and membrane skinners are a logical target for automation because they address a repetitive, physically demanding task with direct implications for yield. Operators are looking for machines that reduce manual intervention without sacrificing flexibility for different cut sizes or product types. This is particularly relevant for beef, pork, and poultry operations, where product dimensions and membrane characteristics can vary significantly. The commercial logic is straightforward: if a machine can improve yield consistency while reducing labor intensity and post-processing rework, it contributes to both operational efficiency and cost control.
Supply chain and cost structure dynamics add further complexity. The reliance on food-grade stainless steel connects membrane skinner manufacturing to broader industrial material markets, where pricing and availability can shift with broader demand patterns. At the same time, manufacturers are under pressure to manage component sourcing, build durability, and keep lead times acceptable for processors planning facility upgrades. This environment rewards suppliers that can maintain production stability, offer clear specifications, and demonstrate that their equipment can withstand continuous use in demanding processing conditions. The broader stainless steel market's growth trajectory suggests that demand for corrosion-resistant processing equipment will remain supported, but it also underscores the importance of cost discipline and supply resilience.
Recent product and exhibition activity illustrates how these drivers are playing out in practice. Compact automatic models have been introduced to serve processors that need high-yield skinning without the footprint or cost of larger systems. Trade show demonstrations have highlighted integrated trimming and skinning solutions, signaling a broader move toward consolidated processing functions and platform-based equipment offerings. These developments point to a market that is not only expanding in volume but also becoming more attentive to practical deployment considerations such as sanitation, footprint, and compatibility with existing workflows.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a mix of established European manufacturers, North American equipment providers, and increasingly cost-competitive OEM suppliers. Market concentration indicates that a limited group of players accounts for a significant share of revenue, but the landscape is not static. Differentiation is emerging along several axes: precision and yield performance, mechanical robustness, integration capability, service and support, and pricing flexibility for different facility scales.
PW Consulting
European manufacturers have built reputations around precision engineering and durable construction. Their product portfolios often span open-top and automatic models, with emphasis on consistent membrane removal and low yield loss across beef, pork, and veal applications. Strong construction standards and familiarity with demanding processing environments give these suppliers credibility in markets where hygiene, repeatability, and long service life are central procurement criteria. Their strategic positioning often extends beyond individual machines to include compatibility with broader automated processing lines, which reinforces their role as part of a larger operational ecosystem rather than a standalone equipment vendor.
North American players contribute a complementary set of strengths, particularly around practical deployment in varied facility sizes and responsive support structures. Compact automatic models have opened opportunities among small-to-medium processors that need reliable skinning capability without the scale or cost of large-line systems. Demonstrations at industry exhibitions have further emphasized yield optimization, durability, and ease of sanitation, reflecting a market that values equipment capable of performing in day-to-day production conditions as much as in controlled specifications. Some providers have also explored platform-based approaches, linking skinning technologies with adjacent trimming and processing functions to offer more consolidated solutions.
Italian manufacturers have carved out a position centered on high-yield derinding and membrane skinning for pork, poultry, and delicate cuts. Their offerings often include single- and dual-blade configurations designed to handle varied product characteristics while maintaining safe and precise operation. Distribution partnerships in key regions, including North America, extend their reach and allow them to compete in markets where local support and service availability influence purchasing decisions.
The competitive picture is further shaped by the presence of lower-cost OEM suppliers, particularly from China, that target cost-sensitive industrial applications. These manufacturers often focus on automatic skinning functionality with adjustable parameters, appealing to processors seeking affordable entry points or replacement units. While their value proposition can be compelling on price, competitive success in the broader market increasingly depends on reliability, sanitation compatibility, and the ability to support consistent yield outcomes over repeated use. Price alone is rarely sufficient when procurement teams weigh total cost of ownership, downtime risk, and integration requirements.
Recent developments highlight the direction of competition. Product launches have targeted compact, lower-cost models that expand accessibility for smaller processors while maintaining durable construction and sanitation-friendly design. Exhibition activity has showcased both standalone skinning machines and broader platform demonstrations, suggesting that suppliers are increasingly thinking in terms of integrated value rather than isolated hardware. This pattern indicates a market in which differentiation is becoming more nuanced: instead of competing only on capacity or price, suppliers are aligning their offerings with specific operational needs, from small-footprint facilities to high-volume automated lines.
Looking ahead, the landscape is likely to evolve through a combination of consolidation, specialization, and new entry. Larger players with broad portfolios may strengthen their position by linking skinning equipment to wider processing systems and service networks. Specialist manufacturers may continue to compete on precision, application fit, and regional support. New entrants will need to establish credibility through consistent quality, clear specifications, and demonstrable performance in real processing conditions. The net effect is a market where strategic positioning matters as much as product capability, and where long-term advantage will depend on how well suppliers match equipment design to the practical constraints of modern meat processing.
Future Outlook: Trends Shaping the Next Three to Five Years
One clear trend is the continued migration toward higher automation in membrane skinning, driven by labor constraints and the desire for consistent yield. Over the next few years, procurement is likely to favor machines that reduce manual intervention while preserving flexibility for different cut sizes and product types. This does not necessarily mean uniform adoption of large-scale automatic systems across all facilities. Instead, the market will probably see a more layered adoption pattern: large processors expanding automated lines, mid-sized operations selecting compact automatic or semi-automatic solutions, and smaller facilities adopting practical, lower-footprint equipment where full automation is not yet justified. The commercial opportunity lies in matching equipment scale to facility reality while still capturing the yield and labor benefits that motivate the transition.
Slitter Market
A second trend is the growing importance of hygiene-enabled design and integration-ready architecture. As sanitation expectations remain elevated and processors seek to minimize downtime, equipment that supports quick cleaning, accessible surfaces, and compatibility with surrounding line components will become more valuable. This trend favors suppliers that can demonstrate not only skinning performance but also how their machines fit into broader operational workflows. It also creates openings for platform-oriented offerings that combine skinning with adjacent trimming or processing functions, reducing the number of separate changeovers and simplifying maintenance planning.
A third trend is the widening gap between premium and value-oriented supply options. As stainless steel and other material inputs remain central to equipment construction, cost structures will continue to matter. However, the market will likely distinguish more clearly between low-cost machines that meet basic functional needs and higher-value systems that offer stronger durability, more predictable yield outcomes, and better integration support. Processors making capital decisions will increasingly weigh total cost of ownership rather than purchase price alone, which could pressure purely price-based competition and reward suppliers that can show reliable long-term performance.
These trends carry both opportunity and uncertainty. Demand for membrane skinning equipment should remain supported by ongoing capacity investment, yield-focused operations, and automation adoption. Yet external variables, including raw material pricing, regional economic conditions, and shifts in processing volumes, can affect purchasing timing and equipment specifications. Suppliers and buyers alike will need to manage flexibility carefully, ensuring that procurement decisions account for both current requirements and the possibility of changing line configurations, product mixes, and labor availability in the years ahead.
Worldwide Pellicle Market
Strategic Actions for Decision-Makers
For equipment manufacturers, the priority is to align product development with practical processing needs rather than abstract specifications. That means continuing to refine precision and yield performance while also emphasizing sanitation-friendly design, durability, and compatibility with different facility scales. Suppliers that can offer a credible range from compact models to higher-capacity automatic systems, supported by clear service and parts availability, will be better positioned to compete across diverse buyer segments. Differentiation should be anchored in measurable operational value, including ease of cleaning, consistent output, and integration fit.
For investors and strategic planners, the market signals a sector with steady baseline growth and selective upside tied to automation adoption and integration-oriented offerings. Attention should focus on companies that demonstrate strong product reliability, clear regional support, and the ability to serve both mature and growth markets without compromising quality or compliance expectations. Investment theses that assume uniform expansion across all segments are likely to overlook the reality that procurement behavior is becoming more segmented, with different facility types prioritizing different combinations of cost, performance, and support.
For processors and procurement teams, the practical task is to evaluate membrane skinning equipment as part of a broader operational strategy rather than as an isolated purchase. Decisions should weigh yield impact, labor reduction, sanitation efficiency, integration with existing lines, and long-term service support alongside upfront cost. Selecting equipment that matches current facility conditions while leaving room for future line adjustments can reduce the risk of under- or over-specifying capacity. As product options expand and competitive positioning becomes more nuanced, access to detailed segmentation data and customized procurement insights can help narrow choices more efficiently and avoid costly mismatches between equipment capabilities and operational requirements.
For detailed analysis of this topic, please visit the official page: Worldwide Meat Membrane Skinner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com