

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Global IP Outsourcing Market 2032 Outlook: How 12% CAGR Redefines Growth

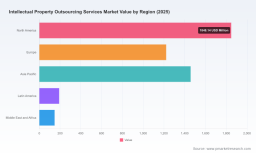
Strategic Shifts and Commercial Opportunities in the Global IP Outsourcing Services Market
The worldwide market for intellectual property outsourcing services has matured into a multi-billion-dollar ecosystem that now touches nearly every sector of the innovation economy. Over the past five years, the industry has scaled from a modest base to a valuation approaching five billion dollars, and forward projections indicate sustained expansion through the early 2030s. This trajectory reflects more than temporary demand; it signals a structural realignment in how enterprises and law firms manage patents, trademarks, and related IP workflows. As organizations seek to stretch internal resources while maintaining rigorous compliance standards, specialized external providers have become integral partners rather than auxiliary vendors. The sector’s momentum is underpinned by consistent compound annual growth, suggesting that outsourcing is transitioning from a cost-saving alternative to a strategic capability embedded in core IP operations.
Despite the favorable headline numbers, the market sits at a critical inflection point. Three interconnected challenges are reshaping how providers differentiate themselves and how buyers evaluate outsourcing relationships. First, the regulatory environment around data protection and cross-border information transfer has tightened considerably. Sensitive patent filings, unpublished invention disclosures, and portfolio administration records now require robust security frameworks, and outsourcing agreements must explicitly address IP ownership, invention assignment, and confidentiality to remain enforceable across jurisdictions. Second, the cost advantage that historically drove volume-based outsourcing is evolving. While administrative cost reductions of up to 40 percent remain achievable for U.S. firms that partner with specialized providers, organizations now demand more than efficiency; they require faster turnaround, deeper technical comprehension, and analytics that inform portfolio strategy. Providers that cannot demonstrate measurable improvements in quality, speed, or insight generation are losing competitive ground. Third, the dispute landscape has intensified significantly. WIPO administered over 1,400 IP disputes in 2025, marking a record year with demand growth of roughly 70 percent, which translates into heightened demand for specialized resolution support and more sophisticated portfolio documentation. Service providers that can integrate dispute preparedness, evidence tracking, and jurisdiction-specific know-how into their offerings are gaining a distinct edge.
A deeper look at the forces propelling this market reveals four core drivers that are reshaping demand patterns and service models.
Worldwide IT Infrastructure Outsourcing Service Market
Technology Innovation and the Emergence of AI-Enhanced Workflows
The integration of artificial intelligence and automation into intellectual property operations represents one of the most consequential shifts in the sector. Traditionally, patent drafting, prior-art searching, docketing, and renewal management relied heavily on manual review and linear processes. Today, AI-assisted tools accelerate search workflows, identify prior-art clusters with greater precision, automate docketing alerts, and streamline IDS management. Opposing counsel and corporate IP teams alike are beginning to rely on AI-enhanced platforms to reduce administrative burden while maintaining attorney oversight. Providers such as Black Hills AI exemplify this transition, delivering attorney-led outsourcing services that combine paralegal and docketing support with AI-enhanced tools. The strategic advantage is no longer limited to speed; it lies in the ability to surface insights that inform filing decisions, portfolio pruning, and competitive monitoring. Firms that embed these capabilities into their service offerings are positioning themselves as knowledge partners rather than transactional processors.
Policy and Regulatory Environment
Regulatory dynamics continue to shape both the supply and demand sides of IP outsourcing. Stricter data protection laws have elevated the importance of security architecture, encryption protocols, and compliance documentation for any provider handling sensitive patent and portfolio data. Cross-border outsourcing arrangements face additional scrutiny, as legal frameworks increasingly require clear definitions around IP ownership, assignment of inventions, and confidentiality obligations to ensure enforceability under local laws. These requirements create both friction and opportunity: they raise the barrier to entry for providers lacking mature compliance infrastructure, while rewarding established players with proven track records and standardized contractual vehicles. Additionally, WIPO administered a record number of IP disputes in 2025, reflecting a broader trend toward heightened enforcement and more complex jurisdictional interactions. As organizations navigate this environment, they are seeking outsourcing partners that can not only administer portfolios but also anticipate compliance risks and reinforce documentation standards that stand up in contested proceedings.
Demand-Side Shifts in Corporate and Law Firm Behavior
On the demand side, organizational behavior is shifting from reactive administration to proactive portfolio strategy. Global patent applications reached 3.7 million in 2024, up 4.9 percent, which has sustained demand for prosecution support, docketing, and portfolio administration. Yet the underlying driver is not volume alone; it is the increasing complexity of maintaining and monetizing IP assets across multiple jurisdictions. Enterprises are treating IP portfolios as strategic capital, and they expect outsourcing providers to contribute to decisions about where to file, when to abandon, how to defend, and how to leverage assets in partnerships or litigation. Law firms, meanwhile, face capacity constraints and are increasingly turning to external support to handle prosecution assistance, prior-art searches, and administrative workflows so their attorneys can focus on high-value advisory work. This behavioral shift creates opportunities for providers that can deliver more than transactional support; it rewards those that offer portfolio landscaping, analytics, and strategic recommendations aligned with business objectives.
Supply Chain and Cost Structure Evolution
The economics of IP outsourcing are being redefined by geographic specialization and service-model innovation. Traditional cost arbitrage remains relevant, but the value proposition has expanded to include access to specialized talent pools, multilingual prosecution expertise, and jurisdiction-specific knowledge that is difficult to replicate in-house. Providers operating from India and other specialized hubs have demonstrated the ability to deliver cost-effective patent drafting, searches, filing support, and portfolio management for international clients, while firms with strong European and North American footprints emphasize full-service lifecycle management and analytics. The supply-side evolution is also visible in partnerships that extend reach into specific markets. For example, recent strategic collaborations have strengthened capabilities in China and enhanced IP office management, enabling providers to offer more seamless cross-border administration. These developments indicate that cost remains important, but the decisive factor is the ability to combine efficiency with jurisdictional depth and workflow flexibility.
Competitive Landscape and Leading Strategies
The market features a diverse set of players spanning mature global platforms, specialized boutique firms, and technology-forward entrants. Leading organizations have carved out distinct strategic positions by emphasizing breadth of service, depth of analytics, and integration of software-enabled workflows. Providers that offer comprehensive IP management software alongside outsourcing services have gained traction because they reduce handoff friction and create unified environments for portfolio management, docketing, renewals, and analytics. This combination is particularly valuable for corporations and law firms seeking to standardize processes across multiple jurisdictions. Players focused on full-service portfolio administration, including filing coordination, renewals, and annuity payments, have positioned themselves as reliable administrators with strong cross-border capabilities. Meanwhile, firms emphasizing IP research, prior-art search, patent landscaping, and analytics support are competing on insight generation, helping clients make evidence-based decisions about filing strategies and portfolio optimization. The landscape also includes cost-competitive providers that serve international clients with practical, high-volume support, as well as attorney-led services that blend human expertise with AI-enhanced tools for docketing, paralegal support, and IDS management. The presence of multiple models reflects a market that is simultaneously consolidating around integrated platforms and fragmenting as niche specialists emerge to address specific pain points.
Market Evolution Trajectories
Three evolutionary patterns are shaping the competitive environment. First, integration is accelerating as larger platforms expand their service portfolios and pursue partnerships that broaden geographic reach and domain coverage. Strategic collaborations are increasingly used to strengthen capabilities in key markets, enhance office management services, and align offerings with client demand for seamless cross-border administration. Second, differentiation is intensifying around quality, analytics, and compliance infrastructure. Providers that can demonstrate measurable improvements in turnaround, accuracy, and strategic insight are outperforming those that compete primarily on price. Third, new entrants are gaining footholds by targeting underserved segments or regions, bringing software-enabled workflows, specialized talent, or AI-assisted tools to bear on specific tasks such as docketing, prior-art search, or prosecution support. This combination of consolidation and specialization suggests a market in which scale advantages matter, but adaptability and depth in specific verticals or geographies can also generate durable positions.
Future Trends and Their Commercial Implications
Looking ahead three to five years, several trends are likely to define the next phase of market development. The first is the deepening integration of AI and automation into core IP workflows. As AI tools mature, they will shift from augmenting discrete tasks to enabling more holistic portfolio management, predictive analytics, and automated compliance checks. This trend will favor providers that invest in robust data pipelines, domain-trained models, and attorney-in-the-loop architectures that preserve quality and accountability. The commercial opportunity lies in offering scalable, insight-rich services that reduce cycle times while improving decision quality for filing, prosecution, and defense strategies.
Intellectual Property Translation Services Market
The second trend is the continued rise of compliance-centric outsourcing. With data protection laws tightening and cross-border enforcement growing, organizations will increasingly require providers that can demonstrate rigorous security, clear contractual governance, and jurisdiction-specific expertise. Service agreements that explicitly address data handling, IP ownership, and confidentiality will become standard expectations rather than special provisions. Providers that build compliance into their operating model and transparently communicate governance standards will gain trust and win larger, longer-term engagements.
The third trend is the expanding role of analytics in portfolio strategy. As patent applications continue to grow and dispute activity intensifies, clients will demand more sophisticated landscaping, competitive monitoring, and risk assessment. Analytics-driven outsourcing will enable enterprises to identify white spaces, prune underperforming assets, and strengthen defenses in contested environments. This shift creates opportunities for providers that combine research depth with actionable reporting, enabling clients to translate IP data into business decisions. Potential risks include over-reliance on automation without adequate expert oversight, variability in jurisdiction-specific knowledge, and the possibility that cost pressure could push providers toward lower-quality models. Organizations evaluating partners should weigh these risks against the benefits of scale, speed, and strategic insight.
Strategic Recommendations for Decision-Makers
Manufacturers and R&D-intensive enterprises should view IP outsourcing as a strategic lever rather than a back-office function. Prioritize partners that offer jurisdiction-specific prosecution support, robust docketing, and analytics that inform filing decisions across markets. Evaluate providers not only on cost but on turnaround reliability, quality controls, and the ability to scale as global filing volume increases. Build contractual clarity around data handling, IP ownership, and confidentiality to protect sensitive portfolio information and ensure enforceability in cross-border contexts.
Investors assessing the sector should focus on providers that demonstrate a credible combination of technology-enabled workflows, compliance maturity, and geographic or vertical specialization. Scalable platforms with integrated software and service offerings are well positioned to capture demand as organizations seek to reduce fragmentation and standardize IP operations. Monitor signs of consolidation and partnership activity, as these often indicate where scale advantages and market access are being strengthened.
PW Consulting
Procurement teams and IP function leaders should adopt a structured evaluation framework that balances efficiency, quality, and strategic value. Define clear service-level expectations for docketing, renewals, prior-art search, and portfolio administration, and require evidence of attorney-led oversight where appropriate. Prioritize vendors that can articulate how they manage data security, cross-border compliance, and dispute readiness. As market dynamics continue to evolve, maintaining access to detailed, up-to-date segmentation data and scenario analysis will help organizations align outsourcing decisions with long-term portfolio strategy. Readers seeking deeper breakdowns by service type, industry vertical, and region, along with customized recommendations, can explore the full research report for comprehensive detail and actionable guidance.
For detailed analysis of this topic, please visit the official page: Worldwide Intellectual Property Outsourcing Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com