

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
HR Consulting Market: Why 5.25% CAGR and $66B by 2032 Signal a Strategic Shift

The Worldwide HR Consulting Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
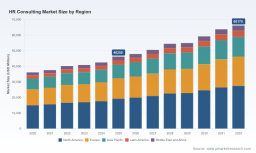
The global HR consulting sector has demonstrated resilient expansion over the past half-decade, evolving from a traditional advisory function into a strategic capability that organizations treat as critical infrastructure. Total market revenue climbed from approximately USD 36,150 million in 2020 to an estimated USD 46,250 million in 2025, reflecting a compound annual growth rate of 5.25 percent across the historical window. The trajectory is expected to continue upward through the forecast period ending in 2032, with revenue projected to reach USD 66,170 million. This growth trajectory signals sustained demand for human capital advisory services, yet the pace of expansion masks underlying structural shifts that are reshaping competitive dynamics and value creation pathways.
Regional distribution reveals a mature core alongside rapidly scaling markets. North America continues to command the largest revenue share, reflecting the depth of enterprise consulting adoption and the concentration of global headquarters in the region. Europe maintains a substantial footprint, supported by established regulatory frameworks and corporate governance expectations that drive consulting engagement. Asia Pacific represents the most dynamic growth corridor, fueled by expanding multinational operations, rising labor costs, and accelerated digital transformation initiatives across both established economies and emerging markets. Latin America and the Middle East and Africa collectively contribute smaller but steadily increasing revenue streams, often tied to infrastructure investments, resource sector workforce planning, and public sector modernization programs.
Beneath the aggregate figures, the sector faces three pressing challenges that will define competitive positioning over the next several years. First, the integration of artificial intelligence into HR processes has moved from experimental pilots to operational expectations. Organizations now expect consulting providers to deliver not only strategic recommendations but also implementation roadmaps for AI-enabled recruitment, compensation modeling, workforce analytics, and employee experience design. Firms that cannot credibly bridge strategy and technology execution face growing pressure on their relevance and pricing power.
Second, regulatory and compliance complexity is intensifying across multiple jurisdictions. Data privacy requirements, emerging standards for responsible AI deployment, and evolving labor classification rules are complicating the delivery of HR advisory services. Consulting engagements now routinely require governance frameworks, audit readiness, and cross-border compliance coordination. This environment raises the bar for expertise and increases the operational cost of service delivery, particularly for firms managing global client portfolios.
Workday Human Capital Management Consulting Service Market
Third, talent itself has become the most constrained input. HR consulting firms are competing for the same scarce pool of professionals who combine domain expertise in human capital strategy with fluency in data analytics, technology implementation, and change management. The talent shortage affects both the supply side of the consulting industry and the demand side of client organizations, creating a dual pressure point. Clients are increasingly scrutinizing whether consulting engagements produce measurable improvements in workforce effectiveness rather than deferring action through prolonged advisory cycles.
Key Drivers of Market Change
Several interconnected forces are accelerating demand for HR consulting services and reshaping how value is delivered. Understanding these drivers is essential for executives evaluating partnership opportunities, investors assessing sector exposure, and service providers refining their go-to-market strategies.
Technology Innovation and AI Integration
The adoption of artificial intelligence across HR functions has reached a point where it is no longer a differentiator but a baseline expectation. Recent industry data indicates that a substantial majority of HR leaders are engaging with AI capabilities at some level, spanning talent acquisition screening, skills inference, compensation benchmarking, attrition risk modeling, and employee service automation. This broad participation is generating demand for specialized consulting support in AI strategy, workforce readiness, and ethical deployment. Organizations need help identifying where AI can improve decision quality, how to structure data and governance for responsible use, and how to redesign roles and workflows as automation absorbs routine tasks.
Technology-driven transformation is also expanding the scope of HR consulting beyond traditional advisory work. Implementation support for HR technology platforms, integration of analytics dashboards, and redesign of employee experience journeys are increasingly bundled into larger transformation engagements. Providers that combine domain expertise with demonstrated capability in technology enablement are capturing share in this expanding service perimeter. The emphasis is shifting from advising on what to do to helping organizations execute, measure, and iterate.
Regulatory and Compliance Pressures
The regulatory environment surrounding HR data, algorithmic decision-making, and workforce classification is becoming more demanding. Firms operating across multiple jurisdictions must navigate divergent privacy regimes, emerging certification expectations for AI systems, and evolving standards for transparency in automated HR processes. In response, consulting providers are building compliance-oriented service offerings that help clients establish governance structures, document decision logic, and align HR practices with responsible AI principles.
PW Consulting
Certification frameworks and audit readiness are gaining prominence as tangible signals of rigor. For example, the integration of AI into HR business processes is increasingly accompanied by governance measures designed to ensure compliance and human-centered outcomes. This trend benefits consulting firms that can offer structured methodologies for embedding governance into HR operations, as well as firms that can advise on cross-border data handling and regulatory alignment. The compliance dimension also raises the cost of entry for less mature providers, reinforcing the advantage of established players with global delivery capabilities and dedicated risk and compliance practices.
Demand-Side Shifts in Enterprise Behavior
Enterprise buyers are reevaluating how they allocate HR spending, with growing attention to total workforce costs and the efficiency of HR service delivery. Leadership teams are examining not only direct HR staff costs but also the expenditures associated with systems, chargebacks, and external service utilization. This more granular cost perspective is prompting organizations to seek consulting support for workforce optimization, outsourcing decisions, and the redesign of HR operating models. The objective is to improve value delivery while maintaining or enhancing employee experience and operational resilience.
At the same time, the strategic importance of talent management has intensified. Competition for skilled workers, particularly in technology, analytics, and specialized professional domains, is pushing organizations to invest more heavily in leadership development, succession planning, and skills-based talent architectures. Consulting engagements are increasingly focused on building internal capabilities for continuous learning, skill gap closure, and mobility programs that reduce dependency on external hiring. The shift from transactional HR support to strategic workforce planning reflects a broader recognition that human capital decisions are direct levers on competitive performance.
Cost Structure and Location Dynamics
Cost considerations continue to influence both the supply and demand sides of the HR consulting market. On the client side, location choices affect labor costs, recruiting expenses, and the economics of global HR operations. Organizations are weighing the trade-offs between centralized and distributed HR service delivery, often seeking consulting advice on how to structure shared services, offshore or nearshore components, and technology-enabled self-service models. On the provider side, consulting firms are managing their own cost structures by balancing senior advisor capacity with scalable delivery resources, including analysts, technologists, and implementation specialists.
This dynamic is encouraging a more modular approach to service delivery. Rather than offering monolithic advisory engagements, many providers are designing tiered offerings that allow clients to select the level of strategic depth, data analysis, and implementation support they require. The result is a broader accessible price point for mid-sized enterprises while preserving high-value strategic work for large, complex organizations. Cost transparency and delivery efficiency are becoming competitive differentiators in a market where buyers are increasingly sophisticated about what they are paying for.
Competitive Landscape and Leading Strategies
The HR consulting market is characterized by a diverse set of participants spanning global professional services networks, management consultancies with human capital practices, and specialized HR advisory firms. Market concentration remains moderate, with the top three firms accounting for a minority share of total revenue and the top five collectively representing roughly one-third of the market. This fragmentation reflects the breadth of service requirements and the continued presence of regional and niche players that compete on specialization, local relationships, and cost effectiveness.
Several strategic archetypes are evident among leading participants. Global professional services organizations offer comprehensive human capital capabilities integrated with broader consulting, technology, and risk advisory portfolios. Their scale, global delivery footprint, and ability to combine workforce strategy with technology implementation and compliance support position them well for large, multi-jurisdiction engagements. These firms are increasingly emphasizing workforce transformation, HR technology adoption, and organizational design as interconnected workstreams rather than standalone advisory projects.
Management Consulting Services Market
Management consultancies bring a strong orientation toward organizational performance, leadership development, and human capital strategy as part of enterprise-wide transformation. Their value proposition often centers on aligning people strategy with business strategy, improving operating model design, and building leadership pipelines that support growth and change. These firms compete on strategic depth, executive relationships, and the ability to connect workforce decisions to financial and operational outcomes.
Specialized HR and human capital firms focus deeply on talent management, executive search, compensation and benefits, retirement, health, and workforce analytics. Their differentiation comes from domain depth, proprietary data and benchmarks, and established reputations in specific capability areas. For clients with concentrated needs—such as benefits restructuring, executive assessment, or compensation strategy—these specialists can offer credibility and precision that broader consultancies may not match without partner ecosystems.
Technology-forward providers are gaining traction by combining consulting with implementation and platform capabilities. The launch of AI-powered workforce solutions in partnership with technology vendors illustrates the trend toward embedding intelligence into HR processes and offering clients a more complete path from strategy to deployment. This model is appealing to organizations that want to reduce the friction between advisory recommendations and operational execution.
Recent developments highlight how leading firms are responding to these dynamics. Major consultancies continue to publish large-scale workforce and human capital trends research, using data from thousands of leaders across numerous countries to frame the strategic conversation around work, workforce, and workplace change. Such research serves both to establish thought leadership and to inform consulting propositions. In parallel, acquisitions and capability expansions are being used to deepen expertise in fiduciary, tax-related HR services, and AI-driven workforce solutions. These moves reflect a strategic push to broaden service perimeters, strengthen compliance and risk capabilities, and embed technology more directly into consulting delivery.
The competitive landscape is evolving along multiple axes. Consolidation is occurring through acquisition as larger firms absorb specialized capabilities and expand their foothold in adjacent service areas. Differentiation is intensifying as firms compete on AI readiness, data assets, implementation depth, and regional expertise. New entrants and technology companies are also pressing into the space, particularly where HR technology platforms offer embedded advisory features or partner ecosystems that blur the line between software and consulting. For buyers, this evolution creates more options but also greater complexity in evaluating which provider model best fits a given need.
Forward Outlook: Key Trends and Commercial Implications
Looking ahead to the 2026–2032 period, several trends are likely to shape the direction of the HR consulting market and create distinct commercial opportunities.
The first trend is the maturation of AI-enabled HR consulting from experimentation to operational integration. As organizations move beyond pilot projects, demand will grow for structured programs that embed AI into recruitment, workforce planning, compensation analysis, and employee experience design while maintaining governance and human oversight. Consulting firms that can provide end-to-end support—strategy, data readiness, model selection, change management, and continuous measurement—will capture premium engagements. The opportunity lies not only in advising on AI adoption but in helping clients build the organizational capabilities required to sustain it.
The second trend is the continued shift toward total workforce cost optimization and HR operating model redesign. Enterprises are increasingly treating HR as a value-delivery function that must justify its cost structure and demonstrate efficiency. This creates demand for consulting support in shared services design, outsourcing strategy, technology consolidation, and the reallocation of HR resources toward higher-impact activities. Providers that can combine cost analysis with employee experience and compliance considerations will be better positioned to deliver recommendations that are both financially and operationally credible.
The third trend is the growing importance of skills-based talent architectures and internal mobility. As external hiring becomes more competitive and expensive in key domains, organizations are investing in reskilling, internal talent marketplaces, and dynamic workforce planning. Consulting engagements will increasingly focus on designing skill taxonomies, identifying capability gaps, and building programs that move talent to where it is needed. This trend aligns with broader digital transformation efforts and offers a pathway to reduce reliance on costly external recruitment while improving retention and engagement.
Strategic Recommendations for Decision Makers
For enterprise leaders and strategy teams, the priority is to treat HR consulting as a strategic lever rather than a reactive support function. Engage providers with clear scope definitions that link workforce objectives to measurable business outcomes, and insist on roadmaps that include implementation, governance, and performance tracking. Evaluating partners on their ability to combine strategy, data, and technology execution will reduce the risk of recommendations that are difficult to operationalize.
For investors assessing exposure to the HR consulting sector, differentiate between business models. Firms with strong AI and technology integration capabilities, scalable delivery platforms, and comprehensive compliance support are likely to benefit from the shift toward AI-enabled, governance-aware HR services. Specialized firms with deep domain expertise and proprietary benchmarks can command premium positioning in focused segments. Monitoring deal activity, capability expansions, and research output can provide early signals of where competitive advantage is being built.
For procurement and sourcing leaders, the expanding menu of provider models calls for more nuanced evaluation criteria. Consider whether a single global provider, a specialized partner, or a combined ecosystem best matches the organization's needs across strategy, implementation, and ongoing support. Request transparent cost structures, delivery models, and evidence of measurable impact. Given the pace of change in technology, regulation, and workforce expectations, timely access to detailed segment data and customized advisory input can materially improve sourcing decisions and reduce implementation risk.
Detailed segmentation data, regional revenue estimates, service-type breakdowns, industry-vertical analysis, and company-level profiles are available in the full research report, supporting deeper due diligence and tailored strategy development.
For detailed analysis of this topic, please visit the official page: Worldwide HR Consulting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com