

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Rehabilitation Retractor Market: The 5.85% CAGR Driver Reshaping Future Growth

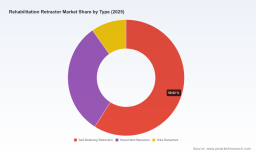
Strategic Trends and Commercial Opportunities in the Worldwide Rehabilitation Retractor Market
Market Landscape and Core Challenges
The worldwide rehabilitation retractor market, encompassing devices utilized for spinal rehabilitation treatment to relieve pain and improve function through adjustable traction force, time, and angle, is navigating a period of steady expansion. Valued at approximately USD 545.6 million in 2025, the sector is projected to grow at a compound annual growth rate of 5.85% through 2032. This growth trajectory reflects a maturing market that is transitioning from basic mechanical tools to sophisticated electronic systems capable of supporting static or intermittent modes for cervical, lumbar, or multifunctional applications in rehabilitation centers or household use.
Despite the positive revenue outlook, the industry stands at a critical juncture defined by several structural challenges. One primary hurdle is the differentiation between clinical-grade equipment and consumer-grade devices. As the definition of rehabilitation retractors broadens to include home-use solutions, manufacturers face the complexity of meeting stringent medical device classifications while competing on cost and usability in the consumer space. Devices such as powered traction units are often classified as Class II medical devices under relevant regulatory frameworks, imposing specific compliance burdens that can stifle innovation among smaller players lacking regulatory expertise.
Secondly, supply chain stability remains a concern. The precision required for calibrated traction systems means that disruptions in electronic component manufacturing or specialized material sourcing can delay product launches and inflate costs. This vulnerability is particularly acute for companies relying on complex powered mechanisms rather than simple manual designs.
Finally, market concentration indicates a moderately consolidated environment, where a handful of established players hold significant sway. With the top three companies accounting for a notable share of revenue, new entrants must offer compelling technological advantages or niche specializations to gain traction. This concentration creates a barrier to entry but also signals stability for investors looking at the incumbent leaders. The challenge lies in balancing the need for regulatory compliance and supply chain resilience with the demand for affordable, accessible rehabilitation solutions.
Key Drivers of Market Change
Several interconnected factors are propelling the rehabilitation retractor market forward, reshaping how products are developed, regulated, and adopted.
Technological Innovation and Automation
The shift from manual to powered traction units represents the most significant technological driver. Modern devices are increasingly incorporating automatic calibration and multiple traction modes, including intermittent, static, and progressive settings. This technological leap allows for more precise treatment protocols tailored to individual patient needs. For instance, advanced units now feature safety controls that monitor traction force and angle in real-time, reducing the risk of injury during spinal rehabilitation. This move towards automation not only improves clinical outcomes but also enhances the value proposition for home-care settings, where professional supervision may be limited. The integration of digital interfaces and data logging capabilities is further enabling clinicians to track patient progress remotely, aligning with the broader trend of digital health integration.
Worldwide Urethral Dilator Market
Regulatory Frameworks and Safety Standards
The regulatory environment is tightening, particularly regarding the classification of traction devices. As noted in recent policy discussions, certain powered traction units are classified as Class II medical devices. This classification necessitates rigorous testing for safety and efficacy before market entry. While this adds a layer of complexity for manufacturers, it also serves as a quality filter that benefits established companies with robust compliance infrastructures. Regulatory clarity helps standardize treatment protocols and builds trust among healthcare providers and patients. Consequently, companies that proactively invest in regulatory affairs and quality assurance are better positioned to secure approvals and expand their market reach across different regions with varying compliance requirements.
Demand-Side Shifts Towards Non-Invasive Care
There is a growing preference among patients and healthcare providers for non-invasive rehabilitation treatments over surgical interventions where possible. Spinal issues related to aging, sedentary lifestyles, and sports injuries are driving demand for conservative management techniques. Rehabilitation retractors offer a non-surgical option to relieve pain and improve function, making them an attractive component of comprehensive rehabilitation product lines for musculoskeletal and spinal treatment. Furthermore, the aging global population is increasing the prevalence of degenerative spinal conditions, directly expanding the addressable market. Patients are seeking solutions that allow for faster recovery times and reduced hospital stays, fueling demand for devices that can be used in outpatient clinics or at home.
Supply Chain and Cost Structure Evolution
Cost structures are evolving as manufacturers seek to balance performance with affordability. The demand for household-use devices is pushing companies to design cost-effective models without compromising essential safety features. Simultaneously, supply chain localization efforts are gaining traction to mitigate risks associated with global logistics disruptions. Companies that can optimize their manufacturing processes to reduce dependencies on single-source components while maintaining high precision in traction force adjustment will gain a competitive edge. This dynamic is encouraging innovation in material science and manufacturing techniques that lower production costs while enhancing durability and reliability.
Competitive Landscape and Leading Strategies
The competitive environment in the rehabilitation retractor market is characterized by a mix of large multinational corporations and specialized regional manufacturers. The market is moderately consolidated, with leading players leveraging diverse product portfolios and technological expertise to maintain their positions.
Rehabilitation Robotics Market
Major western companies often dominate through comprehensive rehabilitation product lines. For example, Chattanooga (Enovis), based in the United States, offers traction and decompression equipment as part of its extensive rehabilitation product line for musculoskeletal and spinal treatment, including Saunders Cervical Traction systems. Their strategy relies on brand recognition and integration within broader clinical ecosystems. Similarly, Mettler Electronics, also based in the United States, is known for electrotherapy and traction devices used in physical rehabilitation, leveraging decades of experience in physical therapy equipment to maintain market relevance.
In contrast, Japanese manufacturers are focusing on precision engineering and advanced feature sets. ITO Co., Ltd. develops powered traction units like the TM-400 with automatic calibration and multiple traction modes for cervical and lumbar rehabilitation. Their emphasis on technical sophistication appeals to clinical settings requiring high precision. OG Wellness Technologies Co., Ltd. also manufactures physiotherapy traction equipment, including ORTHO TRAC cervical traction units with multi-step traction modes, catering to the specific needs of rehabilitation treatment in structured clinical environments. MINATO Medical Science supplies rehabilitation equipment including traction systems, further strengthening the presence of Japanese engineering in this sector.
Emerging players and regional specialists are carving out niches through targeted solutions. V2U Healthcare, with a regional focus in Malaysia and the Philippines, provides traction decompression systems such as V2U TRAC TDM and TRAC PRO for cervical and lumbar spinal rehabilitation. These devices feature static, intermittent, and cyclic modes with safety controls, addressing specific regional needs and price points. Enraf-Nonius, based in the Netherlands, supplies the Eltrac 471 traction therapy device designed for precise lumbar and cervical traction with continuous and intermittent protocols in physiotherapy settings, emphasizing clinical efficacy.
European manufacturers like Elettronica Pagani and Fisiotech, based in Italy, remain active in the rehabilitation retracter and traction equipment market, often focusing on specific physiotherapy applications. Meanwhile, companies like Huntex Corporation in Taiwan manufacture rehabilitation traction and retractor devices, contributing to the global supply diversity. Other entities such as Bilt-Rite Mastex Health and EVERYWAY MEDICAL offer products in the household and clinical rehabilitation retracter segment, indicating a trend towards diversifying end-use applications. Meditrac and SIRIUSMED also provide rehabilitation retracter and traction solutions, adding to the breadth of available options.
The market landscape is evolving through a combination of consolidation and specialization. Larger entities may seek to acquire smaller innovators to integrate advanced technologies like automatic calibration or digital connectivity into their portfolios. Simultaneously, new entrants are likely to emerge from regions with growing healthcare infrastructure, offering cost-effective alternatives. Strategic differentiation will increasingly depend on the ability to offer versatile devices that can switch between static and intermittent modes, ensuring safety controls are robust, and providing support for both clinical and home use cases. Companies that fail to adapt to the demand for multifunctional rehabilitation retractors risk losing share to more agile competitors.
PW Consulting
Future Trends and Predictions
Looking ahead to the next three to five years, the rehabilitation retractor market is expected to evolve along several key trajectories that will define commercial opportunities.
First, the convergence of rehabilitation retractors with broader digital health ecosystems will accelerate. Devices will not merely apply traction but will likely incorporate data analytics to monitor patient compliance and treatment efficacy. This shift creates opportunities for manufacturers to offer subscription-based services or software-linked hardware that adds ongoing value beyond the initial sale. The ability to remotely adjust parameters or receive alerts on device usage could become a standard expectation for clinical buyers.
Second, the market for home-based rehabilitation devices is poised for significant growth. As healthcare systems seek to reduce costs and hospital burden, there will be increased support for devices that patients can use safely at home under remote supervision. This trend favors companies that can design intuitive, user-friendly interfaces and ensure devices meet safety standards for non-professional operation. The segmentation between clinical and household use may blur further, with high-end home devices approaching clinical capabilities.
Third, regional dynamics will shift as healthcare infrastructure develops in emerging markets. Areas previously underserved by advanced rehabilitation technology may see increased adoption due to rising healthcare expenditure and awareness. However, this expansion comes with risks. Regulatory divergence between regions could complicate global product launches. Additionally, economic volatility may impact procurement budgets in public healthcare systems, potentially slowing growth in certain segments. Manufacturers must remain agile, adapting their product offerings and pricing strategies to local economic conditions while maintaining quality standards. The potential for supply chain disruptions remains a constant threat, requiring robust contingency planning.
Strategic Recommendations for Decision Makers
For manufacturers, the priority should be investing in R&D that enhances usability and connectivity without escalating costs disproportionately. Focusing on automatic calibration and safety controls can differentiate products in a crowded market. Exploring partnerships for digital integration could unlock new revenue models and strengthen customer loyalty.
Investors should look for companies with strong regulatory compliance records and diversified product portfolios that span both clinical and home-care segments. Firms that demonstrate resilience in supply chain management and have a clear strategy for emerging markets may offer better risk-adjusted returns. Evaluating the technological moat of potential targets, specifically regarding proprietary traction modes or calibration technology, is essential.
Procurement teams and healthcare providers should evaluate devices based on total cost of ownership and clinical outcomes rather than just initial purchase price. Selecting equipment that supports multiple traction modes and offers reliable safety features can reduce long-term operational risks. Keeping abreast of changing regulatory classifications is crucial to ensure continued compliance and avoid disruptions in service delivery. Engaging with suppliers who provide comprehensive training and support for both clinical and home-use scenarios will maximize the utility of the equipment.
For stakeholders seeking detailed segmentation data and customized strategic advice, accessing comprehensive market intelligence reports provides a clearer picture of regional nuances and competitive moves. Deep-dive analyses can reveal specific growth pockets and potential partnership opportunities that are not visible at the aggregate level.
For detailed analysis of this topic, please visit the official page: Worldwide Rehabilitation Retractor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com