

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
D-Sub Mixed Contact Connector Market: Why 6.2% CAGR and Segmentation Shifts Redefine Growth to 2032

Navigating the Strategic Terrain of the Worldwide D-Sub Mixed Contact Connector Market
Market Landscape and Core Challenges
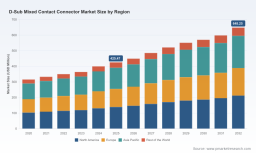
The global market for D-Sub mixed contact connectors has demonstrated steady, measurable growth throughout the 2020–2025 period, transitioning from a mature interconnect category into a more specialized solution space. Valued at approximately 315.4 million USD in 2020, the market expanded to 425.47 million USD by 2025. Forward-looking projections indicate continued expansion through the end of the decade, with a compound annual growth rate of 6.2 percent expected between 2026 and 2032. This trajectory signals that despite the prevalence of newer high-speed and miniature interconnect forms, mixed-contact D-Sub architectures remain strategically relevant for applications requiring simultaneous power delivery, signal integrity, and environmental resilience within a single envelope.
The category's resilience stems from its functional versatility. By integrating standard signal pins, high-current power contacts, coaxial terminations, and high-voltage configurations within a familiar D-Sub shell, these connectors address legacy redesign costs while meeting modern performance thresholds. However, this very versatility introduces operational complexity. Manufacturers and system integrators must navigate competing requirements around pin assignment, current-carrying capacity, impedance control, and mechanical retention, all while maintaining compatibility with established board-mount and cable-assembly workflows.
Several structural challenges currently define the market's inflection point. First, regulatory and compliance fragmentation has intensified. Mixed-layout designs frequently require adherence to multiple certification frameworks simultaneously, including ISO 9001 and AS9100 quality management expectations, MIL-DTL-24308 specifications for defense-destined variants, UL recognition for power-carrying contacts, and lead-free plating mandates for board-level and cable applications. Navigating these overlapping standards increases engineering validation timelines and raises the cost of qualification for custom configurations.
Second, material and trade policy dynamics are reshaping cost structures. Tariff measures on imported connectors and socket assemblies from China have combined with elevated duties on copper components, directly affecting raw material inputs for D-Sub mixed contact manufacturing. The intersection of trade policy volatility and commodity price sensitivity means that traditional volume-based sourcing models face renewed margin pressure, particularly for producers relying on imported copper stock or foreign-assembled cable harnesses.
Third, the market is encountering a design paradox. Engineers seek the spatial efficiency and single-cable simplification that mixed-contact D-Sub solutions offer, yet they also demand higher density, faster mating cycles, and stricter environmental sealing. Reconciling these requirements within the geometric constraints of the D-Sub footprint has become a central product development challenge, pushing suppliers to balance incremental improvements with more radical form-factor adaptations.
Worldwide Connector Backshells Market
Key Growth Drivers and Market Catalysts
The sustained expansion of the D-Sub mixed contact segment is being propelled by a convergence of technological, regulatory, demand-side, and supply chain forces. Each driver reinforces the others, creating a multi-layered growth environment that rewards suppliers capable of aligning product roadmaps with application-specific performance and compliance requirements.
Technological Innovation and Contact-Level Integration
One of the most significant catalysts has been the refinement of mixed-contact engineering. Manufacturers have progressively expanded the range of contact types that can coexist within a single D-Sub shell, enabling simultaneous routing of low-voltage signals, high-current power lines, coaxial references, and high-voltage isolation paths. This integration reduces harness complexity, minimizes connector count on PCBs, and simplifies field servicing. Advances in press-fit, surface-mount, and full-power termination technologies have further broadened deployment options, allowing mixed-layout D-Sub components to serve both legacy through-hole assemblies and modern high-density board architectures. High-reliability variants, including combo configurations with coaxial integration and non-magnetic or feed-through adaptations, illustrate how incremental contact-level innovation continues to unlock value in demanding environments.
A practical manifestation of this trajectory can be seen in recent product introductions that enhance installation efficiency without abandoning the mixed-contact principle. In May 2025, HARTING launched D-Sub PushPull housings compatible with mixed, standard, and high-density configurations, offering up to 50 percent time savings during installation and maintenance while supporting up to 36 coding variations. This was preceded by the Q1 2025 release of a PushPull locking system designed for classic D-Sub connectors, including mixed layouts, with the explicit goal of simplifying connections in industrial settings. These developments highlight a broader shift: the market is not only seeking functional mixed-contact capabilities, but also faster, more repeatable mating experiences that reduce assembly labor and field-service errors.
Policy, Compliance, and Standards as Design Enablers
Regulatory and standards-driven requirements are functioning less as barriers and more as design accelerators. Mixed-layout D-Sub connectors frequently undergo qualification against customer-specific environmental and performance expectations, with many product lines certified to ISO 9001 and AS9100 quality frameworks and MIL-DTL-24308 for defense-oriented applications. These frameworks create predictable performance baselines for aerospace, defense, and industrial buyers, reducing evaluation uncertainty and encouraging specification standardization. At the same time, compliance mandates such as UL recognition for power-carrying contacts and lead-free plating standards push manufacturers toward more disciplined material selection, plating processes, and traceability practices.
The effect is twofold. First, compliance maturity becomes a competitive differentiator, especially in sectors where qualification cycles are long and re-testing is costly. Second, standardized high-reliability families simplify cross-platform adoption, allowing system designers to reuse qualified connector families across multiple programs. In this way, regulation and certification, when managed proactively, help expand the addressable use cases for mixed-contact D-Sub components rather than constrain them.
Demand-Side Shifts Across Mission-Critical and Industrial End Use
Demand patterns are increasingly shaped by applications where power aggregation, signal fidelity, and ruggedization must coexist. Aerospace and defense programs continue to favor mixed-contact D-Sub architectures for their ability to consolidate high-reliability interconnects within weight- and space-constrained assemblies, particularly where custom pin assignments and specialized terminations are required. Industrial automation similarly benefits from mixed-contact solutions that simplify I/O consolidation on machinery, control cabinets, and fieldbus interfaces, especially when combined with sealing and mechanical robustness for harsh operating conditions. Medical electronics, meanwhile, leverages mixed-layout variants for equipment requiring integrated signal and power paths with strict reliability expectations, while telecommunications infrastructure uses combination connectors to reduce port density and cable bulk in switching, routing, and backhaul environments.
Across these sectors, the unifying theme is consolidation. Engineers are under pressure to reduce component count, simplify cable assemblies, and shorten deployment timelines without compromising performance. Mixed-contact D-Sub connectors align directly with these priorities, making them a practical choice in scenarios where redesigning around smaller or faster interconnect families would introduce disproportionate engineering, qualification, or supply risk.
Supply Chain Reconfiguration and Cost Dynamics
On the supply side, the market is navigating a more complex cost landscape. Trade policy developments have affected import costs for finished connectors and subcomponents, with duties on certain Chinese-origin connector products reaching combined levels that materially alter landed-cost calculations. At the same time, raw material pressures—most notably copper-related tariff impacts—have increased input costs for D-Sub mixed contact components and associated cable assemblies. These dynamics are prompting manufacturers to revisit supplier base strategies, evaluate regional sourcing alternatives, and refine cost pass-through models.
This environment is also accelerating a broader structural shift. Suppliers are increasingly emphasizing value-added configurations, application-specific terminations, and sealed or ruggedized variants that command stronger margins than commodity D-Sub lines. The trend favors manufacturers that can combine material cost discipline with engineering differentiation, rather than competing solely on catalog availability or unit price. In practice, this means mixed-contact D-Sub competitiveness is increasingly defined by the ability to offer predictable qualification outcomes, flexible contact mixing, and robust termination options that reduce downstream integration risk.
Competitive Dynamics and Strategic Positioning
The competitive landscape for D-Sub mixed contact connectors is characterized by a mix of broad-line interconnect leaders, high-reliability specialists, and regional manufacturing players. The market exhibits meaningful concentration, with a core group of established suppliers capturing a substantial share of mainstream and specification-driven demand. This concentration reflects the importance of qualification portfolios, engineering support, and long-term supply reliability in the D-Sub category, where buyers often prefer proven suppliers over lower-cost alternatives when performance and compliance are critical.
Amphenol maintains a broad footprint through its standard and mixed-power D-Sub offerings, spanning press-fit, SMT, full-power, and mixed-power versions with coaxial contacts for industrial, telecom, aerospace, and board/cable applications. Its portfolio includes combo-D and high-reliability variants, supported by the scale and breadth of a global interconnect platform. Within the Amphenol ecosystem, Positronic adds a focused high-reliability dimension, specializing in combo D-Sub configurations that combine signal, power, coax, high-voltage, and fiber optic contacts in both standard and high-density formats, often qualified to MIL specifications for aerospace and defense. This combination of breadth and specialization illustrates a common strategic pattern: use core manufacturing scale to anchor demand while layering on mission-critical variants to capture higher-value segments.
TE Connectivity approaches the market through its AMPLIMITE D-Subminiature line, offering mixed signal, power, and coax contacts with high-density options and MIL-DTL-24308 qualified versions. The portfolio also includes specialized non-magnetic and feed-through configurations for aerospace, defense, and industrial use, reinforcing a positioning centered on qualified performance and application adaptability. Molex complements this landscape with mixed-layout D-Sub connectors and cable assemblies that support high-current, high-voltage, pneumatic, and coaxial contacts within standard housings, addressing varied application requirements through flexible contact mixing and assembly options.
PW Consulting
A second strategic cluster is defined by ruggedization, sealing, and combo specialization. NorComp distinguishes itself with combo and mixed-contact D-Sub designs that combine signal contacts in the 5A range with power contacts rated in the 20–40A band inside the same shell, including IP67-rated versions and custom rugged I/O solutions. CONEC provides combination and mixed-layout D-Sub connectors with signal, power, and high-density options, offering IP67 sealed and crimp termination variants for automation, telecom, and industrial use. HARTING contributes a modular approach that supports nearly unlimited variants with signal, power, and other contacts for industrial PCB and harsh-environment applications, including THR and SMT mounting choices. Signal Origin focuses on waterproof IP68 D-Sub mixed contact connectors with power and coaxial combinations for industrial and harsh environments, while AUK Connector supplies mixed-contact variants through precision manufacturing for global OEM and ODM supply. Together, these players emphasize durability, sealing, and customized pin assignments as the basis for differentiation.
A third layer of competition comes from high-reliability and defense-oriented specialists. ITT Cannon extends its legacy and high-reliability interconnect portfolio into D-Sub mixed contact configurations for defense, industrial, and harsh environments. Glenair produces high-reliability D-Sub mixed contact connectors and accessories, often tailored for aerospace, defense, and severe operating conditions with custom and MIL-spec options. EDAC broadens the catalog side of the market with its D-Sub+ family, offering mixed configurations in standard and high-density formats, including stacked and dual-port options with varied termination, plating, and mounting choices. Phoenix Contact integrates D-Sub mixed contact connectors into its wider industrial connectivity portfolio, with variants suited to automation and control systems. This multi-tiered structure ensures that while a few large suppliers anchor mainstream demand, specialized manufacturers continue to capture segments where qualification, environment, and customization weigh more heavily than volume economics.
The competitive evolution is moving along three axes. First, consolidation is increasing among application-focused product lines as suppliers bundle mixed-contact options into broader industrial, defense, and telecom portfolios, reducing the number of standalone purchasing decisions for system designers. Second, differentiation is shifting from basic connector availability toward faster mating systems, sealed performance, contact-level flexibility, and qualification support. HARTING's recent PushPull initiatives illustrate this direction, using coding variation and installation speed to compete on integration efficiency rather than shell geometry alone. Third, new and regional entrants are carving out niches through sealing, pricing, and customized configurations, particularly where regional supply resilience or application-specific requirements create room to bypass established catalog routes. The result is a market that is neither purely commoditized nor fully fragmented, but increasingly segmented by performance class, qualification status, and service model.
Forward Outlook: Three Trends Shaping the Next 3–5 Years
The next several years are likely to be defined by an interplay of integration, qualification discipline, and supply chain adaptation. Three trends stand out as particularly consequential.
The first trend is the continued expansion of mixed-contact functionality within increasingly compact and service-friendly mechanical designs. As installation efficiency gains importance, suppliers will keep investing in locking mechanisms, coding variations, and termination options that reduce assembly time and field-service complexity. Mixed-contact D-Sub connectors that combine high-current, coaxial, and signal paths with faster mating and improved sealing will see growing adoption in industrial automation, mission-critical control systems, and telecom infrastructure where downtime and handling errors carry significant cost. The commercial opportunity here lies in bundling mechanical convenience with electrical performance: designs that shorten integration cycles while preserving qualification integrity can command stronger attachment rates in specification-driven projects.
The second trend is the deepening importance of compliance and reliability as purchasing criteria. With overlapping environmental, quality, and performance requirements becoming standard in aerospace, defense, medical, and industrial applications, qualification maturity will increasingly determine supplier selection. Mixed-layout designs that are pre-qualified to recognized standards and offer traceable material and plating processes will benefit from shorter approval cycles and broader cross-program reuse. For manufacturers, this creates an opportunity to move beyond connector sales toward qualification support and documentation services, helping customers navigate UL recognition, lead-free requirements, and MIL-DTL-24308 expectations with less internal burden. The associated risk is that compliance timelines can compress product launch windows if engineering and testing processes are not streamlined early in development.
The third trend is supply chain adaptation in response to material and trade pressures. Tariff-related cost increases and copper input volatility will continue to influence sourcing strategies, encouraging regionalization, dual-sourcing, and more disciplined bill-of-materials planning. This shift will likely favor suppliers that can provide stable availability, predictable pricing structures, and flexible configuration options, especially for customers seeking to reduce exposure to single-region dependency. At the same time, the risk of input cost swings and policy uncertainty means that margin management will remain a central concern, and over-reliance on commodity-grade mixed-contact lines may limit resilience. Companies that can align cost discipline with differentiated contact mixing, sealing, and qualification support will be better positioned to absorb these pressures without ceding competitive ground.
Actionable Implications for Decision-Makers
For manufacturers, the most effective path is to treat mixed-contact D-Sub strategies as application-centric rather than catalog-centric. Product roadmaps should prioritize contact-level flexibility, faster mating systems, and qualified high-reliability variants where demand is concentrated in aerospace, defense, industrial automation, and medical electronics. Aligning termination options, sealing levels, and plating compliance with the expectations of target sectors can reduce qualification friction and improve win rates in specification-driven procurements.
For investors, the opportunity lies in identifying suppliers that combine steady mainstream demand with stronger-margin specialty offerings. Portfolios that balance standard mixed-layout volumes with combo, sealed, high-voltage, or MIL-qualified variants tend to offer more resilient economics in an environment shaped by tariffs and raw material pressure. Monitoring the pace of product launches that improve installation speed and coding flexibility can also provide early signals of where competitive advantage is forming, particularly when paired with broadening qualification support and application-specific assembly solutions.
For procurement and engineering leaders, the priority is to evaluate mixed-contact D-Sub solutions against total integration cost, not unit price alone. Connector families that simplify pin assignment, reduce harness count, and streamline field servicing can lower downstream labor and maintenance burdens, while pre-qualified lines can shorten approval cycles and reduce project risk. Where possible, standardizing on mixed-contact families with documented UL recognition, lead-free compliance, and relevant quality or MIL qualifications can improve supply predictability and reduce re-validation overhead across multiple programs.
Worldwide Data XLR Connector Market
Strategic clarity in this market increasingly depends on detailed, segment-level intelligence that connects product architecture, qualification requirements, regional sourcing realities, and application demand patterns. In a category where mechanical convenience, electrical performance, and compliance maturity intersect, decision-makers benefit from a precise view of where mixed-contact D-Sub value is being created and where competitive pressure is intensifying. For a fuller breakdown of segment trajectories, regional dynamics, and supplier-level positioning, the comprehensive PW Consulting market report provides the expanded analysis and structured data needed to translate these trends into actionable planning.
For detailed analysis of this topic, please visit the official page: Worldwide D-Sub Mixed Contact Connector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com