

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Soil Fumigant Market at $865M in 2026: True Growth Engines & Regional Dynamics

Strategic Trends and Commercial Opportunities in the Worldwide Soil Fumigant Market
Market Context and Core Challenges
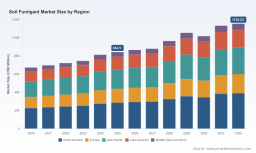
The global soil fumigant market has demonstrated sustained expansion, with total industry revenue progressing from approximately 672.4 million USD in 2020 to an estimated 842.5 million USD by 2025. Forward projections indicate continued growth through 2032, driven by consistent annual increases that point toward a market surpassing the 1.15 billion USD threshold by the end of the forecast period. The compound annual growth rate across this trajectory underscores a steady, rather than explosive, expansion pattern. This measured pace reflects an industry navigating both persistent agricultural demand and intensifying regulatory and environmental scrutiny.
Several structural challenges define the current inflection point for soil fumigant suppliers, distributors, and end-users. First, regulatory frameworks continue to tighten around application protocols, buffer zone requirements, and exposure mitigation measures. Jurisdictions such as the United States maintain reregistration eligibility decisions that establish baseline safety parameters for active ingredients including chloropicrin, metam sodium, and 1,3-dichloropropene. Regional authorities have introduced time-of-day restrictions and additional mitigation mandates, particularly in high-value crop regions where residential proximity and environmental sensitivity heighten compliance complexity. These evolving requirements reshape operational workflows and increase the cost of compliant application.
Second, the phase-down of methyl bromide under international environmental agreements has permanently altered the product mix available to growers. While limited critical use exemptions and quarantine applications persist in select regions, the broader unavailability of this once widely deployed fumigant has accelerated the transition toward alternative chemistries and integrated pest management approaches. Suppliers and distributors must continuously adapt product portfolios to match shifting compliance landscapes while ensuring effective soil-borne pest control.
Third, supply chain dynamics and raw material availability introduce volatility into cost structures. Fumigant production depends on upstream chemical intermediates whose pricing and supply consistency are influenced by broader specialty chemical manufacturing conditions. Fluctuations in precursor availability can affect formulation stability, delivery timelines, and ultimately the economics of both manufacturers and end-users. Organizations that lack diversified sourcing strategies or inventory flexibility face heightened exposure to these input-side disruptions.
Taken together, these challenges create a market environment where operational agility, regulatory literacy, and product diversification determine competitive resilience. Companies that treat compliance and supply chain management as strategic capabilities rather than administrative burdens are better positioned to sustain growth through the forecast period.
Paraquat Market
Key Drivers Shaping Market Trajectory
Technological innovation continues to reshape how soil fumigants are formulated, applied, and integrated into broader crop protection programs. Advances in delivery methods, including drip and shank application systems, enable more precise placement and reduced off-target exposure. Formulations that combine multiple active ingredients or integrate complementary modes of action address the growing need for broad-spectrum control against nematodes, weeds, and soil pathogens. These innovations respond directly to the operational constraints imposed by tighter application windows and heightened safety requirements. Manufacturers investing in application-compatible formulations and technically supported service models gain a distinct advantage in markets where performance consistency and regulatory compliance must be delivered simultaneously.
Policy and regulatory evolution operates as both a constraint and a catalyst. Reregistration programs, buffer zone mandates, and region-specific application restrictions define the operational boundaries within which fumigants can be deployed. In key agricultural states, new regulations affecting 1,3-D use and time-of-day application limits for chloropicrin and metam sodium have already altered field practices. At the same time, regulatory pressure accelerates the adoption of alternative chemistries and encourages investment in products that meet stricter exposure reduction standards. The regulatory environment therefore filters out less adaptable offerings while creating demand for solutions that align with contemporary safety and environmental expectations. Companies that maintain proactive regulatory monitoring and engage early in compliance-driven product development are better equipped to capture shifting demand.
Demand-side behavior reflects changing grower priorities driven by crop intensity, soil health considerations, and the economic imperative of yield protection. High-value fruit and vegetable production, cereals and grains, oilseeds and pulses, and turf and ornamental sectors all rely on pre-plant soil treatment to manage soil-borne threats that can undermine establishment and productivity. As rotational intensity increases and land use becomes more optimized, the need for reliable soil pest control remains stable even as product preferences evolve. Growers increasingly seek solutions that fit within integrated management programs, reduce application risk, and support consistent crop outcomes. This demand profile favors suppliers that can provide technical guidance, formulation flexibility, and regionally appropriate product recommendations rather than commoditized chemical supply alone.
Cost structure and supply chain organization represent a fourth critical driver. The reliance on specialty chemical intermediates means that feedstock availability, production capacity, and logistics performance directly influence product pricing and market responsiveness. Recent corporate activity illustrates how the industry is adapting to these dynamics. In May 2025, Dow Inc. completed the sale of its Telone soil fumigation product line to TriCal Soil Solutions, Inc., a transaction that realigned product ownership within a distribution and application-focused business model. Such moves highlight a broader trend in which manufacturers, distributors, and applicators reorganize to improve market access, streamline compliance management, and strengthen regional service capabilities. Organizations that integrate production, distribution, and application expertise can better absorb input volatility and deliver consistent value to end-users.
These drivers interact continuously. Regulatory changes influence which technologies gain traction, demand patterns determine where innovation is most needed, and supply chain structure shapes which companies can scale effectively. The market is moving toward a configuration in which technical performance, compliance readiness, and service integration are jointly evaluated by buyers, rather than price or product name acting as the primary decision factor.
Competitive Landscape and Leading Strategies
The competitive field features a mix of global crop protection companies, specialty chemical producers, and regionally focused distributors and applicators. Each group pursues a distinct strategic positioning that reflects its capabilities, regulatory footprint, and market access model.
Global Crop Protection and Specialty Chemical Players
Large multinational providers leverage broad agricultural portfolios, established regulatory affairs functions, and global manufacturing scale. Their soil fumigant offerings are typically positioned within integrated crop protection programs that combine chemical control with agronomic guidance. Companies such as Corteva Agriscience, BASF SE, Syngenta AG, FMC Corporation, and ADAMA Agricultural Solutions operate in this segment, emphasizing nematode, weed, and pathogen management through chloropicrin, metam sodium, and related formulations. Their advantage lies in the ability to support customers across multiple crop systems, maintain compliance documentation across jurisdictions, and integrate fumigant use with broader pest and disease management strategies.
PW Consulting
Specialty chemistry-focused organizations bring differentiated product technologies to the market. Arkema S.A., for example, offers DMDS-based fumigants designed for drip or shank applications in fruits, vegetables, and horticultural crops, emphasizing broad-spectrum control and application flexibility. LANXESS AG and Detia Degesch GmbH contribute through fumigant intermediates and specialty products that support formulation diversity and supply chain resilience. These players often compete on technical specificity, application compatibility, and the ability to meet particular regulatory or agronomic requirements that broader portfolios may address less directly.
Distribution and Application-Focused Operators
Distributors and applicators represent a critical layer of the market, particularly in regions where product stewardship, application compliance, and local agronomic support determine adoption. TriEst Ag Group and TriCal Group have strengthened their position through targeted acquisitions, including the 2025 acquisition of Dow's Telone product line, which expanded their soil solution capabilities and reinforced their role as both distributor and applicator. AMVAC Chemical Corporation, Gowan Company, UPL Ltd., Tessenderlo Group, Trinity Manufacturing, and Draslovka Services operate across varying combinations of manufacturing, distribution, and regional service models. Their strategic value derives from proximity to end-users, application expertise, and the ability to navigate local regulatory conditions while maintaining product availability and performance consistency.
Strategic Differentiation and Market Evolution
Leading companies differentiate through a combination of portfolio breadth, application support, regulatory readiness, and regional execution capability. Some prioritize integrated crop protection positioning that connects soil fumigation to broader agronomic outcomes. Others emphasize formulation technology and application method compatibility to meet specific compliance and performance demands. A third group focuses on distribution and application integration, ensuring that products reach the field with the technical support necessary for safe and effective use.
Greenhouse Soil Market
The market structure is evolving through selective consolidation and the realignment of product ownership. Transactions such as the divestiture of product lines to specialized distributors reflect a trend in which manufacturing assets and application-focused businesses reconfigure to capture value more efficiently. At the same time, new entrants and regional operators continue to establish niches wherever local crop systems, regulatory conditions, or supply gaps create opportunity. The overall effect is a landscape that is neither fully consolidated nor highly fragmented, but rather organized around clusters of capability that match specific market needs. Competition increasingly centers on reliability, compliance assurance, and the quality of technical support delivered alongside the product itself.
Future Outlook and Emerging Opportunities
Over the next three to five years, the soil fumigant market is likely to be shaped by three interconnected developments. First, regulatory refinement will continue to define where and how fumigants can be applied, with incremental restrictions, updated buffer requirements, and tighter application timing likely to persist in sensitive regions. This will reward companies that already operate with strong compliance infrastructure and penalize those that rely on reactive adjustment. Second, application technology and formulation innovation will gain relative importance as growers seek to maintain efficacy within narrower operational windows. Drip-compatible products, controlled-release approaches, and integrated treatment programs that combine chemical and non-chemical tactics will become more central to purchasing decisions. Third, supply chain reorganization will likely continue, with further portfolio adjustments, regional capacity realignment, and partnership models emerging to manage raw material exposure and improve delivery reliability.
These trends translate into concrete commercial opportunities. Manufacturers and formulators can expand value by developing products that align with prevailing application methods and compliance requirements, reducing the friction associated with adoption. Distributors and applicators can deepen their role as regional solutions providers, combining product selection, application scheduling, and stewardship support to build customer loyalty and differentiate from commodity supply models. Investors and strategic buyers can look for assets that enhance application capabilities, strengthen regulatory readiness, or fill supply gaps in high-demand crop regions. At the same time, uncertainty remains. Regulatory trajectories can shift with policy changes, raw material volatility can compress margins, and regional demand patterns can diverge as crop economics and land use evolve. Organizations that treat these variables as manageable risks through diversification, technical investment, and close market monitoring will be better positioned to capture the upside while limiting exposure to disruption.
Strategic Actions for Decision-Makers
For manufacturers and formulators, the priority is to align product development with the operational realities of modern application and compliance. Investing in formulations that support drip and shank applications, maintaining clear regulatory documentation, and building reliable access to key intermediates can strengthen market position and reduce vulnerability to input-side shocks. Differentiation through technical service, not just product names, is increasingly essential.
For investors and strategic acquirers, attention should focus on businesses that combine distribution reach with application expertise, regulatory competence, and stable supply relationships. Transactions that improve regional execution or secure product lines with established demand can create durable value, provided they are supported by capable stewardship and compliance operations. Due diligence should weigh regulatory exposure, raw material dependencies, and the quality of customer support infrastructure alongside financial metrics.
For growers, distributors, and procurement teams, the most effective approach is to evaluate suppliers on the basis of application compatibility, compliance assurance, and technical support, rather than unit price alone. Selecting partners that can provide regionally appropriate recommendations, monitor regulatory updates, and maintain consistent product availability reduces operational risk and improves field outcomes. Staying informed about evolving application restrictions and ingredient availability is a practical necessity, not a passive concern.
As the market continues to evolve, access to detailed segment-level data, regional regulatory tracking, and company-specific capability assessments becomes a strategic asset. Decision-makers who incorporate granular market intelligence into planning are better equipped to allocate resources, prioritize partnerships, and time commercial moves with confidence. Comprehensive research and customized analysis remain valuable tools for translating broad market dynamics into actionable strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Soil Fumigant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com