

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Worldwide Chip Probing Market: Why Automation Tools Are Reshaping Growth
By pmarketresearch, 2026-09-18
Navigating the Next Wave: Strategic Insights into the Worldwide Chip Probing Market
The worldwide chip probing market has entered a decisive phase of expansion, defined by surging test complexity and a structural shift toward higher parallelism. Valued at approximately $4.65 billion in 2025, the market has grown from $2.84 billion in 2020, reflecting a compound annual growth rate of 9.21 percent through 2032, when it is projected to approach $8.6 billion. This trajectory is not merely a function of volume; it signals a fundamental recalibration of how semiconductors are validated at the wafer level. As device architectures fracture into heterogeneous integration, chiplets, and advanced memory stacks, probing has moved from a supporting test step to a critical yield-enabling bottleneck. The base-year momentum underscores that capital is flowing into test infrastructure at a pace that outstrips historical norms, yet the expansion is unevenly distributed across technology nodes and application segments.
Beneath the headline growth, the industry confronts three interlocking challenges that will shape competitive outcomes over the next three years. First, sub-5 nanometer design complexity has slowed the introduction of new probe card architectures, with roughly one in four new designs encountering development delays as pin counts, signal integrity requirements, and thermal constraints intensify. Second, geopolitical export controls have introduced new friction into equipment flows. Refinements to the U.S. Foreign-Produced Direct Product Rule now capture certain wafer probing equipment with positioning accuracy finer than 3.5 micrometers for advanced computing applications, forcing suppliers and buyers to reconfigure supply chains and qualification pathways. Third, the economics of high-precision probing remain punishing. Fine-pitch probe cards can exceed $80,000 per unit in materials and precision assembly costs, while nearly two in five wafer test probe cards in recent years have incorporated advanced tungsten and nickel alloys to sustain durability under repeated contact cycles. These cost and complexity pressures are compressing margins for incumbents and raising the barrier for new entrants, even as demand accelerates.
The result is a market that rewards technological agility, vertical integration, and early alignment with advanced packaging and high-bandwidth memory roadmaps. Growth is no longer driven by uniform volume increases; it is being pulled by a subset of high-value applications that demand higher parallelism, lower contact resistance, and specialized RF or photonic test capabilities. Companies that can reconcile cost discipline with rapid design iteration will capture disproportionate share as the market scales toward the end of the decade.
Key Drivers Reshaping the Market
Technological Innovation and the Parallelism Imperative
The most consequential driver is the technical escalation of wafer-level testing requirements. Modern logic and system-on-chip devices, alongside high-bandwidth memory stacks, are pushing probe cards toward higher contact densities, finer pitches, and multi-site test configurations that maximize throughput. MEMS-based probe architectures and vertical probe designs have emerged as enabling technologies for these workloads, offering improved mechanical stability and better alignment with advanced node geometries. At the same time, test content is expanding beyond traditional DC and analog verification to include RF, mmWave, cryogenic, and silicon photonics characterization. This broadening test envelope is reshaping product roadmaps, as suppliers invest in specialized probe heads and integrated test systems that can address co-packaged optics and heterogeneous die-to-die interfaces. The practical effect is a market where performance differentiation increasingly hinges on the ability to deliver high-parallelism solutions without sacrificing yield or signal integrity.
Policy, Export Controls, and Infrastructure Acceleration
Policy dynamics are reshaping both the pace and geography of deployment. On one side, export control refinements have added complexity to equipment sourcing for advanced computing workloads, particularly where positioning accuracy and application context intersect with controlled thresholds. These rules do not halt demand, but they compel manufacturers to diversify supply, accelerate Qualification timelines, and in some cases re-architect test cells to remain compliant while preserving performance. On the other side, domestic semiconductor incentives are compressing time-to-production for new fab lines. Grant programs associated with national chip initiatives have helped accelerate probe card qualification for new facilities, shortening the window between process bring-up and volume test readiness. This dual force—more restrictive cross-border equipment flows paired with faster domestic fab ramp schedules—creates a distinct operating environment in which suppliers with localized manufacturing, flexible qualification processes, and broad technology portfolios gain strategic leverage.
Demand-Side Shifts: AI, HBM, and High-Performance Computing
Demand is being reconfigured by the rapid scaling of artificial intelligence accelerators, high-bandwidth memory, and high-performance computing platforms. These applications impose unusually stringent test requirements, including high contact density for multi-die validation, high-frequency signal fidelity for RF paths, and specialized handling for advanced packaging configurations. Lead-time signals already reflect this pressure: major probe card suppliers have reported extended delivery timelines, with some probe card lead times stretching to roughly six months as AI-related demand absorbs available capacity. Record financial results at several leading suppliers underscore the breadth of this demand surge, while also highlighting capacity as a binding constraint. The strategic implication is that demand is being shaped not just by unit volume but by test intensity—each advanced device now requires more probing content per wafer, amplifying the value of high-throughput, high-reliability probe solutions.
Supply Chain and Cost Structure Realities
Cost structure and material availability form the fourth pillar of change. Fine-pitch probe card production demands precision assembly and specialized alloys, pushing per-unit costs into a range that rewards scale and process maturity. The widespread use of advanced tungsten and nickel alloys in recent years reflects an industry-wide push to improve contact durability and reduce downstream yield loss, but it also ties supplier economics to material sourcing and manufacturing precision. Meanwhile, strategic partnerships and selective investments are beginning to reshape the supply base. Collaborations between test equipment producers and probe card specialists have deepened, combining complementary strengths in instrumentation, printed circuit board design, and probe technology. These alliances are accelerating development cycles and distributing risk in a market where design complexity and capacity constraints can otherwise slow responsiveness. The net effect is a supply environment in which cost discipline, material reliability, and partnership ecosystems are becoming as important as raw engineering talent.
Competitive Landscape and Leading Strategies
The competitive structure of the chip probing market is concentrated and capability-driven. The top three suppliers command a combined share in the high-sixy percent range, and the top five approach the low-eighties, reflecting the advantages of scale, established foundry and OSAT relationships, and deep application-specific engineering. Yet concentration has not translated into uniformity. Leaders are differentiating along technology axes—MEMS and vertical probe architectures, RF and photonics test readiness, cryogenic capability, and advanced packaging support—while also expanding through targeted acquisitions, capacity investments, and long-term supply agreements. The field is broad enough to accommodate specialized players in memory, logic, RF, and photonics, but the center of gravity is shifting toward suppliers that can address multiple high-growth segments without diluting technical focus.
PW Consulting
FormFactor exemplifies the integrated, high-parallelism strategy. Headquartered in Livermore, California, the company has built a portfolio around advanced wafer probe cards, including MEMS-based solutions for high-parallelism SoC, HBM, DRAM, and logic testing, alongside systems for RF, cryogenic, and silicon photonics probing. Its recent activity shows a deliberate push into capacity, partnerships, and adjacent technology domains. A new manufacturing facility in Farmers Branch, Texas, was acquired to support increased probe card demand driven by advanced packaging and HBM. In parallel, the company expanded its MeasureOne Partner Program with Rohde & Schwarz to advance on-wafer RF component characterization, and it was recognized with a 2026 Intel EPIC Supplier Award. On the inorganic side, the acquisition of Keystone Photonics extended silicon photonics and co-packaged optics wafer test capabilities. A strategic partnership with Advantest, involving minority investment and technology and PCB collaboration, further signals a preference for ecosystem alignment in probe card development. Taken together, these moves reflect a strategy that blends scale, specialized test content, and partnership-driven innovation.
Technoprobe, based in Cernusco Lombardone, Italy, competes through precision probe card design and a strong emphasis on vertical and MEMS technologies for high-volume wafer-level testing across logic, memory, and advanced packaging. Its recent supply agreement— a five-year commitment with WinWay Technology and MS SUN for MEMS probe cards based on Technoprobe’s proprietary TPEG technology—illustrates a strategy of locking in demand while extending technology reach through partners. This long-term contracting approach helps stabilize utilization and funds continued investment in high-parallelism and advanced node test solutions. MPI Corporation, headquartered in Hsinchu, Taiwan, has positioned itself around advanced probe card technologies and one-stop wafer sort test solutions, including TITAN RF probes spanning DC to 250 GHz and high-performance cards for RF, mmWave, photonics, and AI/HPC semiconductor testing. Its demand signal is notable: probe card lead times have stretched to six months amid strong AI chip demand, even as the company reported record 2025 revenue and profit alongside capacity expansion plans. MPI’s profile highlights how RF and mmWave competencies are becoming a differentiator as test content diversifies.
The regional dimension of competition is equally important. Micronics Japan and Japan Electronic Materials bring high-precision probe card expertise and close foundry collaborations, with strengths in advanced node testing, DRAM, Flash, and logic applications, as well as high-frequency materials and precision engineering. European participation remains meaningful through Feinmetall’s focus on contact probes and fine-pitch, high-reliability probe cards. In Asia, a dense cohort of suppliers—including SV Probe in Singapore, TSE and Korea Instrument in South Korea, and a cluster of Taiwanese and Korean specialists such as CHPT, WinWay Technology, Nidec SV TCL, Microfriend, STAr Technologies, and Wentworth Laboratories in the United States—demonstrates how regional manufacturing footprints and foundry relationships continue to shape access and responsiveness. This multifaceted landscape suggests two concurrent trends: consolidation among the most capable, multi-segment players, and sustained differentiation among specialists who can meet the exacting requirements of memory, RF, photonics, or advanced packaging niches. New entrants face a high bar, not only because of cost and precision demands, but because qualification cycles and customer integration depth favor incumbents with proven track records.
Probe Card Market
Future Trends and Commercial Opportunities
Looking toward 2030 and beyond, three trends are likely to define the market’s evolution. The first is the normalization of high-parallelism probing as a baseline requirement rather than a premium option. As chiplet-based designs, advanced packaging, and high-bandwidth memory become more pervasive, test cells will increasingly rely on multi-site configurations and vertical probe architectures that can address dense interface arrays with consistent contact performance. Suppliers that standardize high-parallelism platforms while retaining flexibility for application-specific variants will be best positioned to capture recurring demand and shorten qualification cycles for new device families.
Worldwide Probe Cards Market
The second trend is the convergence of probe cards with broader test ecosystems. RF, mmWave, cryogenic, and photonics test capabilities are moving from specialty add-ons to core considerations for a growing set of applications. This convergence opens commercial opportunities for integrated solutions that combine probe hardware, instrumentation alignment, and software-driven calibration, reducing the integration burden on device makers and test houses. It also favors suppliers that can orchestrate partnerships across the test chain, ensuring that wafer-level characterization keeps pace with device complexity without fragmenting accountability across too many vendors.
The third trend is geopolitical and operational decentralization. Export rule refinements and regional incentive programs are encouraging more localized qualification, manufacturing, and supply redundancy. For commercial players, this creates opportunities to build or strengthen regional capacity, align with domestic fab and packaging roadmaps, and offer predictable lead times in environments where supply assurance is becoming a competitive differentiator. The associated risk is that regulatory scope may continue to evolve, particularly around controlled accuracy thresholds and advanced computing end uses, requiring agile compliance strategies and flexible product configurations. Design complexity for leading-edge nodes will remain a persistent source of delay risk, and material cost volatility can pressure margins if not offset by scale or value-based pricing. Companies that treat these uncertainties as design inputs—by diversifying supply, modularizing probe architectures, and investing in early co-development with customers—will convert risk into durable advantage.
Strategic Actions for Decision-Makers
For probe card manufacturers and test equipment suppliers, the priority is to align capacity expansion with the highest-value demand nodes while preserving technology breadth. Investing in high-parallelism platforms, RF and photonics readiness, and advanced packaging test content should be paired with long-term supply agreements and selective partnerships that stabilize utilization and shorten development cycles. Localized manufacturing and qualification agility will increasingly matter as customers seek predictable lead times and regulatory resilience. Differentiation will come less from generic scale than from the ability to deliver repeatable performance across demanding applications while controlling per-unit cost through process maturity and material strategy.
For investors, the market’s growth is real, but share gains will be uneven. The most compelling opportunities lie with suppliers that demonstrate multi-segment capability, especially where MEMS, vertical probe, RF, and photonics competencies intersect with AI/HPC and HBM roadmaps. Monitoring lead-time signals, capacity announcements, and partnership or acquisition activity provides early indication of which players are converting demand into durable positioning. Valuation should account for the capital intensity of precision assembly, the importance of alkalinity in materials sourcing, and the potential for consolidation among mid-tier specialists who lack the breadth to compete across logic, memory, and advanced packaging.
For procurement and test strategy leaders, the practical imperative is to reduce integration risk while preserving optionality. Prioritize suppliers with proven qualification depth and the ability to support multiple test modalities, and structure agreements to balance volume commitments with flexibility for evolving device architectures. Engaging earlier in the design cycle—aligning probe card selection with packaging, interface, and test content decisions—can compress qualification timelines and mitigate the delays associated with leading-edge node complexity. Building redundancy into the supplier base, where feasible, helps manage exposure to export control shifts and capacity constraints without sacrificing performance.
The chip probing market is being reshaped by the simultaneous pull of advanced device complexity, policy-driven supply reconfiguration, and demand intensity from AI and high-performance computing. Navigating this environment requires more than broad market data; it demands segment-level visibility into technology roadmaps, supplier capabilities, and the contractual and regulatory dynamics that determine who captures value as the market scales. For decision-makers seeking granular segmentation, regional demand patterns, and tailored strategic recommendations, the full PW Consulting study provides the detailed evidence base and scenario analysis needed to translate these trends into concrete action.
For detailed analysis of this topic, please visit the official page: Worldwide Chip Probing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Insulated Cup Sleeves Market: Why the 5.76% CAGR Tells a Deeper Resilience Story
By pmarketresearch, 2026-09-18
The Worldwide Insulated Cup Sleeves Market: Strategic Trends and Commercial Opportunities Through 2032
The global insulated cup sleeves market has evolved from a peripheral accessory into a strategically significant segment within the broader foodservice packaging ecosystem. Valued at USD 1,458.6 million in 2025 and projected to expand at a compound annual growth rate of 5.76 percent through 2032, the market reflects a structural shift in how hot and cold beverages are packaged, delivered, and perceived by end users. Historical revenue progression from 2020 through 2025 demonstrates consistent upward momentum, with the segment crossing the 1,400 million threshold in 2024 before accelerating into the mid-1,500 million range in 2026. The trajectory continues upward through the forecast horizon, surpassing 2,150 million by 2032, signaling sustained commercial relevance beyond short-term consumer fads.
This growth is not merely a function of volume expansion. It represents a convergence of regulatory pressure, sustainability mandates, material innovation, and shifting handling expectations across both commercial and residential channels. Insulated cup sleeves now serve dual purposes: thermal protection and brand communication, while increasingly operating as a compliance touchpoint in jurisdictions tightening rules around single-use packaging. For executives and investors, the market offers a window into how disposable food accessories are being redesigned to align with circular economy principles without sacrificing cost efficiency or user experience.
Despite the favorable trajectory, the industry faces several structural challenges that will define competitive outcomes over the next cycle. First, the transition toward higher recycled content and alternative fiber sources introduces variability in supply consistency, pricing, and performance characteristics. Manufacturers must balance sustainability targets with the physical requirements of thermal insulation, print fidelity, and stackability. Second, regulatory frameworks across Europe, North America, and parts of Asia are increasingly tying compliance costs to recyclability metrics and post-consumer content thresholds, reshaping procurement economics and pushing smaller producers into difficult positioning decisions. Third, the market remains moderately fragmented, with concentration levels indicating room for consolidation but also leaving space for niche players who can differentiate through material science, custom engineering, or regional service models. Navigating these dynamics requires more than volume scaling; it demands strategic clarity around material selection, compliance readiness, and end-user value propositions.
Key Drivers Reshaping the Insulated Cup Sleeves Market
Material Innovation and Thermal Performance Engineering
Material selection has moved from a cost-centric decision to a performance and compliance-driven strategic lever. Kraft paper and corrugated paperboard, whether sourced from virgin or post-consumer recycled fiber, continue to anchor the segment due to their balance of cost efficiency, printability, and consumer familiarity. However, manufacturers are increasingly deploying embossed architectures, textured surfaces, and engineered air-trapping geometries to enhance insulation without simply adding material weight. Embossed fiber formats, for instance, allow producers to reduce basis weight while maintaining thermal resistance, creating a direct link between design innovation and margin preservation. Water-based and polylactic acid coatings are also gaining traction as alternatives to conventional barriers, particularly where compostability or recyclability claims must be substantiated. These developments are not incremental; they are redefining the cost-performance envelope and enabling sleeve solutions that align with both handling expectations and end-of-life requirements.
Regulatory Pressure and Extended Producer Responsibility
Policy momentum is reshaping procurement behavior across multiple regions. The EU Single-Use Plastics Directive and associated Extended Producer Responsibility schemes now encompass single-use packaging items, including paper-based beverage accessories, requiring producers to finance collection and recycling infrastructure. In the United Kingdom, the expanding EPR framework for packaging introduces fees structured around recyclability and recycled content, directly influencing the economics of disposable sleeves. Similar dynamics are emerging in California through SB 54, which establishes extended producer responsibility for packaging and is steering foodservice procurement toward recyclable fiber-based formats. These regimes do not merely impose compliance costs; they alter the relative attractiveness of material choices, reward higher recycled fractions, and penalize designs that complicate recovery streams. Companies that anticipate these requirements in product architecture and sourcing strategies can convert regulatory pressure into a procurement advantage rather than a reactive expense.
Demand-Side Shifts Among Consumers and Commercial Buyers
End-user expectations are increasingly shaping sleeve design and specification. Coffee shops and cafes remain the dominant commercial channel, where sleeves function as both thermal protection and a canvas for branding, making printability, consistency, and fit critical. Household consumers represent a growing segment, driven by at-home beverage preparation, reusable cup ecosystems that still require disposable protection in certain contexts, and heightened sensitivity to tactile comfort and environmental claims. Corporate and institutional buyers add another layer of complexity, as procurement teams evaluate total cost of ownership, compliance alignment, and visibility into material provenance. Across these channels, the common thread is a demand for sleeves that perform reliably, communicate sustainability credibly, and integrate smoothly into existing cup formats without introducing friction in high-volume environments.
Supply Chain Reconfiguration and Cost Structure Dynamics
The cost structure of insulated cup sleeves is being recalibrated by fiber availability, recycled content sourcing, energy inputs, and regional manufacturing footprints. As producers increase reliance on post-consumer recycled fiber, they must manage variability in pulp quality, contamination risk, and processing requirements. At the same time, the push toward fossil-free production and lower carbon intensity is influencing facility investments and logistics decisions. Some manufacturers are positioning around localized production to reduce transport emissions and respond faster to regional compliance mandates, while others are scaling centralized capacity to optimize material purchasing and technical development. These contrasting models reflect a broader divergence in how companies are managing the trade-off between agility and scale, with implications for pricing stability and service levels across customer segments.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of established packaging groups, specialized fiber innovators, and regionally focused producers. Leadership is increasingly defined not by volume alone but by the ability to align material science, sustainability credentials, and application-specific engineering. Several companies have built differentiation around distinct value propositions that illustrate where the market is heading.
One major player has expanded its portfolio around hot cup sleeves designed as accessories for single-wall paper cups, while also advancing insulated cup formats that incorporate a built-in thermal effect, reducing the need for separate sleeves in certain applications. Its emphasis on post-consumer recycled fiber and recognized forestry standards positions it at the intersection of performance and responsible sourcing. Another leading supplier has focused on deeply embossed fiber formats engineered for superior thermal insulation with reduced material consumption, emphasizing printability and a high degree of fossil-free production. This approach illustrates how design-led material use can simultaneously address cost, performance, and environmental targets. A China-based manufacturer has concentrated on custom recyclable paper sleeves compatible across common cup sizes, offering corrugated or textured designs that protect against heat or cold transfer while supporting custom printing and recycled fiber options. This model highlights the importance of application flexibility and regional customization in capturing demand across diverse foodservice configurations.
Worldwide Paper Cup Sleeve Market
Several companies have carved out strong positions in compostable and recycled-content sleeves, targeting operators and institutional buyers seeking credible end-of-life claims. One U.S.-based producer offers sleeves made from recycled paper content that are fully compostable and designed for comfortable handling across a range of cup sizes. Another focuses on sleeves made entirely from post-consumer recycled paper, aligned with sustainable foodservice applications. A Finnish manufacturer adds a premium kraft sleeve offering and insulated paper cup designs that integrate insulation into the cup itself, reducing dependence on separate sleeves in premium segments. Meanwhile, a global packaging group has advanced recyclable sleeve solutions with high post-consumer recycled content, reinforcing a circular packaging narrative across beverage applications. These varied strategies show that differentiation is increasingly multidimensional, spanning material composition, end-of-life pathway, thermal engineering, and brand trust.
Recent recognitions underscore how sustainability and performance are converging in corporate positioning. One global supplier received an industry award for a stretch sleeve solution containing up to 75 percent post-consumer recycled material and associated with significantly lower CO₂ emissions, supporting circular packaging in beverage sectors. The same company was later named Packaging Company of the Year at a major UK awards program, reflecting leadership in sustainability, innovation, and performance, including sleeve solutions. These milestones matter because they signal to procurement teams and investors that recyclable, high-recycled-content designs are moving from pilot concepts to commercially validated offerings with external validation.
Market structure is likely to continue evolving along two tracks. On one hand, consolidation and partnership will remain attractive for players seeking broader geographic coverage, integrated material sourcing, and scaled compliance capabilities. On the other hand, differentiation will protect specialized producers who can offer superior insulation per gram, credible compostability or recyclability claims, or rapid custom response for regional foodservice channels. New entrants will find opportunity not in commodity overlap but in targeted engineering, compliance-forward material choices, and service models that reduce friction for high-volume buyers. The result is a landscape where scale and specialization can coexist, but only if each player clearly owns a defensible value proposition.
Forward Outlook: Trends Shaping the Next 3–5 Years
Several interrelated trends are likely to define the insulated cup sleeves market through the early 2030s. First, design-led efficiency will become a central competitive battleground. As material costs and compliance costs rise, producers that can deliver equivalent or better thermal protection with less fiber, more precise embossing, and smarter cup-sleeve integration will capture margin and procurement preference. This trend favors companies that invest in prototyping, application testing, and close collaboration with cup manufacturers, because the most efficient solutions often emerge at the interface between cup and sleeve rather than within either component alone.
Second, compliance-aligned material procurement will shift from a defensive requirement to a sourcing advantage. Extended producer responsibility frameworks and recycled content expectations are expanding the premium on traceable fiber, lower fossil intensity, and designs that fit existing recovery streams. Buyers will increasingly treat recyclability, compostability, and recycled fraction not as marketing attributes but as procurement prerequisites. This creates opportunities for suppliers that can document content composition, provide consistent lot-to-lot quality, and align sleeve architecture with regional end-of-life infrastructure. It also raises the stakes for companies that rely on ambiguous claims or inconsistent material streams, since procurement scrutiny is likely to intensify.
Third, application segmentation will deepen as channel needs diverge. Coffee shops and cafes will continue to prioritize fit, print quality, and throughput reliability. Household consumption will reward comfort, reusability compatibility, and clarity around environmental attributes. Corporate and institutional procurement will weigh compliance documentation, total cost, and supply continuity more heavily. The practical implication is that one-size positioning will lose ground to channel-tuned offerings, with modular design platforms and configurable material options becoming more valuable than rigid standardized SKUs. The opportunity lies in building flexible production and specification systems that can serve multiple channels without sacrificing cost discipline.
These trends carry risk. If recycled fiber availability tightens or quality variability increases, cost structures could become less predictable, particularly for smaller producers. If regulatory definitions around compostability, recyclability, or recycled content diverge across regions, compliance complexity could erode the benefits of otherwise strong product designs. If cup manufacturers accelerate integrated insulation features, separate sleeve demand could shift in certain premium formats, redistributing volume rather than eliminating it. Companies that monitor these forces closely and maintain agile sourcing, design, and compliance capabilities will be better positioned to convert uncertainty into commercial advantage.
Worldwide Ice Silk Sleeves Market
Actionable Guidance for Decision Makers
For manufacturers and material suppliers, the priority is to invest in insulation efficiency and compliance-ready material streams in tandem. Reducing basis weight through embossing and structural design, expanding verified recycled content, and aligning sleeve architecture with regional recovery expectations can protect margins while strengthening procurement appeal. Equally important is building close feedback loops with cup producers and high-volume foodservice buyers, because the most valuable innovations often emerge from integrated fit, handling, and printing requirements rather than from material substitution alone.
For investors, the signal is to distinguish between commoditized scale plays and differentiated capability plays. Volume growth is real, but sustained outperformance is likely to concentrate among companies that can demonstrate credible sustainability performance, consistent quality at higher recycled fractions, and application-specific engineering that reduces total handling cost for end users. Due diligence should evaluate not only capacity and footprint but also traceability systems, regulatory readiness, and the strength of customer relationships in channels where sleeve specifications are becoming more rigorous.
For procurement teams and brand operators, the focus should shift from price-per-unit comparisons to total value across handling, compliance, and supply reliability. Sleeves that fit consistently, protect comfortably, and align with local recycling or composting infrastructure can reduce operational friction and reputational risk. Evaluating suppliers on documented material composition, print performance, and continuity of supply will become more important as specifications tighten and channel expectations diverge. Where possible, coordinating sleeve selection with cup format decisions can unlock efficiency gains that are not visible when the two are procured in isolation.
The market trajectory through 2032 suggests that insulated cup sleeves will remain a meaningful and evolving segment within foodservice packaging, shaped by material engineering, regulatory alignment, and channel-specific demand. Executives who treat the category as a strategic interface between product performance, compliance, and brand trust will be better positioned to capture the opportunities embedded in the growth path. For organizations seeking deeper segmentation, competitive benchmarking, and customized procurement or investment scenarios, the full PW Consulting research report provides the detailed data and scenario-based analysis needed to translate these market-level insights into operational decisions.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Insulated Cup Sleeves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Chassis-by-Wire Market: Why 19.5% CAGR and Brake-by-Wire Shift Change Everything
By pmarketresearch, 2026-09-18
The Chassis-by-Wire Revolution: Strategic Trends and Commercial Opportunities in a Rapidly Evolving Market
Market Current Status & Core Challenges
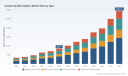
The global chassis-by-wire system market has entered a phase of rapid expansion, driven by the convergence of electrification, software-defined vehicle architectures, and escalating demands for advanced driver assistance capabilities. Valued at approximately USD 8.4 billion in 2025, the sector has demonstrated a compound annual growth rate of 19.5 percent over the recent historical period and is projected to sustain this aggressive trajectory through the forecast horizon ending in 2032. This growth reflects a structural shift away from hydraulic and electromechanical linkages toward fully digital, electronically mediated control systems across braking, steering, suspension, and transmission interfaces. The transition is not merely incremental; it represents a foundational rearchitecture of how vehicles interpret driver intent, manage dynamic stability, and interface with autonomous driving stacks.
Despite the robust growth trajectory, the industry faces several critical inflection points that will determine which players capture sustainable value. First, functional safety and redundancy remain paramount. Chassis systems are inherently safety-critical, and replacing mechanical fail-safes with electronic architectures demands rigorous validation, dual-redundant control loops, and fail-operational designs. The absence of universally harmonized standards outside major regulatory jurisdictions introduces compliance complexity and slows cross-market product rollouts. Second, the integration depth required to realize the full value of chassis-by-wire architectures is reshaping supplier-OEM relationships. Standalone actuators are increasingly insufficient; OEMs demand cohesive software platforms, real-time vehicle dynamics control, and seamless connectivity with domain controllers. Suppliers that cannot deliver integrated, software-enabled solutions risk commoditization. Third, the supply chain for high-reliability power electronics, precision sensors, and safety-certified semiconductors remains constrained. Scaling production while maintaining ASIL-D compliance creates bottlenecks, particularly as multiple OEMs and tier suppliers simultaneously accelerate commercialization timelines.
Key Drivers Shaping the Market
Technological innovation stands as the primary catalyst for chassis-by-wire adoption. The maturation of high-response electric actuators, low-latency communication buses, and advanced torque and position sensors has enabled steering, braking, and suspension systems to operate with precision previously achievable only through mechanical linkages. More importantly, these components are now being bundled into cohesive platforms that support over-the-air updates, predictive stability control, and seamless integration with advanced driver assistance systems. The shift toward software-defined vehicles amplifies this effect, as chassis functions become programmable layers rather than fixed hardware assemblies. Suppliers that have historically operated in isolated component silos are now competing on the basis of system-level integration, algorithmic control, and lifecycle software support.
Regulatory and standardization developments are simultaneously accelerating and shaping deployment pathways. Several major markets have moved to explicitly accommodate steer-by-wire and brake-by-wire architectures within their regulatory frameworks, provided that systems meet stringent functional safety and cybersecurity requirements. The push toward ISO 26262 compliance at ASIL-D levels, combined with cybersecurity standards such as ISO/SAE 21434, has raised the bar for entry but also created defensible moats for established players with proven validation pipelines. International standardization bodies are actively developing guidelines that clarify safety expectations for steer-by-wire systems in passenger and light commercial vehicles, offering a more predictable compliance landscape. At the same time, regional regulatory bodies have begun publishing national standards that explicitly incorporate steer-by-wire requirements, with participation from both OEMs and component suppliers. This institutional recognition reduces ambiguity for engineers and procurement teams, encouraging broader adoption beyond pilot programs.
On the demand side, consumer and fleet behavior is reinforcing the technology shift. Electrified platforms inherently free up packaging constraints associated with hydraulic lines and mechanical linkages, making by-wire systems more attractive from both a weight and design flexibility standpoint. Automakers pursuing advanced maneuvering features, reduced cabin intrusion, and enhanced driver comfort are increasingly viewing chassis-by-wire as a strategic enabler rather than a compliance checkbox. In the commercial segment, fleet operators and logistics-focused OEMs are evaluating digital chassis architectures for improved energy efficiency, predictive maintenance, and alignment with higher levels of automated operation. The commercial vehicle segment, while smaller in absolute terms than passenger cars, is gaining momentum as operators seek differentiated reliability and total cost of ownership profiles.
Supply chain and cost structure dynamics are also evolving. The transition to by-wire architectures redistributes value toward electronics, software, and system integration, while reducing reliance on traditional hydraulic components and metal-intensive linkages. However, the initial capital intensity of developing fail-operational architectures, dual-redundant controllers, and safety-certified microcontrollers remains high. Suppliers are responding by offering modular portfolios that span electric, hydraulic, and hybrid actuation options, allowing OEMs to phase adoption based on vehicle segment, safety certification timelines, and cost targets. Semiconductor and power electronics availability continues to influence production pacing, but strategic partnerships between chipmakers, tier suppliers, and OEMs are gradually stabilizing the supply base. The emergence of integrated chassis control platforms is also creating economies of scale, as shared software stacks and common sensor suites reduce per-unit engineering costs across vehicle programs.
Technology Innovation and System-Level Integration
The competitive advantage in chassis-by-wire is increasingly defined by how effectively suppliers can combine actuation hardware with control software, safety architecture, and vehicle dynamics algorithms. Companies that offer one-box or tightly integrated solutions are gaining traction with OEMs seeking to simplify wiring harnesses, reduce part counts, and accelerate software-defined chassis development. The ability to deliver steer-by-wire systems with stowable column options, electro-mechanical brake architectures, and integrated suspension actuation under a unified software layer is becoming a differentiator in premium and technology-forward vehicle segments. This integration push is also driving collaboration across the value chain, with semiconductor suppliers playing a more visible role in enabling high-safety motor control and real-time processing for by-wire applications.
PW Consulting
Policy, Standards, and Regulatory Clarity
Regulatory evolution is acting as both an enabler and a gatekeeper. As international and regional standards begin to articulate explicit requirements for steer-by-wire and brake-by-wire systems, engineers gain clearer design targets and validation pathways. The allowance of steer-by-wire architectures without mechanical backup under defined conditions in certain regulatory frameworks has reduced a long-standing barrier to full by-wire deployment. Simultaneously, the expectation of dual-controller architectures, redundant power supplies, and fail-operational behavior reinforces the need for robust engineering and testing capabilities. Suppliers with established functional safety certification records and proven cybersecurity processes are positioned to benefit from this regulatory maturation, while newer entrants must navigate a steep compliance curve.
Competitive Landscape and Leading Strategies
The market is characterized by a concentrated group of multinational suppliers with deep chassis engineering heritage, complemented by regional specialists and technology-focused entrants. The top three players account for a substantial share of industry revenue, while the top five collectively represent a majority of total market value. This concentration reflects the capital intensity, safety validation requirements, and long qualification cycles inherent to chassis-by-wire systems. However, the landscape is dynamic, with consolidation, partnership formation, and targeted acquisitions reshaping competitive positions.
Leading suppliers are pursuing distinct strategic playbooks. Continental AG has positioned itself around integrated electronic braking and chassis control solutions tailored for software-defined vehicles, emphasizing system-level coherence across brake-by-wire and broader chassis functions. ZF Friedrichshafen AG has expanded its portfolio to cover comprehensive brake-by-wire and steer-by-wire offerings, including one-box systems and a dedicated chassis solutions division that addresses light vehicles and software-defined chassis architectures. In mid-2025, ZF unveiled a broad brake-by-wire portfolio encompassing electric, hydraulic, and hybrid options, signaling flexibility to accommodate varying OEM safety strategies and cost targets. Robert Bosch GmbH continues to leverage its full chassis integration expertise, developing steer-by-wire and brake-by-wire systems that align with ADAS, automated driving, and electrified platform requirements.
Nexteer Automotive has built a focused steer-by-wire and brake-by-wire narrative, offering stowable column steer-by-wire options and an electro-mechanical brake system aimed at motion control and software-defined chassis integration. In 2025, the company launched its electro-mechanical brake system to enhance safety, comfort, and serviceability while reinforcing chassis-by-wire integration. Shortly thereafter, it achieved ASIL D functional safety certification for its steer-by-wire system with multi-layer redundancy and participated actively in China’s chassis-by-wire standards development. Nexteer’s engagement in Chinese standardization efforts, alongside supply of steer-by-wire and brake-by-wire systems to multiple domestic OEMs, illustrates how regional market access and standards influence strategy. Meanwhile, Li Auto implemented combined steer-by-wire and brake-by-wire in its L9 Livis model under a “big chassis” architecture, with subsequent deployments from other Chinese OEMs, signaling rapid commercial integration in one of the most active electrification markets.
Server Chassis Market
Regional and technology specialists are carving niches that complement the larger players. JTEKT Corporation specializes in steer-by-wire systems and chassis components, scaling production for EV and autonomous platforms. Schaeffler AG is advancing steer-by-wire and integrated actuation for vehicle motion control, while thyssenkrupp AG focuses on steer-by-wire with innovative feedforward control and vehicle motion control integration that operates independently of traditional steering column infrastructure. Kongsberg Automotive has emphasized fail-operational steer-by-wire systems, strengthened through the acquisition of Chassis Autonomy SBA AB to target autonomous and commercial vehicle applications. Infineon Technologies AG supplies the underlying chipsets and semiconductors that enable high-safety steer-by-wire and chassis-by-wire motor control, highlighting the strategic importance of the semiconductor layer in this ecosystem.
The market trajectory points toward continued consolidation at the system-integration tier, as OEMs prefer fewer, deeper partnerships that can deliver validated, software-enabled chassis platforms. At the same time, differentiation is intensifying in areas such as fail-operational architecture, cybersecurity, regional standards alignment, and packaging flexibility. New entrants with strong software stacks, specialized redundancy designs, or cost-competitive actuation technologies may find opportunities in commercial vehicles, autonomous shuttles, or specific regional markets where certification pathways are clearer and deployment cycles are shorter. The overall pattern is one of convergence around integrated platforms, paired with ongoing fragmentation in specialized capabilities and regional go-to-market strategies.
Future Trends and Commercial Opportunities
Over the next three to five years, the most consequential trend will be the mainstreaming of software-defined chassis architectures that treat steering, braking, and suspension as programmable, data-rich subsystems rather than isolated hardware. As more OEMs deploy combined steer-by-wire and brake-by-wire configurations, the value pool will shift from component supply toward system integration, control algorithms, and lifecycle software management. Commercial opportunities will accrue to suppliers that can offer validated redundancy, rapid calibration tools, and OTA-capable platforms that reduce time-to-market for next-generation vehicle programs. Companies that bridge the gap between component performance and vehicle dynamics optimization will be well positioned to capture premium pricing and longer-term service relationships.
A second trend is the convergence of chassis-by-wire adoption with higher levels of automated driving and commercial fleet electrification. As passenger cars and light commercial vehicles incorporate more advanced driver assistance and partial automation features, the need for precise, latency-sensitive chassis control will intensify. This creates opportunities for fail-operational steer-by-wire systems, integrated vehicle motion control, and architectures that simplify the interface between chassis actuators and autonomy stacks. The commercial vehicle segment, while historically slower to adopt, may accelerate as operators seek energy efficiency, predictable maintenance schedules, and platform commonality across fleets. Suppliers that tailor redundancy and validation approaches to commercial duty cycles, rather than simply adapting passenger car solutions, can open a differentiated niche.
A third trend involves regulatory and standards harmonization reducing deployment friction across markets. As international guidelines and national standards clarify safety expectations for steer-by-wire and brake-by-wire systems, engineering teams will face fewer ambiguous compliance questions, and OEMs will be more willing to commit to by-wire architectures in volume programs. This trend favors suppliers with mature functional safety processes and established cybersecurity frameworks, while also lowering barriers for regional players that can align quickly with local standards. The downside risk is that rapid regulatory evolution can still create uneven compliance requirements across jurisdictions, forcing suppliers to maintain multiple validation tracks. Additionally, semiconductor availability, cost volatility in power electronics, and the engineering complexity of fail-operational designs will continue to temper the pace of adoption in cost-sensitive segments. Strategic flexibility, modular portfolios, and clear safety case documentation will be essential to navigate these uncertainties.
Chassis Sensor Market
Strategic Recommendations for Decision Makers
For vehicle manufacturers and platform architects, the priority is to treat chassis-by-wire as a system-level capability rather than a components upgrade. Selecting partners that can deliver integrated steer-by-wire and brake-by-wire solutions with proven ASIL-D functional safety, fail-operational redundancy, and software-defined integration will reduce program risk and accelerate time-to-market. Aligning hardware choices with broader software architecture plans, including OTA capability and vehicle dynamics control strategies, will determine whether by-wire investments translate into competitive differentiation or merely compliance.
For investors and strategic planners, the opportunity lies in identifying suppliers and technology enablers with defensible safety validation pipelines, scalable redundancy architectures, and strong positions in emerging standardization processes. Companies that combine actuation hardware expertise with software control capabilities, or that provide critical semiconductor and sensor layers for high-safety chassis applications, are likely to capture disproportionate value as the market expands. Monitoring regional standards development and early commercial integrations in leading EV markets can provide leading indicators of volume adoption and partnership shifts.
For procurement and supply chain leaders, diversification and qualification strategy are essential. Given the safety-critical nature of chassis-by-wire systems, relying on a single source for redundant controllers, power electronics, or actuator assemblies introduces concentration risk. Building qualified secondary sources, aligning on cybersecurity and functional safety documentation requirements early, and securing visibility into semiconductor and power electronics roadmaps will help stabilize production schedules. Engaging with suppliers that offer modular electric, hydraulic, and hybrid options can provide flexibility to balance cost, safety certification timelines, and vehicle segment requirements.
Given the pace of technical evolution, regulatory change, and commercial integration activity, decision makers benefit from detailed, segment-level intelligence that maps supplier capabilities, regional standards trajectories, and deployment timelines to specific vehicle programs. Access to comprehensive market research and customized analysis can clarify which architectures, partnerships, and geographic pathways offer the strongest risk-adjusted opportunity in the years ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Chassis-by-Wire System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fast Electric Rolling Door Market: How 7.85% CAGR and Shifts Reshape Strategy Through 2032
By pmarketresearch, 2026-09-18
The Fast Electric Rolling Door Market: Strategic Trends and Commercial Opportunities (2025–2032)
Market Landscape and Core Challenges
The fast electric rolling door market has evolved into a critical infrastructure segment for industrial, commercial, and logistics operations worldwide. Valued at approximately 712.6 million in 2025, the market is projected to reach 1.2 billion by 2032, expanding at a compound annual growth rate of 7.85 percent over the forecast period. This trajectory reflects more than steady replacement cycles; it signals a structural shift in how facilities manage energy, throughput, and environmental controls. The base year of 2025 captures a market that has already absorbed several years of accelerated demand, with historical growth from 2020 through 2025 demonstrating consistent upward momentum across multiple end-use sectors and geographies.
Beneath the headline figures, three interconnected challenges are reshaping how manufacturers, distributors, and end-users approach this market. First, raw material volatility has become a persistent margin pressure. Steel and aluminum pricing swings, compounded by trade policy adjustments in recent years, are creating unpredictable input costs and forcing suppliers to reconsider pricing structures, inventory strategies, and product mix. Second, energy efficiency expectations are no longer optional specifications. Federal building energy standards and revised incentive frameworks are pushing facility operators to prioritize doors that reduce air exchange, limit thermal loss, and integrate more tightly with broader building management systems. This shifts procurement discussions from simple durability and cycle speed toward total cost of ownership and compliance alignment.
Third, the market is navigating a quality-versus-speed tension that affects both product design and adoption curves. Operators in high-traffic environments demand faster cycle times, improved impact resistance, and reliable automated refeed functionality, yet these performance enhancements often require more sophisticated control electronics, reinforced components, and tighter manufacturing tolerances. Suppliers that can balance rapid deployment with long-term reliability are gaining traction, while those competing primarily on price are facing margin compression and higher warranty exposure. Together, these challenges define a market that is maturing quickly but still offers meaningful differentiation for players that can align product architecture, cost discipline, and regulatory awareness.
Key Demand Drivers Reshaping the Segment
Technology Innovation and Performance Expectations
Product innovation remains one of the most direct catalysts for market expansion. High-speed door manufacturers are increasingly launching tiered product families that balance premium performance with cost-sensitive configurations. Recent releases have emphasized enhanced customization, modular control options, and variants designed for distinct industrial environments, allowing buyers to match door specifications more precisely to application requirements. At the same time, advances in fabric-based rolling systems, rigid slat designs, and composite constructions are broadening the range of operating conditions these doors can support. The practical effect is not just faster doors, but doors that integrate more cleanly into modern facility workflows, reduce downtime during maintenance, and maintain performance in aggressive environments such as cold storage and high-traffic loading areas.
High Speed Doors Market
Policy and Regulatory Environment
Regulatory and incentive mechanisms are becoming powerful levers in procurement decisions. Federal building energy efficiency standards are pushing commercial and industrial facilities to reduce on-site energy consumption, which directly increases the value of doors that minimize conditioned air loss during frequent openings. At the same time, incentive programs tied to certified efficient exterior doors have improved the financial case for upgrades, particularly for organizations planning phased facility modernization. These dynamics are not simply compliance issues; they are reshaping specification criteria. Facility managers and engineers increasingly evaluate door selections through an energy-performance lens, weighing cycle speed, sealing behavior, and integration potential alongside traditional factors like durability and footprint.
Demand-Side Shifts in Warehousing, Cold Chain, and Manufacturing
End-use demand is being driven by operational intensity rather than incremental replacement alone. Warehouse and logistics facilities continue to prioritize throughput, requiring door systems that support frequent, automated passage while controlling environmental drift. Food processing and cold storage operators face even stricter temperature retention requirements, making fast cycle times and reliable sealing critical to product integrity and energy costs. Automotive and general manufacturing environments add another layer of demand, where impact resistance, safety performance, and integration with material-handling workflows matter as much as speed. As these sectors expand or modernize, the door becomes less of a passive barrier and more of an active component in facility efficiency, which broadens the addressable market and raises the performance baseline for competitive products.
Automatic Door Market
Supply Chain and Cost Structure Dynamics
Cost structure pressures are reshaping supplier strategies across the value chain. Fluctuations in steel pricing, along with periodic trade measures affecting steel and aluminum inputs, have translated into meaningful installation-level price variability depending on material composition. These conditions reward manufacturers that can optimize material usage, offer alternative constructions where appropriate, and maintain flexible production planning. They also encourage greater attention to regional production footprints and supply continuity. Recent expansion activity in select markets, including localized production moves in Southeast Asia, reflects an effort to reduce exposure to logistics delays, currency risk, and input cost uncertainty. For buyers, this environment means that lead times, warranty terms, and service availability are becoming just as important as unit price in evaluating long-term value.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of specialized high-speed door manufacturers, broader rolling-door producers, and regional players with strong compliance or installation capabilities. Market concentration remains moderate, with the top three and top five firms holding meaningful but not dominant shares, indicating room for continued differentiation and selective consolidation. Leading participants generally compete on a combination of speed, durability, automation features, and application-specific engineering rather than on commodity pricing alone. This positions the market as one where product architecture, control technology, and service networks often determine share gains more than volume alone.
Several strategic profiles stand out. Some manufacturers emphasize high-performance fabric and rigid overhead systems designed for industrial, cold storage, and commercial environments, building reputation on large installed bases and repeatable reliability. Others focus on high-speed roll-up and fabric door lines that target logistics and facility applications where throughput and ease of operation are paramount. European manufacturers have often leaned into advanced control technology, spiral and vertically opening high-speed designs, and refined engineering for demanding industrial use. In parallel, U.S.-based producers have expanded product lines that highlight energy efficiency, impact resistance, and automated refeed capabilities for warehouses and loading docks. Traditional steel door manufacturers and service-door specialists remain relevant in applications where security, heavy-duty use, and code compliance carry significant weight. Meanwhile, regional fabricators with hurricane-zone or local code expertise maintain strong positioning in jurisdictions where compliance and installation know-how are decisive buying factors.
Recent company actions illustrate how these strategies are evolving. Tiered product launches are giving buyers more granular choices across premium, eco, and basic configurations, supporting customization without forcing a one-size-fits-all approach. Updates to existing high-performance lines have reinforced the importance of energy efficiency and impact resistance for commercial facilities. Selective geographic expansion, including regional acquisitions to strengthen local production, indicates a growing emphasis on supply resilience and proximity to end markets. New high-performance steel door introductions with improved opening speeds also show that speed remains a competitive battleground even in more traditional product categories.
The broader market evolution appears to be moving along two tracks simultaneously. On one hand, integration is likely to continue as larger players seek to strengthen regional presence, acquire niche capabilities, or broaden application coverage. On the other hand, segmentation will remain important because requirements differ sharply across cold storage, logistics, manufacturing, and specialty code-driven environments. New entrants face a realistic bar: success typically depends on solving a clear operational pain point, such as cycle speed with robust refeed behavior, improved thermal performance, or compliance-ready designs for specific regions. Companies that can pair product performance with reliable service, clear specification support, and cost-stable material strategies are best positioned to convert market growth into durable share.
Forward-Looking Trends for the Next Three to Five Years
Several trends are likely to shape the market through the late 2020s and early 2030s. The first is deeper integration of door performance with building energy strategy. As efficiency expectations become embedded in procurement specifications and incentive structures, fast electric rolling doors will increasingly be evaluated as part of a facility’s overall energy and environmental control system rather than as standalone hardware. That shift opens opportunities for manufacturers and solution providers that can demonstrate measurable gains in air exchange reduction, thermal retention, and operational consistency.
The second trend is continued product stratification. Buyers will likely demand more clearly differentiated options between premium high-speed systems, cost-efficient standard configurations, and application-tailored variants for cold storage, high-impact zones, or specialized code environments. Suppliers that can manage this stratification efficiently, without sacrificing quality or service reliability, will be better placed to capture both performance-driven and price-sensitive demand.
The third trend is supply-side localization and cost resilience. Input cost volatility and trade dynamics will keep pressure on margins, encouraging more regional production, diversified sourcing, and product designs that reduce material exposure where possible. At the same time, service coverage and uptime assurance will become stronger differentiators, especially in markets where facility downtime carries high operational cost. The main uncertainty lies in the pace and direction of regulatory incentives, material pricing, and adoption speed in newer geographic markets. Organizations that rely on a single product narrative or a narrow pricing strategy may find it harder to adapt if incentive frameworks shift or if input costs reaccelerate.
Strategic Actions for Decision Makers
Manufacturers and product developers should prioritize clear performance tiers, energy-aligned specifications, and service reliability as core commercial levers. Differentiating through measurable efficiency benefits, cycle consistency, and application-specific engineering can help protect margins in an environment where raw material and trade conditions remain variable. It is equally important to treat installation support, parts availability, and maintenance workflows as competitive assets rather than back-office functions.
Investors and corporate strategy teams should pay close attention to companies that combine technology differentiation with resilient supply strategies and credible regional reach. Opportunities are likely to emerge where providers can demonstrate integrated value across hardware, controls, and service, especially in logistics, cold storage, and energy-conscious facility upgrades. Monitoring consolidation activity, localized production moves, and product launches that address both speed and efficiency will help identify where competitive advantage is being built.
PW Consulting Automotive & Machinery Research Center
Procurement leaders and facility operators should evaluate fast electric rolling door purchases with a longer time horizon, weighing total operating cost, energy performance, downtime risk, and compliance alignment alongside initial price. Specification clarity matters: matching door type and control configuration to actual traffic patterns and environmental requirements can reduce operational losses and improve return on investment over the asset life.
For organizations that need deeper segmentation detail, regional granularity, company-level benchmarks, and tailored sourcing or expansion scenarios, a dedicated market research report can provide the structured data and scenario analysis needed to support precise decisions. Access to more detailed breakdowns can help translate these broad trends into actionable plans with clearer assumptions and better risk control.
For detailed analysis of this topic, please visit the official page: Fast Electric Rolling Door Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Nystatin API Market 2026: Why 3.85% CAGR and Geography Redefine Growth Drivers
By pmarketresearch, 2026-09-18
The Nystatin API Market at an Inflection Point: Sizing the Opportunity in a Mature, Quality-Driven Segment
Market Overview: A Steady Trajectory Masked by Structural Headwinds
The Nystatin API market has followed a measured expansion path over the past half-decade, settling into a phase where growth is real but increasingly dependent on margin preservation rather than volume surges. Valued at approximately $345.5 million in 2020, the market climbed to $385.58 million by 2023 and reached $409.68 million in 2024 before settling at $417.33 million in 2025. The forward trajectory points to a consolidated rise, with the market expected to reach $441.53 million in 2026, $490.43 million by 2028, and peak around $543.65 million by 2032. The implied compound annual growth rate of roughly 3.85% across the 2025–2032 horizon reflects a market that is growing but not booming, where incremental gains depend heavily on formulation refinement, regional access expansion, and supply chain reliability.
This baseline growth masks a more nuanced operational picture. The segment is not characterized by explosive demand spikes; rather, it is defined by steady clinical utilization, a mature therapeutic footprint, and a supply base that must continuously adapt to tighter quality expectations and shifting cost structures. For decision-makers, the headline figures should not be read as a signal of untapped volume potential. Instead, they point to a market where value capture will increasingly come from operational efficiency, regional market access, and differentiation in product format rather than from broad-based consumption growth.
Three structural challenges dominate the current landscape and shape how participants allocate capital and attention. First, the market exhibits moderate but meaningful concentration, with a handful of established suppliers controlling a significant share of the addressable supply. This concentration limits pricing flexibility for smaller entrants and raises switching costs for buyers who rely on validated sources with established regulatory footprints. Second, production economics are tightly coupled to fermentation-based synthesis, which introduces exposure to raw material variability, process control complexity, and impurity management. Even when demand is predictable, margin pressure can emerge quickly if input costs rise or yield consistency falters. Third, regulatory and quality expectations continue to intensify. Compliance with recognized pharmacopeial standards and contamination-control protocols is no longer a baseline differentiator; it has become a gatekeeper for market access, especially in procurement environments where audit-ready documentation and consistent batch quality dictate supplier selection.
These challenges do not signal stagnation. They signal a market in which the rules of competition are shifting from supply availability toward supply credibility, operational resilience, and formulation relevance. Companies that treat Nystatin API as a commodity input may find themselves squeezed by price comparisons and tender dynamics. Those that approach it as a regulated, process-sensitive specialty ingredient can defend position through certification depth, supply continuity, and application-specific support.
What Is Actually Driving the Market
Technical Process Complexity as a Demand Filter
Nystatin API remains bound to fermentation-derived production methods, and that dependence shapes both who can compete and how they must operate. The production process requires rigorous control of fermentation-derived impurities, with tight adherence to recognized pharmacopeial and quality guidelines. In practical terms, this means that scale alone is not a reliable competitive advantage. A manufacturer with high-volume capacity but inconsistent process control will face greater rejection risk, more frequent quality investigations, and higher cost of compliance than a smaller operator with superior process discipline. This dynamic reinforces a filter in the market: quality maturity is becoming a precondition for sustained commercial relevance, not simply a hygiene factor.
Penicillin Active Pharmaceutical Ingredients Market
The business implication is clear. For producers, the most durable gains are likely to come from refining fermentation yield, tightening impurity control, and building repeatable batch consistency. For buyers, the decision logic increasingly favors sources that can demonstrate documented process control and traceability, especially where finished formulations must meet stringent pharmacopeial performance expectations. In this environment, technical capability translates directly into commercial optionality.
Certification and Regulatory Access as Commercial Currency
Regulatory documentation has evolved from a back-office requirement into a front-line commercial asset. Recent certification activity illustrates how suppliers use compliance milestones to reinforce market standing. In December 2025, VUAB Pharma updated its CEP certificate for Nystatin, a move that reinforces its position in markets where European compliance documentation carries significant procurement weight. Certifications such as CEP, USDMF, FDA-related approvals, and GMP alignment are not just regulatory checkboxes; they reduce friction in sourcing decisions, support cross-border supply, and give buyers a defensible basis for supplier qualification.
This is especially relevant because the Nystatin API supply chain is geographically distributed, with meaningful production presence across multiple regions rather than confined to a single sourcing hub. In such an environment, buyers often weigh not just price but the speed with which a supplier can enter qualified status, support routine procurement without repeated documentary burden, and respond to audit or quality inquiries. Regulatory readiness therefore functions as both a barrier and an enabler: it raises entry difficulty, but it also protects incumbents that have already invested in the necessary compliance infrastructure.
Application Mix and Formulation Relevance
The market’s demand side is shaped by how Nystatin is deployed across therapeutic settings. The most significant application footprint lies in dermatology, followed by gastroenterology, with a smaller remainder distributed across other uses. This split matters because it shapes product format requirements, delivery expectations, and buyer preferences. Topical and oral formulations continue to carry the largest share of market activity, with powder intended for compounding representing a more specialized but important niche. The practical consequence is that demand is not uniform. Buyers in dermatology-oriented procurement may prioritize batch-to-batch consistency, formulation compatibility, and supply stability, while gastroenterology-driven demand may place additional weight on oral dosage requirements and handling characteristics.
Beyond clinical application, the demand picture is also influenced by procurement behavior. In many purchasing environments, repeat procurement is driven less by brand novelty and more by reliability, documentation readiness, and total cost of ownership. As a result, suppliers that can align their product formats with the practical needs of compounding, dispensing, or formulation integration have a stronger chance of becoming preferred partners rather than interchangeable vendors.
Supply Geography and Cost Structure Realignment
Global Nystatin API production reached approximately 128 tons in 2025, with an average market price around $298 per kilogram. These figures provide a useful anchor for understanding the market’s cost geography. The supply base is concentrated in a limited number of manufacturing centers, including Romania, the Czech Republic, China, and India, while procurement patterns are more dispersed. This uneven distribution creates both opportunity and friction. On one hand, multiple sourcing geographies can support competition and resilience. On the other, fermentation raw material sourcing and process inputs remain vulnerable points that can affect availability and pricing.
For commercial strategy, the key takeaway is that cost leadership cannot be pursued naively. Price competitiveness in this market is inseparable from process stability, certification depth, and logistics reliability. A lower headline price may be offset by qualification delays, quality disputes, or supply interruptions. Conversely, suppliers that can maintain disciplined production economics while offering predictable availability may command stronger buyer preference even in a price-sensitive environment.
Competitive Landscape: Scale, Certification, and Strategic Positioning
Established Producers and Their Distinct Advantages
The competitive field is led by manufacturers that combine long operating history, fermentation expertise, and regulatory documentation with broad market reach. Antibiotice S.A., headquartered in Iași, Romania, stands out as one of the most established Nystatin API producers, with more than 66 years of experience in fermentation-based synthesis. Its commercial footprint extends to more than 75 markets, supported by FDA approval, CEP, and EU GMP certifications. That combination of longevity, certification breadth, and multi-market distribution gives the company a structural advantage in procurement environments where supplier track record and regulatory completeness reduce sourcing risk.
VUAB Pharma a.s., based in Roztoky u Prahy, Czech Republic, is another central player in the global supply picture. As a major producer of Nystatin API for both human and veterinary use, the company has built a profile around multiple certifications, including CEP, USDMF, FDA, and GMP alignment. Its affiliation with the Safichem Group further extends its operational context, alongside additional production in injections and cytostatic intermediates. For buyers, VUAB’s relevance lies in its ability to serve diversified demand while maintaining documentation that supports international procurement pathways.
Centrient Pharmaceuticals, operating from the Netherlands, reinforces the importance of certification-based positioning by supplying Nystatin API with active USDMF and CEP certifications. In a market where buyer confidence often hinges on documentation readiness and cross-border compliance, this type of positioning can be as important as volume capacity. Pfizer Inc. also remains relevant in the broader landscape through its historical and operational involvement, illustrating that large pharmaceutical organizations can maintain a presence even in smaller, mature API categories when alignment with broader supply strategy or legacy portfolio logic exists.
Regional Manufacturing Depth and Emerging Competition
Beyond the established European and multinational names, the supply base includes active manufacturers in China and India. Companies such as Fujian Fukang Pharmaceutical, Guangzhou Tosun Pharmaceutical, Zhejiang Huida Biotech, and Cerata Pharmaceuticals LLP represent the regional manufacturing depth that continues to shape sourcing options. Cerata’s WHO-GMP certification status, for example, signals a pathway to compete in procurement environments that value internationally recognized quality frameworks. Chinese manufacturers listed as Nystatin API suppliers contribute to broader availability and price competition, while also increasing the importance of due diligence on consistency and documentation.
Olon S.p.A. adds an Italian manufacturing dimension as an active supplier with GMP capabilities, showing that even within Europe, competition is not limited to the largest names. Collectively, these players indicate a market that is neither fully consolidated nor highly fragmented in a chaotic sense. Instead, it is a structured competitive field where several manufacturers hold defensible positions, and where differentiation depends on the intersection of quality assurance, supply continuity, and regional access.
How the Landscape Is Evolving
The current trajectory suggests a market that is consolidating competence rather than merely consolidating share. Certification updates, documentation maturity, and process discipline are becoming more important than the ability to simply offer an API in bulk. New entry is possible, but it is more likely to succeed where a company brings verifiable quality infrastructure, recognized compliance credentials, and a clear route to buyer qualification. In contrast, undifferentiated capacity expansion without credible regulatory or quality positioning is increasingly difficult to monetize in a market where procurement teams weigh audit readiness and supply reliability heavily.
PW Consulting Health Care Research Center
At the same time, M&A dynamics, group affiliations, and portfolio extensions may continue to shape the field. Where manufacturers can combine API supply with formulation relevance, veterinary lines, or related intermediates, they may create broader commercial resilience. For decision-makers, the competitive signal is straightforward: the market rewards manufacturers that can present themselves as low-friction, well-documented, and operationally dependable sources rather than as low-cost commodity providers alone.
The Next Three to Five Years: Trends That Will Shape Value Capture
Trend One: Compliance Depth as a Pricing and Access Lever
Over the next several years, the ability to demonstrate robust compliance documentation is likely to become a stronger commercial lever than in the past. As procurement organizations compare suppliers not only on unit price but also on qualification effort, audit exposure, and supply continuity, manufacturers with stronger certification portfolios and more mature process control will be better positioned to defend margins. The trend does not imply that price becomes irrelevant; it implies that price negotiations occur within a narrower field of qualified, trusted sources. Companies that can present clean documentation, consistent quality performance, and traceable manufacturing practices will have more room to compete on total value rather than on headline cost alone.
For commercial strategy, this trend suggests that investments in documentation rigor, regulatory upkeep, and quality systems can pay dividends in buyer preference and supplier longevity. The opportunity is not just to maintain certifications, but to use them as part of a broader value narrative that reduces friction for procurement teams.
Worldwide Butenafine API Market
Trend Two: Supply Resilience and Procurement Behavior Realignment
Supply chain vulnerabilities linked to fermentation raw material sourcing and geographically concentrated production are likely to remain a central concern. Buyers will continue to evaluate multi-source options, safety stock logic, and supplier responsiveness, especially where recurring demand must be met without interruption. This creates an environment in which suppliers that can provide predictable availability, transparent communication, and contingency readiness may gain preference even if their unit pricing is not the lowest in a tender comparison.
The commercial opportunity here lies in reliability as a differentiator. For manufacturers, this may mean investing in feedstock management, yield consistency, inventory planning, or regional distribution support. For buyers, it means re-evaluating sourcing strategies so that resilience is priced into supplier selection rather than treated as an afterthought. In practice, the market may increasingly reward a “ dependable supplier premium,” where dependable means more than delivery timeliness and includes documentation, quality stability, and responsiveness under stress.
Trend Three: Formulation Alignment and Application-Specific Differentiation
Because dermatological and gastrointestinal applications dominate usage, the most relevant commercial opportunities will continue to cluster around formulation alignment and practical usability. Topical and oral products represent the largest share of activity, while compounding-oriented powder remains a narrower but meaningful niche. Suppliers that understand how their API behaves in downstream formulation contexts, and that can support customers with relevant documentation, handling guidance, and format consistency, may strengthen their commercial position beyond what volume competition alone allows.
This trend opens the door to more application-aware engagement. Rather than selling Nystatin API purely as an ingredient, successful players may increasingly frame their offering around formulation compatibility, batch consistency, and customer-specific supply needs. That shift does not require dramatic product innovation; it requires a sharper understanding of how purchasing and formulation teams evaluate risk and usability in day-to-day operations.
Strategic Implications for Different Decision-Makers
For manufacturers and suppliers, the most important move is to treat quality and documentation as core competitive assets rather than administrative overhead. Reducing process variability, maintaining certification currency, and building a credible narrative around supply reliability can improve both buyer confidence and margin resilience. Where capacity expansion is considered, it should be tied to demonstrable quality capability and clear sourcing differentiation, not solely to cost leadership.
For investors and strategic backers, the market offers a relatively stable but selective opportunity. Growth is present, but value creation depends on competitive position, compliance maturity, and supply continuity rather than on broad category expansion. Due diligence should focus on process control, certification status, raw material exposure, and the supplier’s ability to serve procurement needs across regulated markets. In this segment, durable advantage is more likely to arise from operational credibility than from speculative volume plays.
For procurement and sourcing teams, the practical task is to balance cost with qualification burden and continuity risk. Diversifying among competent suppliers, evaluating total cost of ownership, and not over-relying on the lowest-unit-price option can reduce exposure to quality or availability disruptions. In markets where documentation and process consistency determine how quickly a supplier can be onboarded and retained, procurement strategy should make those factors part of the evaluation framework from the outset.
The broader strategic implication is that the Nystatin API market is not primarily a story of explosive scale. It is a story of maturing competition, where disciplined manufacturing, regulatory readiness, and supply dependability determine who retains commercial leverage over time. The market rewards participants who can reduce friction for buyers while preserving operational control over quality and availability.
For organizations seeking a more granular view of regional dynamics, format-level demand shifts, procurement behavior patterns, and supplier-level benchmarking, a fuller commercial intelligence package can help translate these high-level trends into sourcing decisions, investment theses, and operational planning. Detailed segmentation-level data and tailored scenario analysis can sharpen the picture considerably, especially when the objective is to move from general market awareness to concrete purchasing, production, or entry decisions.
For detailed analysis of this topic, please visit the official page: Nystatin API Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Dried Lemon Market 2026: Why 6.8% CAGR and High Growth Signal Industry Shifts
By pmarketresearch, 2026-09-18
Worldwide Dried Lemon Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The worldwide dried lemon market has demonstrated steady expansion over the past five years, transitioning from a niche ingredient category to a broadly integrated component of global food, wellness, and personal care supply chains. Valued at approximately USD 318.4 million in 2025, the market has moved from a 2020 baseline of roughly USD 235 million, reflecting a compound annual growth rate of 6.8 percent through 2032. This trajectory indicates more than incremental demand growth; it signals a structural shift in how manufacturers source, formulate, and commercialize citrus-derived ingredients. Dry lemon formats now serve multiple downstream channels, from culinary and beverage applications to pharmaceutical formulations and cosmetic extracts, creating cross-sector demand that insulates the market from single-industry volatility.
Despite this momentum, the industry faces several interconnected challenges that will shape competitive positioning and margin structures in the near term. The first is raw material supply volatility. Fresh lemon harvests are increasingly exposed to climate variability, labor constraints, and regional weather disruptions, which directly affect the volume and quality of fruit available for dehydration. When fresh fruit availability contracts, processing margins tighten and downstream buyers face pricing uncertainty, forcing manufacturers to balance inventory strategies against cost control.
The second challenge lies in quality consistency and specification standardization across global trade lanes. Dried lemon products vary widely in moisture content, particle size, essential oil retention, and processing method, making it difficult for formulators to maintain consistent sensory profiles or regulatory compliance across regions. Buyers increasingly demand traceable, batch-uniform ingredients, yet the supply base remains fragmented, with differing drying technologies and agricultural practices producing uneven output characteristics.
A third pressure point is the evolving regulatory and trade classification environment. Citrus peel and dried fruit products navigate distinct customs codes, phytosanitary requirements, and labeling standards depending on destination markets. Changes in trade documentation, organic certification expectations, and food safety protocols can introduce friction in cross-border sourcing, particularly for smaller processors that lack the compliance infrastructure of multinational ingredient suppliers. These dynamics do not undermine the market's growth trajectory, but they require operators to invest in supply chain visibility, quality assurance, and regulatory readiness to capture premium segments.
Key Drivers of Market Change
Technology Innovation and Processing Breakthroughs
Advances in dehydration and drying technologies are reshaping the value proposition of dried lemon products. Traditional air-drying methods are increasingly supplemented by controlled-temperature dehydration and freeze-drying processes that better preserve color, aroma compounds, and functional constituents. For ingredient manufacturers, this means a wider range of product forms can be engineered to meet specific application needs, whether the priority is visual appeal in retail-ready packaging or rapid solubility in beverage mixes and pharmaceutical excipients. Improved moisture control and particle-size consistency also reduce waste during downstream processing, allowing food and beverage manufacturers to standardize formulations with greater confidence.
PW Consulting
Parallel developments in extraction and encapsulation are expanding how dried lemon derivatives are used. Essential oil recovery, natural flavor isolation, and stabilized citrus extracts enable companies to deliver lemon functionality in formats that withstand shelf-life requirements and processing conditions. These capabilities are particularly relevant for nutraceutical and cosmetic formulators seeking clean-label inputs that can replace synthetic alternatives without compromising performance.
Policy and Regulatory Environment
Trade classification and regulatory frameworks are becoming more precise, influencing how dried lemon products move across borders. Standardized customs coding for citrus peel and dried citrus fruit has clarified import pathways, reducing ambiguity in documentation and easing compliance for bulk shippers. At the same time, destination markets continue to refine food safety, organic certification, and labeling expectations, which raises the bar for suppliers seeking access to premium European and North American channels.
This regulatory tightening is a double-edged force. On one hand, it increases the operational burden for smaller exporters that must invest in traceability systems and certification upkeep. On the other hand, it rewards processors that can demonstrate consistent quality, transparent sourcing, and verified agricultural practices. In effect, the regulatory landscape is accelerating a shift from commodity-style trading toward specification-driven supply relationships, where documented process controls and origin verification become competitive differentiators.
Demand-Side Shifts in Consumer and Corporate Behavior
Consumer preferences are steering demand toward natural, recognizable ingredients across food, beverage, and personal care categories. Lemon's sensory profile and association with freshness make it a versatile choice for flavor enhancement, functional positioning, and visual appeal. In the food and beverage sector, dehydrated lemon forms are increasingly used to deliver consistent flavor without the logistical complexity of fresh fruit, particularly in markets where seasonal availability or transportation constraints limit fresh citrus access.
Beyond flavor, lemon-derived ingredients are gaining traction in wellness-oriented formulations. Nutraceutical developers incorporate dried lemon components into products positioned around digestive support, antioxidant content, and clean-label botanical profiles. In cosmetics and personal care, citrus extracts and dried lemon derivatives serve both functional and sensory roles, aligning with the broader demand for naturally derived ingredients. These demand shifts are not limited to retail consumers; foodservice operators and industrial manufacturers are also seeking ingredient suppliers that can provide reliable batch consistency, flexible packaging formats, and documentation that supports their own labeling claims.
Supply Chain and Cost Structure Dynamics
Cost structures in the dried lemon market are being reshaped by upstream agricultural conditions and energy inputs tied to drying operations. Producer price movements for fresh lemons have shown upward pressure, reflecting tighter harvests in key growing regions and elevated wholesale pricing in major European markets. At the same time, projections for global fresh lemon and lime production indicate a notable decline for the current marketing year, compounding supply constraints for processors that depend on steady fruit inflow.
These pressures are prompting supply chain recalibration. Some processors are extending forward contracting with growers, diversifying sourcing footprints, and adjusting inventory strategies to buffer against seasonal shortfalls. Others are investing in processing efficiency to offset higher raw material and energy costs, including improved drying throughput and better byproduct utilization. For downstream buyers, the implication is that pricing and availability will become more sensitive to harvest cycles and regional supply disruptions, making supplier relationships and contract structures increasingly strategic rather than purely transactional.
Competitive Landscape and Leading Strategies
The dried lemon market remains moderately fragmented, with the top three firms holding a combined share in the mid-teens and the top five approaching less than thirty percent. This structure favors a diverse mix of regional processors, multinational ingredient suppliers, and value-added specialists, each pursuing distinct strategic positions rather than competing solely on volume.
Leading companies have differentiated themselves through vertical integration, application-focused innovation, and sustainability positioning. Citrus processors with orchard control or long-term grower relationships, such as large Argentinean lemon operators, are able to secure raw material continuity and manage quality from harvest through dehydration. Their ability to produce dehydrated peel, essential oils, juices, and pulp cells from owned or tightly managed orchards gives them an advantage in consistency and supply resilience, particularly when fresh fruit markets tighten.
Dry Fruit Market
European and North American ingredient suppliers have built their strategies around formulation support and application versatility. Specialist dehydration providers and freeze-drying operations focus on delivering dried slices, powders, and fruit ingredients tailored to foodservice, snack, and industrial use cases, emphasizing particle uniformity, moisture control, and packaging formats that suit downstream processing. Multinational ingredient companies contribute a different set of capabilities, including natural flavor solutions, dried lemon derivatives, and technical service support that helps food and beverage manufacturers integrate citrus inputs into complex formulations. Cooperative and grower-marketer models extend fresh citrus operations into value-added dried supply chains, leveraging brand recognition and existing orchard infrastructure to serve both retail and industrial channels.
Dried Fruit Market
Strategic differentiation is increasingly tied to sustainability and traceability. Several processors have emphasized renewable processing facilities, byproduct utilization, and sustainable sourcing models, aligning with buyer expectations in European and North American markets where procurement teams evaluate environmental credentials alongside cost and quality. This is visible in ongoing distribution of dehydrated citrus by-products from sustainable processing facilities, as well as in forward-looking supply guidance from fresh lemon producers that supports downstream dried processing volumes.
The market structure is likely to evolve through selective consolidation and continued specialization rather than full concentration. Larger ingredient groups may pursue acquisitions to broaden their dried citrus portfolios and strengthen technical service capabilities, while regional processors may deepen relationships with specific applications or geographic channels. New entrants are most likely to succeed by targeting underserved product forms, such as organic-certified dried lemon inputs or customized powder specifications for nutraceutical and cosmetic use, where technical differentiation and compliance readiness matter more than sheer scale.
Future Trends and Opportunity Outlook
Over the next three to five years, one of the clearest trends will be the continued expansion of dried lemon into functional and clean-label formulations. As food, beverage, and personal care companies seek natural alternatives to synthetic flavorings and additives, dried lemon inputs will see broader adoption in products where ingredient transparency and recognizable sourcing are part of the value proposition. This trend favors suppliers that can provide documented origin, consistent specifications, and application support, because formulators will prioritize inputs that simplify compliance and labeling while maintaining performance.
A second trend is the growing importance of supply resilience and contractual structure. With fresh lemon production facing cyclical pressure and wholesale prices elevated in key regions, buyers and processors alike will place greater emphasis on forward contracting, diversified sourcing, and inventory planning. This creates opportunities for processors with strong grower relationships, multi-origin supply footprints, or efficient processing operations that can absorb cost variability better than less integrated competitors. It also encourages closer collaboration between suppliers and downstream customers, where sharing demand forecasts and coordinating harvest timing can smooth availability across seasons.
A third trend is the broadening of premiumization within dried lemon categories. Organic-certified products, specialty dried forms, and ingredients optimized for specific sensory or functional outcomes are likely to command higher margins and deeper buyer engagement. As European and North American procurement teams become more accustomed to evaluating sustainability, traceability, and processing standards, premium segments may grow faster than commoditized bulk channels. At the same time, potential risks remain: weather-driven harvest variability, energy cost exposure in drying operations, and regulatory shifts in trade classification or certification requirements could all disrupt short-term pricing and availability. Companies that treat these risks as strategic variables, rather than background noise, will be better positioned to capture the upside.
Actionable Guidance for Decision Makers
For manufacturers and ingredient suppliers, the priority is to strengthen supply continuity and specification reliability. Investing in drying efficiency, quality assurance protocols, and traceability systems will help protect margins and meet the expectations of buyers who require batch consistency and documentation for labeling claims. Where possible, diversifying sourcing and securing forward fruit commitments can reduce exposure to harvest shocks and wholesale price swings. For companies with technical service capabilities, expanding application support for nutraceutical, cosmetic, and foodservice use cases can open higher-value channels beyond bulk commodity sales.
For investors and strategic planners, the market warrants attention to value-added segments and sustainability-oriented operators. The moderate concentration of the market leaves room for targeted consolidation and for specialists that can differentiate through product form, certification, or technical integration. Monitoring harvest forecasts, producer price trends, and regulatory changes will be essential for anticipating shifts in input costs and sourcing feasibility. Capital allocation should favor businesses that demonstrate both supply resilience and the ability to serve premium, specification-driven demand rather than those reliant on undifferentiated bulk volume.
For procurement teams and sourcing managers, the most effective move is to treat dried lemon suppliers as strategic partners rather than transactional vendors. Embedding quality requirements, traceability expectations, and sustainability criteria into sourcing decisions will reduce downstream formulation risk and support cleaner labeling. Where demand is growing or seasonal volatility is high, developing multi-source strategies and flexible contracting structures can improve availability while limiting cost surprises. For organizations seeking deeper segmentation data, regional sourcing intelligence, and tailored recommendations aligned with specific product portfolios, a comprehensive market report can provide the detailed structure needed to translate these trends into concrete sourcing and investment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Dried Lemon Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Liquid Propylene Glycol Market: Why 4.52% CAGR and APAC Growth Reshape 2032 Outlook
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Liquid Propylene Glycol Market
The worldwide liquid propylene glycol market continues to demonstrate resilience and steady expansion, anchored by diverse end-use applications spanning industrial manufacturing, consumer goods, and life sciences. Current valuation places the market at approximately 5,008.83 million USD for the base year 2025, reflecting a compound annual growth rate of 4.52 percent over the historical review window of 2020 through 2025. The trajectory from 2020, when the market stood at 4,015.5 million USD, through successive annual increments to the 2025 benchmark underscores sustained demand absorption across mature and emerging channels. Forward-looking projections indicate a measured but consistent climb toward 6,825.45 million USD by 2032, with intermediate milestones reflecting incremental capacity additions, regional demand shifts, and evolving feedstock economics. Rather than experiencing explosive volatility, the market advances through a combination of steady industrial throughput, targeted pharmaceutical and cosmetic formulation growth, and gradual substitution in specialized cooling and heat transfer applications.
Despite this constructive backdrop, the industry navigates a set of structural challenges that will shape competitive positioning and operational risk profiles over the coming years. First, the supply chain remains highly exposed to upstream propylene oxide dynamics, where regional pricing divergence and logistical bottlenecks can quickly compress margins or trigger short-term allocation constraints for downstream processors. Second, regulatory scrutiny is intensifying across multiple jurisdictions, particularly around food-contact safety, inhalation exposure limits, and environmental release thresholds. These policy shifts introduce compliance complexity and can alter formulation choices in consumer-facing categories. Third, the market is experiencing a gradual bifurcation between conventional petroleum-derived streams and renewable or circular alternatives, forcing producers and formulators to reconcile cost differentials, certification requirements, and end-market acceptance. Navigating these crosscurrents requires a clear understanding of where demand is structurally hardening, where substitution risk is material, and how supply-side disruptions translate into commercial vulnerability.
Propylene Glycol Solvent Market
Key Drivers Shaping Market Evolution
Technological innovation and product differentiation are becoming central to competitive advantage in liquid propylene glycol supply. Producers are expanding the portfolio beyond standard industrial and USP/pharmaceutical grades into certified sustainable variants, including bio-circular and circular feedstocks that carry third-party mass balance certification. This shift is not purely a marketing exercise; it responds to formulation teams seeking to reduce lifecycle emissions and align with corporate sustainability commitments without sacrificing performance characteristics. At the same time, process optimization and integrated oxide-to-glycol operations are improving yield consistency and reducing per-unit energy intensity, which matters in an environment where operating costs are sensitive to regional energy pricing and feedstock volatility. Facilities that have recently expanded capacity or added certification pathways are better positioned to serve customers who require both volume reliability and documented sustainability attributes, creating a two-tier dynamic in which conventional supply competes on cost while certified supply competes on compliance and brand alignment.
Policy and regulatory developments are simultaneously reshaping the demand landscape. In the United States, the EPA finalized Significant New Use Rules under TSCA targeting certain chemical substances, introducing restrictions on processing and use of specific propylene glycol-related compounds to limit inhalation exposure and cap surface water releases exceeding 14 ppb. These measures do not eliminate the material from mainstream applications, but they raise the compliance bar for manufacturers, formulators, and downstream users who must document handling practices, update safety data sheets, and adapt emission controls. In parallel, regional food safety legislation is beginning to influence formulation strategies in consumer goods. California’s Food Safety Act bans propylene glycol in food products effective January 1, 2027, alongside other specified additives, creating a localized but symbolically important shift that may prompt brand owners to re-evaluate ingredient portfolios ahead of the deadline. Regulatory divergence across jurisdictions means that global suppliers and multinational formulators must manage multiple compliance tracks, which favors organizations with robust regulatory affairs capabilities and transparent supply documentation.
Propylene Glycol (PG) Market
On the demand side, behavior shifts in both consumer and industrial segments are reinforcing selective growth. In pharmaceuticals and cosmetics, formulation preferences continue to favor humectant and solvent properties that liquid propylene glycol delivers reliably, particularly where texture, stability, and compatibility with active ingredients are critical. Food and beverage applications remain significant, though regional regulatory actions are encouraging reformulation in certain categories, prompting suppliers to offer alternative grades or partner with customers on ingredient transitions. In industrial fluids, antifreeze and coolants continue to absorb a meaningful share of throughput, supported by maintenance cycles in automotive, HVAC, and process cooling systems. The unsaturated polyester resins segment also contributes steady demand, tied to coatings, composites, and construction-related output. Across these applications, the common thread is not uniform expansion but a reallocation of volume toward segments where performance requirements, regulatory clarity, and sustainability alignment intersect. This reallocating demand rewards suppliers who can match grade specifications to end-use constraints and who can communicate grade differences clearly to procurement and technical teams.
Supply chain and cost structure dynamics remain a defining feature of the market. Propylene oxide, the primary upstream feedstock, exhibited notable regional price dispersion in March 2026, with Northeast Asia prices easing to approximately 1.18 USD per kilogram, North America trading lower at around 1.14 USD per kilogram, and Europe firming to about 1.63 USD per kilogram. This divergence reflects differing supply availability, energy cost environments, and local demand conditions, and it translates directly into uneven production economics for glycol manufacturers. Integrated producers with oxide capacity or secure feedstock arrangements gain a structural cost advantage, while non-integrated operators face greater exposure to spot market fluctuations and freight variability. In addition, operational disruptions can amplify these cost differentials quickly. A fire at LyondellBasell’s Bayport, Texas facility, which has approximately 600,000 tonnes per year of propylene oxide capacity and also produces propylene glycol, led to force majeure declarations on propylene oxide and downstream products, including propylene glycol. The incident illustrates how concentrated capacity nodes can affect regional supply availability and pricing power, especially when downstream customers rely on just-in-time delivery or carry limited inventory buffers.
Competitive Landscape and Leading Strategies
The market is characterized by a relatively concentrated set of global and regional producers, with the top three firms accounting for roughly 43.15 percent of revenue and the top five reaching approximately 59.4 percent. This concentration reflects the capital intensity of oxide-to-glycol operations, the importance of integrated feedstock positioning, and the value of scale in serving multinational customers with consistent quality and documentation. Yet concentration does not imply uniformity; leading companies differentiate through feedstock strategy, grade coverage, geographic footprint, and certification portfolios.
Dow Inc. stands out for its combination of large-scale industrial and USP/EP production and its recent expansion into certified circular and bio-circular offerings. Its facilities, including a major site in Map Ta Phut, Thailand with total capacity reaching 250,000 tons per year, provide volume reliability for personal care, pharmaceutical, food, and industrial fluid applications. The company’s July 2025 expansion of ISCC PLUS certification for its Thailand facility, following an 80,000-ton capacity addition, signals a deliberate move to serve customers who require documented sustainable feedstock pathways alongside conventional grades. In April 2026, Dow announced price increases across its propylene glycol portfolio, including PURAGUARD PG USP/EP, Propylene Glycol Industrial, and Dipropylene Glycol LO+, effective April 3, 2026. This pricing action reflects the interplay of cost pressure, capacity utilization, and the premium that certified or specialty grades can command when demand from formulation-sensitive segments holds firm.
LyondellBasell Industries operates with strong integration into propylene oxide production and supplies USP/EP and industrial grades for antifreeze, coolants, and industrial applications, including kosher-certified options. Its pricing actions in early 2026, including an increase on all grades effective February 16, 2026, and a subsequent force majeure declaration in March 2026 after the Bayport fire, illustrate both the pricing leverage that integrated producers can exercise under normal operations and the vulnerability that concentrated nodes create when disruption strikes. The contrast between these two events within a short window underscores how operational resilience, inventory strategy, and customer communication become critical levers for maintaining market share during volatility.
BASF SE maintains a broad global manufacturing base for propylene glycol, positioning the material as a solvent, extraction liquid, and humectant across food and beverage, cosmetics, and industrial sectors. Its scale and formulation knowledge support customers who need consistent quality across multiple regions, while its oxide-based processing routes provide cost discipline in markets where sustainability certification is less decisive than performance and availability. Archer Daniels Midland Company offers a distinct strategic angle through plant-based and bio-based liquid propylene glycol derived from renewable glycerin sourced from vegetable oils. For buyers seeking petroleum-free alternatives, ADM’s pathway creates a differentiated value proposition, particularly in applications where green branding and renewable content claims carry commercial weight. Repsol S.A. focuses on high-quality pharmaceutical and industrial grades, including dipropylene and tripropylene glycols, with emphasis on cosmetics, personal care, heat transfer, and aircraft de-icing, illustrating how specialized grade portfolios can anchor customer relationships in performance-sensitive niches.
Other major players, including INEOS Group, Shell plc, and Huntsman International LLC, reinforce the market’s breadth. INEOS and Shell leverage oxide derivative positions and integrated feedstock advantages to supply industrial and specialty grades for automotive and chemical intermediate applications, while Huntsman concentrates on performance products for coatings, adhesives, and industrial uses. Together, these companies show that the competitive field is not simply about largest volume; it is increasingly about which producer can align feedstock security, grade flexibility, regional proximity, and certification readiness with the specific requirements of each end-use segment.
The competitive landscape is evolving along several axes. Consolidation pressure remains present where scale and integration confer durable advantages, but fragmentation persists in regional niches where local supply, rapid response, and customized grade support matter more than global volume leadership. New entrants and existing players alike are exploring renewable feedstock routes and circular mass balance offerings, which could gradually redraw the competitive map if certification acceptance broadens and cost gaps narrow. At the same time, customers are becoming more sophisticated in their sourcing criteria, weighing not only price but also supply continuity, regulatory documentation, and sustainability credentials. This shift favors suppliers that can present a coherent value narrative across technical, commercial, and compliance dimensions rather than competing on price alone.
PW Consulting
Future Trajectory: Trends and Commercial Implications
Over the next three to five years, one clear trend is the continued expansion of certified sustainable and bio-based propylene glycol offerings alongside conventional streams. As formulation teams face internal and external pressure to reduce carbon intensity and respond to consumer expectations, demand for ISCC PLUS-certified and plant-based grades is likely to grow in personal care, cosmetics, and select food-adjacent applications where reformulation windows are manageable. The commercial opportunity lies in pairing sustainable grades with reliable volume and clear documentation, because buyers will increasingly compare not just chemical purity but also the credibility and traceability of the feedstock pathway. Suppliers that can standardize certification processes across sites and communicate grade equivalence without ambiguity will capture a larger share of this premium segment.
A second trend will be regionalization of supply strategy in response to feedstock price dispersion, logistics risk, and regulatory divergence. The March 2026 price pattern, with Europe firm and Asia and North America easing, combined with the Bayport disruption, suggests that buyers and producers alike will place greater weight on regional availability, diversified sourcing, and contingency planning. For commercial players, this opens opportunities to build or strengthen regional supply positions, offer dual-sourcing arrangements, and provide inventory buffering services to customers who want to reduce exposure to single-node failures. It also raises the importance of transparent communications during disruptions, since market share can shift quickly when customers lose confidence in delivery predictability.
A third trend is the gradual influence of food safety and environmental regulation on application mix. The California Food Safety Act’s ban on propylene glycol in food products from January 1, 2027, alongside EPA use restrictions designed to limit inhalation exposure and surface water releases, indicates that the regulatory environment will continue to differentiate between application categories. This does not threaten the industrial core of the market, but it may accelerate reformulation in consumer-facing food and beverage uses and increase demand for compliant alternatives or adapted formulations. The associated opportunity is for suppliers and service providers who can help customers navigate ingredient transitions, identify functionally equivalent grades, and maintain performance while meeting new compliance thresholds. The risk lies in underestimating the pace of reformulation in sensitive categories and overcommitting to volume assumptions that assume static regulatory conditions.
Strategic Considerations for Decision-Makers
For manufacturers and producers, the priority is to align feedstock strategy with the dual reality of cost volatility and sustainability demand. Integrated oxide access, flexible grade production, and credible certification pathways provide a stronger footing than volume alone. Operators should also stress-test supply continuity plans against concentrated-node disruption scenarios, because the difference between retaining customers and losing share during an event often comes down to preparedness and communication.
For investors, the market offers selective opportunities in companies that combine scale with differentiated feedstock portfolios and strong regulatory documentation capabilities. The growth trajectory is steady rather than explosive, so value creation will likely come from margin management, certification premium capture, and the ability to serve customers who require both reliability and sustainability attributes. Monitoring regional price dispersion, capacity announcements, and regulatory milestones will be essential for timing exposure and assessing durable competitive advantages.
For procurement and formulation teams, the most practical step is to diversify grade sourcing and clarify specification requirements early, especially where food-safety and environmental regulations are shifting. Building supplier relationships that include transparent documentation, contingency logistics, and grade equivalence support can reduce the operational and compliance burden when regulations or supply conditions change. In this environment, access to detailed segmentation data, regional pricing intelligence, and scenario analysis can sharpen sourcing decisions and reduce the risk of overreliance on single suppliers or single grades. Detailed market intelligence that maps segmentation splits, regional dynamics, and company-specific developments provides the foundation for more confident planning and more resilient commercial positioning.
For detailed analysis of this topic, please visit the official page: Worldwide Liquid Propylene Glycol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Pellicle Market 2026: Asia Pacific’s 11.5% CAGR and 72.5% CR3 Concentration
By pmarketresearch, 2026-09-18
Navigating the Next Wave: Strategic Trends and Commercial Opportunities in the Global Pellicle Market
Market Overview and Core Challenges
The global pellicle market has entered a phase of accelerated expansion, driven by the relentless scaling of semiconductor manufacturing and the proliferation of advanced lithography techniques. In 2025, worldwide revenue for pellicle products reached approximately USD 1.78 billion. This figure represents a meaningful acceleration compared with earlier years, as the segment moved beyond a flat trajectory observed during 2022-2023 into renewed growth. Projections indicate that the market will surpass USD 3.8 billion by 2032, implying a compound annual growth rate of roughly 11.5 percent across the forecast horizon. Such momentum underscores a structural shift rather than a cyclical upturn, rooted in the transition to sub-3nm process nodes and the widespread adoption of extreme ultraviolet lithography for critical patterning layers.
Despite this favorable backdrop, the industry faces several defining challenges. First, the pellicle landscape is highly concentrated, with a small group of specialized suppliers accounting for the vast majority of global revenue. This concentration creates dependency risks for downstream manufacturers, limits pricing flexibility, and raises barriers to entry for new competitors. Second, the transition from conventional photolithography pellicles to EUV-compatible variants demands entirely different material science capabilities. Membranes must operate at thicknesses measured in tens of nanometers, maintain transmittance above ninety percent at a wavelength of 13.5 nanometers, and withstand intense radiation environments without compromising particle protection. Third, qualification cycles are lengthy and stringent. Equipment vendors enforce rigorous certification protocols, meaning that any shift in scanner architecture, power level, or operating protocol requires revalidation that can delay product ramps by months or even years. Finally, the rapid emergence of high-power EUV systems, including those supporting high numerical aperture configurations, places unprecedented thermal and mechanical stress on pellicle membranes. Suppliers must simultaneously improve durability, throughput, and yield reliability while managing raw material costs and scaling production capacity.
Black Pellets Market
These dynamics converge to create a market where technical readiness, supply chain execution, and strategic positioning determine competitive advantage. Companies that can align material innovation with manufacturing scale, while navigating qualification and customer integration cycles, are best positioned to capture the value being generated by next-generation lithography.
Key Drivers of Market Evolution
Several interconnected forces are reshaping demand, supply, and competitive strategy across the pellicle ecosystem.
Technological Innovation and Material Breakthroughs
The central driver remains the push toward higher energy, higher resolution lithography. Traditional polysilicon membranes are being supplemented or replaced by carbon nanotube and other advanced membrane architectures that deliver superior transmittance and thermal resilience. Carbon nanotube-based solutions, for instance, demonstrate single-pass EUV transmission approaching 97 percent and thermal stability extending to 1500 degrees Celsius in vacuum environments. These properties are critical for high-power scanners operating above 500 watts, where pellicle durability directly influences tool uptime and pattern fidelity. In practical terms, such membranes can support productivity gains in the range of 8 to 15 percent by reducing contamination risk and enabling longer operational intervals between replacements. As memory makers and logic suppliers adopt higher-NA and higher-output EUV tools, demand for pellicles that tolerate elevated thermal loads while preserving optical performance will intensify.
Policy, Standards, and Qualification Frameworks
The regulatory and standardization environment exerts a decisive influence on market speed and supplier viability. Equipment manufacturers require third-party certification for scanner safety and performance before alternative pellicle technologies can be deployed in EUV systems. This requirement ensures interoperability and risk mitigation but also extends development timelines and concentrates influence among a few qualified suppliers. The interplay between proprietary equipment roadmaps and industry certification expectations creates a moat around established material platforms while incentivizing suppliers to invest early in alignment with tool vendor specifications. Policy signals related to semiconductor sovereignty, export controls, and domestic manufacturing incentives further shape regional demand patterns and encourage localized supply chain development, particularly in jurisdictions seeking to reduce dependence on imported advanced materials.
Worldwide Meat Membrane Skinner Market
Demand-Side Shifts Across End-Use Applications
Demand is being pulled by multiple application streams. Advanced logic and foundry operations dominate volume, reflecting the need for pellicle protection on multi-patterning and single-exposure EUV layers as node scaling continues. Memory device manufacturers represent a substantial and growing segment, particularly as advanced DRAM and NAND architectures adopt EUV for critical masking steps that improve yield and reduce process complexity. Flat panel display manufacturing also contributes meaningful demand, though at different performance and cost thresholds than leading-edge semiconductors. Across these applications, the common thread is increased layer counts, tighter defect budgets, and higher sensitivity to particle contamination, all of which elevate the strategic value of reliable pellicle solutions.
Supply Chain and Cost Structure Dynamics
On the supply side, scaling production capacity while preserving membrane quality is a central tension. Facilities must be designed for highly controlled environments, specialized reactor systems, and post-processing steps that maintain nanoscale uniformity. Recent capacity expansions and licensing arrangements illustrate how suppliers are building out the manufacturing infrastructure required to meet accelerating demand. At the same time, cost structures are influenced by the availability of specialized precursor materials, the economics of reactor utilization, and the need to amortize qualification investments across customer programs. Suppliers that secure early reactor deployment, lock in customer site acceptance milestones, and achieve steady-state production rates are better able to manage unit economics and compete on both performance and reliability.
Competitive Landscape and Leading Strategies
The market remains dominated by a handful of firms with deep expertise in advanced materials, silicon processing, and lithography-adjacent technologies. This concentration shapes both opportunity and risk.
Differentiated Positioning Among Leaders
Mitsui Chemicals has established a prominent position in the EUV pellicle space, initially commercializing polysilicon-based solutions under licensing arrangements and subsequently investing in carbon nanotube variants for high-power and high-NA systems. Its strategy emphasizes scale-up through dedicated production facilities targeting annual output capacity in the range of thousands of sheets, with supply ramp timelines aligned to next-generation tool adoption. The company’s focus extends beyond logic applications toward memory segments, signaling a diversification of end-use exposure.
Shin-Etsu Chemical leverages its foundational strengths in silicon wafers and photomask substrates to develop advanced LSI and EUV-oriented membranes. Its approach centers on improving yield and process stability through material quality and integration know-how, positioning the company as a reliable contributor to the broader lithography supply chain.
Canatu has carved out a distinctive role by specializing in carbon nanotube membranes engineered for high transmittance and extreme thermal stability. Its product capabilities support productivity improvements in high-power scanners, and the firm has pursued a partner-centric commercial model that includes licensing its reactor technology for mass production. This route enables scale without requiring the licensee to replicate the full technology stack, accelerating time-to-market for advanced membrane production.
FINE SEMITECH represents a regional manufacturing play, focusing on advanced pellicle production for Asian foundries and next-generation EUV tools. Its adoption of licensed reactor technology underscores a pragmatic path to capacity build-out while aligning with the geographic concentration of leading-edge logic and memory production.
A broader set of participants, including AGC, S&S Tech, Toppan Photomasks, Entegris, SKC, and ASML itself, contributes through material inputs, coating technologies, mask and handling solutions, and equipment qualification. Their roles illustrate how the pellicle value chain is interconnected with substrate supply, protective handling systems, and scanner integration. ASML’s position as the primary EUV system provider grants it outsized influence over qualification pathways and compatible membrane specifications.
Strategic Themes and Market Evolution
Several strategic patterns emerge from the current landscape. First, technology roadmaps are moving from polysilicon toward carbon nanotube and silicon-based membranes designed for higher thermal loads and stricter defect budgets. Second, commercialization increasingly relies on licensing and joint readiness milestones, with reactor shipments, site acceptance test approvals, and production line commissioning serving as de facto gate checks for scale. Third, geographic demand remains concentrated, and suppliers are expanding capacity in proximity to major fabrication hubs to reduce lead times and support customer co-development. Fourth, the qualification barrier acts as both a shield for incumbents and a filter for new entrants, meaning that sustained investment in certification alignment and tool-vendor relationships is essential.
The evolution of the market is likely to feature incremental consolidation among specialized material suppliers, while application-specific differentiation grows. As high-power and high-NA systems scale, suppliers that can demonstrate durable transmission performance, reproducible manufacturing yield, and rapid qualification turnaround will capture disproportionate share. At the same time, new entrants will need to solve not only material performance but also the operational realities of reactor utilization, post-processing consistency, and customer integration.
Outlook for the Next Three to Five Years
Looking ahead, three trends are poised to define the market trajectory.
Higher-NA and higher-power adoption will accelerate pellicle performance requirements. As more scanners operate at elevated power levels and tighter focus conditions, pellicle membranes must sustain optical performance and mechanical integrity over extended cycles. This will favor materials with proven thermal stability and consistent transmittance, and it will push qualification programs to prioritize long-duration reliability data.
Manufacturing scale and licensing-driven commercialization will expand capacity. The market is moving from pilot-scale production toward steady-state manufacturing. Reactor deployment, site acceptance milestones, and dedicated facility completions are translating into the ability to serve multiple high-volume customers. Companies that secure early production readiness and align supply timing with tool rollouts will be better positioned to capture demand.
PW Consulting
Application diversification will broaden the opportunity set while complicating prioritization. While advanced logic and foundry operations will remain the largest demand pool, memory and select display applications will contribute growing volume. This diversification offers revenue resilience but also requires suppliers to manage different performance, cost, and qualification expectations across customer segments.
These trends create commercial opportunities for suppliers that can deliver differentiated membrane performance, scale production efficiently, and navigate qualification pathways quickly. At the same time, uncertainty remains. Shifts in scanner power strategies, changes in node migration timing, and the risk of revalidation delays can alter demand timing. Cost volatility in specialized materials and the need for sustained capital investment in reactor infrastructure also introduce execution risk. Participants must therefore balance aggressive capacity planning with disciplined qualification and customer engagement.
Actionable Guidance for Decision-Makers
For manufacturers and technology developers: Prioritize early alignment with equipment qualification roadmaps and invest in membrane formulations that demonstrate thermal stability and consistent transmittance under high-power conditions. Build modular production capacity that can be scaled as site acceptance and certification milestones are met, and structure partnerships to accelerate commercialization without overextending internal R&D resources.
For investors and corporate development teams: Focus on the intersection of material differentiation and manufacturing readiness. The most durable value creation will come from suppliers that combine proven performance in high-power EUV environments with credible paths to steady-state production and diversified application exposure. Evaluate progress against reactor deployment, qualification status, and capacity ramp timing rather than headline announcements alone.
For procurement and strategic sourcing leaders: Treat pellicle selection as a multi-year reliability decision rather than a component-level purchase. Evaluate suppliers on long-term transmittance consistency, thermal durability, qualification support, and ability to sustain yield across high-volume production. Diversify where possible to reduce concentration risk, while ensuring that any alternative solution meets stringent scanner certification requirements.
Timely, granular intelligence on capacity timelines, qualification status, application mix, and regional demand shifts is essential for making these decisions with confidence. Detailed segmentation data, supplier benchmarking, and scenario analysis can sharpen planning and reveal where to allocate resources for maximum impact. Interested readers can explore the full research report for comprehensive breakdowns, company profiles, and tailored recommendations that extend beyond the strategic overview presented here.
For detailed analysis of this topic, please visit the official page: Worldwide Pellicle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com