

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Fast Electric Rolling Door Market: How 7.85% CAGR and Shifts Reshape Strategy Through 2032

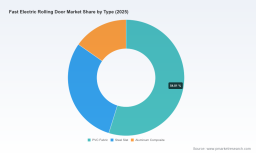
The Fast Electric Rolling Door Market: Strategic Trends and Commercial Opportunities (2025–2032)
Market Landscape and Core Challenges
The fast electric rolling door market has evolved into a critical infrastructure segment for industrial, commercial, and logistics operations worldwide. Valued at approximately 712.6 million in 2025, the market is projected to reach 1.2 billion by 2032, expanding at a compound annual growth rate of 7.85 percent over the forecast period. This trajectory reflects more than steady replacement cycles; it signals a structural shift in how facilities manage energy, throughput, and environmental controls. The base year of 2025 captures a market that has already absorbed several years of accelerated demand, with historical growth from 2020 through 2025 demonstrating consistent upward momentum across multiple end-use sectors and geographies.
Beneath the headline figures, three interconnected challenges are reshaping how manufacturers, distributors, and end-users approach this market. First, raw material volatility has become a persistent margin pressure. Steel and aluminum pricing swings, compounded by trade policy adjustments in recent years, are creating unpredictable input costs and forcing suppliers to reconsider pricing structures, inventory strategies, and product mix. Second, energy efficiency expectations are no longer optional specifications. Federal building energy standards and revised incentive frameworks are pushing facility operators to prioritize doors that reduce air exchange, limit thermal loss, and integrate more tightly with broader building management systems. This shifts procurement discussions from simple durability and cycle speed toward total cost of ownership and compliance alignment.
Third, the market is navigating a quality-versus-speed tension that affects both product design and adoption curves. Operators in high-traffic environments demand faster cycle times, improved impact resistance, and reliable automated refeed functionality, yet these performance enhancements often require more sophisticated control electronics, reinforced components, and tighter manufacturing tolerances. Suppliers that can balance rapid deployment with long-term reliability are gaining traction, while those competing primarily on price are facing margin compression and higher warranty exposure. Together, these challenges define a market that is maturing quickly but still offers meaningful differentiation for players that can align product architecture, cost discipline, and regulatory awareness.
Key Demand Drivers Reshaping the Segment
Technology Innovation and Performance Expectations
Product innovation remains one of the most direct catalysts for market expansion. High-speed door manufacturers are increasingly launching tiered product families that balance premium performance with cost-sensitive configurations. Recent releases have emphasized enhanced customization, modular control options, and variants designed for distinct industrial environments, allowing buyers to match door specifications more precisely to application requirements. At the same time, advances in fabric-based rolling systems, rigid slat designs, and composite constructions are broadening the range of operating conditions these doors can support. The practical effect is not just faster doors, but doors that integrate more cleanly into modern facility workflows, reduce downtime during maintenance, and maintain performance in aggressive environments such as cold storage and high-traffic loading areas.
High Speed Doors Market
Policy and Regulatory Environment
Regulatory and incentive mechanisms are becoming powerful levers in procurement decisions. Federal building energy efficiency standards are pushing commercial and industrial facilities to reduce on-site energy consumption, which directly increases the value of doors that minimize conditioned air loss during frequent openings. At the same time, incentive programs tied to certified efficient exterior doors have improved the financial case for upgrades, particularly for organizations planning phased facility modernization. These dynamics are not simply compliance issues; they are reshaping specification criteria. Facility managers and engineers increasingly evaluate door selections through an energy-performance lens, weighing cycle speed, sealing behavior, and integration potential alongside traditional factors like durability and footprint.
Demand-Side Shifts in Warehousing, Cold Chain, and Manufacturing
End-use demand is being driven by operational intensity rather than incremental replacement alone. Warehouse and logistics facilities continue to prioritize throughput, requiring door systems that support frequent, automated passage while controlling environmental drift. Food processing and cold storage operators face even stricter temperature retention requirements, making fast cycle times and reliable sealing critical to product integrity and energy costs. Automotive and general manufacturing environments add another layer of demand, where impact resistance, safety performance, and integration with material-handling workflows matter as much as speed. As these sectors expand or modernize, the door becomes less of a passive barrier and more of an active component in facility efficiency, which broadens the addressable market and raises the performance baseline for competitive products.
Automatic Door Market
Supply Chain and Cost Structure Dynamics
Cost structure pressures are reshaping supplier strategies across the value chain. Fluctuations in steel pricing, along with periodic trade measures affecting steel and aluminum inputs, have translated into meaningful installation-level price variability depending on material composition. These conditions reward manufacturers that can optimize material usage, offer alternative constructions where appropriate, and maintain flexible production planning. They also encourage greater attention to regional production footprints and supply continuity. Recent expansion activity in select markets, including localized production moves in Southeast Asia, reflects an effort to reduce exposure to logistics delays, currency risk, and input cost uncertainty. For buyers, this environment means that lead times, warranty terms, and service availability are becoming just as important as unit price in evaluating long-term value.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of specialized high-speed door manufacturers, broader rolling-door producers, and regional players with strong compliance or installation capabilities. Market concentration remains moderate, with the top three and top five firms holding meaningful but not dominant shares, indicating room for continued differentiation and selective consolidation. Leading participants generally compete on a combination of speed, durability, automation features, and application-specific engineering rather than on commodity pricing alone. This positions the market as one where product architecture, control technology, and service networks often determine share gains more than volume alone.
Several strategic profiles stand out. Some manufacturers emphasize high-performance fabric and rigid overhead systems designed for industrial, cold storage, and commercial environments, building reputation on large installed bases and repeatable reliability. Others focus on high-speed roll-up and fabric door lines that target logistics and facility applications where throughput and ease of operation are paramount. European manufacturers have often leaned into advanced control technology, spiral and vertically opening high-speed designs, and refined engineering for demanding industrial use. In parallel, U.S.-based producers have expanded product lines that highlight energy efficiency, impact resistance, and automated refeed capabilities for warehouses and loading docks. Traditional steel door manufacturers and service-door specialists remain relevant in applications where security, heavy-duty use, and code compliance carry significant weight. Meanwhile, regional fabricators with hurricane-zone or local code expertise maintain strong positioning in jurisdictions where compliance and installation know-how are decisive buying factors.
Recent company actions illustrate how these strategies are evolving. Tiered product launches are giving buyers more granular choices across premium, eco, and basic configurations, supporting customization without forcing a one-size-fits-all approach. Updates to existing high-performance lines have reinforced the importance of energy efficiency and impact resistance for commercial facilities. Selective geographic expansion, including regional acquisitions to strengthen local production, indicates a growing emphasis on supply resilience and proximity to end markets. New high-performance steel door introductions with improved opening speeds also show that speed remains a competitive battleground even in more traditional product categories.
The broader market evolution appears to be moving along two tracks simultaneously. On one hand, integration is likely to continue as larger players seek to strengthen regional presence, acquire niche capabilities, or broaden application coverage. On the other hand, segmentation will remain important because requirements differ sharply across cold storage, logistics, manufacturing, and specialty code-driven environments. New entrants face a realistic bar: success typically depends on solving a clear operational pain point, such as cycle speed with robust refeed behavior, improved thermal performance, or compliance-ready designs for specific regions. Companies that can pair product performance with reliable service, clear specification support, and cost-stable material strategies are best positioned to convert market growth into durable share.
Forward-Looking Trends for the Next Three to Five Years
Several trends are likely to shape the market through the late 2020s and early 2030s. The first is deeper integration of door performance with building energy strategy. As efficiency expectations become embedded in procurement specifications and incentive structures, fast electric rolling doors will increasingly be evaluated as part of a facility’s overall energy and environmental control system rather than as standalone hardware. That shift opens opportunities for manufacturers and solution providers that can demonstrate measurable gains in air exchange reduction, thermal retention, and operational consistency.
The second trend is continued product stratification. Buyers will likely demand more clearly differentiated options between premium high-speed systems, cost-efficient standard configurations, and application-tailored variants for cold storage, high-impact zones, or specialized code environments. Suppliers that can manage this stratification efficiently, without sacrificing quality or service reliability, will be better placed to capture both performance-driven and price-sensitive demand.
The third trend is supply-side localization and cost resilience. Input cost volatility and trade dynamics will keep pressure on margins, encouraging more regional production, diversified sourcing, and product designs that reduce material exposure where possible. At the same time, service coverage and uptime assurance will become stronger differentiators, especially in markets where facility downtime carries high operational cost. The main uncertainty lies in the pace and direction of regulatory incentives, material pricing, and adoption speed in newer geographic markets. Organizations that rely on a single product narrative or a narrow pricing strategy may find it harder to adapt if incentive frameworks shift or if input costs reaccelerate.
Strategic Actions for Decision Makers
Manufacturers and product developers should prioritize clear performance tiers, energy-aligned specifications, and service reliability as core commercial levers. Differentiating through measurable efficiency benefits, cycle consistency, and application-specific engineering can help protect margins in an environment where raw material and trade conditions remain variable. It is equally important to treat installation support, parts availability, and maintenance workflows as competitive assets rather than back-office functions.
Investors and corporate strategy teams should pay close attention to companies that combine technology differentiation with resilient supply strategies and credible regional reach. Opportunities are likely to emerge where providers can demonstrate integrated value across hardware, controls, and service, especially in logistics, cold storage, and energy-conscious facility upgrades. Monitoring consolidation activity, localized production moves, and product launches that address both speed and efficiency will help identify where competitive advantage is being built.
PW Consulting Automotive & Machinery Research Center
Procurement leaders and facility operators should evaluate fast electric rolling door purchases with a longer time horizon, weighing total operating cost, energy performance, downtime risk, and compliance alignment alongside initial price. Specification clarity matters: matching door type and control configuration to actual traffic patterns and environmental requirements can reduce operational losses and improve return on investment over the asset life.
For organizations that need deeper segmentation detail, regional granularity, company-level benchmarks, and tailored sourcing or expansion scenarios, a dedicated market research report can provide the structured data and scenario analysis needed to support precise decisions. Access to more detailed breakdowns can help translate these broad trends into actionable plans with clearer assumptions and better risk control.
For detailed analysis of this topic, please visit the official page: Fast Electric Rolling Door Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com