

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Liquid Propylene Glycol Market: Why 4.52% CAGR and APAC Growth Reshape 2032 Outlook

Strategic Trends and Commercial Opportunities in the Worldwide Liquid Propylene Glycol Market
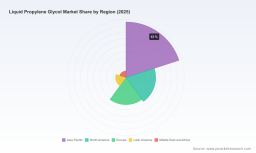
The worldwide liquid propylene glycol market continues to demonstrate resilience and steady expansion, anchored by diverse end-use applications spanning industrial manufacturing, consumer goods, and life sciences. Current valuation places the market at approximately 5,008.83 million USD for the base year 2025, reflecting a compound annual growth rate of 4.52 percent over the historical review window of 2020 through 2025. The trajectory from 2020, when the market stood at 4,015.5 million USD, through successive annual increments to the 2025 benchmark underscores sustained demand absorption across mature and emerging channels. Forward-looking projections indicate a measured but consistent climb toward 6,825.45 million USD by 2032, with intermediate milestones reflecting incremental capacity additions, regional demand shifts, and evolving feedstock economics. Rather than experiencing explosive volatility, the market advances through a combination of steady industrial throughput, targeted pharmaceutical and cosmetic formulation growth, and gradual substitution in specialized cooling and heat transfer applications.
Despite this constructive backdrop, the industry navigates a set of structural challenges that will shape competitive positioning and operational risk profiles over the coming years. First, the supply chain remains highly exposed to upstream propylene oxide dynamics, where regional pricing divergence and logistical bottlenecks can quickly compress margins or trigger short-term allocation constraints for downstream processors. Second, regulatory scrutiny is intensifying across multiple jurisdictions, particularly around food-contact safety, inhalation exposure limits, and environmental release thresholds. These policy shifts introduce compliance complexity and can alter formulation choices in consumer-facing categories. Third, the market is experiencing a gradual bifurcation between conventional petroleum-derived streams and renewable or circular alternatives, forcing producers and formulators to reconcile cost differentials, certification requirements, and end-market acceptance. Navigating these crosscurrents requires a clear understanding of where demand is structurally hardening, where substitution risk is material, and how supply-side disruptions translate into commercial vulnerability.
Propylene Glycol Solvent Market
Key Drivers Shaping Market Evolution
Technological innovation and product differentiation are becoming central to competitive advantage in liquid propylene glycol supply. Producers are expanding the portfolio beyond standard industrial and USP/pharmaceutical grades into certified sustainable variants, including bio-circular and circular feedstocks that carry third-party mass balance certification. This shift is not purely a marketing exercise; it responds to formulation teams seeking to reduce lifecycle emissions and align with corporate sustainability commitments without sacrificing performance characteristics. At the same time, process optimization and integrated oxide-to-glycol operations are improving yield consistency and reducing per-unit energy intensity, which matters in an environment where operating costs are sensitive to regional energy pricing and feedstock volatility. Facilities that have recently expanded capacity or added certification pathways are better positioned to serve customers who require both volume reliability and documented sustainability attributes, creating a two-tier dynamic in which conventional supply competes on cost while certified supply competes on compliance and brand alignment.
Policy and regulatory developments are simultaneously reshaping the demand landscape. In the United States, the EPA finalized Significant New Use Rules under TSCA targeting certain chemical substances, introducing restrictions on processing and use of specific propylene glycol-related compounds to limit inhalation exposure and cap surface water releases exceeding 14 ppb. These measures do not eliminate the material from mainstream applications, but they raise the compliance bar for manufacturers, formulators, and downstream users who must document handling practices, update safety data sheets, and adapt emission controls. In parallel, regional food safety legislation is beginning to influence formulation strategies in consumer goods. California’s Food Safety Act bans propylene glycol in food products effective January 1, 2027, alongside other specified additives, creating a localized but symbolically important shift that may prompt brand owners to re-evaluate ingredient portfolios ahead of the deadline. Regulatory divergence across jurisdictions means that global suppliers and multinational formulators must manage multiple compliance tracks, which favors organizations with robust regulatory affairs capabilities and transparent supply documentation.
Propylene Glycol (PG) Market
On the demand side, behavior shifts in both consumer and industrial segments are reinforcing selective growth. In pharmaceuticals and cosmetics, formulation preferences continue to favor humectant and solvent properties that liquid propylene glycol delivers reliably, particularly where texture, stability, and compatibility with active ingredients are critical. Food and beverage applications remain significant, though regional regulatory actions are encouraging reformulation in certain categories, prompting suppliers to offer alternative grades or partner with customers on ingredient transitions. In industrial fluids, antifreeze and coolants continue to absorb a meaningful share of throughput, supported by maintenance cycles in automotive, HVAC, and process cooling systems. The unsaturated polyester resins segment also contributes steady demand, tied to coatings, composites, and construction-related output. Across these applications, the common thread is not uniform expansion but a reallocation of volume toward segments where performance requirements, regulatory clarity, and sustainability alignment intersect. This reallocating demand rewards suppliers who can match grade specifications to end-use constraints and who can communicate grade differences clearly to procurement and technical teams.
Supply chain and cost structure dynamics remain a defining feature of the market. Propylene oxide, the primary upstream feedstock, exhibited notable regional price dispersion in March 2026, with Northeast Asia prices easing to approximately 1.18 USD per kilogram, North America trading lower at around 1.14 USD per kilogram, and Europe firming to about 1.63 USD per kilogram. This divergence reflects differing supply availability, energy cost environments, and local demand conditions, and it translates directly into uneven production economics for glycol manufacturers. Integrated producers with oxide capacity or secure feedstock arrangements gain a structural cost advantage, while non-integrated operators face greater exposure to spot market fluctuations and freight variability. In addition, operational disruptions can amplify these cost differentials quickly. A fire at LyondellBasell’s Bayport, Texas facility, which has approximately 600,000 tonnes per year of propylene oxide capacity and also produces propylene glycol, led to force majeure declarations on propylene oxide and downstream products, including propylene glycol. The incident illustrates how concentrated capacity nodes can affect regional supply availability and pricing power, especially when downstream customers rely on just-in-time delivery or carry limited inventory buffers.
Competitive Landscape and Leading Strategies
The market is characterized by a relatively concentrated set of global and regional producers, with the top three firms accounting for roughly 43.15 percent of revenue and the top five reaching approximately 59.4 percent. This concentration reflects the capital intensity of oxide-to-glycol operations, the importance of integrated feedstock positioning, and the value of scale in serving multinational customers with consistent quality and documentation. Yet concentration does not imply uniformity; leading companies differentiate through feedstock strategy, grade coverage, geographic footprint, and certification portfolios.
Dow Inc. stands out for its combination of large-scale industrial and USP/EP production and its recent expansion into certified circular and bio-circular offerings. Its facilities, including a major site in Map Ta Phut, Thailand with total capacity reaching 250,000 tons per year, provide volume reliability for personal care, pharmaceutical, food, and industrial fluid applications. The company’s July 2025 expansion of ISCC PLUS certification for its Thailand facility, following an 80,000-ton capacity addition, signals a deliberate move to serve customers who require documented sustainable feedstock pathways alongside conventional grades. In April 2026, Dow announced price increases across its propylene glycol portfolio, including PURAGUARD PG USP/EP, Propylene Glycol Industrial, and Dipropylene Glycol LO+, effective April 3, 2026. This pricing action reflects the interplay of cost pressure, capacity utilization, and the premium that certified or specialty grades can command when demand from formulation-sensitive segments holds firm.
LyondellBasell Industries operates with strong integration into propylene oxide production and supplies USP/EP and industrial grades for antifreeze, coolants, and industrial applications, including kosher-certified options. Its pricing actions in early 2026, including an increase on all grades effective February 16, 2026, and a subsequent force majeure declaration in March 2026 after the Bayport fire, illustrate both the pricing leverage that integrated producers can exercise under normal operations and the vulnerability that concentrated nodes create when disruption strikes. The contrast between these two events within a short window underscores how operational resilience, inventory strategy, and customer communication become critical levers for maintaining market share during volatility.
BASF SE maintains a broad global manufacturing base for propylene glycol, positioning the material as a solvent, extraction liquid, and humectant across food and beverage, cosmetics, and industrial sectors. Its scale and formulation knowledge support customers who need consistent quality across multiple regions, while its oxide-based processing routes provide cost discipline in markets where sustainability certification is less decisive than performance and availability. Archer Daniels Midland Company offers a distinct strategic angle through plant-based and bio-based liquid propylene glycol derived from renewable glycerin sourced from vegetable oils. For buyers seeking petroleum-free alternatives, ADM’s pathway creates a differentiated value proposition, particularly in applications where green branding and renewable content claims carry commercial weight. Repsol S.A. focuses on high-quality pharmaceutical and industrial grades, including dipropylene and tripropylene glycols, with emphasis on cosmetics, personal care, heat transfer, and aircraft de-icing, illustrating how specialized grade portfolios can anchor customer relationships in performance-sensitive niches.
Other major players, including INEOS Group, Shell plc, and Huntsman International LLC, reinforce the market’s breadth. INEOS and Shell leverage oxide derivative positions and integrated feedstock advantages to supply industrial and specialty grades for automotive and chemical intermediate applications, while Huntsman concentrates on performance products for coatings, adhesives, and industrial uses. Together, these companies show that the competitive field is not simply about largest volume; it is increasingly about which producer can align feedstock security, grade flexibility, regional proximity, and certification readiness with the specific requirements of each end-use segment.
The competitive landscape is evolving along several axes. Consolidation pressure remains present where scale and integration confer durable advantages, but fragmentation persists in regional niches where local supply, rapid response, and customized grade support matter more than global volume leadership. New entrants and existing players alike are exploring renewable feedstock routes and circular mass balance offerings, which could gradually redraw the competitive map if certification acceptance broadens and cost gaps narrow. At the same time, customers are becoming more sophisticated in their sourcing criteria, weighing not only price but also supply continuity, regulatory documentation, and sustainability credentials. This shift favors suppliers that can present a coherent value narrative across technical, commercial, and compliance dimensions rather than competing on price alone.
PW Consulting
Future Trajectory: Trends and Commercial Implications
Over the next three to five years, one clear trend is the continued expansion of certified sustainable and bio-based propylene glycol offerings alongside conventional streams. As formulation teams face internal and external pressure to reduce carbon intensity and respond to consumer expectations, demand for ISCC PLUS-certified and plant-based grades is likely to grow in personal care, cosmetics, and select food-adjacent applications where reformulation windows are manageable. The commercial opportunity lies in pairing sustainable grades with reliable volume and clear documentation, because buyers will increasingly compare not just chemical purity but also the credibility and traceability of the feedstock pathway. Suppliers that can standardize certification processes across sites and communicate grade equivalence without ambiguity will capture a larger share of this premium segment.
A second trend will be regionalization of supply strategy in response to feedstock price dispersion, logistics risk, and regulatory divergence. The March 2026 price pattern, with Europe firm and Asia and North America easing, combined with the Bayport disruption, suggests that buyers and producers alike will place greater weight on regional availability, diversified sourcing, and contingency planning. For commercial players, this opens opportunities to build or strengthen regional supply positions, offer dual-sourcing arrangements, and provide inventory buffering services to customers who want to reduce exposure to single-node failures. It also raises the importance of transparent communications during disruptions, since market share can shift quickly when customers lose confidence in delivery predictability.
A third trend is the gradual influence of food safety and environmental regulation on application mix. The California Food Safety Act’s ban on propylene glycol in food products from January 1, 2027, alongside EPA use restrictions designed to limit inhalation exposure and surface water releases, indicates that the regulatory environment will continue to differentiate between application categories. This does not threaten the industrial core of the market, but it may accelerate reformulation in consumer-facing food and beverage uses and increase demand for compliant alternatives or adapted formulations. The associated opportunity is for suppliers and service providers who can help customers navigate ingredient transitions, identify functionally equivalent grades, and maintain performance while meeting new compliance thresholds. The risk lies in underestimating the pace of reformulation in sensitive categories and overcommitting to volume assumptions that assume static regulatory conditions.
Strategic Considerations for Decision-Makers
For manufacturers and producers, the priority is to align feedstock strategy with the dual reality of cost volatility and sustainability demand. Integrated oxide access, flexible grade production, and credible certification pathways provide a stronger footing than volume alone. Operators should also stress-test supply continuity plans against concentrated-node disruption scenarios, because the difference between retaining customers and losing share during an event often comes down to preparedness and communication.
For investors, the market offers selective opportunities in companies that combine scale with differentiated feedstock portfolios and strong regulatory documentation capabilities. The growth trajectory is steady rather than explosive, so value creation will likely come from margin management, certification premium capture, and the ability to serve customers who require both reliability and sustainability attributes. Monitoring regional price dispersion, capacity announcements, and regulatory milestones will be essential for timing exposure and assessing durable competitive advantages.
For procurement and formulation teams, the most practical step is to diversify grade sourcing and clarify specification requirements early, especially where food-safety and environmental regulations are shifting. Building supplier relationships that include transparent documentation, contingency logistics, and grade equivalence support can reduce the operational and compliance burden when regulations or supply conditions change. In this environment, access to detailed segmentation data, regional pricing intelligence, and scenario analysis can sharpen sourcing decisions and reduce the risk of overreliance on single suppliers or single grades. Detailed market intelligence that maps segmentation splits, regional dynamics, and company-specific developments provides the foundation for more confident planning and more resilient commercial positioning.
For detailed analysis of this topic, please visit the official page: Worldwide Liquid Propylene Glycol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com