

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Nystatin API Market 2026: Why 3.85% CAGR and Geography Redefine Growth Drivers

The Nystatin API Market at an Inflection Point: Sizing the Opportunity in a Mature, Quality-Driven Segment
Market Overview: A Steady Trajectory Masked by Structural Headwinds
The Nystatin API market has followed a measured expansion path over the past half-decade, settling into a phase where growth is real but increasingly dependent on margin preservation rather than volume surges. Valued at approximately $345.5 million in 2020, the market climbed to $385.58 million by 2023 and reached $409.68 million in 2024 before settling at $417.33 million in 2025. The forward trajectory points to a consolidated rise, with the market expected to reach $441.53 million in 2026, $490.43 million by 2028, and peak around $543.65 million by 2032. The implied compound annual growth rate of roughly 3.85% across the 2025–2032 horizon reflects a market that is growing but not booming, where incremental gains depend heavily on formulation refinement, regional access expansion, and supply chain reliability.
This baseline growth masks a more nuanced operational picture. The segment is not characterized by explosive demand spikes; rather, it is defined by steady clinical utilization, a mature therapeutic footprint, and a supply base that must continuously adapt to tighter quality expectations and shifting cost structures. For decision-makers, the headline figures should not be read as a signal of untapped volume potential. Instead, they point to a market where value capture will increasingly come from operational efficiency, regional market access, and differentiation in product format rather than from broad-based consumption growth.
Three structural challenges dominate the current landscape and shape how participants allocate capital and attention. First, the market exhibits moderate but meaningful concentration, with a handful of established suppliers controlling a significant share of the addressable supply. This concentration limits pricing flexibility for smaller entrants and raises switching costs for buyers who rely on validated sources with established regulatory footprints. Second, production economics are tightly coupled to fermentation-based synthesis, which introduces exposure to raw material variability, process control complexity, and impurity management. Even when demand is predictable, margin pressure can emerge quickly if input costs rise or yield consistency falters. Third, regulatory and quality expectations continue to intensify. Compliance with recognized pharmacopeial standards and contamination-control protocols is no longer a baseline differentiator; it has become a gatekeeper for market access, especially in procurement environments where audit-ready documentation and consistent batch quality dictate supplier selection.
These challenges do not signal stagnation. They signal a market in which the rules of competition are shifting from supply availability toward supply credibility, operational resilience, and formulation relevance. Companies that treat Nystatin API as a commodity input may find themselves squeezed by price comparisons and tender dynamics. Those that approach it as a regulated, process-sensitive specialty ingredient can defend position through certification depth, supply continuity, and application-specific support.
What Is Actually Driving the Market
Technical Process Complexity as a Demand Filter
Nystatin API remains bound to fermentation-derived production methods, and that dependence shapes both who can compete and how they must operate. The production process requires rigorous control of fermentation-derived impurities, with tight adherence to recognized pharmacopeial and quality guidelines. In practical terms, this means that scale alone is not a reliable competitive advantage. A manufacturer with high-volume capacity but inconsistent process control will face greater rejection risk, more frequent quality investigations, and higher cost of compliance than a smaller operator with superior process discipline. This dynamic reinforces a filter in the market: quality maturity is becoming a precondition for sustained commercial relevance, not simply a hygiene factor.
Penicillin Active Pharmaceutical Ingredients Market
The business implication is clear. For producers, the most durable gains are likely to come from refining fermentation yield, tightening impurity control, and building repeatable batch consistency. For buyers, the decision logic increasingly favors sources that can demonstrate documented process control and traceability, especially where finished formulations must meet stringent pharmacopeial performance expectations. In this environment, technical capability translates directly into commercial optionality.
Certification and Regulatory Access as Commercial Currency
Regulatory documentation has evolved from a back-office requirement into a front-line commercial asset. Recent certification activity illustrates how suppliers use compliance milestones to reinforce market standing. In December 2025, VUAB Pharma updated its CEP certificate for Nystatin, a move that reinforces its position in markets where European compliance documentation carries significant procurement weight. Certifications such as CEP, USDMF, FDA-related approvals, and GMP alignment are not just regulatory checkboxes; they reduce friction in sourcing decisions, support cross-border supply, and give buyers a defensible basis for supplier qualification.
This is especially relevant because the Nystatin API supply chain is geographically distributed, with meaningful production presence across multiple regions rather than confined to a single sourcing hub. In such an environment, buyers often weigh not just price but the speed with which a supplier can enter qualified status, support routine procurement without repeated documentary burden, and respond to audit or quality inquiries. Regulatory readiness therefore functions as both a barrier and an enabler: it raises entry difficulty, but it also protects incumbents that have already invested in the necessary compliance infrastructure.
Application Mix and Formulation Relevance
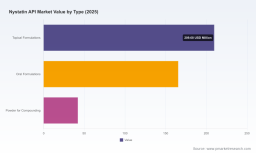
The market’s demand side is shaped by how Nystatin is deployed across therapeutic settings. The most significant application footprint lies in dermatology, followed by gastroenterology, with a smaller remainder distributed across other uses. This split matters because it shapes product format requirements, delivery expectations, and buyer preferences. Topical and oral formulations continue to carry the largest share of market activity, with powder intended for compounding representing a more specialized but important niche. The practical consequence is that demand is not uniform. Buyers in dermatology-oriented procurement may prioritize batch-to-batch consistency, formulation compatibility, and supply stability, while gastroenterology-driven demand may place additional weight on oral dosage requirements and handling characteristics.
Beyond clinical application, the demand picture is also influenced by procurement behavior. In many purchasing environments, repeat procurement is driven less by brand novelty and more by reliability, documentation readiness, and total cost of ownership. As a result, suppliers that can align their product formats with the practical needs of compounding, dispensing, or formulation integration have a stronger chance of becoming preferred partners rather than interchangeable vendors.
Supply Geography and Cost Structure Realignment
Global Nystatin API production reached approximately 128 tons in 2025, with an average market price around $298 per kilogram. These figures provide a useful anchor for understanding the market’s cost geography. The supply base is concentrated in a limited number of manufacturing centers, including Romania, the Czech Republic, China, and India, while procurement patterns are more dispersed. This uneven distribution creates both opportunity and friction. On one hand, multiple sourcing geographies can support competition and resilience. On the other, fermentation raw material sourcing and process inputs remain vulnerable points that can affect availability and pricing.
For commercial strategy, the key takeaway is that cost leadership cannot be pursued naively. Price competitiveness in this market is inseparable from process stability, certification depth, and logistics reliability. A lower headline price may be offset by qualification delays, quality disputes, or supply interruptions. Conversely, suppliers that can maintain disciplined production economics while offering predictable availability may command stronger buyer preference even in a price-sensitive environment.
Competitive Landscape: Scale, Certification, and Strategic Positioning
Established Producers and Their Distinct Advantages
The competitive field is led by manufacturers that combine long operating history, fermentation expertise, and regulatory documentation with broad market reach. Antibiotice S.A., headquartered in Iași, Romania, stands out as one of the most established Nystatin API producers, with more than 66 years of experience in fermentation-based synthesis. Its commercial footprint extends to more than 75 markets, supported by FDA approval, CEP, and EU GMP certifications. That combination of longevity, certification breadth, and multi-market distribution gives the company a structural advantage in procurement environments where supplier track record and regulatory completeness reduce sourcing risk.
VUAB Pharma a.s., based in Roztoky u Prahy, Czech Republic, is another central player in the global supply picture. As a major producer of Nystatin API for both human and veterinary use, the company has built a profile around multiple certifications, including CEP, USDMF, FDA, and GMP alignment. Its affiliation with the Safichem Group further extends its operational context, alongside additional production in injections and cytostatic intermediates. For buyers, VUAB’s relevance lies in its ability to serve diversified demand while maintaining documentation that supports international procurement pathways.
Centrient Pharmaceuticals, operating from the Netherlands, reinforces the importance of certification-based positioning by supplying Nystatin API with active USDMF and CEP certifications. In a market where buyer confidence often hinges on documentation readiness and cross-border compliance, this type of positioning can be as important as volume capacity. Pfizer Inc. also remains relevant in the broader landscape through its historical and operational involvement, illustrating that large pharmaceutical organizations can maintain a presence even in smaller, mature API categories when alignment with broader supply strategy or legacy portfolio logic exists.
Regional Manufacturing Depth and Emerging Competition
Beyond the established European and multinational names, the supply base includes active manufacturers in China and India. Companies such as Fujian Fukang Pharmaceutical, Guangzhou Tosun Pharmaceutical, Zhejiang Huida Biotech, and Cerata Pharmaceuticals LLP represent the regional manufacturing depth that continues to shape sourcing options. Cerata’s WHO-GMP certification status, for example, signals a pathway to compete in procurement environments that value internationally recognized quality frameworks. Chinese manufacturers listed as Nystatin API suppliers contribute to broader availability and price competition, while also increasing the importance of due diligence on consistency and documentation.
Olon S.p.A. adds an Italian manufacturing dimension as an active supplier with GMP capabilities, showing that even within Europe, competition is not limited to the largest names. Collectively, these players indicate a market that is neither fully consolidated nor highly fragmented in a chaotic sense. Instead, it is a structured competitive field where several manufacturers hold defensible positions, and where differentiation depends on the intersection of quality assurance, supply continuity, and regional access.
How the Landscape Is Evolving
The current trajectory suggests a market that is consolidating competence rather than merely consolidating share. Certification updates, documentation maturity, and process discipline are becoming more important than the ability to simply offer an API in bulk. New entry is possible, but it is more likely to succeed where a company brings verifiable quality infrastructure, recognized compliance credentials, and a clear route to buyer qualification. In contrast, undifferentiated capacity expansion without credible regulatory or quality positioning is increasingly difficult to monetize in a market where procurement teams weigh audit readiness and supply reliability heavily.
PW Consulting Health Care Research Center
At the same time, M&A dynamics, group affiliations, and portfolio extensions may continue to shape the field. Where manufacturers can combine API supply with formulation relevance, veterinary lines, or related intermediates, they may create broader commercial resilience. For decision-makers, the competitive signal is straightforward: the market rewards manufacturers that can present themselves as low-friction, well-documented, and operationally dependable sources rather than as low-cost commodity providers alone.
The Next Three to Five Years: Trends That Will Shape Value Capture
Trend One: Compliance Depth as a Pricing and Access Lever
Over the next several years, the ability to demonstrate robust compliance documentation is likely to become a stronger commercial lever than in the past. As procurement organizations compare suppliers not only on unit price but also on qualification effort, audit exposure, and supply continuity, manufacturers with stronger certification portfolios and more mature process control will be better positioned to defend margins. The trend does not imply that price becomes irrelevant; it implies that price negotiations occur within a narrower field of qualified, trusted sources. Companies that can present clean documentation, consistent quality performance, and traceable manufacturing practices will have more room to compete on total value rather than on headline cost alone.
For commercial strategy, this trend suggests that investments in documentation rigor, regulatory upkeep, and quality systems can pay dividends in buyer preference and supplier longevity. The opportunity is not just to maintain certifications, but to use them as part of a broader value narrative that reduces friction for procurement teams.
Worldwide Butenafine API Market
Trend Two: Supply Resilience and Procurement Behavior Realignment
Supply chain vulnerabilities linked to fermentation raw material sourcing and geographically concentrated production are likely to remain a central concern. Buyers will continue to evaluate multi-source options, safety stock logic, and supplier responsiveness, especially where recurring demand must be met without interruption. This creates an environment in which suppliers that can provide predictable availability, transparent communication, and contingency readiness may gain preference even if their unit pricing is not the lowest in a tender comparison.
The commercial opportunity here lies in reliability as a differentiator. For manufacturers, this may mean investing in feedstock management, yield consistency, inventory planning, or regional distribution support. For buyers, it means re-evaluating sourcing strategies so that resilience is priced into supplier selection rather than treated as an afterthought. In practice, the market may increasingly reward a “ dependable supplier premium,” where dependable means more than delivery timeliness and includes documentation, quality stability, and responsiveness under stress.
Trend Three: Formulation Alignment and Application-Specific Differentiation
Because dermatological and gastrointestinal applications dominate usage, the most relevant commercial opportunities will continue to cluster around formulation alignment and practical usability. Topical and oral products represent the largest share of activity, while compounding-oriented powder remains a narrower but meaningful niche. Suppliers that understand how their API behaves in downstream formulation contexts, and that can support customers with relevant documentation, handling guidance, and format consistency, may strengthen their commercial position beyond what volume competition alone allows.
This trend opens the door to more application-aware engagement. Rather than selling Nystatin API purely as an ingredient, successful players may increasingly frame their offering around formulation compatibility, batch consistency, and customer-specific supply needs. That shift does not require dramatic product innovation; it requires a sharper understanding of how purchasing and formulation teams evaluate risk and usability in day-to-day operations.
Strategic Implications for Different Decision-Makers
For manufacturers and suppliers, the most important move is to treat quality and documentation as core competitive assets rather than administrative overhead. Reducing process variability, maintaining certification currency, and building a credible narrative around supply reliability can improve both buyer confidence and margin resilience. Where capacity expansion is considered, it should be tied to demonstrable quality capability and clear sourcing differentiation, not solely to cost leadership.
For investors and strategic backers, the market offers a relatively stable but selective opportunity. Growth is present, but value creation depends on competitive position, compliance maturity, and supply continuity rather than on broad category expansion. Due diligence should focus on process control, certification status, raw material exposure, and the supplier’s ability to serve procurement needs across regulated markets. In this segment, durable advantage is more likely to arise from operational credibility than from speculative volume plays.
For procurement and sourcing teams, the practical task is to balance cost with qualification burden and continuity risk. Diversifying among competent suppliers, evaluating total cost of ownership, and not over-relying on the lowest-unit-price option can reduce exposure to quality or availability disruptions. In markets where documentation and process consistency determine how quickly a supplier can be onboarded and retained, procurement strategy should make those factors part of the evaluation framework from the outset.
The broader strategic implication is that the Nystatin API market is not primarily a story of explosive scale. It is a story of maturing competition, where disciplined manufacturing, regulatory readiness, and supply dependability determine who retains commercial leverage over time. The market rewards participants who can reduce friction for buyers while preserving operational control over quality and availability.
For organizations seeking a more granular view of regional dynamics, format-level demand shifts, procurement behavior patterns, and supplier-level benchmarking, a fuller commercial intelligence package can help translate these high-level trends into sourcing decisions, investment theses, and operational planning. Detailed segmentation-level data and tailored scenario analysis can sharpen the picture considerably, especially when the objective is to move from general market awareness to concrete purchasing, production, or entry decisions.
For detailed analysis of this topic, please visit the official page: Nystatin API Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com