

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Dried Lemon Market 2026: Why 6.8% CAGR and High Growth Signal Industry Shifts

Worldwide Dried Lemon Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
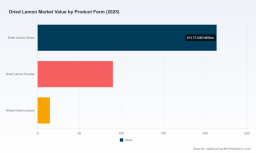
The worldwide dried lemon market has demonstrated steady expansion over the past five years, transitioning from a niche ingredient category to a broadly integrated component of global food, wellness, and personal care supply chains. Valued at approximately USD 318.4 million in 2025, the market has moved from a 2020 baseline of roughly USD 235 million, reflecting a compound annual growth rate of 6.8 percent through 2032. This trajectory indicates more than incremental demand growth; it signals a structural shift in how manufacturers source, formulate, and commercialize citrus-derived ingredients. Dry lemon formats now serve multiple downstream channels, from culinary and beverage applications to pharmaceutical formulations and cosmetic extracts, creating cross-sector demand that insulates the market from single-industry volatility.
Despite this momentum, the industry faces several interconnected challenges that will shape competitive positioning and margin structures in the near term. The first is raw material supply volatility. Fresh lemon harvests are increasingly exposed to climate variability, labor constraints, and regional weather disruptions, which directly affect the volume and quality of fruit available for dehydration. When fresh fruit availability contracts, processing margins tighten and downstream buyers face pricing uncertainty, forcing manufacturers to balance inventory strategies against cost control.
The second challenge lies in quality consistency and specification standardization across global trade lanes. Dried lemon products vary widely in moisture content, particle size, essential oil retention, and processing method, making it difficult for formulators to maintain consistent sensory profiles or regulatory compliance across regions. Buyers increasingly demand traceable, batch-uniform ingredients, yet the supply base remains fragmented, with differing drying technologies and agricultural practices producing uneven output characteristics.
A third pressure point is the evolving regulatory and trade classification environment. Citrus peel and dried fruit products navigate distinct customs codes, phytosanitary requirements, and labeling standards depending on destination markets. Changes in trade documentation, organic certification expectations, and food safety protocols can introduce friction in cross-border sourcing, particularly for smaller processors that lack the compliance infrastructure of multinational ingredient suppliers. These dynamics do not undermine the market's growth trajectory, but they require operators to invest in supply chain visibility, quality assurance, and regulatory readiness to capture premium segments.
Key Drivers of Market Change
Technology Innovation and Processing Breakthroughs
Advances in dehydration and drying technologies are reshaping the value proposition of dried lemon products. Traditional air-drying methods are increasingly supplemented by controlled-temperature dehydration and freeze-drying processes that better preserve color, aroma compounds, and functional constituents. For ingredient manufacturers, this means a wider range of product forms can be engineered to meet specific application needs, whether the priority is visual appeal in retail-ready packaging or rapid solubility in beverage mixes and pharmaceutical excipients. Improved moisture control and particle-size consistency also reduce waste during downstream processing, allowing food and beverage manufacturers to standardize formulations with greater confidence.
PW Consulting
Parallel developments in extraction and encapsulation are expanding how dried lemon derivatives are used. Essential oil recovery, natural flavor isolation, and stabilized citrus extracts enable companies to deliver lemon functionality in formats that withstand shelf-life requirements and processing conditions. These capabilities are particularly relevant for nutraceutical and cosmetic formulators seeking clean-label inputs that can replace synthetic alternatives without compromising performance.
Policy and Regulatory Environment
Trade classification and regulatory frameworks are becoming more precise, influencing how dried lemon products move across borders. Standardized customs coding for citrus peel and dried citrus fruit has clarified import pathways, reducing ambiguity in documentation and easing compliance for bulk shippers. At the same time, destination markets continue to refine food safety, organic certification, and labeling expectations, which raises the bar for suppliers seeking access to premium European and North American channels.
This regulatory tightening is a double-edged force. On one hand, it increases the operational burden for smaller exporters that must invest in traceability systems and certification upkeep. On the other hand, it rewards processors that can demonstrate consistent quality, transparent sourcing, and verified agricultural practices. In effect, the regulatory landscape is accelerating a shift from commodity-style trading toward specification-driven supply relationships, where documented process controls and origin verification become competitive differentiators.
Demand-Side Shifts in Consumer and Corporate Behavior
Consumer preferences are steering demand toward natural, recognizable ingredients across food, beverage, and personal care categories. Lemon's sensory profile and association with freshness make it a versatile choice for flavor enhancement, functional positioning, and visual appeal. In the food and beverage sector, dehydrated lemon forms are increasingly used to deliver consistent flavor without the logistical complexity of fresh fruit, particularly in markets where seasonal availability or transportation constraints limit fresh citrus access.
Beyond flavor, lemon-derived ingredients are gaining traction in wellness-oriented formulations. Nutraceutical developers incorporate dried lemon components into products positioned around digestive support, antioxidant content, and clean-label botanical profiles. In cosmetics and personal care, citrus extracts and dried lemon derivatives serve both functional and sensory roles, aligning with the broader demand for naturally derived ingredients. These demand shifts are not limited to retail consumers; foodservice operators and industrial manufacturers are also seeking ingredient suppliers that can provide reliable batch consistency, flexible packaging formats, and documentation that supports their own labeling claims.
Supply Chain and Cost Structure Dynamics
Cost structures in the dried lemon market are being reshaped by upstream agricultural conditions and energy inputs tied to drying operations. Producer price movements for fresh lemons have shown upward pressure, reflecting tighter harvests in key growing regions and elevated wholesale pricing in major European markets. At the same time, projections for global fresh lemon and lime production indicate a notable decline for the current marketing year, compounding supply constraints for processors that depend on steady fruit inflow.
These pressures are prompting supply chain recalibration. Some processors are extending forward contracting with growers, diversifying sourcing footprints, and adjusting inventory strategies to buffer against seasonal shortfalls. Others are investing in processing efficiency to offset higher raw material and energy costs, including improved drying throughput and better byproduct utilization. For downstream buyers, the implication is that pricing and availability will become more sensitive to harvest cycles and regional supply disruptions, making supplier relationships and contract structures increasingly strategic rather than purely transactional.
Competitive Landscape and Leading Strategies
The dried lemon market remains moderately fragmented, with the top three firms holding a combined share in the mid-teens and the top five approaching less than thirty percent. This structure favors a diverse mix of regional processors, multinational ingredient suppliers, and value-added specialists, each pursuing distinct strategic positions rather than competing solely on volume.
Leading companies have differentiated themselves through vertical integration, application-focused innovation, and sustainability positioning. Citrus processors with orchard control or long-term grower relationships, such as large Argentinean lemon operators, are able to secure raw material continuity and manage quality from harvest through dehydration. Their ability to produce dehydrated peel, essential oils, juices, and pulp cells from owned or tightly managed orchards gives them an advantage in consistency and supply resilience, particularly when fresh fruit markets tighten.
Dry Fruit Market
European and North American ingredient suppliers have built their strategies around formulation support and application versatility. Specialist dehydration providers and freeze-drying operations focus on delivering dried slices, powders, and fruit ingredients tailored to foodservice, snack, and industrial use cases, emphasizing particle uniformity, moisture control, and packaging formats that suit downstream processing. Multinational ingredient companies contribute a different set of capabilities, including natural flavor solutions, dried lemon derivatives, and technical service support that helps food and beverage manufacturers integrate citrus inputs into complex formulations. Cooperative and grower-marketer models extend fresh citrus operations into value-added dried supply chains, leveraging brand recognition and existing orchard infrastructure to serve both retail and industrial channels.
Dried Fruit Market
Strategic differentiation is increasingly tied to sustainability and traceability. Several processors have emphasized renewable processing facilities, byproduct utilization, and sustainable sourcing models, aligning with buyer expectations in European and North American markets where procurement teams evaluate environmental credentials alongside cost and quality. This is visible in ongoing distribution of dehydrated citrus by-products from sustainable processing facilities, as well as in forward-looking supply guidance from fresh lemon producers that supports downstream dried processing volumes.
The market structure is likely to evolve through selective consolidation and continued specialization rather than full concentration. Larger ingredient groups may pursue acquisitions to broaden their dried citrus portfolios and strengthen technical service capabilities, while regional processors may deepen relationships with specific applications or geographic channels. New entrants are most likely to succeed by targeting underserved product forms, such as organic-certified dried lemon inputs or customized powder specifications for nutraceutical and cosmetic use, where technical differentiation and compliance readiness matter more than sheer scale.
Future Trends and Opportunity Outlook
Over the next three to five years, one of the clearest trends will be the continued expansion of dried lemon into functional and clean-label formulations. As food, beverage, and personal care companies seek natural alternatives to synthetic flavorings and additives, dried lemon inputs will see broader adoption in products where ingredient transparency and recognizable sourcing are part of the value proposition. This trend favors suppliers that can provide documented origin, consistent specifications, and application support, because formulators will prioritize inputs that simplify compliance and labeling while maintaining performance.
A second trend is the growing importance of supply resilience and contractual structure. With fresh lemon production facing cyclical pressure and wholesale prices elevated in key regions, buyers and processors alike will place greater emphasis on forward contracting, diversified sourcing, and inventory planning. This creates opportunities for processors with strong grower relationships, multi-origin supply footprints, or efficient processing operations that can absorb cost variability better than less integrated competitors. It also encourages closer collaboration between suppliers and downstream customers, where sharing demand forecasts and coordinating harvest timing can smooth availability across seasons.
A third trend is the broadening of premiumization within dried lemon categories. Organic-certified products, specialty dried forms, and ingredients optimized for specific sensory or functional outcomes are likely to command higher margins and deeper buyer engagement. As European and North American procurement teams become more accustomed to evaluating sustainability, traceability, and processing standards, premium segments may grow faster than commoditized bulk channels. At the same time, potential risks remain: weather-driven harvest variability, energy cost exposure in drying operations, and regulatory shifts in trade classification or certification requirements could all disrupt short-term pricing and availability. Companies that treat these risks as strategic variables, rather than background noise, will be better positioned to capture the upside.
Actionable Guidance for Decision Makers
For manufacturers and ingredient suppliers, the priority is to strengthen supply continuity and specification reliability. Investing in drying efficiency, quality assurance protocols, and traceability systems will help protect margins and meet the expectations of buyers who require batch consistency and documentation for labeling claims. Where possible, diversifying sourcing and securing forward fruit commitments can reduce exposure to harvest shocks and wholesale price swings. For companies with technical service capabilities, expanding application support for nutraceutical, cosmetic, and foodservice use cases can open higher-value channels beyond bulk commodity sales.
For investors and strategic planners, the market warrants attention to value-added segments and sustainability-oriented operators. The moderate concentration of the market leaves room for targeted consolidation and for specialists that can differentiate through product form, certification, or technical integration. Monitoring harvest forecasts, producer price trends, and regulatory changes will be essential for anticipating shifts in input costs and sourcing feasibility. Capital allocation should favor businesses that demonstrate both supply resilience and the ability to serve premium, specification-driven demand rather than those reliant on undifferentiated bulk volume.
For procurement teams and sourcing managers, the most effective move is to treat dried lemon suppliers as strategic partners rather than transactional vendors. Embedding quality requirements, traceability expectations, and sustainability criteria into sourcing decisions will reduce downstream formulation risk and support cleaner labeling. Where demand is growing or seasonal volatility is high, developing multi-source strategies and flexible contracting structures can improve availability while limiting cost surprises. For organizations seeking deeper segmentation data, regional sourcing intelligence, and tailored recommendations aligned with specific product portfolios, a comprehensive market report can provide the detailed structure needed to translate these trends into concrete sourcing and investment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Dried Lemon Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com