

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Pellicle Market 2026: Asia Pacific’s 11.5% CAGR and 72.5% CR3 Concentration

Navigating the Next Wave: Strategic Trends and Commercial Opportunities in the Global Pellicle Market
Market Overview and Core Challenges
The global pellicle market has entered a phase of accelerated expansion, driven by the relentless scaling of semiconductor manufacturing and the proliferation of advanced lithography techniques. In 2025, worldwide revenue for pellicle products reached approximately USD 1.78 billion. This figure represents a meaningful acceleration compared with earlier years, as the segment moved beyond a flat trajectory observed during 2022-2023 into renewed growth. Projections indicate that the market will surpass USD 3.8 billion by 2032, implying a compound annual growth rate of roughly 11.5 percent across the forecast horizon. Such momentum underscores a structural shift rather than a cyclical upturn, rooted in the transition to sub-3nm process nodes and the widespread adoption of extreme ultraviolet lithography for critical patterning layers.
Despite this favorable backdrop, the industry faces several defining challenges. First, the pellicle landscape is highly concentrated, with a small group of specialized suppliers accounting for the vast majority of global revenue. This concentration creates dependency risks for downstream manufacturers, limits pricing flexibility, and raises barriers to entry for new competitors. Second, the transition from conventional photolithography pellicles to EUV-compatible variants demands entirely different material science capabilities. Membranes must operate at thicknesses measured in tens of nanometers, maintain transmittance above ninety percent at a wavelength of 13.5 nanometers, and withstand intense radiation environments without compromising particle protection. Third, qualification cycles are lengthy and stringent. Equipment vendors enforce rigorous certification protocols, meaning that any shift in scanner architecture, power level, or operating protocol requires revalidation that can delay product ramps by months or even years. Finally, the rapid emergence of high-power EUV systems, including those supporting high numerical aperture configurations, places unprecedented thermal and mechanical stress on pellicle membranes. Suppliers must simultaneously improve durability, throughput, and yield reliability while managing raw material costs and scaling production capacity.
Black Pellets Market
These dynamics converge to create a market where technical readiness, supply chain execution, and strategic positioning determine competitive advantage. Companies that can align material innovation with manufacturing scale, while navigating qualification and customer integration cycles, are best positioned to capture the value being generated by next-generation lithography.
Key Drivers of Market Evolution
Several interconnected forces are reshaping demand, supply, and competitive strategy across the pellicle ecosystem.
Technological Innovation and Material Breakthroughs
The central driver remains the push toward higher energy, higher resolution lithography. Traditional polysilicon membranes are being supplemented or replaced by carbon nanotube and other advanced membrane architectures that deliver superior transmittance and thermal resilience. Carbon nanotube-based solutions, for instance, demonstrate single-pass EUV transmission approaching 97 percent and thermal stability extending to 1500 degrees Celsius in vacuum environments. These properties are critical for high-power scanners operating above 500 watts, where pellicle durability directly influences tool uptime and pattern fidelity. In practical terms, such membranes can support productivity gains in the range of 8 to 15 percent by reducing contamination risk and enabling longer operational intervals between replacements. As memory makers and logic suppliers adopt higher-NA and higher-output EUV tools, demand for pellicles that tolerate elevated thermal loads while preserving optical performance will intensify.
Policy, Standards, and Qualification Frameworks
The regulatory and standardization environment exerts a decisive influence on market speed and supplier viability. Equipment manufacturers require third-party certification for scanner safety and performance before alternative pellicle technologies can be deployed in EUV systems. This requirement ensures interoperability and risk mitigation but also extends development timelines and concentrates influence among a few qualified suppliers. The interplay between proprietary equipment roadmaps and industry certification expectations creates a moat around established material platforms while incentivizing suppliers to invest early in alignment with tool vendor specifications. Policy signals related to semiconductor sovereignty, export controls, and domestic manufacturing incentives further shape regional demand patterns and encourage localized supply chain development, particularly in jurisdictions seeking to reduce dependence on imported advanced materials.
Worldwide Meat Membrane Skinner Market
Demand-Side Shifts Across End-Use Applications
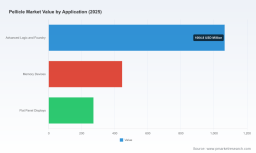
Demand is being pulled by multiple application streams. Advanced logic and foundry operations dominate volume, reflecting the need for pellicle protection on multi-patterning and single-exposure EUV layers as node scaling continues. Memory device manufacturers represent a substantial and growing segment, particularly as advanced DRAM and NAND architectures adopt EUV for critical masking steps that improve yield and reduce process complexity. Flat panel display manufacturing also contributes meaningful demand, though at different performance and cost thresholds than leading-edge semiconductors. Across these applications, the common thread is increased layer counts, tighter defect budgets, and higher sensitivity to particle contamination, all of which elevate the strategic value of reliable pellicle solutions.
Supply Chain and Cost Structure Dynamics
On the supply side, scaling production capacity while preserving membrane quality is a central tension. Facilities must be designed for highly controlled environments, specialized reactor systems, and post-processing steps that maintain nanoscale uniformity. Recent capacity expansions and licensing arrangements illustrate how suppliers are building out the manufacturing infrastructure required to meet accelerating demand. At the same time, cost structures are influenced by the availability of specialized precursor materials, the economics of reactor utilization, and the need to amortize qualification investments across customer programs. Suppliers that secure early reactor deployment, lock in customer site acceptance milestones, and achieve steady-state production rates are better able to manage unit economics and compete on both performance and reliability.
Competitive Landscape and Leading Strategies
The market remains dominated by a handful of firms with deep expertise in advanced materials, silicon processing, and lithography-adjacent technologies. This concentration shapes both opportunity and risk.
Differentiated Positioning Among Leaders
Mitsui Chemicals has established a prominent position in the EUV pellicle space, initially commercializing polysilicon-based solutions under licensing arrangements and subsequently investing in carbon nanotube variants for high-power and high-NA systems. Its strategy emphasizes scale-up through dedicated production facilities targeting annual output capacity in the range of thousands of sheets, with supply ramp timelines aligned to next-generation tool adoption. The company’s focus extends beyond logic applications toward memory segments, signaling a diversification of end-use exposure.
Shin-Etsu Chemical leverages its foundational strengths in silicon wafers and photomask substrates to develop advanced LSI and EUV-oriented membranes. Its approach centers on improving yield and process stability through material quality and integration know-how, positioning the company as a reliable contributor to the broader lithography supply chain.
Canatu has carved out a distinctive role by specializing in carbon nanotube membranes engineered for high transmittance and extreme thermal stability. Its product capabilities support productivity improvements in high-power scanners, and the firm has pursued a partner-centric commercial model that includes licensing its reactor technology for mass production. This route enables scale without requiring the licensee to replicate the full technology stack, accelerating time-to-market for advanced membrane production.
FINE SEMITECH represents a regional manufacturing play, focusing on advanced pellicle production for Asian foundries and next-generation EUV tools. Its adoption of licensed reactor technology underscores a pragmatic path to capacity build-out while aligning with the geographic concentration of leading-edge logic and memory production.
A broader set of participants, including AGC, S&S Tech, Toppan Photomasks, Entegris, SKC, and ASML itself, contributes through material inputs, coating technologies, mask and handling solutions, and equipment qualification. Their roles illustrate how the pellicle value chain is interconnected with substrate supply, protective handling systems, and scanner integration. ASML’s position as the primary EUV system provider grants it outsized influence over qualification pathways and compatible membrane specifications.
Strategic Themes and Market Evolution
Several strategic patterns emerge from the current landscape. First, technology roadmaps are moving from polysilicon toward carbon nanotube and silicon-based membranes designed for higher thermal loads and stricter defect budgets. Second, commercialization increasingly relies on licensing and joint readiness milestones, with reactor shipments, site acceptance test approvals, and production line commissioning serving as de facto gate checks for scale. Third, geographic demand remains concentrated, and suppliers are expanding capacity in proximity to major fabrication hubs to reduce lead times and support customer co-development. Fourth, the qualification barrier acts as both a shield for incumbents and a filter for new entrants, meaning that sustained investment in certification alignment and tool-vendor relationships is essential.
The evolution of the market is likely to feature incremental consolidation among specialized material suppliers, while application-specific differentiation grows. As high-power and high-NA systems scale, suppliers that can demonstrate durable transmission performance, reproducible manufacturing yield, and rapid qualification turnaround will capture disproportionate share. At the same time, new entrants will need to solve not only material performance but also the operational realities of reactor utilization, post-processing consistency, and customer integration.
Outlook for the Next Three to Five Years
Looking ahead, three trends are poised to define the market trajectory.
Higher-NA and higher-power adoption will accelerate pellicle performance requirements. As more scanners operate at elevated power levels and tighter focus conditions, pellicle membranes must sustain optical performance and mechanical integrity over extended cycles. This will favor materials with proven thermal stability and consistent transmittance, and it will push qualification programs to prioritize long-duration reliability data.
Manufacturing scale and licensing-driven commercialization will expand capacity. The market is moving from pilot-scale production toward steady-state manufacturing. Reactor deployment, site acceptance milestones, and dedicated facility completions are translating into the ability to serve multiple high-volume customers. Companies that secure early production readiness and align supply timing with tool rollouts will be better positioned to capture demand.
PW Consulting
Application diversification will broaden the opportunity set while complicating prioritization. While advanced logic and foundry operations will remain the largest demand pool, memory and select display applications will contribute growing volume. This diversification offers revenue resilience but also requires suppliers to manage different performance, cost, and qualification expectations across customer segments.
These trends create commercial opportunities for suppliers that can deliver differentiated membrane performance, scale production efficiently, and navigate qualification pathways quickly. At the same time, uncertainty remains. Shifts in scanner power strategies, changes in node migration timing, and the risk of revalidation delays can alter demand timing. Cost volatility in specialized materials and the need for sustained capital investment in reactor infrastructure also introduce execution risk. Participants must therefore balance aggressive capacity planning with disciplined qualification and customer engagement.
Actionable Guidance for Decision-Makers
For manufacturers and technology developers: Prioritize early alignment with equipment qualification roadmaps and invest in membrane formulations that demonstrate thermal stability and consistent transmittance under high-power conditions. Build modular production capacity that can be scaled as site acceptance and certification milestones are met, and structure partnerships to accelerate commercialization without overextending internal R&D resources.
For investors and corporate development teams: Focus on the intersection of material differentiation and manufacturing readiness. The most durable value creation will come from suppliers that combine proven performance in high-power EUV environments with credible paths to steady-state production and diversified application exposure. Evaluate progress against reactor deployment, qualification status, and capacity ramp timing rather than headline announcements alone.
For procurement and strategic sourcing leaders: Treat pellicle selection as a multi-year reliability decision rather than a component-level purchase. Evaluate suppliers on long-term transmittance consistency, thermal durability, qualification support, and ability to sustain yield across high-volume production. Diversify where possible to reduce concentration risk, while ensuring that any alternative solution meets stringent scanner certification requirements.
Timely, granular intelligence on capacity timelines, qualification status, application mix, and regional demand shifts is essential for making these decisions with confidence. Detailed segmentation data, supplier benchmarking, and scenario analysis can sharpen planning and reveal where to allocate resources for maximum impact. Interested readers can explore the full research report for comprehensive breakdowns, company profiles, and tailored recommendations that extend beyond the strategic overview presented here.
For detailed analysis of this topic, please visit the official page: Worldwide Pellicle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com