

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Electro Pneumatic Converter Market: Why 5.2% CAGR and $1.08B Size Redefine Growth
By pmarketresearch, 2026-09-18
Global Electro-Pneumatic Converter Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The global electro-pneumatic converter market has demonstrated steady expansion over the past half-decade, evolving from a mature instrumentation segment into a dynamic interface technology critical to automated industrial control. Base-year revenue in 2025 establishes the market at approximately 760 million USD, reflecting a compound annual growth rate of 5.19 percent projected through 2032, when the addressable market is expected to surpass 1.08 billion USD. This trajectory signals more than incremental demand growth; it reflects a structural shift in how industries bridge electronic control architectures with pneumatic actuation systems. Revenue patterns between 2020 and 2025 reveal a recovery phase following supply chain disruptions, followed by sustained expansion as industrial automation investments accelerated across process and discrete manufacturing environments. The forward forecast, however, introduces a notable inflection point: a temporary leveling of growth momentum around the 2028-to-2029 window, followed by renewed acceleration toward the end of the decade. This pattern suggests that near-term saturation in legacy installations will give way to replacement cycles, efficiency mandates, and emerging application domains.
Despite the encouraging growth baseline, the sector faces three intersecting challenges that will shape competitive outcomes over the next several years. First, performance expectations are escalating. End users increasingly demand converters that deliver tighter linearity, lower hysteresis, faster response times, and extended operational stability under fluctuating pressure, temperature, and vibration conditions. Meeting these specifications requires advanced sensor integration, refined solenoid design, and more rigorous calibration protocols, pushing manufacturers to continuously upgrade engineering capabilities. Second, regulatory complexity continues to intensify, particularly for installations in hazardous environments. Intrinsic safety requirements, regional compliance variations, and certification pathways such as ATEX introduce additional validation costs, lengthen product development cycles, and complicate global market access for suppliers that lack established compliance infrastructure. Third, cost volatility is reshaping margin dynamics. Inputs including stainless steel, copper, precision pressure sensors, and high-performance engineering plastics are subject to price swings that directly affect production economics. Suppliers that depend on passive procurement or inflexible supply arrangements face greater exposure, while those with diversified sourcing, material substitution strategies, or value-engineered product architectures are better positioned to preserve profitability.
A further structural observation is worth emphasizing: market concentration remains moderate, with the top three participants capturing roughly 42.5 percent of total revenue and the top five collectively representing approximately 58.7 percent. This distribution indicates a competitive field that is neither dominated by a small oligopoly nor fragmented into ineffective niches. Incumbents hold meaningful scale advantages in distribution, service networks, and brand trust, yet sufficient headroom exists for specialized players, regional specialists, and technology-differentiated entrants to capture share by addressing underserved segments or performance gaps. The implication for strategy is clear: growth will increasingly be determined by how effectively companies navigate specification escalation, compliance burdens, and input cost variability while maintaining credible value propositions in a moderately consolidated landscape.
Key Drivers Reshaping Market Trajectory
The momentum behind the electro-pneumatic converter market is not uniform; it is being shaped by several reinforcing forces that alter both demand patterns and competitive requirements. Understanding these drivers is essential for anticipating where growth will concentrate and which capabilities will separate thriving suppliers from laggards.
Technological Innovation and Performance Escalation
A defining feature of current market evolution is the push toward higher precision, enhanced reliability, and tighter integration between electronic signals and pneumatic output. Converters are no longer treated as passive signal interfaces; they are expected to maintain stable calibration under demanding process conditions, reduce drift over extended service intervals, and interface cleanly with broader control architectures. Advances in solenoid valve design, improved feedback sensing, and refined open-loop and closed-loop control approaches are enabling products that deliver better linearity and faster response. These improvements matter because process control accuracy increasingly translates directly into yield, safety, and operational consistency for end users. Manufacturers that invest in robust engineering, repeatable quality systems, and transparent performance specifications are gaining credibility, particularly in applications where downtime or control error carries significant operational cost.
Regulatory and Compliance Pressures Raising the Bar
Regulation is acting as both a barrier and a differentiator. In industries where equipment operates in potentially explosive atmospheres or other hazardous environments, certification is not optional. Converters with recognized safety approvals provide a meaningful commercial advantage because they reduce integration risk and accelerate deployment in constrained sites. At the same time, quality management standards and process documentation expectations are becoming baseline requirements rather than competitive extras. Suppliers that maintain disciplined quality systems and clear compliance pathways can shorten customer qualification cycles and expand their addressable market in regulated verticals. Conversely, companies that treat certification and quality assurance as afterthoughts face mounting friction in bidding for projects where risk tolerance is low and procurement scrutiny is high.
Demand-Side Shifts in Industrial Automation and Process Control
Demand is being driven by broader automation trends across multiple industrial contexts. Process industries continue to modernize valve control, fluid handling, and actuation systems to improve throughput, consistency, and operator safety. At the same time, automation expansion in packaging, material handling, and specialized manufacturing environments is broadening the use cases for electro-pneumatic conversion. Buyers are increasingly specifying converters not only for functionality, but also for lifecycle performance, maintenance burden, and compatibility with existing control infrastructure. This shift favors suppliers that can present credible value across total cost of ownership rather than competing solely on unit price. It also encourages demand for standardized product families that simplify specification, spares management, and field replacement.
Supply Chain and Cost Structure Dynamics
Input cost volatility remains a persistent strategic issue. Prices for materials such as stainless steel, copper, and components used in solenoid and electronic assemblies can fluctuate enough to influence production economics and pricing stability. This environment rewards suppliers that build resilient sourcing strategies, monitor material exposure proactively, and design products with reasonable flexibility for alternative materials or manufacturing approaches where performance allows. It also places a premium on operational discipline: yield optimization, scrap reduction, and inventory planning become more consequential when raw material and component costs are unpredictable. In practical terms, cost structure resilience is becoming a competitive advantage, not just an internal efficiency metric.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a mix of established global suppliers, region-focused manufacturers, and specialized firms targeting high-value niches. The market’s moderate concentration leaves room for multiple viable strategic postures, but it also forces companies to be explicit about where they will win. Competitive advantage is increasingly less about listing a broad product catalog and more about demonstrating credible performance, dependable compliance, and deployment ease in the target application set.
Strategic Positioning of Leading Participants
Several incumbents illustrate the range of viable strategic plays. ControlAir has built its positioning around precision I/P and E/P transducers and electro-pneumatic regulators for process control, valve automation, and fluid power applications, reinforced by an ISO-9001:2015 registered quality system. This combination of performance focus and disciplined quality management supports credibility in applications where specification adherence matters. The emphasis on worldwide distribution further extends reach without requiring every market to be served through a single direct model.
ABB represents a different but complementary approach, offering converter series designed for signal conversion between control rooms and pneumatic actuators, with housing options that include or exclude booster stages. This product flexibility aligns with the practical reality that end users often need solutions tailored to specific mounting, flow, and interface requirements. The strategic value here lies in offering configurable solutions that reduce engineering customization at the project level.
Yokogawa Electric Corporation draws on decades of experience in valve positioners and converters for industrial process control, an asset that supports trust in demanding continuous-process environments. Longevity in process instrumentation often translates into customer confidence, especially where reliability and service familiarity are weighted heavily in procurement decisions. SMC Corporation applies its broader automation and pneumatic expertise to electro-pneumatic regulators and converters, including high-flow and manifold-type solutions. This positions the company well in industrial automation settings where integration with compressed air systems and manifold efficiency are important selection criteria.
Additional participants add further texture to the landscape. Emerson, through its Fisher-related transducer offerings, emphasizes uptime and environmental performance in final control applications, an angle that resonates in operations where downtime is costly. Watson Smith, now part of Norgren, highlights safety-conscious design with converter options carrying ATEX certification for hazardous areas, demonstrating how compliance capability can become a market entrance ticket in specific verticals. Regional and application-focused manufacturers such as Valcom, Fujikura Composite, Bellofram, and Valve Related Controls illustrate how targeted designs, modular construction, and environmentally sealed options can sustain competitive relevance even in a consolidated market. The common thread among stronger players is not merely product breadth, but clarity of fit between product attributes and customer priorities.
Pneumatic Components Market
Evolution of the Market Structure
The competitive structure appears to be moving along two parallel paths. In one direction, integration is increasing among suppliers seeking broader portfolios, wider geographic coverage, and improved ability to serve customers with unified specifications and service models. In the other direction, differentiation is intensifying around precision, hazardous-area compliance, specialized flow ranges, and modular or sealed designs. This dual dynamic suggests that pure price competition will be insufficient for sustained advantage. New entrants and smaller specialists can still win by addressing performance gaps, regional service expectations, or application-specific constraints, but they must do so with clear technical justification and dependable execution. For incumbents, the strategic question is whether to expand through portfolio breadth, deepen presence in high-value verticals, or both.
Future Outlook and Emerging Commercial Opportunities
Looking toward the 2026-to-2032 horizon, the market’s direction appears shaped by a combination of replacement demand, specification escalation, and expanding deployment contexts. The projected growth path implies that the strongest opportunities will not come from a single driver, but from the convergence of several trends that increase both the volume and the value of converter installations.
One likely trend is the growing importance of certified, safety-capable converter solutions in hazardous and regulated environments. As enforcement expectations and site risk standards continue to mature, buyers will increasingly favor products with established certification and documented compliance histories. This creates commercial opportunities for suppliers that can provide clear qualification support, maintain approved product lines, and reduce procurement friction in constrained environments. It also suggests that certification capability will become a strategic asset rather than a compliance checkbox.
Worldwide Electro-pneumatic Transducers Market
A second trend is the continued pressure for higher precision and longer service stability. As process control and automation systems become more interconnected, converter performance can have outsized effects on overall system behavior. Suppliers offering tighter specifications, better repeatability, and transparent performance data are likely to gain preference in applications where control quality influences output consistency, safety, or maintenance frequency. There is also opportunity in product designs that simplify replacement, calibration, and integration, since installation and lifecycle handling are increasingly part of the purchasing decision.
PW Consulting
A third trend is the uneven regional and vertical expansion of demand. Stronger uptake is expected where automation modernization, process optimization, and safety upgrades are prioritized, while slower segments will depend on capital cycles and retrofit timing. This unevenness creates both opportunity and risk: companies that can align product portfolios with the most active verticals and regions stand to capture disproportionate share, but they also face the risk of overcommitting to segments where spending pauses or shifts toward alternative technologies. For the broader market, the key uncertainty is whether macroeconomic volatility, input cost shocks, or project delays could compress near-term investment and alter the pace of adoption, particularly around the 2028-to-2029 period where the forecast implies a temporary deceleration before later acceleration.
Strategic Recommendations for Decision Makers
For manufacturers, the priority should be to sharpen product positioning around verifiable performance and compliance, rather than relying on generic specification claims. Investment in quality systems, calibration discipline, and application-specific variants can help capture buyers who are comparing total cost of ownership, not just upfront price. Equally important is supply chain resilience: building flexibility into material sourcing and production planning can protect margins when input costs fluctuate.
For investors, the market offers value in companies that combine credible technical differentiation with disciplined execution in quality, certification, and regional service. The moderate concentration of the market suggests there is room for both scaled incumbents and capable specialists, but durable advantage will likely accrue to firms that can demonstrate repeatability, reduce customer integration risk, and manage cost exposure effectively. Caution is warranted in segments where pricing pressure is intense and differentiation is weak, since those areas are more vulnerable to margin erosion and demand volatility.
For procurement and engineering leaders evaluating converter suppliers, the practical focus should be on specification realism, certification coverage, service responsiveness, and lifecycle support. A lower unit cost can be misleading if it introduces qualification delays, higher replacement frequency, or compatibility challenges. Evaluating supplier consistency, documentation quality, and track record in the relevant operating environment will usually yield better long-term outcomes than optimizing for the lowest initial quotation.
Detailed segment data, regional revenue splits, company-level comparisons, and scenario analysis can materially improve strategic planning and sourcing decisions, especially where capital allocation or product roadmap choices depend on precise market sizing. For decision makers seeking a fuller picture beyond the directional trends outlined here, the complete study provides a deeper breakdown of market structure, growth path, and competitive dynamics to support more targeted action.
For detailed analysis of this topic, please visit the official page: Worldwide Electro Pneumatic Converter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Snowblower Market Trends: Why Two-Stage Models and North America Reshape Growth by 2032
By pmarketresearch, 2026-09-18
Navigating the Snowblower Market: Strategic Trends and Commercial Opportunities (2026-2032)
Market Overview and Core Challenges
The global snowblower market has demonstrated steady growth over the past five years, expanding from approximately $10.82 billion in 2020 to an estimated $12.61 billion in 2025. This trajectory reflects consistent demand drivers tied to winter preparedness, residential infrastructure expansion, and commercial facility management. Looking ahead to 2032, the market is projected to reach $15.61 billion, representing a compound annual growth rate of 3.1 percent. While the growth rate suggests maturity rather than explosive expansion, the underlying dynamics reveal significant shifts in how snow removal equipment is developed, distributed, and utilized.
Revenue distribution across regions highlights a clear concentration pattern. North America accounts for the largest share of global sales, reflecting the region's climate profile, established consumer base, and mature distribution networks. Europe follows as the second-largest market, driven by consistent winter conditions and a growing emphasis on commercial snow management solutions. Asia Pacific, Latin America, and the Middle East and Africa collectively represent smaller but emerging opportunities, where infrastructure development and variable winter patterns create niche demand segments.
Within the product landscape, two-stage snow blowers dominate the market, valued at over $7.08 billion, reflecting their versatility and effectiveness for moderate to heavy snow conditions. Single-stage models, valued at approximately $4.01 billion, serve lighter snowfall regions and residential applications where ease of use and lower cost take priority. Three-stage units, valued at around $1.51 billion, capture a specialized segment focused on extreme conditions and professional-grade performance. Application-wise, the residential segment leads with approximately $7.43 billion in revenue, while commercial applications contribute roughly $5.18 billion, indicating strong demand from property management firms, municipal operations, and facility maintenance providers.
Several challenges are reshaping how companies approach strategy in this market. First, the supply chain environment has become increasingly volatile. Raw material costs, particularly for steel and aluminum, have been influenced by tariff policies and global supply fluctuations. In early 2026, U.S. hot-rolled coil steel prices ranged from $935 to $965 per ton, driven in part by tariffs affecting snow blower manufacturing costs. The continued imposition of Section 232 tariffs on steel and aluminum imports at 25 percent has further complicated sourcing for manufacturers reliant on imported components. Global steel supply chain dynamics show apparent steel consumption projected to recover by 3.1 percent in 2026 following prior declines, but this recovery introduces pricing uncertainty that manufacturers must carefully manage.
Second, regulatory and safety scrutiny has intensified. Product safety incidents have prompted recalls and heightened attention to design integrity. For instance, Ariens recalled Deluxe, Platinum, and Professional series snow throwers due to impeller and auger assembly continuing to rotate after control lever release, as documented by the U.S. Consumer Product Safety Commission in early 2025. This event underscores the importance of robust engineering and quality assurance processes, particularly for companies competing on performance and durability.
Third, the market is experiencing a technology transition as battery-electric alternatives gain traction. While traditional gas-powered models continue to lead in many segments, the introduction of cordless and low-emission options is reshaping consumer expectations and forcing incumbents to invest in powertrain diversification. Companies must balance the performance advantages of internal combustion engines with the environmental and operational benefits of electric platforms, all while managing cost structures and consumer education.
For decision-makers, these dynamics signal a market where growth is no longer solely about volume expansion. Strategic positioning requires attention to cost resilience, product safety, and adaptation to evolving powertrain preferences. Companies that can navigate these pressures while delivering reliable, differentiated solutions will be best positioned to capture value in the coming years.
Key Drivers Shaping the Market
Technological Innovation and Performance Differentiation
The snowblower market is undergoing a period of meaningful technological evolution. Manufacturers are investing in engine optimization, clearing technology improvements, and user-centric design features that enhance performance across diverse snow conditions. Ariens introduced 2026 Platinum series updates with enhanced 389cc engines designed for heavy snow conditions, demonstrating how incremental engineering advancements can reinforce market leadership in the two-stage segment. Similarly, Toro released a 2025-2026 lineup including 60V MAX Power Max e26 two-stage battery snow blower models, signaling a strategic push toward electric platforms that combine performance with reduced noise and emissions.
Beyond powertrain shifts, three-stage clearing technology has emerged as a differentiator for heavy-duty applications. This configuration, which incorporates an accelerator in addition to the auger and impeller, addresses scenarios where rapid snow displacement is critical. Cub Cadet's 3X series and Troy-Bilt's Storm series have both emphasized three-stage options, illustrating how brands are using advanced clearing architectures to appeal to users who face frequent, intense snowfall. These advancements are not merely incremental; they reflect a broader industry trend toward segment-specific engineering, where product design aligns closely with regional climate profiles and usage intensity.
For manufacturers, the implication is clear: competitive advantage increasingly depends on delivering measurable performance improvements that resonate with specific user needs. Companies that invest in R&D focused on engine reliability, clearing efficiency, and ease of operation can command premium positioning and foster brand loyalty in a market where replacement cycles create recurring demand opportunities.
Policy and Regulatory Environment
Regulatory developments continue to shape cost structures and product strategy. The persistence of U.S. Section 232 tariffs on steel and aluminum imports at 25 percent in 2026 has direct implications for snow blower manufacturing, as these materials are fundamental to chassis construction, auger systems, and impeller assemblies. Imported components and raw materials face higher costs, prompting manufacturers to evaluate sourcing strategies, domestic production adjustments, and pricing models.
Fully Automatic Snow Blower Market
At the same time, safety regulations and consumer protection oversight are becoming more rigorous. Recalls and incident reporting highlight the need for proactive compliance and design validation. The Ariens recall exemplifies how mechanical failure modes can trigger regulatory action and reputational risk, reinforcing the importance of thorough testing protocols and quality control across production lines.
Policy uncertainty also extends to environmental expectations. While no sweeping regulatory mandate currently dictates powertrain transitions in snow removal equipment, shifting consumer sentiment and local emissions considerations are influencing purchasing behavior. Manufacturers that anticipate these trends by developing lower-emission options and communicating environmental benefits can position themselves ahead of potential regulation while appealing to eco-conscious buyers.
Demand-Side Changes in Consumer and Commercial Behavior
Demand patterns are evolving as end users reassess their snow removal priorities. In the residential segment, homeowners are increasingly seeking equipment that balances power, ease of use, and operational cleanliness. Battery-powered snow blowers, such as those offered by EGO Power+ and Greenworks, address concerns around noise, emissions, and maintenance while providing sufficient clearing capability for typical residential snowfall. These products appeal particularly to users in suburban areas where garage space, storage, and proximity to neighbors make quieter, cordless operation desirable.
On the commercial side, facilities management teams and municipal operators are prioritizing reliability and throughput. Snow Joe and similar affordable electric and battery options target lighter residential removal, while commercial-focused users look for durability and clearing speed. The broader trend indicates a bifurcation in demand: lighter-duty, user-friendly products for homeowners and more robust, high-performance systems for businesses that cannot afford clearing downtime.
Weather variability also influences purchasing timing and volume. Regions experiencing heavier or more unpredictable winter patterns tend to see stronger equipment demand, while milder winters can temporarily suppress replacement cycles. This volatility encourages manufacturers to maintain flexible production planning and regional marketing strategies that align with localized climate expectations.
Supply Chain and Cost Structure Evolution
Cost pressures from raw materials and trade policy are reshaping margin expectations. Steel price fluctuations, tariffs on imported inputs, and global supply chain adjustments have forced manufacturers to examine component sourcing, inventory management, and pricing strategies more closely. The projected 3.1 percent recovery in global steel consumption in 2026 suggests improving availability, but price stability remains uncertain.
Manufacturers are responding by diversifying supplier bases, evaluating domestic production options, and exploring design efficiencies that reduce material intensity without compromising durability. Battery-electric models also introduce a different cost structure, shifting expense from fuel and maintenance toward battery technology and electronic components. Over time, as battery costs evolve and production scales, the economics of electric snow blowers may improve, expanding their viability beyond niche applications.
For industry participants, supply chain resilience has become a strategic priority. Companies that can manage input cost volatility, maintain production continuity, and adapt pricing to preserve value perception will be better equipped to sustain margins in a fluctuating cost environment.
Competitive Landscape and Leading Strategies
The market features a mix of established manufacturers, brand portfolios under larger industrial groups, and emerging electric-focused entrants. Ariens stands out for its focus on two-stage snow blowers with Deluxe, Platinum, and Professional series targeting heavy-duty residential and commercial snow removal. Its recent product updates and engine enhancements reflect a strategy centered on performance credibility and segment specialization. Toro Company complements this approach with a broad portfolio spanning gas and battery-powered models, including Power Max and Power Clear series, enabling it to serve both traditional and transitioning customer preferences.
Honda Power Equipment maintains a premium positioning known for reliability, with HSS series two-stage models leveraging Honda engines optimized for performance and ease of use. This reputation for durability supports a higher price point and appeals to users who prioritize long-term value. Cub Cadet and Troy-Bilt, both part of the MTD Products network, offer distinct brand positioning: Cub Cadet emphasizes power steering and three-stage clearing technology through its 2X and 3X series, while Troy-Bilt focuses on affordable, high-performance two and three-stage options via its Storm series. This parent-company strategy of managing multiple brands allows coverage across price points and feature sets without internal cannibalization.
Husqvarna and John Deere both integrate snow blowers into broader outdoor power equipment lineups, leveraging brand trust and cross-category customer relationships. Craftsman provides single, two, and three-stage models distributed through major retail channels like Lowe's, capitalizing on widespread retail access and brand recognition. EGO Power+ and Greenworks represent the electric-focused cohort, specializing in battery-powered and corded electric solutions that emphasize quiet, emission-free operation for residential applications. Snow Joe and RYOBI target affordability and accessibility, with Snow Joe known for lighter residential electric and battery throwers and RYOBI offering battery and gas options sold primarily through Home Depot. KOVACO adds European manufacturing presence with compact and professional snow blowers, reflecting localized product strategies in regional markets. Simplicity, also MTD-affiliated, reinforces the durability-focused homeowner segment.
Several strategic patterns emerge from this landscape. First, brand portfolios and multi-tier offerings enable companies to address diverse customer segments while maintaining operational efficiencies. Second, electric powertrain development is becoming a competitive differentiator, with incumbents expanding battery lines and specialized entrants building credibility around cordless performance. Third, product safety and quality assurance are increasingly visible elements of brand reputation, as recalls and regulatory scrutiny can influence consumer trust and retailer relationships.
The competitive environment is evolving through both consolidation and fragmentation. Larger industrial groups continue to manage multiple brands, creating economies of scale in manufacturing and distribution while preserving distinct brand identities. At the same time, the rise of electric solutions and specialized clearing technologies opens space for focused entrants that can innovate quickly in specific niches. Trade show participation, such as RPM Tech exhibiting the PB-2000 snow blower at the Atlantic Heavy Equipment Show to showcase municipal and airport clearing capabilities, illustrates how new and expanding players are targeting specialized commercial applications beyond traditional residential markets.
Worldwide Hand Held Blower Market
For market participants, the key question is not simply who leads today, but which companies can adapt product architectures, supply chains, and brand messaging to align with shifting consumer expectations and cost realities. Differentiation will increasingly depend on performance consistency, powertrain flexibility, and the ability to communicate value in ways that resonate with both traditional and new user priorities.
Future Trends and Strategic Implications
Looking ahead to the 2026-2032 period, several trends are likely to shape market evolution. The first is the continued expansion of battery-electric options across residential and light commercial segments. As battery technology improves and production scales, cordless snow blowers will become more capable of handling moderate to heavy snowfall, broadening their addressable market. Manufacturers that develop reliable electric platforms and educate consumers on performance realities will capture early-mover advantage in an transitioning segment. However, this trend carries uncertainty around battery cost trajectories, charging infrastructure expectations, and consumer willingness to adopt cordless solutions for heavy-duty use.
The second trend is increasing focus on segment-specific engineering and application alignment. As climate variability and regional snowfall patterns influence purchasing decisions, companies will likely invest further in product configurations tailored to distinct use cases. This includes three-stage systems for extreme conditions, compact electric units for suburban homeowners, and commercial-grade equipment for municipal and facility operations. The strategic opportunity lies in matching product portfolios to regional demand profiles and avoiding one-size-fits-all positioning that may dilute brand relevance.
The third trend involves supply chain and cost management as persistent competitive factors. Tariffs, steel price volatility, and global material flows will continue to influence manufacturing economics. Companies that diversify sourcing, optimize material usage, and maintain pricing flexibility will protect margins more effectively than those dependent on single supply routes or rigid cost structures. At the same time, any relaxation or reconfiguration of trade policy could shift cost dynamics quickly, requiring agile planning and scenario readiness.
These trends create commercial opportunities for manufacturers that can balance innovation with operational resilience, for investors seeking exposure to brands that demonstrate adaptability across powertrain transitions, and for procurement teams that benefit from understanding which suppliers are best positioned to deliver consistent quality amid cost volatility. The primary risk is complacency in the face of technological and regulatory shifts; companies that treat the market as static may lose ground to competitors who anticipate changing user expectations and cost environments.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to strengthen product differentiation through targeted engineering and powertrain diversification. Investing in engine reliability, clearing technology, and electric platform development can reinforce market position across segments. Equally important is proactive quality assurance and compliance to mitigate safety-related disruptions that can affect brand trust and retail relationships. Companies should also evaluate supply chain flexibility, including multi-source sourcing and material optimization, to manage cost volatility without sacrificing product durability.
For investors, the strategic focus should be on companies that demonstrate adaptability across traditional and electric product lines, maintain strong brand equity in core regions, and exhibit disciplined cost management. Brands with multi-tier portfolios and clear segment positioning may offer more resilient growth profiles in a market where demand is bifurcating between lightweight residential solutions and heavy-duty commercial systems. Monitoring trade policy developments and raw material trends can also help anticipate shifts in manufacturer margins and pricing strategies.
PW Consulting Automotive & Machinery Research Center
For procurement and purchasing leaders, understanding supplier positioning and product architecture differences can inform sourcing decisions for residential, facility, or municipal applications. Evaluating manufacturers based on engineering depth, safety track records, and powertrain options enables more informed selection aligned with operational requirements and environmental preferences. Building relationships with suppliers that demonstrate supply chain resilience and consistent quality can reduce disruption risk during peak demand periods.
Detailed segmentation data, cost structure analysis, and customized strategic guidance can provide deeper clarity for organizations making specific investment or sourcing decisions. A complete research report offers granular breakdowns across regions, product types, and applications, along with forward-looking scenarios that support more precise planning.
For detailed analysis of this topic, please visit the official page: Snowblower Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Ceramic Flap Disc Market: Beyond the 6.15% CAGR and Strategic Shifts to 2032
By pmarketresearch, 2026-09-18
The Worldwide Ceramic Flap Disc Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview: Sizing the Opportunity and Identifying the Pressure Points
The global ceramic flap disc market is navigating a period of measured expansion, underpinned by steady industrial activity and evolving surface-finishing requirements across multiple heavy industries. Revenue generated by this segment has grown consistently over the past five years, reflecting a compound annual growth rate that institutions tracking industrial consumables have placed in the low-to-mid single digits. Market size has expanded from the mid-$500 million range in the early 2020s to well over $700 million at the current reference point, with forward trajectories suggesting continued upward movement through the end of the decade and beyond. By 2032, total market value is expected to surpass the $1.1 billion threshold, a path that implies a compounding growth rate around 6.15 percent. This trajectory signals a market that is not merely expanding in absolute terms but is also gradually shifting in composition as end users demand higher precision, longer tool life, and safer operating profiles across increasingly complex fabrication workflows.
While aggregate growth looks healthy, the industry is confronting structural headwinds that will separate resilient operators from those that fail to adapt. First, raw material cost volatility has moved from a cyclical nuisance to a persistent strategic factor. Calcined alumina, a cornerstone input for premium ceramic abrasives, has experienced price appreciation driven by elevated energy costs and constrained production capacity in key sourcing regions. When material inputs rise steadily but final demand grows only moderately, manufacturers face margin compression unless they can pass costs downstream, redesign formulations, or capture operational efficiencies that offset input inflation. This dynamic is particularly pronounced in ceramic flap discs, where grain quality directly dictates performance and substitution into lower-cost alternatives often sacrifices finishing quality or tool longevity.
Second, the regulatory environment has tightened in ways that reshape product design and operational risk. Updated safety standards in major industrial markets now prescribe maximum safe operating speeds and mandate clearer performance classifications for abrasive tools used in fixed machinery. These requirements are not trivial administrative updates; they force manufacturers to validate designs against stricter testing protocols, adjust labeling and packaging for compliance, and ensure that product claims align with verified operating parameters. For buyers, the regulatory shift means that sourcing decisions increasingly hinge on documented compliance records and traceability, reducing the room for ad hoc procurement based solely on unit price.
Third, labor dynamics in metalworking-heavy economies are altering the calculus of tool selection at the shop floor level. Rising wages in fabrication centers coincide with persistent shortages of skilled welders and finishing technicians. In this environment, workplaces are prioritizing consumables that reduce rework, extend run time between changes, and lower the skill threshold required to achieve consistent surface quality. The implication is subtle but powerful: the value proposition of ceramic flap discs is not only about final fineness or stock removal speed, but also about reducing variability in high-mix, lower-margin fabrication environments where every minute of downtime and every error carries an outsized cost.
Key Drivers Reshaping the Market
Technological Innovation in Grain Geometry and Binding Systems
The most consequential driver in this market is the ongoing refinement of ceramic grain architecture and bonding formulations. Precision-shaped grains have moved the industry past the blunt trade-offs of earlier abrasive generations, enabling higher stock removal with less heat generation and a longer predictable life cycle. Manufacturers have increasingly focused on controlling grain fracture behavior so that fresh cutting edges are exposed in a more controlled manner, maintaining cutting efficiency over a broader wear window. This is especially relevant in applications where operators switch frequently between carbon steel, stainless steel, and alloy surfaces; a disc that maintains consistent aggressiveness without premature loading reduces changeover frequency and improves throughput.
At the same time, advances in resin and fiber bonding have contributed to improved concentricity and reduced vibration at higher rotational speeds. For users running powered hand tools or fixed machines at aggressive settings, these improvements translate into safer operation and more uniform surface blending. The performance envelope that ceramic flap discs now offer is narrowing the historical gap between dedicated grinding wheels and flexible finishing media, allowing shops to consolidate their abrasive inventory without sacrificing process quality. From a commercial standpoint, this consolidation is attractive because it simplifies procurement, reduces training complexity, and creates a clearer preference for premium products over generic alternatives when performance consistency is tied to downstream quality metrics.
Regulatory and Standards-Driven Product Redesign
Regulatory updates are functioning as a second powerful driver by forcing a reexamination of how flap discs are rated, labeled, and used. Modern safety standards do not merely set guardrails; they influence the engineering choices that manufacturers make years before a product reaches the market. When operating speed limits and safety performance requirements are codified with greater specificity, companies that already maintain rigorous test protocols and documentation can turn compliance into a competitive advantage. Buyers, in turn, are placing greater weight on certifications, operating envelopes, and traceable quality records when evaluating suppliers for volume contracts.
This dynamic creates a subtle market premium for documentation discipline. Suppliers with mature quality systems are better positioned to respond quickly to revised standards, while smaller or less structured competitors may face delays or redesign costs that affect time-to-market. The practical outcome is a gradual reinforcement of the position held by established industrial abrasive brands, not because regulation explicitly favors incumbents, but because the burden of compliance scales more gracefully for organizations with existing engineering and quality infrastructure.
End-User Behavior and the Demand for Consistency
Demand-side behavior is shifting as fabrication and finishing operations face more variable workloads and tighter turnaround expectations. Metal fabrication shops, welding operations, and aerospace and automotive finishing teams are less interested in isolated performance metrics than in predictable outcomes across batches. A disc that delivers acceptable results on one steel grade but degrades quickly on another introduces process risk, particularly where rework triggers downstream delays or scrap penalties. As a result, the purchasing conversation is increasingly framed around consistency, operator feedback, and total cost per finished surface rather than sticker price alone.
This preference for consistency is amplified by labor economics. When skilled welders and finishers are scarce and expensive, shops are motivated to choose consumables that reduce operator error and support less experienced staff in achieving acceptable results. Ceramic flap discs with stable cutting behavior, clear wear indications, and reliable load resistance fit this requirement well. The trend also encourages manufacturers to invest in application-specific guidance, not as a marketing exercise but as a genuine operational support function that helps buyers match the right disc geometry and grit to the right substrate and operation.
Supply Chain Reconfiguration and Trade Friction
The third major driver is the reconfiguration of the abrasive supply chain under the influence of cost pressure, local sourcing preferences, and trade barriers. Chinese abrasives exports have scaled significantly in absolute terms, but facing elevated tariffs in European markets has altered the cost structure for imported products in certain regions. These trade dynamics do not eliminate the relevance of globally sourced inputs; instead, they shift attention toward regional supply resilience, inventory positioning, and supplier diversification. For downstream manufacturers and distributors, the practical response has been to balance cost-competitive sourcing with nearer-term inventory buffers and to factor tariff and logistics volatility into multi-year supply planning rather than relying on spot pricing.
Raw material economics remain intertwined with this supply chain story. When key inputs such as calcined alumina move upward in price due to energy and production costs, the entire value chain must absorb or redistribute that pressure. Companies that can negotiate stable input contracts, optimize grain formulations for cost-performance balance, or offer product tiers that align with different application requirements will be better equipped to preserve margins without losing price-sensitive segments of the market. The net effect is a market in which supply chain strategy is becoming as important as product performance in determining competitive outcomes.
Competitive Landscape and Leading Strategies
The competitive environment is moderately concentrated, with the largest three players accounting for roughly one-third of market revenue and the top five approaching just under half. That concentration level is high enough to signal the influence of established brands but not so extreme as to prevent nimble challengers from gaining traction in specific applications or geographies. The roster of major participants includes manufacturers with strong regional identities, deep application expertise, and product families tailored to metalworking, welding, and finishing workflows.
PW Consulting
Several strategic postures stand out across this group. One common approach is differentiated product architecture, where companies build distinct disc families for flat versus conical configurations, each optimized for particular stock removal, blending, or weld seam preparation tasks. The T27 flat ceramic flap disc format remains a workhorse for broad surface preparation and aggressive stock removal, while the T29 conical format is typically favored for weld seam cleanup and contour blending where operator ergonomics and access to curved surfaces matter. Companies that clearly communicate these application differences tend to capture more wallet share because buyers are better able to standardize on a smaller set of SKUs that cover the majority of shop floor scenarios.
A second strategic element is application-led product development supported by visible market presence. Firms that exhibit new or refined disc lines at major trade events and promptly push updated products into catalogs are signaling responsiveness to end-user feedback. For instance, recent showcases have highlighted ceramic flap disc variants positioned for improved stainless steel and carbon steel grinding, as well as enhanced formulations intended for pipeline welding and other demanding fabrication tasks. These moves matter because they reduce the lag between field requirements and product availability, reinforcing the perception that a supplier can keep pace with evolving fabrication needs.
A third and often underestimated dimension is safety and standards readiness. With updated operating-speed mandates and performance requirements for fixed machinery gaining prominence, companies that embed compliance into product development and documentation are creating a moat around their commercial relationships. Procurement teams increasingly look for documented operating envelopes and consistent quality records when awarding volume business. Suppliers that can supply this information reliably reduce the buyer's perceived risk, which can be decisive in competitive bidding situations where unit cost differences are narrow.
The market is also exhibiting a blend of consolidation and fragmentation pressure. Larger industrial abrasive groups benefit from scale in R&D, global distribution, and quality systems, which supports their ability to compete across regions and applications. At the same time, there is room for specialization: regional specialists and application-focused brands can win by concentrating on particular substrates, weld-finishing workflows, or local service and technical support. New entrants face a challenging path if they try to compete on generic price alone, but a focused approach that addresses a specific application gap or solves a documented operator pain point can secure a foothold, especially in regions where distribution relationships and technical assistance are valued as much as the product itself.
Future Outlook: Trends and Commercial Opportunities for the Next Three to Five Years
Looking ahead, three trends appear especially likely to shape the market's next phase. The first is a continued bias toward premium, application-specific ceramic flap discs as buyers rationalize their abrasive assortments around consistency and total cost per finished part. As fabrication and welding operations grapple with labor scarcity and rework sensitivity, the cost of variability will increasingly outweigh the appeal of lower unit prices. That environment favors products with predictable wear behavior, clear operating envelopes, and strong documentation support, and it should sustain demand growth for higher-performance ceramic formulations even where overall end-market growth is modest.
Zirconium Oxide Flap Disc Market
The second trend is deeper integration of product and process support. Over the next several years, suppliers that combine performance data, application guidance, and compliance documentation into a coherent offering will differentiate more clearly from those that sell discs as undifferentiated consumables. Expect more emphasis on operator training materials, recommended rotational-speed guidance aligned with evolving safety standards, and substrate-specific usage recommendations that help shops standardize on the right disc for each task. This shift creates an opportunity for manufacturers and distributors to strengthen customer stickiness through practical value rather than pricing pressure.
The third trend concerns supply chain architecture and regional resilience. Trade friction, input cost pressure, and the need to reduce inventory risk will nudge buyers and manufacturers toward more diversified sourcing and closer coordination on lead times and safety stock. For companies able to offer stable supply, clear documentation, and regionally appropriate product mixes, this is a window to deepen relationships with larger fabrication and finishing accounts. At the same time, businesses should monitor the possibility of localized price distortions in markets where tariffs or logistical bottlenecks raise the cost of imported abrasives, since those distortions can temporarily advantage regional producers but also complicate long-term planning for buyers seeking predictable pricing.
These trends carry both opportunity and uncertainty. The opportunity lies in aligning product strategy with operational value: fewer SKUs, better documentation, application-specific performance, and supply reliability. The uncertainty centers on macro factors beyond any single company's control, including energy-driven input costs, the pace of regulatory enforcement in major markets, and the trajectory of fabrication activity in sectors sensitive to economic cycles. Companies that treat these variables as part of their strategic planning rather than as external noise will be better positioned to capture the market's incremental growth without overcommitting to assumptions that fail under stress.
Actionable Guidance for Decision Makers
For manufacturers and product developers, the clearest priority is to invest in formulation and testing that align with the new safety and performance expectations while reducing variability across substrates. A disciplined focus on grain behavior, bonding consistency, and documented operating parameters can convert compliance from a cost center into a differentiator. In parallel, narrowing the SKU portfolio around the configurations most frequently used in metal fabrication, welding, and finishing can improve inventory efficiency and reinforce buyer confidence in standardized solutions.
For investors and corporate strategists, the strategic signal is that value in this market is accruing to companies with quality systems, application expertise, and resilient supply structures rather than to undifferentiated price competition. When evaluating exposure to the ceramic flap disc segment, attention should be paid to brands that demonstrate consistent product launches, active presence in relevant trade channels, and the operational discipline to support evolving standards. Portfolio decisions should also account for regional dynamics, including the impact of trade measures on imported abrasives and the relative strength of local fabrication demand.
For procurement and supply-chain leaders, the practical recommendation is to shift evaluation criteria from unit price alone toward total cost of ownership and risk reduction. That means prioritizing suppliers who can provide reliable operating-speed documentation, substrate-specific performance guidance, and stable supply commitments, especially in environments where skilled labor is scarce and rework is costly. Diversifying sources and maintaining visibility into input-cost trends can further reduce exposure to sudden price shocks or regional supply disruptions.
For organizations seeking to go deeper into regional growth patterns, application-level demand structures, and competitive benchmarks at a more granular level, the full research set behind this analysis contains detailed segmentation data, regional breakdowns, and company-level profiles designed to support customized strategic planning. Accessing that level of detail can help decision makers move from a clear market narrative to specific choices about product focus, sourcing, geographic emphasis, and partnership strategy.
Flap Disc Market
For detailed analysis of this topic, please visit the official page: Worldwide Ceramic Flap Disc Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Leadership Due Diligence Market: Why 6.82% CAGR Redefines Private Equity Strategy
By pmarketresearch, 2026-09-18
Leadership Due Diligence Market: Strategic Trends and Commercial Opportunities Through 2032
The leadership due diligence market has evolved from a peripheral consideration in transaction advisory to a central component of investment decision-making. By 2025, the market reached an estimated $450.0 million in revenue, expanding from $321.45 million in 2020. This trajectory reflects a compound annual growth rate of 6.82 percent across the forecast period extending to 2032, with projected revenue climbing toward $708.68 million by the end of the outlook window. The growth pattern indicates sustained demand rather than cyclical fluctuation, driven by structural shifts in how capital allocators and corporate acquirers evaluate human capital risk.
Several structural challenges define the current inflection point. First, the field remains fragmented, with a top three concentration of 38.5 percent and a top five concentration of 48.2 percent. This level of concentration suggests that while established players hold meaningful share, significant room exists for specialized entrants and niche methodologies to capture targeted segments. Second, standardization gaps persist across assessment protocols, creating variability in how leadership risk is quantified, communicated, and integrated into deal pricing or post-close integration planning. Third, the market faces a credibility test: leadership due diligence must move beyond checkbox compliance and demonstrate measurable influence on deal outcomes, retention metrics, and value realization timelines. Buyers and investors increasingly question whether assessments translate into actionable intelligence or merely confirm pre-existing assumptions.
The stakes have risen because leadership and cultural misalignment are now widely recognized as material contributors to transaction failure. Industry analysis indicates that leadership and culture factors surface as key drivers in deal success or failure rates ranging from 70 to 90 percent, while weak succession readiness or elevated leadership turnover can compress enterprise value by up to 20 percent in M&A contexts. These figures reframe leadership due diligence from a soft advisory service into a risk mitigation and value preservation function. For executives and investors, the implication is clear: the market is growing because the cost of ignoring leadership risk has become too visible to overlook.
Key Demand Drivers Reshaping the Landscape
Technology-enabled assessment methodologies are accelerating the sophistication of leadership due diligence. Practitioners increasingly combine psychometrics, structured interviews, cross-feedback loops, and reference verification into integrated diagnostic models. This 360-degree approach helps identify blind spots, leadership bench strength, and cultural friction points that traditional financial or legal due diligence often miss. The shift toward multi-source evidence gathering reduces reliance on self-reported narratives and improves the defensibility of conclusions for investment committees and boards. As assessment tools become more refined, the value proposition moves from identifying obvious red flags to surfacing nuanced risk-and-opportunity profiles that inform retention planning, integration design, and post-deal governance.
Regulatory and standards-based expectations are also shaping service design. The adoption of recognized assessment standards, such as ISO 10667-2 in certain leadership evaluation workflows, signals a broader push toward consistency, documentation rigor, and auditability. While the market does not operate under a single mandated framework, the trend toward standardized protocols responds to buyer demands for repeatable methods that can withstand internal scrutiny and external challenge. For deal teams, this means leadership due diligence is increasingly expected to produce structured outputs that align with broader transaction documentation, risk registers, and integration roadmaps rather than standalone narrative reports.
Demand-side behavior is shifting as capital becomes more selective and post-deal execution risk receives greater attention. Private equity and investment firms represent the largest end-user cohort, followed by corporate M&A departments and venture capital investors. These stakeholders are placing heavier emphasis on human capital risk because leadership quality and team cohesion directly affect synergy realization, customer retention, and operational continuity. The buy-side conversation has moved toward practical questions: Does the leadership team have the depth to execute the business plan? Are there succession vulnerabilities? Will cultural integration create friction that slows value creation? These questions have elevated leadership due diligence from a pre-close formality to a continuous consideration that can influence offer structuring, earn-out design, and leadership retention agreements.
Cost and value dynamics further reinforce demand. Organizations are scrutinizing where diligence spending generates defensible returns, and leadership due diligence is increasingly positioned as a lever for protecting enterprise value rather than an additive expense. The logic is straightforward: identifying leadership gaps early can reduce post-close turnover, accelerate integration, and preserve customer and employee trust during transition periods. Conversely, overlooking leadership risk can lead to expensive corrective actions, delayed synergy capture, and reputational damage. As a result, buyers are more willing to invest in structured leadership assessment when it is tied clearly to deal rationale and integration planning.
Competitive Landscape and Strategic Positioning
The competitive arena blends specialized boutique providers with large professional services networks, each pursuing distinct positioning. Specialized firms tend to emphasize dedicated leadership due diligence work-streams embedded within M&A processes, often focusing on leadership structure, culture, human capital risk, retention planning, and post-deal integration. Their differentiation frequently rests on deep transactional context, repeatable assessment architecture, and close alignment with investor and deal team workflows. By operating as focused work-streams rather than broad human capital add-ons, these providers aim to make leadership insights directly usable in investment committee discussions and integration planning.
Directors and Officers (D&O) Insurance Market
Other providers distinguish themselves through methodological breadth and investor-centric design. Some deploy multi-source diagnostic models that combine psychometrics, interviews, surveys, and cross-feedback to identify risks, blind spots, and value creation levers across pre-investment, post-investment, and turnaround scenarios. This approach appeals to investors seeking a comprehensive view of leadership dynamics rather than isolated executive assessments. A separate segment of high-end providers emphasizes bespoke frameworks tailored to private equity, venture capital, strategy advisors, and law firms, with science-based assessments aligned to strategic objectives and cultural integration analysis. These firms often position quality, customization, and strategic alignment as their core advantages, targeting complex transactions where leadership evaluation must connect directly to value creation assumptions.
Large global advisory and consulting networks meanwhile integrate leadership due diligence into broader M&A, transaction advisory, and human capital offerings. Their strength lies in scale, cross-service coordination, and the ability to link leadership assessment with financial, tax, legal, and operational work-streams. For many corporate and institutional clients, this integration reduces coordination friction and supports a unified diligence narrative. At the same time, executive assessment and leadership advisory firms contribute deep competency modeling, bench strength analysis, and fit-for-role evaluation, particularly where post-deal value creation depends on leadership capability and succession readiness. The presence of multiple service models creates choice but also complexity for buyers seeking the right fit for transaction size, industry context, and internal capability.
Assessment Services Market
Market evolution is shaping up as both consolidation and specialization. On one hand, larger advisors continue to absorb human capital and leadership capabilities into integrated transaction practices, which can improve end-to-end consistency. On the other hand, specialized providers are deepening their methods, expanding their transactional relevance, and increasingly articulating leadership due diligence as a de-risking tool rather than a compliance step. Recent industry commentary reflects this shift: leadership due diligence is being reframed as a boardroom priority for building trust in senior leadership appointments, while practitioner guidance emphasizes practical techniques to spot strengths and risks before buy-side decisions. Specialized providers have also reinforced the message that leadership due diligence should function as a core de-risking mechanism in M&A, not a checkbox exercise. The net effect is a market that is professionalizing while still leaving room for differentiated methodologies, sector focus, and regional expertise.
Future Trends and Commercial Implications (2026–2032)
Over the next three to five years, leadership due diligence is likely to become more integrated into transaction workflows rather than treated as a standalone report. As deal teams seek faster, more defensible insight, assessment outputs will increasingly connect to integration planning, retention agreements, and governance design. This integration creates commercial opportunity for providers that can translate leadership diagnostics into practical post-deal actions, such as role design, succession planning, and cultural harmonization roadmaps. Providers that bridge pre-close assessment and post-close execution will be better positioned to demonstrate value beyond the diligence phase.
PW Consulting Information & Electronics Research Center
A second trend is the continued elevation of human capital risk in deal valuation and structuring. As leadership and culture factors are more frequently cited in deal success or failure discussions, investors and corporate acquirers may embed leadership considerations into pricing assumptions, earn-out structures, and management retention terms. This creates opportunities for advisors who can quantify leadership risk in ways that are understandable to financial and legal stakeholders. The commercial implication is that leadership due diligence may increasingly influence not only whether a deal proceeds, but how it is structured and managed after signing.
A third trend is methodological maturation and greater expectation of consistency. As standards-based practices gain visibility and buyers become more sophisticated, the market will likely reward providers with transparent assessment logic, documented processes, and clear linkage between findings and recommended actions. At the same time, uncertainty remains. The market could face pressure if economic conditions slow transaction volume, if buyers reduce discretionary diligence spending, or if overly generic assessments erode trust in the category. There is also a risk that inconsistent quality across providers makes it harder for buyers to compare offerings, slowing adoption in segments where leadership due diligence is not yet standard practice.
Strategic Actions for Decision-Makers
For private equity and investment firms, the priority is to treat leadership due diligence as an integral part of deal risk assessment rather than an optional enhancement. Structuring leadership evaluation around clear transaction hypotheses—such as synergy dependence on management continuity, scalability of the leadership bench, and cultural compatibility with integration plans—can improve the practical utility of findings. Investors should also define how leadership insights will inform retention planning, incentive design, and post-close governance before diligence begins, so that assessment outputs feed directly into execution planning.
For corporate M&A departments, leadership due diligence should be aligned with the strategic rationale for the acquisition. When deals depend on preserving customer relationships, retaining key talent, or integrating distinct operating cultures, leadership evaluation should be scoped early enough to influence deal architecture and integration design. Corporate buyers can benefit from clear criteria that distinguish between leadership gaps that can be addressed through restructuring or external hires and those that pose deeper strategic risk to value realization.
For venture capital and growth-stage investors, leadership assessment should focus on scalability, decision-making quality, and succession resilience as companies move through expansion phases. Early identification of leadership constraints can shape board involvement, recruitment strategy, and governance evolution. Across all buyer types, the most effective use of leadership due diligence comes when it is tied to specific decisions: whether to proceed, how to price risk, whom to retain, and what integration steps to prioritize. Given the range of methodologies, service models, and regional specialties available, obtaining detailed segmentation data and tailored guidance can help organizations match diligence scope to transaction context and internal capability. The full research report provides more granular segmentation, company-level comparisons, and actionable recommendations for selection and deployment.
For detailed analysis of this topic, please visit the official page: Leadership Due Diligence Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Custom LED Lighting Solution Market: The Real 11.12% Growth Drivers to 2032
By pmarketresearch, 2026-09-18
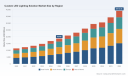
Global Custom LED Lighting Solution Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The worldwide custom LED lighting solution market has transitioned from a niche specialty segment to a significant growth engine within the broader illumination industry. Between 2020 and 2025, market revenue expanded from approximately $11.45 billion to $18.70 billion, reflecting a compound annual growth rate of 11.12 percent. Projections indicate this trajectory will continue, with revenue expected to surpass $39 billion by 2032. This growth underscores a fundamental shift away from standardized, off-the-shelf lighting products toward tailored solutions that integrate specific aesthetic, functional, and technological requirements. The market is no longer solely about illumination; it is about delivering precise lighting environments that align with architectural visions, commercial branding strategies, and specialized operational needs.
Despite the robust growth trajectory, the industry faces several critical challenges that create both headwinds and opportunities for strategic positioning. First, the supply chain for critical raw materials remains a significant vulnerability. The production of essential semiconductor materials such as gallium and germanium is heavily concentrated in specific geographic regions, with China maintaining dominant shares of global output. Export licensing mechanisms and prior restrictions have periodically disrupted supply flows, compelling manufacturers to navigate complex procurement strategies. This reliance creates exposure to price volatility and potential shipment delays, particularly for companies dependent on steady inputs for high-performance LED components.
Second, regulatory and trade policy environments are becoming increasingly stringent. Recent executive directives in the United States have initiated negotiations on imports of processed critical minerals and derivative products, citing national security concerns. The prospect of tariffs or altered trade terms introduces uncertainty for cost structures and sourcing strategies. Companies must now factor geopolitical developments into their supply chain resilience planning, as policy shifts can rapidly alter the cost competitiveness of imported components versus domestically sourced alternatives. The interface between illumination engineering and trade policy has become a routine consideration for strategic planning teams.
Third, the market is experiencing a tension between customization demands and production scalability. Customers increasingly expect bespoke designs, smart integration, and rapid turnaround, yet maintaining margin profiles while accommodating low-volume, high-variety orders requires sophisticated manufacturing flexibility. Organizations that rely on rigid production lines risk losing share to competitors who have invested in modular platforms, digital customization tools, and agile supply networks. The operational challenge lies in balancing the premium pricing potential of custom solutions with the efficiency expectations of a market that continues to grow at double-digit rates.
Finally, market concentration remains relatively fragmented at the aggregate level, with the top three and top five participants together accounting for a modest share of total revenue. This dispersion indicates that no single entity currently dominates the global landscape, creating room for consolidation, niche specialization, and new entrants who can differentiate through technology, service, or regional expertise. The lack of overwhelming concentration also means that competitive advantage is less about scale alone and more about the ability to execute effectively across technical, commercial, and geographic dimensions.
Key Drivers of Market Momentum
Several interconnected forces are accelerating demand for custom LED lighting solutions and reshaping how companies compete. Understanding these drivers is essential for identifying where value will be created over the next several years.
Technological Innovation and Smart Integration. Advances in LED semiconductor performance, optical design, and control electronics are expanding the scope of what custom solutions can achieve. Manufacturers are increasingly integrating sensors, connectivity modules, and adaptive dimming capabilities into luminaires, enabling buildings and industrial facilities to respond dynamically to occupancy, daylight availability, and operational schedules. Smart integrated systems represent a substantial portion of current market activity, reflecting demand for solutions that combine illumination with energy management and data-enabled functionality. In parallel, developments in modular fixture architectures allow designers and engineers to specify tailored configurations without sacrificing production efficiency. Companies that have built expertise in combining high-performance light sources with application-specific optics and control logic are capturing premium positioning, particularly in sectors where lighting must meet both functional and aesthetic criteria. Recent product launches illustrate this trajectory: new offerings in architectural and commercial vehicle branding have demonstrated how customization can serve both design objectives and regulatory compliance simultaneously, integrating brand identity into lighting hardware while maintaining required safety standards.
Hazardous Location Lighting Market
Policy and Regulatory Environment. Energy efficiency mandates, building performance codes, and sustainability requirements continue to push end users toward lighting solutions that reduce consumption while enhancing functionality. Regulations that encourage or require upgrading legacy lighting infrastructure create a structural tailwind for custom solutions, especially when retrofitting existing spaces demands non-standard fixture dimensions, color temperatures, or integration with existing building management systems. At the same time, trade and supply chain policies are reshaping cost dynamics. The push to secure critical mineral supply chains has introduced new considerations for procurement teams, as import negotiations and potential tariffs could affect the cost of gallium, germanium, and derivative products used in LED optoelectronics. Organizations that proactively diversify sourcing, invest in alternative material strategies, or localize certain production steps may find themselves better insulated against regulatory shifts, while also gaining a narrative advantage with customers who prioritize supply chain transparency.
Demand-Side Shifts in Commercial, Architectural, and Specialty Applications. End-user expectations are evolving rapidly across multiple verticals. Commercial and retail operators are leveraging custom lighting to create distinctive brand environments, guide customer flow, and support merchandising strategies that rely on precise color rendering and accent lighting. Architectural and facade projects increasingly treat lighting as an integral design element, requiring bespoke solutions that align with structural forms, material textures, and nighttime visual impact. Industrial and specialty applications, including harsh-environment settings and mission-critical facilities such as data centers, are driving demand for ruggedized, certified solutions that meet stringent performance and reliability standards. High-end residential markets are also contributing, with homeowners and designers seeking personalized lighting schemes that complement interior aesthetics and wellness-oriented environments. Across these segments, the common thread is the need for solutions that cannot be satisfied by catalog products alone. Customers are willing to invest in tailored designs when those designs deliver measurable benefits in energy use, occupant experience, or operational reliability.
Supply Chain and Cost Structure Evolution. Cost pressures are reshaping how custom lighting solutions are developed and delivered. Raw material price increases, driven by chip and component costs as well as packaging material constraints, have prompted lead producers to adjust pricing across light sources and finished goods. Simultaneously, labor availability, logistics complexity, and the cost of maintaining quality across customized production runs add layers of complexity to margin management. In response, leading organizations are pursuing several strategies: forming strategic manufacturing partnerships to strengthen capacity and restore delivery performance for core product lines; leveraging scale in high-volume components while reserving customization for higher-margin added value; and adopting digital design-to-production workflows that reduce lead times and errors in bespoke orders. These adjustments are not merely defensive; they are repositioning companies to compete on reliability, speed, and the ability to scale customized output without eroding profitability.
The interaction of these drivers suggests that the market will reward participants who can integrate technical capability with supply chain resilience and customer-centric design processes. Innovation alone is insufficient if it cannot be delivered at the right cost and with consistent quality. Likewise, cost efficiency that sacrifices the ability to meet specialized requirements will limit growth in a market defined by customization.
Competitive Landscape and Leading Strategies
The competitive environment in the global custom LED lighting solution market is characterized by a mix of global scale players, specialty manufacturers, and regional experts. The absence of extreme concentration means that competitive advantage is earned through differentiated capabilities rather than market dominance alone. Several strategic positions have emerged among leading participants.
Some organizations compete primarily through breadth of customization and global reach. These firms offer extensive options for smart and architectural custom designs, serving commercial, industrial, and specialty applications across multiple regions. Their advantage lies in the ability to draw on large engineering teams, established manufacturing footprints, and broad customer relationships to address diverse project requirements. Sustainability-focused product initiatives, such as introducing lighting tubes made with significant post-consumer recycled content and packaging innovations, signal an effort to align customization with environmental expectations, a theme that resonates with commercial and institutional buyers.
Other participants focus on high-performance components and tailored systems for demanding applications. Companies with strong positions in custom LED components and lighting systems emphasize precision, reliability, and application-specific engineering, particularly for automotive, industrial, and specialty projects. These firms often serve as critical suppliers within larger value chains, where performance specifications and certification requirements create barriers to entry and reward deep technical expertise. In industrial and harsh-environment contexts, strategic manufacturing agreements are being used to reinforce capacity and improve delivery performance for core lines, highlighting the importance of supply reliability as a competitive differentiator.
A third group of competitors specializes in niche, high-value segments where customization intensity is particularly high. Manufacturers of bespoke architectural fixtures, custom LED light sheets, edgelighting solutions, and OEM-specific designs serve customers who require close collaboration on product definition and exact project specifications. In mission-critical environments such as data centers, certification achievements have become a valuable signal of capability, with first-to-market certifications demonstrating compliance with rigorous standards and opening doors to specialized procurements. Specialty providers also serve commercial vehicles, machine vision, and other applications where integration of branding, safety, and functional performance must be exact. These niche players often compete on responsiveness, design collaboration, and the ability to manage low-volume, high-mix production efficiently.
PW Consulting
The market structure appears poised for continued evolution along several axes. Consolidation is likely in segments where scale economies in component sourcing, certification, and distribution create advantages for larger entities, particularly as energy and compliance requirements raise the cost of participation. At the same time, fragmentation will persist in highly customized arenas where local design expertise, regional building practices, and project-specific relationships matter greatly. New entrants may emerge from adjacent technology domains, including smart building controls, advanced optics, and materials science, bringing fresh capabilities that reshape what custom lighting can deliver. The most successful organizations will be those that define a clear strategic identity: whether that means leading with global customization breadth, deep application-specific engineering, or specialized niche expertise, and then aligning manufacturing, sourcing, and service models to support that identity consistently.
Future Trends and Commercial Opportunities
Looking ahead to the 2026 through 2032 period, several trends are likely to shape the market and create distinct commercial opportunities.
Trend One: Smart, Connected Custom Lighting Becomes Standard in Commercial and Institutional Projects. As building owners and facility operators pursue energy savings, occupant experience improvements, and operational analytics, the integration of controls, sensors, and network connectivity into custom luminaires will shift from optional to expected. This trend creates opportunities for manufacturers that can offer customized fixtures with embedded intelligence and for service providers that can design, deploy, and maintain integrated lighting environments. Commercial and retail applications, in particular, stand to benefit from lighting systems that adapt to usage patterns and support broader building management goals. The opportunity lies not only in hardware but in the value-added services that surround it, including specification support, commissioning, and ongoing optimization.
Trend Two: Sustainability and Supply Chain Resilience Become Core Purchasing Criteria. Buyers are increasingly scrutinizing the environmental footprint of lighting products and the resilience of the supply chains behind them. Recycled content, reduced packaging waste, energy-efficient manufacturing, and transparent sourcing are expected to influence procurement decisions, especially in regions with stringent building codes and corporate sustainability commitments. At the same time, the critical minerals context encourages diversification of sourcing and, where feasible, localization of key production steps. Companies that can demonstrate credible sustainability credentials and robust supply continuity will be positioned to command preference in competitive bids, particularly for large-scale commercial and institutional projects where risk mitigation carries significant weight.
Trend Three: Specialty and Mission-Critical Applications Drive Premium Segments. Data centers, industrial facilities, harsh-environment settings, and other specialty applications will continue to generate demand for certified, high-reliability custom solutions. As digital infrastructure expands and industrial automation intensifies, the need for lighting that meets strict performance, safety, and certification requirements will grow. This trend favors suppliers that invest in compliance, testing, and application-specific engineering, and that can articulate clear value around uptime, safety, and operational consistency. The premium associated with these segments can support attractive margins, provided that manufacturers maintain disciplined quality and delivery performance.
Potential risks and uncertainties warrant attention. Trade policy developments could alter cost structures and sourcing feasibility, particularly for materials with concentrated supply. Raw material price volatility may compress margins if manufacturers cannot pass through costs or offset them through design efficiency and sourcing strategy. Additionally, the pace of adoption for smart features will vary by region and sector, meaning that investments in connectivity and controls may not yield uniform returns across all markets. Organizations should monitor these variables closely and maintain flexibility in their product roadmaps and supply arrangements.
Strategic Recommendations for Decision-Makers
For manufacturers and solution providers, the priority is to align product development with the highest-value customization opportunities while building resilience into sourcing and production. This means investing in modular platforms that enable rapid tailoring, strengthening partnerships for critical inputs, and pursuing certifications and sustainability credentials that differentiate offerings in competitive bids. Companies should also evaluate where strategic manufacturing agreements or regional production can improve delivery reliability for core lines, especially in segments where lead time and consistency are decisive factors.
For investors assessing opportunities in this space, the most attractive positions are likely to be found where technical differentiation, certification moats, and recurring demand intersect. Segments such as mission-critical data center lighting, specialty industrial applications, and smart integrated systems for commercial environments offer potential for sustained growth, but due diligence should examine supply chain exposure, certification status, and the scalability of customization processes. Diversification across geographies and application types can help mitigate concentration risk tied to any single market or policy environment.
For procurement leaders and end-user organizations, the focus should be on specifying solutions that balance performance, total cost of ownership, and supply continuity. Engaging early with manufacturers to define project requirements, favoring suppliers with demonstrated certification and sustainability track records, and incorporating flexibility for future upgrades can reduce risk and improve long-term outcomes. Given the range of available options and the rapid evolution of technology and regulation, access to detailed, up-to-date market intelligence is valuable for evaluating vendors, benchmarking specifications, and timing investments.
LED Lighting Market
For those seeking a comprehensive mapping of segments, regional dynamics, competitive benchmarks, and forward-looking scenarios, the full PW Consulting report on the worldwide custom LED lighting solution market provides granular analysis and customized recommendations to support strategic planning.
For detailed analysis of this topic, please visit the official page: Worldwide Custom LED Lighting Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Ocean Recycled Yarn Market: Why a 13.24% CAGR Reshapes the 2026 Outlook
By pmarketresearch, 2026-09-18
The Strategic Frontier: Navigating Growth in the Worldwide Ocean Recycled Yarn Market
Market Current State and Core Challenges
The global market for ocean recycled yarn has entered a phase of accelerated expansion, driven by a confluence of environmental imperatives, regulatory tailwinds, and shifting consumer expectations. From 2020 through 2025, the sector progressed from an emerging niche to a recognized component of the broader recycled textiles landscape, with total market revenue climbing from approximately USD 412 million to roughly USD 742 million. Looking ahead to 2032, the trajectory points toward a sustained upward curve, with revenue projections reaching nearly USD 1.77 billion. This expansion reflects a compound annual growth rate of 13.24 percent across the forecast window, underscoring a market that is no longer dependent solely on brand-led pilot programs but is embedding itself into mainstream textile sourcing strategies. The scale of this growth signals a structural shift rather than a temporary fashion cycle, as ocean-bound plastic recovery becomes an increasingly viable feedstock stream for high-volume fiber production.
Despite this momentum, the industry faces several defining challenges that will shape competitive outcomes over the next decade. First, feedstock availability and collection infrastructure remain fragmented. Ocean-bound plastics represent a specialized input category that competes with conventional post-consumer bottle streams. Securing consistent, certified volumes requires navigating coastal collection networks, informal waste economies, and complex logistics in regions where recycling infrastructure is still developing. The supply of marine-derived material is growing, but it remains a small fraction of total recycled polyester feedstock, which means producers must design robust sourcing strategies that do not overpromise on marine content while still delivering credible sustainability narratives.
Second, traceability and certification complexity introduce both operational and reputational risk. Brands and manufacturers increasingly demand verified provenance, not just recycled content claims. Materials must satisfy standards such as the Global Recycled Standard and Ocean Bound Plastic certification to substantiate marine sourcing and environmental additionality. Maintaining these certifications across multiple tiers of collection, processing, and yarn production adds cost and administrative burden, particularly for firms operating across jurisdictions with different auditing expectations. Failure to maintain credible traceability can quickly erode buyer trust, especially as regulatory scrutiny intensifies.
Third, pricing volatility and policy-driven cost shifts complicate margin planning. Recycled polyester pricing varies significantly by region and feedstock type, with certified ocean-bound material often commanding premiums due to traceability and the perceived environmental value of diverting marine waste. At the same time, trade policy changes can alter the economics of imported recycled feedstocks overnight, affecting input costs for yarn producers who rely on cross-border resin or flake flows. These dynamics create a tension between the demand for sustainable differentiation and the need for stable, competitive input pricing, forcing companies to make strategic choices about how much premium they can absorb or pass through to downstream partners.
Key Drivers of Market Change
Several interconnected drivers are accelerating the adoption and scaling of ocean recycled yarn, and each carries distinct implications for how companies position themselves in the market. Understanding these forces helps clarify where value is created and where execution risk concentrates.
Technological Innovation and Processing Breakthroughs
Advancements in recycling and fiber regeneration technologies are expanding what can be recovered and how cleanly it can be integrated into commercial yarn streams. One of the most consequential developments is the ability to handle more complex waste streams, such as nylon blends and elastic fibers, which historically limited the volume of fishing nets and marine textiles suitable for regeneration. Recent demonstration-scale initiatives have focused on separating elastic components from nylon blends so that the recovered material can be fed back into regeneration systems. This type of processing innovation matters because fishing nets and marine nylon waste are high-value feedstocks with strong brand appeal, but their heterogeneity has long been a bottleneck. As separation and purification techniques improve, producers can access larger volumes of marine-derived input without sacrificing fiber quality, which in turn strengthens the commercial case for ocean recycled yarns in performance and durability-sensitive applications.
Beyond feedstock flexibility, improvements in filament construction and yarn engineering are helping ocean-recycled fibers meet the functional requirements of diverse end uses. Producers are offering a wider range of denier and dtex options, enabling more precise matching to apparel, footwear, and technical textile specifications. This diversification reduces the perception that recycled yarns are limited to cost-driven or purely promotional applications, and instead positions them as viable inputs for items where strength, consistency, and finish matter. For buyers, this means ocean recycled yarns can be evaluated more on performance parity than on sustainability alone.
Policy and Regulatory Environment
Policy is increasingly shaping the economics of recycled fiber adoption, particularly in major markets where recycled-content mandates and packaging regulations create pull-through demand. In the European Union, the Packaging and Packaging Waste Regulation establishes mandatory recycled-content thresholds for PET, which indirectly reinforces demand for traceable recycled polyester across related applications, including textiles. Even when the regulation directly targets packaging, the ripple effect strengthens the broader recycled PET ecosystem and supports price discovery for certified recycled material. For yarn producers, this means regulatory momentum can lift baseline demand and improve the business case for investing in certified ocean-bound supply chains.
At the same time, trade policy adds a layer of complexity. Recent tariff measures on imported PET and recycled PET resin have increased costs for certain imported feedstocks used in yarn production. This highlights the importance of supply chain design: producers that can secure regional or nearshore feedstock, or that have contracts structured to manage policy risk, are better positioned to maintain cost stability. For multinational brands, regulatory divergence between markets means sourcing strategies must be flexible enough to account for differing requirements and cost structures without losing consistency in sustainability messaging.
Demand-Side Shifts in Consumer and Corporate Behavior
Demand for ocean recycled yarn is being reinforced by changes on both the consumer and corporate sides. Consumers are increasingly aware of marine plastic pollution, and this awareness translates into preference for products that communicate credible environmental action. At the same time, corporate buyers face pressure from investors, regulators, and supply chain partners to demonstrate measurable progress on circularity and plastic reduction. This dual pressure encourages brands to move beyond limited-edition recycled collections and integrate recycled yarns into broader assortments and staple products.
PW Consulting
Importantly, corporate demand is becoming more specification-driven. Buyers are asking not just for recycled content, but for documented marine sourcing, traceable chain of custody, and certifications that verify environmental additionality. This shift raises the bar for suppliers. Companies that can offer well-documented provenance and consistent quality are more likely to secure long-term partnerships, whereas those relying on vague sustainability claims risk losing credibility as buyer diligence deepens. The commercial opportunity lies in combining verifiable marine sourcing with reliable product performance, rather than treating ocean recycled yarn as a marketing shortcut.
Fleece Knitting Yarn Market
Supply Chain Reconfiguration and Cost Dynamics
The cost structure of ocean recycled yarn is shaped by feedstock premiums, regional pricing differences, and the logistics of collection and processing. Recycled PET pricing varies considerably across major markets, reflecting local collection capacity, demand intensity, and the availability of bottle-grade versus ocean-bound sources. Certified ocean-bound material typically carries an additional premium because of traceability requirements and the perceived value of marine plastic recovery. This premium can be justified when it is tied to clear sourcing stories and certification, but it also means that producers must manage the balance between ethical sourcing and competitive pricing.
Supply chain reconfiguration is also evident in the growing emphasis on traceability and marketplace models that connect collectors with processors and manufacturers. Some organizations are building platforms that aggregate traceable ocean-bound plastics, helping to standardize provenance and reduce fragmentation in sourcing. This approach can lower transaction costs for buyers who need multiple points of verification, while also giving collectors and processors a more predictable path to market. As these models mature, they may help reduce the cost of certified marine feedstock and make ocean recycled yarns more accessible to a wider range of textile applications.
Competitive Landscape and Leading Strategies
The competitive field in ocean recycled yarn is characterized by a mix of established recycled fiber producers, specialized marine-waste companies, and collaborative initiatives that connect collection networks with production capacity. Market concentration is moderate, with the top three firms accounting for roughly a third of revenue and the top five approaching two-fifths. This structure suggests room for both differentiated specialists and integrated players, but it also means that scale, traceability, and partnership networks are becoming increasingly important differentiators.
Unifi has built a recognizable position through REPREVE, including variants made from ocean-bound plastic waste alongside post-consumer bottles and textile waste. Its strategy leans on broad application coverage across apparel, footwear, and performance textiles, supported by sustainability commitments that extend into the next decade. Recent sustainability announcements have reinforced targets for recycled fibers, signaling continued investment in recycled content as a core element of the business. The strength of this approach lies in combining scale with recognizable branding and a wide customer base, which helps embed recycled yarns into mainstream procurement rather than limiting them to niche projects.
Aquafil has carved out a strong identity around ECONYL, regenerated nylon produced from recycled ocean fishing nets and other marine and nylon waste. Its applications span textiles, apparel, and flooring, giving it a diversified end-use base. A notable recent step has been the inauguration of a pilot-scale demonstration plant focused on separating elastic fibers from nylon blends, aimed at enabling further integration of such materials into the ECONYL regeneration system. This move reflects a strategy centered on unlocking harder-to-process marine feedstocks, which can broaden input availability and reinforce the technical leadership narrative that supports premium positioning.
Tide Ocean operates with a focused emphasis on 100 percent ocean-bound plastic recycled polyester yarn in various dtex norms for fashion, bags, shoes, home interiors, and industrial textiles. Its differentiation comes from purity of source story and the breadth of dtex options that allow closer matching to end-use requirements. By maintaining certifications such as GRS and Ocean Bound Plastic standards, the company seeks to make the marine sourcing claim credible and auditable. This positions it as a supplier for buyers who need a clear, verifiable ocean-plastic narrative rather than blended claims.
SEAQUAL Initiative, working with production partners such as Antex and Vica, provides SEAQUAL YARN, a recycled polyester filament yarn that typically combines marine plastic litter with post-consumer PET. Its model emphasizes collaboration across collection, certification, and production, which helps scale marine-based content while keeping it economically viable by blending with established recycled streams. This hybrid approach can make ocean-derived content more accessible to furnishing, apparel, and technical textile markets without requiring purely marine feedstock at full volume.
Other players illustrate different strategic angles. Bureo focuses on nylon yarn made from post-consumer recycled fishing nets, with a strong fit for performance apparel and outdoor gear. BIONIC develops high-performance yarns and fabrics from recovered marine and coastal plastic waste, including specialized constructions for textiles and polymers. Oceanworks operates a marketplace model for traceable ocean-bound plastics, supplying recycled polyester yarns and materials and emphasizing provenance across textiles and components. In Asia, companies such as Zhejiang Haili Environmental Technology and Everest Textile offer recycled polyester portfolios that include ocean-recycled variants for apparel and technical applications, with Everest Textile notably supplying major brands and showcasing traceable sustainable variants at industry events.
Together, these players reveal an evolving landscape shaped by three tendencies. First, differentiation is increasingly anchored in feedstock specificity, traceability, and certifications rather than recycled content alone. Second, scale players are expanding recycled portfolios to cover multiple applications, while specialized firms emphasize marine sourcing stories or niche performance constructions. Third, collaborative and marketplace models are emerging to reduce fragmentation in collection and verification. As the market matures, expect further consolidation among processors seeking scale and compliance efficiency, alongside continued entry by specialists who can unlock new feedstock pathways or serve high-value brand partnerships with strong provenance.
Future Trends and Commercial Opportunities
Over the next three to five years, three trends are likely to define the direction of the ocean recycled yarn market and create distinct opportunities for companies that prepare early.
The first trend is the gradual scaling of marine feedstock supply through better collection infrastructure and blend strategies. As demonstration plants and separation technologies prove out, more fishing nets, marine textiles, and coastal plastic waste can be routed into regeneration systems. This expansion will not happen overnight, but it should reduce the scarcity premium on certified ocean-bound material over time and allow broader application coverage. For producers, the opportunity lies in securing long-term collection partnerships and designing yarn lines that can accommodate variable marine input without compromising quality. For brands, the opportunity is to lock in multi-year supply commitments that stabilize sourcing and support credible sustainability roadmaps.
The second trend is tighter integration of traceability into commercial contracts. Buyers are increasingly treating certification and chain-of-custody documentation as baseline requirements rather than optional extras. This will favor companies that can provide clear, auditable provenance from collection points through yarn production. The commercial upside is stronger customer retention and the ability to command price premiums that are justified by verified environmental additionality. The risk is that any lapse in documentation or certification can quickly undermine buyer confidence, so traceability systems must be treated as core operational infrastructure rather than a marketing layer.
The third trend is regulatory and trade policy divergence across regions, which will continue to shape sourcing economics. Recycled-content mandates, packaging regulation, and import tariffs can each alter the cost and availability of feedstocks in different markets. Companies that build flexible sourcing networks, including regional or nearshore options and contracts that account for policy shifts, will be better positioned to manage cost volatility. At the same time, divergence can create arbitrage opportunities for firms that can move certified material to the markets where recycled-content requirements and buyer willingness to pay are strongest. The uncertainty here is that policy can change quickly, so strategies must be adaptive rather than locked into a single feedstock geography.
These trends point to a market that is moving from early differentiation toward operational maturity. The commercial winners are likely to be those that combine credible marine sourcing with consistent quality, scalable traceability, and resilient supply chain design. For investors and executives, the signal is that ocean recycled yarn is becoming a strategically relevant input category, but one where execution discipline matters as much as ambition.
Strategic Actions for Decision Makers
For manufacturers, the priority is to secure feedstock resilience and traceability capacity. This means developing multi-source collection relationships, investing in certification readiness, and evaluating whether blend strategies can balance marine content with cost stability. Companies should also assess whether their yarn specifications can meet performance requirements across target applications without relying on consumers to accept lower standards in exchange for sustainability claims.
Cotton Yarn Market
For investors, the opportunity is to differentiate between branded narratives and operational credibility. Companies with demonstrable certification practices, scalable feedstock access, and cost structures that can withstand policy and pricing volatility are better positioned for durable growth. Due diligence should focus on the reliability of marine sourcing, the robustness of traceability systems, and the ability to serve multiple end uses rather than a single promotional segment.
For procurement and brand teams, the key is to treat ocean recycled yarn as a sourcing category with both sustainability and performance dimensions. Define clear requirements for content claims, certifications, and quality thresholds before sourcing, and prioritize suppliers that can provide consistent documentation and application-appropriate variants. Long-term partnerships tend to yield better traceability outcomes and more stable pricing than transactional purchasing, especially as certified marine feedstock becomes more contested.
Given the pace of technological, regulatory, and competitive change, timely access to detailed segmentation data, pricing intelligence, and company-level assessments can make the difference between reactive sourcing and proactive strategy. For decision makers seeking deeper breakdowns and customized guidance, the full research report provides a more granular view of market splits, regional dynamics, and actionable recommendations.
For detailed analysis of this topic, please visit the official page: Worldwide Ocean Recycled Yarn Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
RIM Systems Market 2026: Beyond the 8.25% CAGR and the $3.3B Growth Trajectory
By pmarketresearch, 2026-09-18
Navigating the Regulatory Information Management Systems Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The global Regulatory Information Management (RIM) systems market has entered a phase of sustained expansion, reflecting the increasing complexity of product lifecycle governance across life sciences and medical technology sectors. From 2020 through 2025, the market demonstrated consistent year-over-year growth, reaching a baseline valuation of approximately $1.95 billion. Current projections indicate this trajectory will continue through the end of the decade, with the market expected to approach $2.14 billion by 2026 and ultimately surpassing $3.39 billion by 2032. This expansion is underpinned by a compound annual growth rate of 8.25 percent over the 2026 to 2032 forecast period, signaling a structural shift rather than a cyclical uptick. Organizations are no longer viewing RIM platforms as back-office compliance utilities but as strategic infrastructure that directly influences time-to-market, operational resilience, and cross-functional data integrity.
Despite this momentum, the market faces several structural challenges that are reshaping procurement decisions and vendor expectations. The first challenge lies in the fragmentation of regulatory data across silos. Many organizations still operate with disconnected systems for submissions, product registrations, change control, and archival management, creating bottlenecks during global market access initiatives. The second challenge centers on regulatory harmonization versus regional divergence. While international initiatives aim to streamline submission standards, the reality remains a patchwork of jurisdictional requirements that demand flexible, configurable workflows rather than rigid, one-size-fits-all architectures. The third challenge is the escalating expectation for real-time regulatory intelligence. Decision-makers increasingly require platforms that not only store compliance records but also monitor evolving requirements, assess impact, and trigger downstream processes without manual intervention. These tensions are forcing both buyers and vendors to reconsider what a modern RIM system must deliver.
The competitive field reflects these pressures. Market concentration remains moderate, with the top three providers collectively accounting for roughly 45 percent of revenue and the top five reaching slightly above 58 percent. This distribution suggests a market that is neither fully consolidated nor highly fragmented, leaving meaningful room for differentiation through specialization, integration depth, and technological maturity. For executives evaluating RIM investments, the immediate implication is clear: platform selection must align with organizational complexity, geographic footprint, and the urgency of automating regulatory execution rather than simply digitizing existing paperwork.
Key Drivers Reshaping the RIM Landscape
Several interconnected forces are accelerating adoption and shaping the next generation of RIM capabilities. Understanding these drivers is essential for executives who need to anticipate where investment will flow and which platform attributes will command premium positioning.
Technological Innovation and the Rise of Intelligent Workflows
The most visible driver is the integration of automation and intelligence into core regulatory processes. RIM platforms are evolving from documentation repositories into execution engines that support submission authoring, change impact assessment, and continuous regulatory monitoring. A clear example of this shift is the Spring 2026 launch of a regulatory execution engine embedded within a unified RIM platform, combining submission creation, AI-powered regulatory monitoring, and configurable impact workflows in a single environment. This development signals a broader industry movement toward systems that reduce manual handoffs and enable faster response to regulatory changes. For technology and operations leaders, the implication is that AI-enabled monitoring and configurable workflow engines are transitioning from differentiators to baseline expectations, particularly for organizations managing high volumes of product variations or frequent submission cycles.
Regulatory Complexity and Compliance Mandates
Policy and regulatory environments continue to exert direct pressure on RIM design and deployment. In FDA-regulated environments, platforms must support electronic records and signatures in alignment with 21 CFR Part 11, reinforcing the need for auditable, secure, and traceable data handling. At the same time, data security and privacy requirements have intensified. Regulations such as GDPR and CCPA remain central to RIM architecture, but the landscape is becoming more granular. By 2026, more than 20 U.S. states have enacted comprehensive data privacy laws, expanding the compliance surface for platforms that store sensitive regulatory information. This patchwork of privacy obligations is pushing vendors to build robust data governance controls, role-based access, and jurisdictional data handling logic directly into their systems. For regulated companies, these mandates are no longer peripheral IT concerns; they are core procurement criteria that affect vendor shortlists and implementation timelines.
Demand-Side Shifts in Life Sciences and MedTech Operations
On the demand side, organizations are under increasing pressure to accelerate product registrations, manage global submissions efficiently, and maintain compliance across heterogeneous jurisdictions. Pharmaceutical and biotechnology companies face heightened expectations for lifecycle transparency, while medical device and in vitro diagnostics manufacturers must navigate rapidly evolving technical and clinical documentation requirements. RIM platforms are increasingly selected based on their ability to centralize product data, registration records, submission artifacts, correspondence, and commitment tracking in a coherent workflow. The trend is especially pronounced among sponsors and service providers that must coordinate across internal teams, contract organizations, and multiple health authorities. The commercial logic is straightforward: centralized regulatory information reduces duplication, shortens review cycles, and improves the consistency of submissions across markets.
PW Consulting Information & Electronics Research Center
Cost Structures and Operational Efficiency
Cost dynamics are also influencing adoption patterns. Organizations are seeking to reduce the hidden costs of manual reconciliation, version control errors, and delayed submissions that can stall market entry or trigger compliance findings. Cloud-based deployment has become a significant enabler in this context, offering scalability, lower upfront infrastructure burden, and easier integration with adjacent quality, safety, and clinical systems. At the same time, on-premise deployments persist in settings where data residency, internal control requirements, or legacy integration constraints favor localized infrastructure. The broader cost story is not simply about license pricing; it is about total cost of ownership over the product lifecycle. Platforms that streamline regulatory execution, reduce rework, and provide reusable data structures are gaining preference because they translate compliance activity into measurable operational savings.
Competitive Landscape and Leading Strategies
The RIM market features a mix of purpose-built specialists, broad life sciences platform providers, and diversified compliance vendors. Their strategies reveal distinct approaches to capturing value in a market that rewards both domain depth and execution efficiency.
Supplier Relationship Management System Market
Several vendors have carved out strong positions by focusing on specific end markets or workflow strengths. Rimsys has built a unified RIM platform purpose-built for MedTech, emphasizing global registrations, submissions, product data, and change management within a single system. Its recent product launch illustrates a strategy centered on embedding regulatory execution, AI-powered monitoring, and configurable impact workflows directly into the platform, reducing the need for disjointed point solutions. RegDesk pursues a similar MedTech orientation with centralized regulatory data management, global compliance workflows, and regulatory intelligence, targeting organizations that need streamlined multi-jurisdiction execution. Kivo serves life sciences sponsors and service providers with document and process management, compliance workflows, and support for major authorities such as the FDA and EMA. These specialists compete by delivering focused functionality, faster implementation paths, and clear alignment with the daily realities of regulatory operations teams.
Broader platform players are taking a different approach, leveraging scale, ecosystem integration, and cloud architectures. Veeva Systems offers a cloud-based RIM capability within its Vault portfolio, covering submissions, registrations, publishing, and archival functions for life sciences. Its strategy benefits from a recognized cloud infrastructure and strong adoption across pharmaceutical and biotech organizations that already use Veeva for adjacent processes. IQVIA provides a cloud-based, AI-enabled platform for regulatory submissions, registrations, lifecycle management, and compliance across MedTech, IVD, and pharma, positioning its offering as part of a larger data and services ecosystem. ArisGlobal’s LifeSphere RIMS emphasizes end-to-end regulatory planning, tracking, registration management, and compliance with AI integration, appealing to organizations that want planning and execution tightly coupled. Ennov centralizes product, registration, submission, correspondence, and commitment data for regulatory operations and compliance, while Freyr Solutions offers RIM software as part of broader end-to-end regulatory services, including lifecycle management and compliance support. MasterControl rounds out the field with regulatory information management, product reviews, approvals, releases, and compliance tracking, targeting organizations that value integrated quality and regulatory workflows.
The market is evolving along two complementary paths. One is consolidation through ecosystem breadth, where larger vendors expand functionality and deepen integrations to reduce switching costs and capture more of the regulatory lifecycle. The other is differentiation through specialization, where focused vendors compete on ease of deployment, regulatory domain expertise, and workflow precision. A third dynamic is the continued entry of new players targeting underserved niches, particularly MedTech-specific workflows and AI-assisted monitoring. For buyers, this landscape creates both opportunity and risk. The upside is a growing set of options tailored to different operating models; the risk is platform sprawl if organizations select tools that do not integrate well with existing quality, safety, or content systems. The most effective strategies tend to prioritize data coherence, authorization and audit readiness, and the ability to scale across markets without rebuilding workflows from scratch.
Future Trends and Strategic Implications
Looking ahead three to five years, several trends are likely to define the next stage of RIM market evolution. The first is the deepening embedment of intelligence into regulatory execution. AI-assisted monitoring, automated impact assessment, and smarter submission preparation will become more common, enabling teams to respond faster to changing requirements and reduce manual review burdens. The commercial opportunity here lies in platforms that can translate regulatory signals into actionable workflow steps, not just alerts. Organizations that adopt these capabilities early may gain meaningful advantages in submission readiness and cycle time. The associated risk is over-reliance on automation without adequate validation, governance, and human oversight, especially in highly regulated contexts.
A second trend is the continued pressure toward centralized, interoperable regulatory data architectures. As product portfolios expand and market access strategies become more global, the ability to reuse product data, maintain consistent registration records, and connect regulatory information with quality and safety systems will increasingly separate high-performing organizations from those struggling with fragmentation. The opportunity is to treat regulatory data as a shared asset that supports cross-functional decisions, rather than as a compliance archive. The risk is that legacy system inertia and integration complexity slow transformation, leaving organizations with improved documentation but not improved execution.
A third trend is the tightening of data privacy and security expectations as a core selection criterion. With multiple U.S. state privacy laws in effect and international obligations still evolving, RIM platforms will be evaluated not only on regulatory functionality but also on data handling maturity, access controls, and auditability. Vendors that can demonstrate robust privacy-by-design architectures and clear jurisdictional controls will be better positioned in enterprise deals. The uncertainty lies in how quickly requirements will continue to multiply and whether standardization efforts will ease or complicate compliance burdens.
Actionable Guidance for Decision-Makers
For regulated product manufacturers, the priority should be to assess RIM platforms against the full regulatory execution lifecycle rather than isolated compliance tasks. Selection criteria ought to include submission authoring efficiency, registration and change management coherence, integration with quality and safety systems, and the ability to configure workflows for multiple jurisdictions without excessive customization. Organizations that treat RIM as a strategic execution layer typically see better alignment between regulatory planning and operational delivery.
For investors and strategic partners, the market signals value in vendors that combine domain focus with demonstrable automation benefits and credible data governance. Differentiation is increasingly tied to workflow intelligence, deployment flexibility, and the ability to serve complex MedTech or multi-entity life sciences environments. Due diligence should look beyond feature lists to adoption patterns, implementation outcomes, and the vendor’s capacity to sustain innovation as privacy and regulatory expectations continue to evolve.
Legal Risk And Compliance Solution Market
For procurement and operations leaders, the most practical step is to map current regulatory pain points—such as duplicate data entry, slow impact assessment, or fragmented submission records—against platform capabilities that directly address those bottlenecks. Cloud-based deployment may offer faster time-to-value in many scenarios, but the final decision should reflect data residency needs, internal control requirements, and the organization’s integration roadmap. Given the pace of change and the widening range of vendor strategies, timely access to detailed segmentation data, vendor benchmarking, and tailored implementation considerations can materially improve investment outcomes. Comprehensive research providing deeper segment-level insight and customized analysis is available for teams that need to move from strategic direction to execution planning with greater confidence.
For detailed analysis of this topic, please visit the official page: Regulatory Information Management (RIM) Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Vacuum Isolators Market: Why 5.5% CAGR & $800M Scale Signal Pharma-Driven Shift
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Vacuum Isolators Market
Market Snapshot and Core Challenges
The vacuum isolators market has established itself as a critical infrastructure segment within controlled environment manufacturing, valued at approximately $550.0 million in 2025. Historical data from 2020 to 2025 reveals a compound annual growth rate (CAGR) of 5.5 percent, signaling steady expansion driven by the increasing demand for containment solutions across high-precision industries. Looking ahead to the forecast period of 2026 through 2032, the market trajectory remains positive, with projections indicating a potential valuation of $800.07 million by 2032. This growth reflects a maturation phase where volume increases are increasingly tied to technological sophistication rather than purely capacity expansion.
Regional dynamics show a clear dominance by established markets, with North America and Europe historically holding the largest shares, while Asia Pacific represents a rapidly growing volume center. However, the revenue concentration within the market is significant. The top three players account for 45.5 percent of the market, and the top five entities control 62.8 percent. This high level of concentration suggests that barriers to entry remain steep, largely due to the capital intensity and regulatory complexity associated with pharmaceutical-grade and semiconductor-grade isolation systems.
Three structural challenges define the current market environment. First, the high capital expenditure required for deployment acts as a friction point for adoption. Pharmaceutical-grade isolators often involve initial investments exceeding $150,000 per system, with validation processes adding 20 to 30 percent to total ownership costs. This cost structure limits accessibility for smaller enterprises and slows the rate of incremental capacity addition in mature markets. Second, the regulatory framework is evolving from static compliance to dynamic quality management. Recent updates, such as the FDA Quality Management System Regulation (QMSR) effective from February 2026, update quality system requirements relevant to device manufacturing equipment. These shifts require manufacturers to maintain agility in their design and validation protocols, increasing the operational burden on equipment providers. Third, the industry faces a tension between standardization and customization. While modular custom systems offer flexibility, the majority of revenue is still driven by stainless steel isolators, which are often standard-heavy but require significant integration efforts for specific vacuum processes. Balancing the efficiency of catalog products with the specific needs of potent compound handling or aseptic vacuum drying remains a persistent engineering and commercial challenge.
Key Drivers of Market Change
Technological innovation is reshaping the functional boundaries of vacuum isolators. The shift toward robotic gloveless systems represents a notable evolution in operational efficiency. Insights from the industry have highlighted the economic advantages of robotic gloveless pharmaceutical isolators over traditional manual systems. These systems reduce operator exposure to potent compounds while improving throughput consistency. By removing the human element from the critical path of manipulation within the isolator, manufacturers can achieve higher sterility assurance levels and lower contamination risks. This technological leap is not merely a feature improvement; it fundamentally alters the total cost of ownership calculation by reducing validation complexity related to operator intervention and enhancing long-duration process stability.
The regulatory environment continues to be a primary catalyst for demand. Compliance requirements such as EU GMP Annex 1 mandate that closed isolator systems correspond to a minimum Grade D background environment for sterile medicinal product manufacturing. This regulation reinforces the necessity of high-integrity isolators as the baseline standard rather than an optional upgrade. Furthermore, the alignment of global quality standards, exemplified by the FDA QMSR update, creates a more harmonized but stricter landscape for equipment qualification. Manufacturers operating in or exporting to regulated markets must ensure their isolator solutions can demonstrate robust traceability and quality management integration. This regulatory pressure drives demand for systems that are not only functionally capable but also documentation-ready, favoring suppliers with established quality infrastructure.
Demand-side dynamics are being influenced by the expanding application scope beyond traditional pharmaceutical manufacturing. While pharmaceutical production remains the dominant application, the semiconductor and electronics sector represents a substantial portion of market demand, driven by the need for contamination-free processing environments. The growth in battery and energy storage applications, though currently smaller in revenue contribution, indicates a diversification trend where vacuum isolation is required for handling sensitive materials. Additionally, healthcare capital expenditure trends provide context for the demand environment. Average annual capital expenditure on health across OECD countries remained around 0.6 percent of GDP between 2021 and 2024. While this figure suggests stable public investment, the focus on efficiency and advanced manufacturing capabilities within healthcare and pharmaceutical production pushes end-users toward technologies that offer long-term operational savings, supporting the adoption of advanced isolators despite high upfront costs.
Supply chain and cost structures present a mixed dynamic. The concentration of market revenue among a few key players indicates a mature supply base with strong technical capabilities, but it also implies that pricing power remains with incumbents. The high initial investment threshold creates a procurement cycle that is deliberate and long-term. However, the emergence of modular custom systems suggests a supply-side response to the need for flexibility. These systems aim to reduce lead times and allow for reconfiguration, addressing the cost challenge by potentially lowering integration expenses. The interplay between standardized stainless steel solutions, which offer durability and broad acceptance, and modular or polymer-based alternatives, which offer cost and flexibility benefits, is a key area where supply chain strategies are evolving. Suppliers that can offer a hybrid approach—leveraging the reliability of standard materials while providing modular adaptability—are better positioned to navigate the varying cost sensitivities of different customer segments.
Competitive Landscape and Leading Strategies
The competitive landscape is characterized by a mix of established multinational providers and specialized regional manufacturers. The market is anchored by companies with deep expertise in pharmaceutical containment and aseptic processing. Swiss provider SKAN AG stands out as a leading provider of pharmaceutical isolators with advanced containment and aseptic solutions, offering customized vacuum-compatible systems. Their positioning emphasizes high-end customization and integration, appealing to users with complex process requirements. Similarly, Swedish firm Getinge AB offers isolator systems such as ISOFLEX and ISOTEST for aseptic processing, supporting integrated vacuum operations. Their strategy leverages a broad portfolio of medical and pharmaceutical equipment, allowing for cross-selling and integration within larger facility setups.
Italian manufacturers play a significant role in the market structure. Comecer S.p.A. provides isolators and gloveboxes with integration for vacuum ovens, tray dryers, and potent API processing, focusing on the pharmaceutical manufacturing value chain. Tema Sinergie specializes in pharmaceutical isolators including aseptic and containment systems suitable for vacuum-integrated processes, targeting both production and quality control environments. These companies differentiate through application-specific expertise and regional proximity to European manufacturing hubs, allowing for responsive service and compliance alignment with EU regulations.
In the Asian market, Zhejiang Tailin Bioengineering Co., Ltd. offers vacuum isolators and containment isolators for pharmaceutical dispensing, drying, and filling of potent compounds. Their presence highlights the growing manufacturing capability in China, where cost competitiveness and expanding domestic demand drive growth. Schematic Engineering Industries in India manufactures integrated Vacuum Tray Dryer isolators in rigid and flexible barrier configurations, addressing specific drying applications with localized engineering solutions. These regional players contribute to market diversity by offering alternatives that may align better with specific cost structures or regional regulatory contexts.
Western specialized providers also maintain strong positions. Extract Technology Ltd. in the United Kingdom designs and manufactures containment and aseptic isolators, including systems compatible with vacuum processes for potent compounds and sterility testing. Their focus on containment and sterility underscores the importance of safety and validation in high-risk applications. In Spain, Azbil Telstar develops isolator technologies including dual-mode systems and vacuum-related solutions for sterile and containment applications. A notable recent development is the introduction of a new dual mode isolator system by Azbil Telstar, designed for enhanced flexibility in pharmaceutical processing. This product launch illustrates a strategic move toward versatility, allowing manufacturers to switch between operational modes to accommodate varying batch sizes or process requirements without changing equipment.
Optical Isolators Market
The competitive dynamics point to a trend of differentiation through functionality and integration. The market concentration, with the top three players holding 45.5 percent and the top five holding 62.8 percent, indicates that scale and brand reputation provide significant advantages. However, the rapid pace of innovation, such as the focus on robotic gloveless systems and dual-mode flexibility, suggests that competitive advantage is increasingly tied to technological agility. New entrants or smaller players may find opportunities by targeting niche applications, offering rapid customization, or focusing on specific regions where local service and support are critical differentiators. The evolution of the landscape is likely to see further consolidation as larger players acquire specialized technologies to broaden their portfolios, while smaller firms may need to specialize deeply to remain viable. The integration of vacuum compatibility into broader aseptic and containment solutions is becoming a standard expectation, pushing competitors to demonstrate seamless integration capabilities rather than standalone isolator performance.
Future Trends and Commercial Opportunities
Over the next three to five years, the vacuum isolators market is poised to undergo significant transformation driven by the convergence of automation, regulatory stringency, and application diversification. One key trend is the accelerated adoption of automation and robotic integration within isolator systems. As the economic case for robotic gloveless systems becomes more documented, the market will likely see a shift in procurement preferences, particularly among manufacturers handling highly potent compounds where operator safety and contamination control are paramount. This trend creates commercial opportunities for technology providers that can integrate robotics seamlessly with existing isolator architectures, as well as for service companies that can support the maintenance and validation of automated systems. Manufacturers that invest early in robotic-compatible designs may capture premium segments of the market.
A second trend is the increasing importance of modularity and flexibility in system design. The success of dual-mode systems and modular custom systems reflects a growing demand for equipment that can adapt to changing production needs without significant capital replacement. Future isolators will likely be expected to offer easier reconfiguration, faster changeover times, and interoperability with a wider range of peripheral equipment such as vacuum ovens and tray dryers. This trend opens opportunities for suppliers to develop platform-based solutions that allow customers to scale capabilities incrementally. The commercial advantage will lie in offering systems that reduce the total cost of ownership through adaptability, rather than competing solely on initial hardware price.
A third trend involves the expansion of application boundaries and regional growth. While pharmaceutical manufacturing remains the core driver, the substantial demand from semiconductor and electronics, combined with emerging interest in battery and energy storage, suggests that isolator technology will become relevant in a broader set of high-tech manufacturing environments. Asia Pacific, already a significant revenue contributor, is expected to continue its growth trajectory as manufacturing capacity expands and regulatory standards converge with global best practices. Commercial opportunities in these regions may focus on localized support, cost-optimized designs, and solutions tailored to specific regional regulatory requirements. However, risks remain. The potential for economic fluctuations affecting capital expenditure cycles could dampen demand, particularly in capital-intensive segments. Additionally, the high cost of validation and compliance could create bottlenecks if regulatory scrutiny intensifies further. Companies must also navigate the risk of technological disruption, where new containment paradigms could challenge the dominance of traditional vacuum isolator designs. Success in this environment will require a balance of innovation, cost discipline, and rigorous adherence to evolving quality standards.
Strategic Actions for Decision Makers
Manufacturers and equipment providers should prioritize investment in robotic and automated capabilities to align with the shifting demand toward safer and more efficient processing. Developing or integrating robotic gloveless solutions can provide a competitive edge, particularly in pharmaceutical segments where potent compound handling drives procurement criteria. Additionally, companies should explore modular design strategies that enhance system flexibility, allowing customers to adapt to varying batch sizes and process requirements. Offering dual-mode or reconfigurable systems can differentiate offerings in a market where customization is highly valued. Strengthening validation support and documentation readiness will also be critical, as regulatory frameworks continue to emphasize traceability and quality management integration.
For investors, the market presents opportunities in segments that combine technological advancement with scalable application potential. The concentration of market share among top players suggests that established firms with strong quality infrastructure offer stability, while innovation in automation and modularity may create value in specialized technology providers. Monitoring developments in semiconductor and battery applications, as well as regional growth in Asia Pacific, can inform investment in companies positioned to capture diversification trends. Assessing the total cost of ownership dynamics and the impact of regulatory changes on procurement cycles will be essential for evaluating long-term potential.
PW Consulting Information & Electronics Research Center
Procurement teams and end-users should focus on holistic evaluation criteria that extend beyond initial hardware costs. Given the high validation and integration expenses, assessing the total cost of ownership, including service support, validation assistance, and adaptability over the system lifecycle, is crucial. Engaging with suppliers that offer robust documentation and compliance alignment with regulations such as EU GMP Annex 1 and FDA QMSR can reduce project risk. Evaluating modular and dual-mode options may provide future-proofing benefits, allowing facilities to respond to changing production needs without major capital reinvestment. Detailed segmentation data and customized recommendations can further refine procurement strategies, and accessing comprehensive market intelligence will support informed decision-making in this evolving landscape.
Digital Isolators Market
For detailed analysis of this topic, please visit the official page: Vacuum Isolators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com