

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Vacuum Isolators Market: Why 5.5% CAGR & $800M Scale Signal Pharma-Driven Shift

Strategic Trends and Commercial Opportunities in the Vacuum Isolators Market
Market Snapshot and Core Challenges
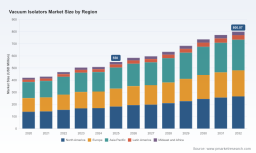
The vacuum isolators market has established itself as a critical infrastructure segment within controlled environment manufacturing, valued at approximately $550.0 million in 2025. Historical data from 2020 to 2025 reveals a compound annual growth rate (CAGR) of 5.5 percent, signaling steady expansion driven by the increasing demand for containment solutions across high-precision industries. Looking ahead to the forecast period of 2026 through 2032, the market trajectory remains positive, with projections indicating a potential valuation of $800.07 million by 2032. This growth reflects a maturation phase where volume increases are increasingly tied to technological sophistication rather than purely capacity expansion.
Regional dynamics show a clear dominance by established markets, with North America and Europe historically holding the largest shares, while Asia Pacific represents a rapidly growing volume center. However, the revenue concentration within the market is significant. The top three players account for 45.5 percent of the market, and the top five entities control 62.8 percent. This high level of concentration suggests that barriers to entry remain steep, largely due to the capital intensity and regulatory complexity associated with pharmaceutical-grade and semiconductor-grade isolation systems.
Three structural challenges define the current market environment. First, the high capital expenditure required for deployment acts as a friction point for adoption. Pharmaceutical-grade isolators often involve initial investments exceeding $150,000 per system, with validation processes adding 20 to 30 percent to total ownership costs. This cost structure limits accessibility for smaller enterprises and slows the rate of incremental capacity addition in mature markets. Second, the regulatory framework is evolving from static compliance to dynamic quality management. Recent updates, such as the FDA Quality Management System Regulation (QMSR) effective from February 2026, update quality system requirements relevant to device manufacturing equipment. These shifts require manufacturers to maintain agility in their design and validation protocols, increasing the operational burden on equipment providers. Third, the industry faces a tension between standardization and customization. While modular custom systems offer flexibility, the majority of revenue is still driven by stainless steel isolators, which are often standard-heavy but require significant integration efforts for specific vacuum processes. Balancing the efficiency of catalog products with the specific needs of potent compound handling or aseptic vacuum drying remains a persistent engineering and commercial challenge.
Key Drivers of Market Change
Technological innovation is reshaping the functional boundaries of vacuum isolators. The shift toward robotic gloveless systems represents a notable evolution in operational efficiency. Insights from the industry have highlighted the economic advantages of robotic gloveless pharmaceutical isolators over traditional manual systems. These systems reduce operator exposure to potent compounds while improving throughput consistency. By removing the human element from the critical path of manipulation within the isolator, manufacturers can achieve higher sterility assurance levels and lower contamination risks. This technological leap is not merely a feature improvement; it fundamentally alters the total cost of ownership calculation by reducing validation complexity related to operator intervention and enhancing long-duration process stability.
The regulatory environment continues to be a primary catalyst for demand. Compliance requirements such as EU GMP Annex 1 mandate that closed isolator systems correspond to a minimum Grade D background environment for sterile medicinal product manufacturing. This regulation reinforces the necessity of high-integrity isolators as the baseline standard rather than an optional upgrade. Furthermore, the alignment of global quality standards, exemplified by the FDA QMSR update, creates a more harmonized but stricter landscape for equipment qualification. Manufacturers operating in or exporting to regulated markets must ensure their isolator solutions can demonstrate robust traceability and quality management integration. This regulatory pressure drives demand for systems that are not only functionally capable but also documentation-ready, favoring suppliers with established quality infrastructure.
Demand-side dynamics are being influenced by the expanding application scope beyond traditional pharmaceutical manufacturing. While pharmaceutical production remains the dominant application, the semiconductor and electronics sector represents a substantial portion of market demand, driven by the need for contamination-free processing environments. The growth in battery and energy storage applications, though currently smaller in revenue contribution, indicates a diversification trend where vacuum isolation is required for handling sensitive materials. Additionally, healthcare capital expenditure trends provide context for the demand environment. Average annual capital expenditure on health across OECD countries remained around 0.6 percent of GDP between 2021 and 2024. While this figure suggests stable public investment, the focus on efficiency and advanced manufacturing capabilities within healthcare and pharmaceutical production pushes end-users toward technologies that offer long-term operational savings, supporting the adoption of advanced isolators despite high upfront costs.
Supply chain and cost structures present a mixed dynamic. The concentration of market revenue among a few key players indicates a mature supply base with strong technical capabilities, but it also implies that pricing power remains with incumbents. The high initial investment threshold creates a procurement cycle that is deliberate and long-term. However, the emergence of modular custom systems suggests a supply-side response to the need for flexibility. These systems aim to reduce lead times and allow for reconfiguration, addressing the cost challenge by potentially lowering integration expenses. The interplay between standardized stainless steel solutions, which offer durability and broad acceptance, and modular or polymer-based alternatives, which offer cost and flexibility benefits, is a key area where supply chain strategies are evolving. Suppliers that can offer a hybrid approach—leveraging the reliability of standard materials while providing modular adaptability—are better positioned to navigate the varying cost sensitivities of different customer segments.
Competitive Landscape and Leading Strategies
The competitive landscape is characterized by a mix of established multinational providers and specialized regional manufacturers. The market is anchored by companies with deep expertise in pharmaceutical containment and aseptic processing. Swiss provider SKAN AG stands out as a leading provider of pharmaceutical isolators with advanced containment and aseptic solutions, offering customized vacuum-compatible systems. Their positioning emphasizes high-end customization and integration, appealing to users with complex process requirements. Similarly, Swedish firm Getinge AB offers isolator systems such as ISOFLEX and ISOTEST for aseptic processing, supporting integrated vacuum operations. Their strategy leverages a broad portfolio of medical and pharmaceutical equipment, allowing for cross-selling and integration within larger facility setups.
Italian manufacturers play a significant role in the market structure. Comecer S.p.A. provides isolators and gloveboxes with integration for vacuum ovens, tray dryers, and potent API processing, focusing on the pharmaceutical manufacturing value chain. Tema Sinergie specializes in pharmaceutical isolators including aseptic and containment systems suitable for vacuum-integrated processes, targeting both production and quality control environments. These companies differentiate through application-specific expertise and regional proximity to European manufacturing hubs, allowing for responsive service and compliance alignment with EU regulations.
In the Asian market, Zhejiang Tailin Bioengineering Co., Ltd. offers vacuum isolators and containment isolators for pharmaceutical dispensing, drying, and filling of potent compounds. Their presence highlights the growing manufacturing capability in China, where cost competitiveness and expanding domestic demand drive growth. Schematic Engineering Industries in India manufactures integrated Vacuum Tray Dryer isolators in rigid and flexible barrier configurations, addressing specific drying applications with localized engineering solutions. These regional players contribute to market diversity by offering alternatives that may align better with specific cost structures or regional regulatory contexts.
Western specialized providers also maintain strong positions. Extract Technology Ltd. in the United Kingdom designs and manufactures containment and aseptic isolators, including systems compatible with vacuum processes for potent compounds and sterility testing. Their focus on containment and sterility underscores the importance of safety and validation in high-risk applications. In Spain, Azbil Telstar develops isolator technologies including dual-mode systems and vacuum-related solutions for sterile and containment applications. A notable recent development is the introduction of a new dual mode isolator system by Azbil Telstar, designed for enhanced flexibility in pharmaceutical processing. This product launch illustrates a strategic move toward versatility, allowing manufacturers to switch between operational modes to accommodate varying batch sizes or process requirements without changing equipment.
Optical Isolators Market
The competitive dynamics point to a trend of differentiation through functionality and integration. The market concentration, with the top three players holding 45.5 percent and the top five holding 62.8 percent, indicates that scale and brand reputation provide significant advantages. However, the rapid pace of innovation, such as the focus on robotic gloveless systems and dual-mode flexibility, suggests that competitive advantage is increasingly tied to technological agility. New entrants or smaller players may find opportunities by targeting niche applications, offering rapid customization, or focusing on specific regions where local service and support are critical differentiators. The evolution of the landscape is likely to see further consolidation as larger players acquire specialized technologies to broaden their portfolios, while smaller firms may need to specialize deeply to remain viable. The integration of vacuum compatibility into broader aseptic and containment solutions is becoming a standard expectation, pushing competitors to demonstrate seamless integration capabilities rather than standalone isolator performance.
Future Trends and Commercial Opportunities
Over the next three to five years, the vacuum isolators market is poised to undergo significant transformation driven by the convergence of automation, regulatory stringency, and application diversification. One key trend is the accelerated adoption of automation and robotic integration within isolator systems. As the economic case for robotic gloveless systems becomes more documented, the market will likely see a shift in procurement preferences, particularly among manufacturers handling highly potent compounds where operator safety and contamination control are paramount. This trend creates commercial opportunities for technology providers that can integrate robotics seamlessly with existing isolator architectures, as well as for service companies that can support the maintenance and validation of automated systems. Manufacturers that invest early in robotic-compatible designs may capture premium segments of the market.
A second trend is the increasing importance of modularity and flexibility in system design. The success of dual-mode systems and modular custom systems reflects a growing demand for equipment that can adapt to changing production needs without significant capital replacement. Future isolators will likely be expected to offer easier reconfiguration, faster changeover times, and interoperability with a wider range of peripheral equipment such as vacuum ovens and tray dryers. This trend opens opportunities for suppliers to develop platform-based solutions that allow customers to scale capabilities incrementally. The commercial advantage will lie in offering systems that reduce the total cost of ownership through adaptability, rather than competing solely on initial hardware price.
A third trend involves the expansion of application boundaries and regional growth. While pharmaceutical manufacturing remains the core driver, the substantial demand from semiconductor and electronics, combined with emerging interest in battery and energy storage, suggests that isolator technology will become relevant in a broader set of high-tech manufacturing environments. Asia Pacific, already a significant revenue contributor, is expected to continue its growth trajectory as manufacturing capacity expands and regulatory standards converge with global best practices. Commercial opportunities in these regions may focus on localized support, cost-optimized designs, and solutions tailored to specific regional regulatory requirements. However, risks remain. The potential for economic fluctuations affecting capital expenditure cycles could dampen demand, particularly in capital-intensive segments. Additionally, the high cost of validation and compliance could create bottlenecks if regulatory scrutiny intensifies further. Companies must also navigate the risk of technological disruption, where new containment paradigms could challenge the dominance of traditional vacuum isolator designs. Success in this environment will require a balance of innovation, cost discipline, and rigorous adherence to evolving quality standards.
Strategic Actions for Decision Makers
Manufacturers and equipment providers should prioritize investment in robotic and automated capabilities to align with the shifting demand toward safer and more efficient processing. Developing or integrating robotic gloveless solutions can provide a competitive edge, particularly in pharmaceutical segments where potent compound handling drives procurement criteria. Additionally, companies should explore modular design strategies that enhance system flexibility, allowing customers to adapt to varying batch sizes and process requirements. Offering dual-mode or reconfigurable systems can differentiate offerings in a market where customization is highly valued. Strengthening validation support and documentation readiness will also be critical, as regulatory frameworks continue to emphasize traceability and quality management integration.
For investors, the market presents opportunities in segments that combine technological advancement with scalable application potential. The concentration of market share among top players suggests that established firms with strong quality infrastructure offer stability, while innovation in automation and modularity may create value in specialized technology providers. Monitoring developments in semiconductor and battery applications, as well as regional growth in Asia Pacific, can inform investment in companies positioned to capture diversification trends. Assessing the total cost of ownership dynamics and the impact of regulatory changes on procurement cycles will be essential for evaluating long-term potential.
PW Consulting Information & Electronics Research Center
Procurement teams and end-users should focus on holistic evaluation criteria that extend beyond initial hardware costs. Given the high validation and integration expenses, assessing the total cost of ownership, including service support, validation assistance, and adaptability over the system lifecycle, is crucial. Engaging with suppliers that offer robust documentation and compliance alignment with regulations such as EU GMP Annex 1 and FDA QMSR can reduce project risk. Evaluating modular and dual-mode options may provide future-proofing benefits, allowing facilities to respond to changing production needs without major capital reinvestment. Detailed segmentation data and customized recommendations can further refine procurement strategies, and accessing comprehensive market intelligence will support informed decision-making in this evolving landscape.
Digital Isolators Market
For detailed analysis of this topic, please visit the official page: Vacuum Isolators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com