

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
RIM Systems Market 2026: Beyond the 8.25% CAGR and the $3.3B Growth Trajectory

Navigating the Regulatory Information Management Systems Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
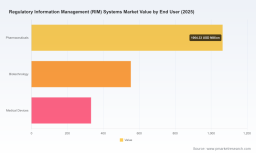
The global Regulatory Information Management (RIM) systems market has entered a phase of sustained expansion, reflecting the increasing complexity of product lifecycle governance across life sciences and medical technology sectors. From 2020 through 2025, the market demonstrated consistent year-over-year growth, reaching a baseline valuation of approximately $1.95 billion. Current projections indicate this trajectory will continue through the end of the decade, with the market expected to approach $2.14 billion by 2026 and ultimately surpassing $3.39 billion by 2032. This expansion is underpinned by a compound annual growth rate of 8.25 percent over the 2026 to 2032 forecast period, signaling a structural shift rather than a cyclical uptick. Organizations are no longer viewing RIM platforms as back-office compliance utilities but as strategic infrastructure that directly influences time-to-market, operational resilience, and cross-functional data integrity.
Despite this momentum, the market faces several structural challenges that are reshaping procurement decisions and vendor expectations. The first challenge lies in the fragmentation of regulatory data across silos. Many organizations still operate with disconnected systems for submissions, product registrations, change control, and archival management, creating bottlenecks during global market access initiatives. The second challenge centers on regulatory harmonization versus regional divergence. While international initiatives aim to streamline submission standards, the reality remains a patchwork of jurisdictional requirements that demand flexible, configurable workflows rather than rigid, one-size-fits-all architectures. The third challenge is the escalating expectation for real-time regulatory intelligence. Decision-makers increasingly require platforms that not only store compliance records but also monitor evolving requirements, assess impact, and trigger downstream processes without manual intervention. These tensions are forcing both buyers and vendors to reconsider what a modern RIM system must deliver.
The competitive field reflects these pressures. Market concentration remains moderate, with the top three providers collectively accounting for roughly 45 percent of revenue and the top five reaching slightly above 58 percent. This distribution suggests a market that is neither fully consolidated nor highly fragmented, leaving meaningful room for differentiation through specialization, integration depth, and technological maturity. For executives evaluating RIM investments, the immediate implication is clear: platform selection must align with organizational complexity, geographic footprint, and the urgency of automating regulatory execution rather than simply digitizing existing paperwork.
Key Drivers Reshaping the RIM Landscape
Several interconnected forces are accelerating adoption and shaping the next generation of RIM capabilities. Understanding these drivers is essential for executives who need to anticipate where investment will flow and which platform attributes will command premium positioning.
Technological Innovation and the Rise of Intelligent Workflows
The most visible driver is the integration of automation and intelligence into core regulatory processes. RIM platforms are evolving from documentation repositories into execution engines that support submission authoring, change impact assessment, and continuous regulatory monitoring. A clear example of this shift is the Spring 2026 launch of a regulatory execution engine embedded within a unified RIM platform, combining submission creation, AI-powered regulatory monitoring, and configurable impact workflows in a single environment. This development signals a broader industry movement toward systems that reduce manual handoffs and enable faster response to regulatory changes. For technology and operations leaders, the implication is that AI-enabled monitoring and configurable workflow engines are transitioning from differentiators to baseline expectations, particularly for organizations managing high volumes of product variations or frequent submission cycles.
Regulatory Complexity and Compliance Mandates
Policy and regulatory environments continue to exert direct pressure on RIM design and deployment. In FDA-regulated environments, platforms must support electronic records and signatures in alignment with 21 CFR Part 11, reinforcing the need for auditable, secure, and traceable data handling. At the same time, data security and privacy requirements have intensified. Regulations such as GDPR and CCPA remain central to RIM architecture, but the landscape is becoming more granular. By 2026, more than 20 U.S. states have enacted comprehensive data privacy laws, expanding the compliance surface for platforms that store sensitive regulatory information. This patchwork of privacy obligations is pushing vendors to build robust data governance controls, role-based access, and jurisdictional data handling logic directly into their systems. For regulated companies, these mandates are no longer peripheral IT concerns; they are core procurement criteria that affect vendor shortlists and implementation timelines.
Demand-Side Shifts in Life Sciences and MedTech Operations
On the demand side, organizations are under increasing pressure to accelerate product registrations, manage global submissions efficiently, and maintain compliance across heterogeneous jurisdictions. Pharmaceutical and biotechnology companies face heightened expectations for lifecycle transparency, while medical device and in vitro diagnostics manufacturers must navigate rapidly evolving technical and clinical documentation requirements. RIM platforms are increasingly selected based on their ability to centralize product data, registration records, submission artifacts, correspondence, and commitment tracking in a coherent workflow. The trend is especially pronounced among sponsors and service providers that must coordinate across internal teams, contract organizations, and multiple health authorities. The commercial logic is straightforward: centralized regulatory information reduces duplication, shortens review cycles, and improves the consistency of submissions across markets.
PW Consulting Information & Electronics Research Center
Cost Structures and Operational Efficiency
Cost dynamics are also influencing adoption patterns. Organizations are seeking to reduce the hidden costs of manual reconciliation, version control errors, and delayed submissions that can stall market entry or trigger compliance findings. Cloud-based deployment has become a significant enabler in this context, offering scalability, lower upfront infrastructure burden, and easier integration with adjacent quality, safety, and clinical systems. At the same time, on-premise deployments persist in settings where data residency, internal control requirements, or legacy integration constraints favor localized infrastructure. The broader cost story is not simply about license pricing; it is about total cost of ownership over the product lifecycle. Platforms that streamline regulatory execution, reduce rework, and provide reusable data structures are gaining preference because they translate compliance activity into measurable operational savings.
Competitive Landscape and Leading Strategies
The RIM market features a mix of purpose-built specialists, broad life sciences platform providers, and diversified compliance vendors. Their strategies reveal distinct approaches to capturing value in a market that rewards both domain depth and execution efficiency.
Supplier Relationship Management System Market
Several vendors have carved out strong positions by focusing on specific end markets or workflow strengths. Rimsys has built a unified RIM platform purpose-built for MedTech, emphasizing global registrations, submissions, product data, and change management within a single system. Its recent product launch illustrates a strategy centered on embedding regulatory execution, AI-powered monitoring, and configurable impact workflows directly into the platform, reducing the need for disjointed point solutions. RegDesk pursues a similar MedTech orientation with centralized regulatory data management, global compliance workflows, and regulatory intelligence, targeting organizations that need streamlined multi-jurisdiction execution. Kivo serves life sciences sponsors and service providers with document and process management, compliance workflows, and support for major authorities such as the FDA and EMA. These specialists compete by delivering focused functionality, faster implementation paths, and clear alignment with the daily realities of regulatory operations teams.
Broader platform players are taking a different approach, leveraging scale, ecosystem integration, and cloud architectures. Veeva Systems offers a cloud-based RIM capability within its Vault portfolio, covering submissions, registrations, publishing, and archival functions for life sciences. Its strategy benefits from a recognized cloud infrastructure and strong adoption across pharmaceutical and biotech organizations that already use Veeva for adjacent processes. IQVIA provides a cloud-based, AI-enabled platform for regulatory submissions, registrations, lifecycle management, and compliance across MedTech, IVD, and pharma, positioning its offering as part of a larger data and services ecosystem. ArisGlobal’s LifeSphere RIMS emphasizes end-to-end regulatory planning, tracking, registration management, and compliance with AI integration, appealing to organizations that want planning and execution tightly coupled. Ennov centralizes product, registration, submission, correspondence, and commitment data for regulatory operations and compliance, while Freyr Solutions offers RIM software as part of broader end-to-end regulatory services, including lifecycle management and compliance support. MasterControl rounds out the field with regulatory information management, product reviews, approvals, releases, and compliance tracking, targeting organizations that value integrated quality and regulatory workflows.
The market is evolving along two complementary paths. One is consolidation through ecosystem breadth, where larger vendors expand functionality and deepen integrations to reduce switching costs and capture more of the regulatory lifecycle. The other is differentiation through specialization, where focused vendors compete on ease of deployment, regulatory domain expertise, and workflow precision. A third dynamic is the continued entry of new players targeting underserved niches, particularly MedTech-specific workflows and AI-assisted monitoring. For buyers, this landscape creates both opportunity and risk. The upside is a growing set of options tailored to different operating models; the risk is platform sprawl if organizations select tools that do not integrate well with existing quality, safety, or content systems. The most effective strategies tend to prioritize data coherence, authorization and audit readiness, and the ability to scale across markets without rebuilding workflows from scratch.
Future Trends and Strategic Implications
Looking ahead three to five years, several trends are likely to define the next stage of RIM market evolution. The first is the deepening embedment of intelligence into regulatory execution. AI-assisted monitoring, automated impact assessment, and smarter submission preparation will become more common, enabling teams to respond faster to changing requirements and reduce manual review burdens. The commercial opportunity here lies in platforms that can translate regulatory signals into actionable workflow steps, not just alerts. Organizations that adopt these capabilities early may gain meaningful advantages in submission readiness and cycle time. The associated risk is over-reliance on automation without adequate validation, governance, and human oversight, especially in highly regulated contexts.
A second trend is the continued pressure toward centralized, interoperable regulatory data architectures. As product portfolios expand and market access strategies become more global, the ability to reuse product data, maintain consistent registration records, and connect regulatory information with quality and safety systems will increasingly separate high-performing organizations from those struggling with fragmentation. The opportunity is to treat regulatory data as a shared asset that supports cross-functional decisions, rather than as a compliance archive. The risk is that legacy system inertia and integration complexity slow transformation, leaving organizations with improved documentation but not improved execution.
A third trend is the tightening of data privacy and security expectations as a core selection criterion. With multiple U.S. state privacy laws in effect and international obligations still evolving, RIM platforms will be evaluated not only on regulatory functionality but also on data handling maturity, access controls, and auditability. Vendors that can demonstrate robust privacy-by-design architectures and clear jurisdictional controls will be better positioned in enterprise deals. The uncertainty lies in how quickly requirements will continue to multiply and whether standardization efforts will ease or complicate compliance burdens.
Actionable Guidance for Decision-Makers
For regulated product manufacturers, the priority should be to assess RIM platforms against the full regulatory execution lifecycle rather than isolated compliance tasks. Selection criteria ought to include submission authoring efficiency, registration and change management coherence, integration with quality and safety systems, and the ability to configure workflows for multiple jurisdictions without excessive customization. Organizations that treat RIM as a strategic execution layer typically see better alignment between regulatory planning and operational delivery.
For investors and strategic partners, the market signals value in vendors that combine domain focus with demonstrable automation benefits and credible data governance. Differentiation is increasingly tied to workflow intelligence, deployment flexibility, and the ability to serve complex MedTech or multi-entity life sciences environments. Due diligence should look beyond feature lists to adoption patterns, implementation outcomes, and the vendor’s capacity to sustain innovation as privacy and regulatory expectations continue to evolve.
Legal Risk And Compliance Solution Market
For procurement and operations leaders, the most practical step is to map current regulatory pain points—such as duplicate data entry, slow impact assessment, or fragmented submission records—against platform capabilities that directly address those bottlenecks. Cloud-based deployment may offer faster time-to-value in many scenarios, but the final decision should reflect data residency needs, internal control requirements, and the organization’s integration roadmap. Given the pace of change and the widening range of vendor strategies, timely access to detailed segmentation data, vendor benchmarking, and tailored implementation considerations can materially improve investment outcomes. Comprehensive research providing deeper segment-level insight and customized analysis is available for teams that need to move from strategic direction to execution planning with greater confidence.
For detailed analysis of this topic, please visit the official page: Regulatory Information Management (RIM) Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com