

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Snowblower Market Trends: Why Two-Stage Models and North America Reshape Growth by 2032

Navigating the Snowblower Market: Strategic Trends and Commercial Opportunities (2026-2032)
Market Overview and Core Challenges
The global snowblower market has demonstrated steady growth over the past five years, expanding from approximately $10.82 billion in 2020 to an estimated $12.61 billion in 2025. This trajectory reflects consistent demand drivers tied to winter preparedness, residential infrastructure expansion, and commercial facility management. Looking ahead to 2032, the market is projected to reach $15.61 billion, representing a compound annual growth rate of 3.1 percent. While the growth rate suggests maturity rather than explosive expansion, the underlying dynamics reveal significant shifts in how snow removal equipment is developed, distributed, and utilized.
Revenue distribution across regions highlights a clear concentration pattern. North America accounts for the largest share of global sales, reflecting the region's climate profile, established consumer base, and mature distribution networks. Europe follows as the second-largest market, driven by consistent winter conditions and a growing emphasis on commercial snow management solutions. Asia Pacific, Latin America, and the Middle East and Africa collectively represent smaller but emerging opportunities, where infrastructure development and variable winter patterns create niche demand segments.
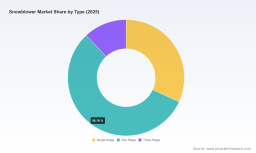
Within the product landscape, two-stage snow blowers dominate the market, valued at over $7.08 billion, reflecting their versatility and effectiveness for moderate to heavy snow conditions. Single-stage models, valued at approximately $4.01 billion, serve lighter snowfall regions and residential applications where ease of use and lower cost take priority. Three-stage units, valued at around $1.51 billion, capture a specialized segment focused on extreme conditions and professional-grade performance. Application-wise, the residential segment leads with approximately $7.43 billion in revenue, while commercial applications contribute roughly $5.18 billion, indicating strong demand from property management firms, municipal operations, and facility maintenance providers.
Several challenges are reshaping how companies approach strategy in this market. First, the supply chain environment has become increasingly volatile. Raw material costs, particularly for steel and aluminum, have been influenced by tariff policies and global supply fluctuations. In early 2026, U.S. hot-rolled coil steel prices ranged from $935 to $965 per ton, driven in part by tariffs affecting snow blower manufacturing costs. The continued imposition of Section 232 tariffs on steel and aluminum imports at 25 percent has further complicated sourcing for manufacturers reliant on imported components. Global steel supply chain dynamics show apparent steel consumption projected to recover by 3.1 percent in 2026 following prior declines, but this recovery introduces pricing uncertainty that manufacturers must carefully manage.
Second, regulatory and safety scrutiny has intensified. Product safety incidents have prompted recalls and heightened attention to design integrity. For instance, Ariens recalled Deluxe, Platinum, and Professional series snow throwers due to impeller and auger assembly continuing to rotate after control lever release, as documented by the U.S. Consumer Product Safety Commission in early 2025. This event underscores the importance of robust engineering and quality assurance processes, particularly for companies competing on performance and durability.
Third, the market is experiencing a technology transition as battery-electric alternatives gain traction. While traditional gas-powered models continue to lead in many segments, the introduction of cordless and low-emission options is reshaping consumer expectations and forcing incumbents to invest in powertrain diversification. Companies must balance the performance advantages of internal combustion engines with the environmental and operational benefits of electric platforms, all while managing cost structures and consumer education.
For decision-makers, these dynamics signal a market where growth is no longer solely about volume expansion. Strategic positioning requires attention to cost resilience, product safety, and adaptation to evolving powertrain preferences. Companies that can navigate these pressures while delivering reliable, differentiated solutions will be best positioned to capture value in the coming years.
Key Drivers Shaping the Market
Technological Innovation and Performance Differentiation
The snowblower market is undergoing a period of meaningful technological evolution. Manufacturers are investing in engine optimization, clearing technology improvements, and user-centric design features that enhance performance across diverse snow conditions. Ariens introduced 2026 Platinum series updates with enhanced 389cc engines designed for heavy snow conditions, demonstrating how incremental engineering advancements can reinforce market leadership in the two-stage segment. Similarly, Toro released a 2025-2026 lineup including 60V MAX Power Max e26 two-stage battery snow blower models, signaling a strategic push toward electric platforms that combine performance with reduced noise and emissions.
Beyond powertrain shifts, three-stage clearing technology has emerged as a differentiator for heavy-duty applications. This configuration, which incorporates an accelerator in addition to the auger and impeller, addresses scenarios where rapid snow displacement is critical. Cub Cadet's 3X series and Troy-Bilt's Storm series have both emphasized three-stage options, illustrating how brands are using advanced clearing architectures to appeal to users who face frequent, intense snowfall. These advancements are not merely incremental; they reflect a broader industry trend toward segment-specific engineering, where product design aligns closely with regional climate profiles and usage intensity.
For manufacturers, the implication is clear: competitive advantage increasingly depends on delivering measurable performance improvements that resonate with specific user needs. Companies that invest in R&D focused on engine reliability, clearing efficiency, and ease of operation can command premium positioning and foster brand loyalty in a market where replacement cycles create recurring demand opportunities.
Policy and Regulatory Environment
Regulatory developments continue to shape cost structures and product strategy. The persistence of U.S. Section 232 tariffs on steel and aluminum imports at 25 percent in 2026 has direct implications for snow blower manufacturing, as these materials are fundamental to chassis construction, auger systems, and impeller assemblies. Imported components and raw materials face higher costs, prompting manufacturers to evaluate sourcing strategies, domestic production adjustments, and pricing models.
Fully Automatic Snow Blower Market
At the same time, safety regulations and consumer protection oversight are becoming more rigorous. Recalls and incident reporting highlight the need for proactive compliance and design validation. The Ariens recall exemplifies how mechanical failure modes can trigger regulatory action and reputational risk, reinforcing the importance of thorough testing protocols and quality control across production lines.
Policy uncertainty also extends to environmental expectations. While no sweeping regulatory mandate currently dictates powertrain transitions in snow removal equipment, shifting consumer sentiment and local emissions considerations are influencing purchasing behavior. Manufacturers that anticipate these trends by developing lower-emission options and communicating environmental benefits can position themselves ahead of potential regulation while appealing to eco-conscious buyers.
Demand-Side Changes in Consumer and Commercial Behavior
Demand patterns are evolving as end users reassess their snow removal priorities. In the residential segment, homeowners are increasingly seeking equipment that balances power, ease of use, and operational cleanliness. Battery-powered snow blowers, such as those offered by EGO Power+ and Greenworks, address concerns around noise, emissions, and maintenance while providing sufficient clearing capability for typical residential snowfall. These products appeal particularly to users in suburban areas where garage space, storage, and proximity to neighbors make quieter, cordless operation desirable.
On the commercial side, facilities management teams and municipal operators are prioritizing reliability and throughput. Snow Joe and similar affordable electric and battery options target lighter residential removal, while commercial-focused users look for durability and clearing speed. The broader trend indicates a bifurcation in demand: lighter-duty, user-friendly products for homeowners and more robust, high-performance systems for businesses that cannot afford clearing downtime.
Weather variability also influences purchasing timing and volume. Regions experiencing heavier or more unpredictable winter patterns tend to see stronger equipment demand, while milder winters can temporarily suppress replacement cycles. This volatility encourages manufacturers to maintain flexible production planning and regional marketing strategies that align with localized climate expectations.
Supply Chain and Cost Structure Evolution
Cost pressures from raw materials and trade policy are reshaping margin expectations. Steel price fluctuations, tariffs on imported inputs, and global supply chain adjustments have forced manufacturers to examine component sourcing, inventory management, and pricing strategies more closely. The projected 3.1 percent recovery in global steel consumption in 2026 suggests improving availability, but price stability remains uncertain.
Manufacturers are responding by diversifying supplier bases, evaluating domestic production options, and exploring design efficiencies that reduce material intensity without compromising durability. Battery-electric models also introduce a different cost structure, shifting expense from fuel and maintenance toward battery technology and electronic components. Over time, as battery costs evolve and production scales, the economics of electric snow blowers may improve, expanding their viability beyond niche applications.
For industry participants, supply chain resilience has become a strategic priority. Companies that can manage input cost volatility, maintain production continuity, and adapt pricing to preserve value perception will be better equipped to sustain margins in a fluctuating cost environment.
Competitive Landscape and Leading Strategies
The market features a mix of established manufacturers, brand portfolios under larger industrial groups, and emerging electric-focused entrants. Ariens stands out for its focus on two-stage snow blowers with Deluxe, Platinum, and Professional series targeting heavy-duty residential and commercial snow removal. Its recent product updates and engine enhancements reflect a strategy centered on performance credibility and segment specialization. Toro Company complements this approach with a broad portfolio spanning gas and battery-powered models, including Power Max and Power Clear series, enabling it to serve both traditional and transitioning customer preferences.
Honda Power Equipment maintains a premium positioning known for reliability, with HSS series two-stage models leveraging Honda engines optimized for performance and ease of use. This reputation for durability supports a higher price point and appeals to users who prioritize long-term value. Cub Cadet and Troy-Bilt, both part of the MTD Products network, offer distinct brand positioning: Cub Cadet emphasizes power steering and three-stage clearing technology through its 2X and 3X series, while Troy-Bilt focuses on affordable, high-performance two and three-stage options via its Storm series. This parent-company strategy of managing multiple brands allows coverage across price points and feature sets without internal cannibalization.
Husqvarna and John Deere both integrate snow blowers into broader outdoor power equipment lineups, leveraging brand trust and cross-category customer relationships. Craftsman provides single, two, and three-stage models distributed through major retail channels like Lowe's, capitalizing on widespread retail access and brand recognition. EGO Power+ and Greenworks represent the electric-focused cohort, specializing in battery-powered and corded electric solutions that emphasize quiet, emission-free operation for residential applications. Snow Joe and RYOBI target affordability and accessibility, with Snow Joe known for lighter residential electric and battery throwers and RYOBI offering battery and gas options sold primarily through Home Depot. KOVACO adds European manufacturing presence with compact and professional snow blowers, reflecting localized product strategies in regional markets. Simplicity, also MTD-affiliated, reinforces the durability-focused homeowner segment.
Several strategic patterns emerge from this landscape. First, brand portfolios and multi-tier offerings enable companies to address diverse customer segments while maintaining operational efficiencies. Second, electric powertrain development is becoming a competitive differentiator, with incumbents expanding battery lines and specialized entrants building credibility around cordless performance. Third, product safety and quality assurance are increasingly visible elements of brand reputation, as recalls and regulatory scrutiny can influence consumer trust and retailer relationships.
The competitive environment is evolving through both consolidation and fragmentation. Larger industrial groups continue to manage multiple brands, creating economies of scale in manufacturing and distribution while preserving distinct brand identities. At the same time, the rise of electric solutions and specialized clearing technologies opens space for focused entrants that can innovate quickly in specific niches. Trade show participation, such as RPM Tech exhibiting the PB-2000 snow blower at the Atlantic Heavy Equipment Show to showcase municipal and airport clearing capabilities, illustrates how new and expanding players are targeting specialized commercial applications beyond traditional residential markets.
Worldwide Hand Held Blower Market
For market participants, the key question is not simply who leads today, but which companies can adapt product architectures, supply chains, and brand messaging to align with shifting consumer expectations and cost realities. Differentiation will increasingly depend on performance consistency, powertrain flexibility, and the ability to communicate value in ways that resonate with both traditional and new user priorities.
Future Trends and Strategic Implications
Looking ahead to the 2026-2032 period, several trends are likely to shape market evolution. The first is the continued expansion of battery-electric options across residential and light commercial segments. As battery technology improves and production scales, cordless snow blowers will become more capable of handling moderate to heavy snowfall, broadening their addressable market. Manufacturers that develop reliable electric platforms and educate consumers on performance realities will capture early-mover advantage in an transitioning segment. However, this trend carries uncertainty around battery cost trajectories, charging infrastructure expectations, and consumer willingness to adopt cordless solutions for heavy-duty use.
The second trend is increasing focus on segment-specific engineering and application alignment. As climate variability and regional snowfall patterns influence purchasing decisions, companies will likely invest further in product configurations tailored to distinct use cases. This includes three-stage systems for extreme conditions, compact electric units for suburban homeowners, and commercial-grade equipment for municipal and facility operations. The strategic opportunity lies in matching product portfolios to regional demand profiles and avoiding one-size-fits-all positioning that may dilute brand relevance.
The third trend involves supply chain and cost management as persistent competitive factors. Tariffs, steel price volatility, and global material flows will continue to influence manufacturing economics. Companies that diversify sourcing, optimize material usage, and maintain pricing flexibility will protect margins more effectively than those dependent on single supply routes or rigid cost structures. At the same time, any relaxation or reconfiguration of trade policy could shift cost dynamics quickly, requiring agile planning and scenario readiness.
These trends create commercial opportunities for manufacturers that can balance innovation with operational resilience, for investors seeking exposure to brands that demonstrate adaptability across powertrain transitions, and for procurement teams that benefit from understanding which suppliers are best positioned to deliver consistent quality amid cost volatility. The primary risk is complacency in the face of technological and regulatory shifts; companies that treat the market as static may lose ground to competitors who anticipate changing user expectations and cost environments.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to strengthen product differentiation through targeted engineering and powertrain diversification. Investing in engine reliability, clearing technology, and electric platform development can reinforce market position across segments. Equally important is proactive quality assurance and compliance to mitigate safety-related disruptions that can affect brand trust and retail relationships. Companies should also evaluate supply chain flexibility, including multi-source sourcing and material optimization, to manage cost volatility without sacrificing product durability.
For investors, the strategic focus should be on companies that demonstrate adaptability across traditional and electric product lines, maintain strong brand equity in core regions, and exhibit disciplined cost management. Brands with multi-tier portfolios and clear segment positioning may offer more resilient growth profiles in a market where demand is bifurcating between lightweight residential solutions and heavy-duty commercial systems. Monitoring trade policy developments and raw material trends can also help anticipate shifts in manufacturer margins and pricing strategies.
PW Consulting Automotive & Machinery Research Center
For procurement and purchasing leaders, understanding supplier positioning and product architecture differences can inform sourcing decisions for residential, facility, or municipal applications. Evaluating manufacturers based on engineering depth, safety track records, and powertrain options enables more informed selection aligned with operational requirements and environmental preferences. Building relationships with suppliers that demonstrate supply chain resilience and consistent quality can reduce disruption risk during peak demand periods.
Detailed segmentation data, cost structure analysis, and customized strategic guidance can provide deeper clarity for organizations making specific investment or sourcing decisions. A complete research report offers granular breakdowns across regions, product types, and applications, along with forward-looking scenarios that support more precise planning.
For detailed analysis of this topic, please visit the official page: Snowblower Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com