

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Custom LED Lighting Solution Market: The Real 11.12% Growth Drivers to 2032

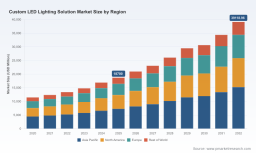
Global Custom LED Lighting Solution Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The worldwide custom LED lighting solution market has transitioned from a niche specialty segment to a significant growth engine within the broader illumination industry. Between 2020 and 2025, market revenue expanded from approximately $11.45 billion to $18.70 billion, reflecting a compound annual growth rate of 11.12 percent. Projections indicate this trajectory will continue, with revenue expected to surpass $39 billion by 2032. This growth underscores a fundamental shift away from standardized, off-the-shelf lighting products toward tailored solutions that integrate specific aesthetic, functional, and technological requirements. The market is no longer solely about illumination; it is about delivering precise lighting environments that align with architectural visions, commercial branding strategies, and specialized operational needs.
Despite the robust growth trajectory, the industry faces several critical challenges that create both headwinds and opportunities for strategic positioning. First, the supply chain for critical raw materials remains a significant vulnerability. The production of essential semiconductor materials such as gallium and germanium is heavily concentrated in specific geographic regions, with China maintaining dominant shares of global output. Export licensing mechanisms and prior restrictions have periodically disrupted supply flows, compelling manufacturers to navigate complex procurement strategies. This reliance creates exposure to price volatility and potential shipment delays, particularly for companies dependent on steady inputs for high-performance LED components.
Second, regulatory and trade policy environments are becoming increasingly stringent. Recent executive directives in the United States have initiated negotiations on imports of processed critical minerals and derivative products, citing national security concerns. The prospect of tariffs or altered trade terms introduces uncertainty for cost structures and sourcing strategies. Companies must now factor geopolitical developments into their supply chain resilience planning, as policy shifts can rapidly alter the cost competitiveness of imported components versus domestically sourced alternatives. The interface between illumination engineering and trade policy has become a routine consideration for strategic planning teams.
Third, the market is experiencing a tension between customization demands and production scalability. Customers increasingly expect bespoke designs, smart integration, and rapid turnaround, yet maintaining margin profiles while accommodating low-volume, high-variety orders requires sophisticated manufacturing flexibility. Organizations that rely on rigid production lines risk losing share to competitors who have invested in modular platforms, digital customization tools, and agile supply networks. The operational challenge lies in balancing the premium pricing potential of custom solutions with the efficiency expectations of a market that continues to grow at double-digit rates.
Finally, market concentration remains relatively fragmented at the aggregate level, with the top three and top five participants together accounting for a modest share of total revenue. This dispersion indicates that no single entity currently dominates the global landscape, creating room for consolidation, niche specialization, and new entrants who can differentiate through technology, service, or regional expertise. The lack of overwhelming concentration also means that competitive advantage is less about scale alone and more about the ability to execute effectively across technical, commercial, and geographic dimensions.
Key Drivers of Market Momentum
Several interconnected forces are accelerating demand for custom LED lighting solutions and reshaping how companies compete. Understanding these drivers is essential for identifying where value will be created over the next several years.
Technological Innovation and Smart Integration. Advances in LED semiconductor performance, optical design, and control electronics are expanding the scope of what custom solutions can achieve. Manufacturers are increasingly integrating sensors, connectivity modules, and adaptive dimming capabilities into luminaires, enabling buildings and industrial facilities to respond dynamically to occupancy, daylight availability, and operational schedules. Smart integrated systems represent a substantial portion of current market activity, reflecting demand for solutions that combine illumination with energy management and data-enabled functionality. In parallel, developments in modular fixture architectures allow designers and engineers to specify tailored configurations without sacrificing production efficiency. Companies that have built expertise in combining high-performance light sources with application-specific optics and control logic are capturing premium positioning, particularly in sectors where lighting must meet both functional and aesthetic criteria. Recent product launches illustrate this trajectory: new offerings in architectural and commercial vehicle branding have demonstrated how customization can serve both design objectives and regulatory compliance simultaneously, integrating brand identity into lighting hardware while maintaining required safety standards.
Hazardous Location Lighting Market
Policy and Regulatory Environment. Energy efficiency mandates, building performance codes, and sustainability requirements continue to push end users toward lighting solutions that reduce consumption while enhancing functionality. Regulations that encourage or require upgrading legacy lighting infrastructure create a structural tailwind for custom solutions, especially when retrofitting existing spaces demands non-standard fixture dimensions, color temperatures, or integration with existing building management systems. At the same time, trade and supply chain policies are reshaping cost dynamics. The push to secure critical mineral supply chains has introduced new considerations for procurement teams, as import negotiations and potential tariffs could affect the cost of gallium, germanium, and derivative products used in LED optoelectronics. Organizations that proactively diversify sourcing, invest in alternative material strategies, or localize certain production steps may find themselves better insulated against regulatory shifts, while also gaining a narrative advantage with customers who prioritize supply chain transparency.
Demand-Side Shifts in Commercial, Architectural, and Specialty Applications. End-user expectations are evolving rapidly across multiple verticals. Commercial and retail operators are leveraging custom lighting to create distinctive brand environments, guide customer flow, and support merchandising strategies that rely on precise color rendering and accent lighting. Architectural and facade projects increasingly treat lighting as an integral design element, requiring bespoke solutions that align with structural forms, material textures, and nighttime visual impact. Industrial and specialty applications, including harsh-environment settings and mission-critical facilities such as data centers, are driving demand for ruggedized, certified solutions that meet stringent performance and reliability standards. High-end residential markets are also contributing, with homeowners and designers seeking personalized lighting schemes that complement interior aesthetics and wellness-oriented environments. Across these segments, the common thread is the need for solutions that cannot be satisfied by catalog products alone. Customers are willing to invest in tailored designs when those designs deliver measurable benefits in energy use, occupant experience, or operational reliability.
Supply Chain and Cost Structure Evolution. Cost pressures are reshaping how custom lighting solutions are developed and delivered. Raw material price increases, driven by chip and component costs as well as packaging material constraints, have prompted lead producers to adjust pricing across light sources and finished goods. Simultaneously, labor availability, logistics complexity, and the cost of maintaining quality across customized production runs add layers of complexity to margin management. In response, leading organizations are pursuing several strategies: forming strategic manufacturing partnerships to strengthen capacity and restore delivery performance for core product lines; leveraging scale in high-volume components while reserving customization for higher-margin added value; and adopting digital design-to-production workflows that reduce lead times and errors in bespoke orders. These adjustments are not merely defensive; they are repositioning companies to compete on reliability, speed, and the ability to scale customized output without eroding profitability.
The interaction of these drivers suggests that the market will reward participants who can integrate technical capability with supply chain resilience and customer-centric design processes. Innovation alone is insufficient if it cannot be delivered at the right cost and with consistent quality. Likewise, cost efficiency that sacrifices the ability to meet specialized requirements will limit growth in a market defined by customization.
Competitive Landscape and Leading Strategies
The competitive environment in the global custom LED lighting solution market is characterized by a mix of global scale players, specialty manufacturers, and regional experts. The absence of extreme concentration means that competitive advantage is earned through differentiated capabilities rather than market dominance alone. Several strategic positions have emerged among leading participants.
Some organizations compete primarily through breadth of customization and global reach. These firms offer extensive options for smart and architectural custom designs, serving commercial, industrial, and specialty applications across multiple regions. Their advantage lies in the ability to draw on large engineering teams, established manufacturing footprints, and broad customer relationships to address diverse project requirements. Sustainability-focused product initiatives, such as introducing lighting tubes made with significant post-consumer recycled content and packaging innovations, signal an effort to align customization with environmental expectations, a theme that resonates with commercial and institutional buyers.
Other participants focus on high-performance components and tailored systems for demanding applications. Companies with strong positions in custom LED components and lighting systems emphasize precision, reliability, and application-specific engineering, particularly for automotive, industrial, and specialty projects. These firms often serve as critical suppliers within larger value chains, where performance specifications and certification requirements create barriers to entry and reward deep technical expertise. In industrial and harsh-environment contexts, strategic manufacturing agreements are being used to reinforce capacity and improve delivery performance for core lines, highlighting the importance of supply reliability as a competitive differentiator.
A third group of competitors specializes in niche, high-value segments where customization intensity is particularly high. Manufacturers of bespoke architectural fixtures, custom LED light sheets, edgelighting solutions, and OEM-specific designs serve customers who require close collaboration on product definition and exact project specifications. In mission-critical environments such as data centers, certification achievements have become a valuable signal of capability, with first-to-market certifications demonstrating compliance with rigorous standards and opening doors to specialized procurements. Specialty providers also serve commercial vehicles, machine vision, and other applications where integration of branding, safety, and functional performance must be exact. These niche players often compete on responsiveness, design collaboration, and the ability to manage low-volume, high-mix production efficiently.
PW Consulting
The market structure appears poised for continued evolution along several axes. Consolidation is likely in segments where scale economies in component sourcing, certification, and distribution create advantages for larger entities, particularly as energy and compliance requirements raise the cost of participation. At the same time, fragmentation will persist in highly customized arenas where local design expertise, regional building practices, and project-specific relationships matter greatly. New entrants may emerge from adjacent technology domains, including smart building controls, advanced optics, and materials science, bringing fresh capabilities that reshape what custom lighting can deliver. The most successful organizations will be those that define a clear strategic identity: whether that means leading with global customization breadth, deep application-specific engineering, or specialized niche expertise, and then aligning manufacturing, sourcing, and service models to support that identity consistently.
Future Trends and Commercial Opportunities
Looking ahead to the 2026 through 2032 period, several trends are likely to shape the market and create distinct commercial opportunities.
Trend One: Smart, Connected Custom Lighting Becomes Standard in Commercial and Institutional Projects. As building owners and facility operators pursue energy savings, occupant experience improvements, and operational analytics, the integration of controls, sensors, and network connectivity into custom luminaires will shift from optional to expected. This trend creates opportunities for manufacturers that can offer customized fixtures with embedded intelligence and for service providers that can design, deploy, and maintain integrated lighting environments. Commercial and retail applications, in particular, stand to benefit from lighting systems that adapt to usage patterns and support broader building management goals. The opportunity lies not only in hardware but in the value-added services that surround it, including specification support, commissioning, and ongoing optimization.
Trend Two: Sustainability and Supply Chain Resilience Become Core Purchasing Criteria. Buyers are increasingly scrutinizing the environmental footprint of lighting products and the resilience of the supply chains behind them. Recycled content, reduced packaging waste, energy-efficient manufacturing, and transparent sourcing are expected to influence procurement decisions, especially in regions with stringent building codes and corporate sustainability commitments. At the same time, the critical minerals context encourages diversification of sourcing and, where feasible, localization of key production steps. Companies that can demonstrate credible sustainability credentials and robust supply continuity will be positioned to command preference in competitive bids, particularly for large-scale commercial and institutional projects where risk mitigation carries significant weight.
Trend Three: Specialty and Mission-Critical Applications Drive Premium Segments. Data centers, industrial facilities, harsh-environment settings, and other specialty applications will continue to generate demand for certified, high-reliability custom solutions. As digital infrastructure expands and industrial automation intensifies, the need for lighting that meets strict performance, safety, and certification requirements will grow. This trend favors suppliers that invest in compliance, testing, and application-specific engineering, and that can articulate clear value around uptime, safety, and operational consistency. The premium associated with these segments can support attractive margins, provided that manufacturers maintain disciplined quality and delivery performance.
Potential risks and uncertainties warrant attention. Trade policy developments could alter cost structures and sourcing feasibility, particularly for materials with concentrated supply. Raw material price volatility may compress margins if manufacturers cannot pass through costs or offset them through design efficiency and sourcing strategy. Additionally, the pace of adoption for smart features will vary by region and sector, meaning that investments in connectivity and controls may not yield uniform returns across all markets. Organizations should monitor these variables closely and maintain flexibility in their product roadmaps and supply arrangements.
Strategic Recommendations for Decision-Makers
For manufacturers and solution providers, the priority is to align product development with the highest-value customization opportunities while building resilience into sourcing and production. This means investing in modular platforms that enable rapid tailoring, strengthening partnerships for critical inputs, and pursuing certifications and sustainability credentials that differentiate offerings in competitive bids. Companies should also evaluate where strategic manufacturing agreements or regional production can improve delivery reliability for core lines, especially in segments where lead time and consistency are decisive factors.
For investors assessing opportunities in this space, the most attractive positions are likely to be found where technical differentiation, certification moats, and recurring demand intersect. Segments such as mission-critical data center lighting, specialty industrial applications, and smart integrated systems for commercial environments offer potential for sustained growth, but due diligence should examine supply chain exposure, certification status, and the scalability of customization processes. Diversification across geographies and application types can help mitigate concentration risk tied to any single market or policy environment.
For procurement leaders and end-user organizations, the focus should be on specifying solutions that balance performance, total cost of ownership, and supply continuity. Engaging early with manufacturers to define project requirements, favoring suppliers with demonstrated certification and sustainability track records, and incorporating flexibility for future upgrades can reduce risk and improve long-term outcomes. Given the range of available options and the rapid evolution of technology and regulation, access to detailed, up-to-date market intelligence is valuable for evaluating vendors, benchmarking specifications, and timing investments.
LED Lighting Market
For those seeking a comprehensive mapping of segments, regional dynamics, competitive benchmarks, and forward-looking scenarios, the full PW Consulting report on the worldwide custom LED lighting solution market provides granular analysis and customized recommendations to support strategic planning.
For detailed analysis of this topic, please visit the official page: Worldwide Custom LED Lighting Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com