

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Ocean Recycled Yarn Market: Why a 13.24% CAGR Reshapes the 2026 Outlook

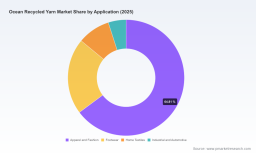
The Strategic Frontier: Navigating Growth in the Worldwide Ocean Recycled Yarn Market
Market Current State and Core Challenges
The global market for ocean recycled yarn has entered a phase of accelerated expansion, driven by a confluence of environmental imperatives, regulatory tailwinds, and shifting consumer expectations. From 2020 through 2025, the sector progressed from an emerging niche to a recognized component of the broader recycled textiles landscape, with total market revenue climbing from approximately USD 412 million to roughly USD 742 million. Looking ahead to 2032, the trajectory points toward a sustained upward curve, with revenue projections reaching nearly USD 1.77 billion. This expansion reflects a compound annual growth rate of 13.24 percent across the forecast window, underscoring a market that is no longer dependent solely on brand-led pilot programs but is embedding itself into mainstream textile sourcing strategies. The scale of this growth signals a structural shift rather than a temporary fashion cycle, as ocean-bound plastic recovery becomes an increasingly viable feedstock stream for high-volume fiber production.
Despite this momentum, the industry faces several defining challenges that will shape competitive outcomes over the next decade. First, feedstock availability and collection infrastructure remain fragmented. Ocean-bound plastics represent a specialized input category that competes with conventional post-consumer bottle streams. Securing consistent, certified volumes requires navigating coastal collection networks, informal waste economies, and complex logistics in regions where recycling infrastructure is still developing. The supply of marine-derived material is growing, but it remains a small fraction of total recycled polyester feedstock, which means producers must design robust sourcing strategies that do not overpromise on marine content while still delivering credible sustainability narratives.
Second, traceability and certification complexity introduce both operational and reputational risk. Brands and manufacturers increasingly demand verified provenance, not just recycled content claims. Materials must satisfy standards such as the Global Recycled Standard and Ocean Bound Plastic certification to substantiate marine sourcing and environmental additionality. Maintaining these certifications across multiple tiers of collection, processing, and yarn production adds cost and administrative burden, particularly for firms operating across jurisdictions with different auditing expectations. Failure to maintain credible traceability can quickly erode buyer trust, especially as regulatory scrutiny intensifies.
Third, pricing volatility and policy-driven cost shifts complicate margin planning. Recycled polyester pricing varies significantly by region and feedstock type, with certified ocean-bound material often commanding premiums due to traceability and the perceived environmental value of diverting marine waste. At the same time, trade policy changes can alter the economics of imported recycled feedstocks overnight, affecting input costs for yarn producers who rely on cross-border resin or flake flows. These dynamics create a tension between the demand for sustainable differentiation and the need for stable, competitive input pricing, forcing companies to make strategic choices about how much premium they can absorb or pass through to downstream partners.
Key Drivers of Market Change
Several interconnected drivers are accelerating the adoption and scaling of ocean recycled yarn, and each carries distinct implications for how companies position themselves in the market. Understanding these forces helps clarify where value is created and where execution risk concentrates.
Technological Innovation and Processing Breakthroughs
Advancements in recycling and fiber regeneration technologies are expanding what can be recovered and how cleanly it can be integrated into commercial yarn streams. One of the most consequential developments is the ability to handle more complex waste streams, such as nylon blends and elastic fibers, which historically limited the volume of fishing nets and marine textiles suitable for regeneration. Recent demonstration-scale initiatives have focused on separating elastic components from nylon blends so that the recovered material can be fed back into regeneration systems. This type of processing innovation matters because fishing nets and marine nylon waste are high-value feedstocks with strong brand appeal, but their heterogeneity has long been a bottleneck. As separation and purification techniques improve, producers can access larger volumes of marine-derived input without sacrificing fiber quality, which in turn strengthens the commercial case for ocean recycled yarns in performance and durability-sensitive applications.
Beyond feedstock flexibility, improvements in filament construction and yarn engineering are helping ocean-recycled fibers meet the functional requirements of diverse end uses. Producers are offering a wider range of denier and dtex options, enabling more precise matching to apparel, footwear, and technical textile specifications. This diversification reduces the perception that recycled yarns are limited to cost-driven or purely promotional applications, and instead positions them as viable inputs for items where strength, consistency, and finish matter. For buyers, this means ocean recycled yarns can be evaluated more on performance parity than on sustainability alone.
Policy and Regulatory Environment
Policy is increasingly shaping the economics of recycled fiber adoption, particularly in major markets where recycled-content mandates and packaging regulations create pull-through demand. In the European Union, the Packaging and Packaging Waste Regulation establishes mandatory recycled-content thresholds for PET, which indirectly reinforces demand for traceable recycled polyester across related applications, including textiles. Even when the regulation directly targets packaging, the ripple effect strengthens the broader recycled PET ecosystem and supports price discovery for certified recycled material. For yarn producers, this means regulatory momentum can lift baseline demand and improve the business case for investing in certified ocean-bound supply chains.
At the same time, trade policy adds a layer of complexity. Recent tariff measures on imported PET and recycled PET resin have increased costs for certain imported feedstocks used in yarn production. This highlights the importance of supply chain design: producers that can secure regional or nearshore feedstock, or that have contracts structured to manage policy risk, are better positioned to maintain cost stability. For multinational brands, regulatory divergence between markets means sourcing strategies must be flexible enough to account for differing requirements and cost structures without losing consistency in sustainability messaging.
Demand-Side Shifts in Consumer and Corporate Behavior
Demand for ocean recycled yarn is being reinforced by changes on both the consumer and corporate sides. Consumers are increasingly aware of marine plastic pollution, and this awareness translates into preference for products that communicate credible environmental action. At the same time, corporate buyers face pressure from investors, regulators, and supply chain partners to demonstrate measurable progress on circularity and plastic reduction. This dual pressure encourages brands to move beyond limited-edition recycled collections and integrate recycled yarns into broader assortments and staple products.
PW Consulting
Importantly, corporate demand is becoming more specification-driven. Buyers are asking not just for recycled content, but for documented marine sourcing, traceable chain of custody, and certifications that verify environmental additionality. This shift raises the bar for suppliers. Companies that can offer well-documented provenance and consistent quality are more likely to secure long-term partnerships, whereas those relying on vague sustainability claims risk losing credibility as buyer diligence deepens. The commercial opportunity lies in combining verifiable marine sourcing with reliable product performance, rather than treating ocean recycled yarn as a marketing shortcut.
Fleece Knitting Yarn Market
Supply Chain Reconfiguration and Cost Dynamics
The cost structure of ocean recycled yarn is shaped by feedstock premiums, regional pricing differences, and the logistics of collection and processing. Recycled PET pricing varies considerably across major markets, reflecting local collection capacity, demand intensity, and the availability of bottle-grade versus ocean-bound sources. Certified ocean-bound material typically carries an additional premium because of traceability requirements and the perceived value of marine plastic recovery. This premium can be justified when it is tied to clear sourcing stories and certification, but it also means that producers must manage the balance between ethical sourcing and competitive pricing.
Supply chain reconfiguration is also evident in the growing emphasis on traceability and marketplace models that connect collectors with processors and manufacturers. Some organizations are building platforms that aggregate traceable ocean-bound plastics, helping to standardize provenance and reduce fragmentation in sourcing. This approach can lower transaction costs for buyers who need multiple points of verification, while also giving collectors and processors a more predictable path to market. As these models mature, they may help reduce the cost of certified marine feedstock and make ocean recycled yarns more accessible to a wider range of textile applications.
Competitive Landscape and Leading Strategies
The competitive field in ocean recycled yarn is characterized by a mix of established recycled fiber producers, specialized marine-waste companies, and collaborative initiatives that connect collection networks with production capacity. Market concentration is moderate, with the top three firms accounting for roughly a third of revenue and the top five approaching two-fifths. This structure suggests room for both differentiated specialists and integrated players, but it also means that scale, traceability, and partnership networks are becoming increasingly important differentiators.
Unifi has built a recognizable position through REPREVE, including variants made from ocean-bound plastic waste alongside post-consumer bottles and textile waste. Its strategy leans on broad application coverage across apparel, footwear, and performance textiles, supported by sustainability commitments that extend into the next decade. Recent sustainability announcements have reinforced targets for recycled fibers, signaling continued investment in recycled content as a core element of the business. The strength of this approach lies in combining scale with recognizable branding and a wide customer base, which helps embed recycled yarns into mainstream procurement rather than limiting them to niche projects.
Aquafil has carved out a strong identity around ECONYL, regenerated nylon produced from recycled ocean fishing nets and other marine and nylon waste. Its applications span textiles, apparel, and flooring, giving it a diversified end-use base. A notable recent step has been the inauguration of a pilot-scale demonstration plant focused on separating elastic fibers from nylon blends, aimed at enabling further integration of such materials into the ECONYL regeneration system. This move reflects a strategy centered on unlocking harder-to-process marine feedstocks, which can broaden input availability and reinforce the technical leadership narrative that supports premium positioning.
Tide Ocean operates with a focused emphasis on 100 percent ocean-bound plastic recycled polyester yarn in various dtex norms for fashion, bags, shoes, home interiors, and industrial textiles. Its differentiation comes from purity of source story and the breadth of dtex options that allow closer matching to end-use requirements. By maintaining certifications such as GRS and Ocean Bound Plastic standards, the company seeks to make the marine sourcing claim credible and auditable. This positions it as a supplier for buyers who need a clear, verifiable ocean-plastic narrative rather than blended claims.
SEAQUAL Initiative, working with production partners such as Antex and Vica, provides SEAQUAL YARN, a recycled polyester filament yarn that typically combines marine plastic litter with post-consumer PET. Its model emphasizes collaboration across collection, certification, and production, which helps scale marine-based content while keeping it economically viable by blending with established recycled streams. This hybrid approach can make ocean-derived content more accessible to furnishing, apparel, and technical textile markets without requiring purely marine feedstock at full volume.
Other players illustrate different strategic angles. Bureo focuses on nylon yarn made from post-consumer recycled fishing nets, with a strong fit for performance apparel and outdoor gear. BIONIC develops high-performance yarns and fabrics from recovered marine and coastal plastic waste, including specialized constructions for textiles and polymers. Oceanworks operates a marketplace model for traceable ocean-bound plastics, supplying recycled polyester yarns and materials and emphasizing provenance across textiles and components. In Asia, companies such as Zhejiang Haili Environmental Technology and Everest Textile offer recycled polyester portfolios that include ocean-recycled variants for apparel and technical applications, with Everest Textile notably supplying major brands and showcasing traceable sustainable variants at industry events.
Together, these players reveal an evolving landscape shaped by three tendencies. First, differentiation is increasingly anchored in feedstock specificity, traceability, and certifications rather than recycled content alone. Second, scale players are expanding recycled portfolios to cover multiple applications, while specialized firms emphasize marine sourcing stories or niche performance constructions. Third, collaborative and marketplace models are emerging to reduce fragmentation in collection and verification. As the market matures, expect further consolidation among processors seeking scale and compliance efficiency, alongside continued entry by specialists who can unlock new feedstock pathways or serve high-value brand partnerships with strong provenance.
Future Trends and Commercial Opportunities
Over the next three to five years, three trends are likely to define the direction of the ocean recycled yarn market and create distinct opportunities for companies that prepare early.
The first trend is the gradual scaling of marine feedstock supply through better collection infrastructure and blend strategies. As demonstration plants and separation technologies prove out, more fishing nets, marine textiles, and coastal plastic waste can be routed into regeneration systems. This expansion will not happen overnight, but it should reduce the scarcity premium on certified ocean-bound material over time and allow broader application coverage. For producers, the opportunity lies in securing long-term collection partnerships and designing yarn lines that can accommodate variable marine input without compromising quality. For brands, the opportunity is to lock in multi-year supply commitments that stabilize sourcing and support credible sustainability roadmaps.
The second trend is tighter integration of traceability into commercial contracts. Buyers are increasingly treating certification and chain-of-custody documentation as baseline requirements rather than optional extras. This will favor companies that can provide clear, auditable provenance from collection points through yarn production. The commercial upside is stronger customer retention and the ability to command price premiums that are justified by verified environmental additionality. The risk is that any lapse in documentation or certification can quickly undermine buyer confidence, so traceability systems must be treated as core operational infrastructure rather than a marketing layer.
The third trend is regulatory and trade policy divergence across regions, which will continue to shape sourcing economics. Recycled-content mandates, packaging regulation, and import tariffs can each alter the cost and availability of feedstocks in different markets. Companies that build flexible sourcing networks, including regional or nearshore options and contracts that account for policy shifts, will be better positioned to manage cost volatility. At the same time, divergence can create arbitrage opportunities for firms that can move certified material to the markets where recycled-content requirements and buyer willingness to pay are strongest. The uncertainty here is that policy can change quickly, so strategies must be adaptive rather than locked into a single feedstock geography.
These trends point to a market that is moving from early differentiation toward operational maturity. The commercial winners are likely to be those that combine credible marine sourcing with consistent quality, scalable traceability, and resilient supply chain design. For investors and executives, the signal is that ocean recycled yarn is becoming a strategically relevant input category, but one where execution discipline matters as much as ambition.
Strategic Actions for Decision Makers
For manufacturers, the priority is to secure feedstock resilience and traceability capacity. This means developing multi-source collection relationships, investing in certification readiness, and evaluating whether blend strategies can balance marine content with cost stability. Companies should also assess whether their yarn specifications can meet performance requirements across target applications without relying on consumers to accept lower standards in exchange for sustainability claims.
Cotton Yarn Market
For investors, the opportunity is to differentiate between branded narratives and operational credibility. Companies with demonstrable certification practices, scalable feedstock access, and cost structures that can withstand policy and pricing volatility are better positioned for durable growth. Due diligence should focus on the reliability of marine sourcing, the robustness of traceability systems, and the ability to serve multiple end uses rather than a single promotional segment.
For procurement and brand teams, the key is to treat ocean recycled yarn as a sourcing category with both sustainability and performance dimensions. Define clear requirements for content claims, certifications, and quality thresholds before sourcing, and prioritize suppliers that can provide consistent documentation and application-appropriate variants. Long-term partnerships tend to yield better traceability outcomes and more stable pricing than transactional purchasing, especially as certified marine feedstock becomes more contested.
Given the pace of technological, regulatory, and competitive change, timely access to detailed segmentation data, pricing intelligence, and company-level assessments can make the difference between reactive sourcing and proactive strategy. For decision makers seeking deeper breakdowns and customized guidance, the full research report provides a more granular view of market splits, regional dynamics, and actionable recommendations.
For detailed analysis of this topic, please visit the official page: Worldwide Ocean Recycled Yarn Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com