

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Worldwide Landscape Rock Market: 5.45% CAGR Fuels Reshaping Competition
By pmarketresearch, 2026-09-18
Global Landscape Rock Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The worldwide landscape rock market has established itself as a resilient component of the broader landscaping and construction materials sector. Valued at approximately 4,333 million USD in 2020, the market expanded to an estimated 5,650 million USD by 2025, reflecting consistent growth across diverse geographic and application segments. Forward projections indicate the market will reach 8,191 million USD by 2032, supported by a compound annual growth rate of 5.45 percent over the 2026–2032 forecast horizon. This trajectory underscores sustained demand for natural and processed stone materials in outdoor design, infrastructure development, and recreational space creation.
From a structural standpoint, the market exhibits moderate fragmentation. The top three companies collectively account for roughly 12.5 percent of total revenue, while the top five hold approximately 18.2 percent. Such concentration levels suggest that while major players maintain meaningful market share, the landscape remains open to specialized operators, regional distributors, and niche product innovators. The revenue distribution across regions reflects a mature base in North America, complemented by steady demand across Europe and the Asia Pacific, alongside emerging opportunities in Latin America and the Middle East and Africa. Application-wise, residential landscaping continues to represent the largest demand driver, followed by commercial infrastructure and public parks and recreational facilities. By product type, crushed granite and stone, river rock, lava rock, and boulders and decorative stones each serve distinct aesthetic and functional requirements across these end-use segments.
Despite the constructive growth outlook, the industry faces several structural challenges that will shape competitive dynamics over the coming years. First, environmental scrutiny and regulatory tightening around quarrying operations, land reclamation, and water usage are increasingly influencing site approvals and operational costs. Companies must navigate evolving local and state requirements while maintaining supply continuity, which can compress margins and delay expansion timelines. Second, the market's reliance on natural stone extraction creates inherent supply constraints. Geological availability, transportation logistics, and quarry permitting cycles introduce volatility in lead times and pricing, particularly for specialty or imported stone varieties. Third, the residential landscaping segment, while dominant, is sensitive to macroeconomic cycles, housing market fluctuations, and discretionary spending patterns. Shifts in consumer confidence or interest rate environments can quickly alter project pacing and material procurement behavior, requiring suppliers and distributors to maintain flexible inventory and pricing strategies.
These challenges are not insurmountable, but they demand proactive strategic positioning. Operators that invest in sustainable extraction practices, diversify product portfolios, and strengthen downstream distribution capabilities are better equipped to absorb regulatory and demand-side shocks. At the same time, the moderate concentration of the market leaves room for consolidation, partnership models, and targeted acquisitions that can enhance scale, geographic reach, and product differentiation.
Key Demand Drivers and Structural Shifts
Several interconnected forces are reshaping the landscape rock market, creating both pressure and opportunity for stakeholders across the value chain. Understanding these drivers is essential for anticipating where growth will concentrate and which capabilities will differentiate leaders from laggards.
Technological Innovation and Product Differentiation
Advances in crushing, screening, and finishing technologies have expanded the range of available stone profiles, enabling more consistent sizing, improved surface textures, and tailored color variations. Producers are increasingly leveraging precision processing to offer specialized aggregates that meet aesthetic and functional specifications for hardscaping, pool deck surrounds, vertical masonry, and decorative ground cover. In parallel, the adoption of eco-friendly extraction techniques and sustainable quarrying practices is gaining traction among natural stone producers seeking to minimize environmental impact while aligning with buyer expectations for responsibly sourced materials. These innovations are not merely operational improvements; they are becoming competitive differentiators that influence procurement decisions among landscape contractors, designers, and retail distributors.
A notable illustration of this trend is the introduction of premium imported natural stone lines designed for hardscape, pool deck, and vertical masonry applications. Such launches signal a broader industry movement toward higher-margin, design-forward product categories that cater to upscale residential and commercial projects. By emphasizing imported specialty stones and curated finishes, suppliers are capturing demand from buyers who prioritize visual appeal, durability, and project-specific performance over commodity-grade alternatives.
Policy and Regulatory Environment
Regulatory frameworks governing quarry operations, reclamation obligations, and water usage continue to evolve, particularly in regions where residential and commercial development intersect with environmentally sensitive areas. Aggregates and landscape materials face local and state requirements that shape permitting timelines, operational boundaries, and post-extraction land management. Companies that proactively integrate compliance into their operational planning—through responsible site design, water conservation measures, and reclamation commitments—can reduce approval friction and build stronger relationships with regulators and community stakeholders.
At the same time, the growing emphasis on sustainable sourcing is influencing procurement standards among larger contractors and commercial developers. Buyers are increasingly requesting documentation on extraction practices, environmental stewardship, and supply chain transparency. This shift is encouraging producers to adopt more formalized sustainability reporting and to differentiate their offerings based on responsible sourcing credentials, which can become a decisive factor in competitive bids and long-term supply agreements.
Demand-Side Behavior and End-Use Evolution
Consumer and enterprise behavior is shifting toward outdoor spaces that serve multiple functions: aesthetic enhancement, recreational use, and durable hardscaping. Residential landscaping remains the largest application driver, supported by home improvement activity, curb appeal investments, and the popularity of low-maintenance outdoor design. Commercial infrastructure demand is also sustained by urban redevelopment, hospitality projects, and mixed-use developments that incorporate landscaped courtyards, pedestrian pathways, and decorative stone elements. Public parks and recreational facilities contribute additional volume, particularly where municipalities invest in trail systems, green spaces, and community amenities.
Limestone Market
Within this demand environment, buyers are placing greater emphasis on coverage efficiency, material consistency, and installation practicality. For example, landscape rock ground cover is commonly evaluated by square footage coverage at specified depths, while cobble or rubble stone is assessed by coverage per ton. These practical considerations influence product selection and pricing sensitivity, encouraging suppliers to provide clear specifications and reliable volume guidance. The result is a market where technical performance and aesthetic value are increasingly intertwined, and where distributors that can articulate usage parameters gain an edge in customer conversations.
Supply Chain and Cost Structure Dynamics
Supply chain considerations are becoming more prominent as operators manage quarry output, transportation constraints, and inventory positioning across regional markets. North America remains a major market for landscape rock, supported by significant domestic quarrying in the United States and selective imports of specialty stones. This dual structure allows suppliers to balance cost efficiency with product variety, but it also requires careful coordination between extraction schedules, logistics capacity, and downstream fulfillment.
Cost structures are influenced by energy inputs, equipment maintenance, labor availability, and site-specific extraction conditions. In response, several operators are pursuing capacity expansion and operational optimization to improve throughput and reduce unit costs. Recent planning approvals for expanded quarry operations illustrate how companies are seeking to scale production footprints to meet projected demand while improving supply reliability. Such expansion decisions are often driven by the expectation that stronger demand visibility and improved operational scale will support margin stability through the forecast period.
Industry performance signals also point to cautious optimism among aggregates and stone operators. Steady performance in core operations, combined with positive outlooks for the near term, suggests that many producers are navigating current conditions with disciplined cost management and selective investment. This environment favors companies that can align capacity plans with demand signals, maintain inventory flexibility, and respond quickly to regional procurement shifts.
Worldwide Natural Stone Market
Competitive Landscape and Leading Strategies
The competitive landscape of the landscape rock market is characterized by a mix of global aggregates leaders, regional stone specialists, and focused decorative product suppliers. This diversity creates multiple pathways to competitive advantage, depending on whether a company competes on scale, product specialization, geographic coverage, or design-oriented branding.
PW Consulting
Global aggregates leaders such as Holcim, CRH plc, Vulcan Materials Company, Martin Marietta, and Heidelberg Materials bring extensive production capabilities, broad distribution networks, and deep experience in crushed stone and landscape rock supply for construction and landscaping projects. Their scale enables them to serve large commercial infrastructure programs, maintain consistent output across multiple regions, and invest in processing infrastructure that supports a wide range of product grades. For these companies, differentiation often comes from supply reliability, standard product breadth, and the ability to integrate landscape rock offerings within broader aggregates and building materials portfolios.
Regional and specialty players occupy a different strategic space. Companies such as Aggregates International, Polycor Inc., Kafka Granite LLC, RCP Block & Brick, Inc., Techo-Bloc, Yardco Rock & Stone, Euro Quarries, Minick Materials, Basalite Concrete Products, and Boral Limited compete by emphasizing curated decorative aggregates, natural stone quarrying expertise, hardscape product integration, and nationwide or regional delivery capabilities. Their portfolios often include pebbles, chippings, rockery, decomposed granite, flagstone, and complementary concrete or pavers, allowing them to address design-sensitive residential and commercial projects with a more tailored value proposition. For these operators, differentiation is frequently built on product variety, aesthetic positioning, sourcing flexibility, and service responsiveness.
Recent market developments highlight how companies are executing on these strategic paths. The launch of premium imported natural stone lines for hardscape, pool deck, and vertical masonry applications reflects a deliberate move toward higher-value product categories that align with upscale project requirements. At the same time, capacity expansion initiatives, such as planning approvals to significantly increase quarry acreage, demonstrate efforts to strengthen production scale and supply resilience. Alongside these moves, steady operational performance and constructive near-term outlooks among aggregates and stone operators indicate that disciplined execution remains central to navigating demand variability and cost pressures.
The market structure is evolving along several trends. Consolidation is likely to continue where larger players seek to expand regional coverage, acquire specialized product lines, or integrate downstream distribution. At the same time, fragmentation will persist in segments where local sourcing, decorative specialization, and customer intimacy matter most. New entrants and expanding distributors can gain traction by focusing on underserved geographies, importing distinctive stone varieties, or combining landscape rock with complementary hardscape products. The net effect is a competitive environment where scale and specialization are not mutually exclusive; rather, successful companies often blend both by operating efficient core production while cultivating differentiated product and service offerings.
Future Trends and Strategic Implications
Looking ahead over the next three to five years, several trends are likely to shape the direction of the landscape rock market and inform where commercial opportunities will emerge.
One key trend is the continued expansion of design-forward and specialty stone categories. As residential and commercial projects place greater emphasis on outdoor aesthetics, durable hardscaping, and multi-functional recreational spaces, demand for curated finishes, imported varieties, and application-specific products is expected to grow. This creates opportunities for suppliers that can reliably source, process, and distribute distinctive materials while providing clear guidance on coverage, installation, and performance. Companies that invest in product education, specification support, and visual merchandising will be better positioned to capture higher-margin demand.
A second trend is the increasing importance of sustainable sourcing and regulatory readiness as competitive factors. Buyers, contractors, and municipal purchasers are likely to place greater weight on responsible extraction practices, environmental documentation, and long-term site stewardship. Operators that formalize sustainability credentials, adopt eco-friendly extraction techniques, and maintain strong compliance records can use these attributes to strengthen bids, build customer trust, and reduce regulatory risk. This trend also favors partnerships and supply chain transparency, as downstream buyers seek assurance across the sourcing-to-delivery chain.
A third trend is the ongoing alignment of capacity and distribution with regional demand patterns. As housing activity, commercial development, and public space investment fluctuate across markets, suppliers will need to balance production scale with inventory agility. Capacity expansions that improve throughput and reduce lead times can strengthen market position, but they must be paired with demand forecasting and logistics coordination to avoid oversupply or underutilized assets. In this environment, companies that develop flexible distribution models, regional stock positioning, and responsive customer service will be more resilient to localized demand shifts.
These trends carry potential risks and uncertainties. Regulatory changes can alter permitting timelines and operating costs, particularly in areas where quarry expansion intersects with community or environmental concerns. Macroeconomic conditions may affect discretionary residential spending and the pace of commercial construction, creating variability in order flow. Supply disruptions, transportation constraints, and shifts in energy or input costs can also pressure margins. Companies should therefore treat growth planning as conditional on scenario awareness, maintaining flexibility in capacity commitments, product mix, and pricing strategy.
Actionable Guidance for Decision-Makers
For manufacturers and producers, the priority is to align processing capability and product breadth with the growing demand for specialty and design-oriented stone categories. Investing in finishing consistency, curated color and texture options, and clear usage specifications can help capture higher-value demand while supporting customer installation success. At the same time, strengthening sustainable sourcing practices and compliance documentation will increasingly serve as a baseline expectation rather than a differentiator alone.
For investors, the market's moderate concentration and diverse competitive pathways suggest value in evaluating both scaled aggregates operators and specialized decorative stone suppliers. Due diligence should focus on geographic exposure, capacity expansion plans, product mix toward higher-margin categories, and the ability to manage regulatory and supply chain risk. Companies with disciplined cost structures, flexible distribution, and credible sustainability positioning are likely to be better prepared for demand variability and evolving buyer standards.
For procurement teams and distributors, the emphasis should be on supplier reliability, specification clarity, and inventory responsiveness. Understanding coverage parameters, material consistency, and regional availability can reduce project risk and improve customer outcomes. Building relationships with suppliers that offer both dependable core products and distinctive specialty lines can provide a balanced portfolio that serves a wider range of residential, commercial, and public-sector projects.
Given the number of moving parts across regulation, demand cycles, product innovation, and competitive consolidation, timely access to detailed segment data, regional breakdowns, and company-level benchmarking can materially improve planning quality. For decision-makers seeking deeper segmentation, granular regional insights, and customized strategic recommendations, the full PW Consulting research report provides the supporting detail needed to translate these market-level trends into specific investment, sourcing, and growth decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Landscape Rock Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Commercial Encryption Products Market: Why 13.5% CAGR and 15B Scale Redefine Security Strategy by 2032
By pmarketresearch, 2026-09-18
The Commercial Encryption Products Market: Strategic Trends and Commercial Opportunities
The commercial encryption products market has evolved from a niche cybersecurity concern into a foundational layer of digital infrastructure. By 2025, the market has reached an estimated 6.5 billion USD in revenue, with consistent compound annual growth of 13.5 percent projected through 2032. Over the five-year historical window from 2020 to 2025, revenue expanded by nearly 87 percent, reflecting a structural shift rather than a temporary surge. The trajectory ahead points to continued acceleration, with forecasts suggesting the market will exceed 15.7 billion USD by the end of the forecast period. This growth is not evenly distributed across product types or sectors, but the overall magnitude signals that encryption has moved from compliance-driven procurement to strategic investment.
Several characteristics define the current market landscape. The ecosystem remains moderately concentrated, with the top three players capturing roughly a third of total revenue and the top five accounting for just under 43 percent. This concentration leaves substantial room for specialization, regional differentiation, and niche innovation, particularly in segments where performance, assurance, and integration matter more than price. At the same time, the market faces a pivot point driven by certification transitions, quantum readiness expectations, and the growing mismatch between legacy architectures and cloud-native workloads.
Hardware Encryption Devices Market
Key Challenges and Inflection Points
One of the most consequential challenges is the regulatory transition from FIPS 140-2 to FIPS 140-3. The formal move of FIPS 140-2 certificates to a historical list in September 2026 forces commercial encryption products and the systems that embed them to adopt validated modules under the newer standard. For vendors, this is not a simple recertification exercise; it requires re-architecting validation footprints, aligning engineering roadmaps, and addressing procurement cycles that may stall until compliance is confirmed. For buyers, the risk is procurement inertia: legacy deployments that were once acceptable may face audit exposure or sourcing constraints, while new projects must specify FIPS 140-3 from the outset.
A second inflection point is the post-quantum cryptography transition. NIST finalized post-quantum standards in 2024, and CISA published product categories to support adoption in commercial technologies in early 2026. The market is not yet in full implementation mode, but the direction of travel is clear: organizations are beginning to inventory cryptographic dependencies, assess migration paths, and evaluate vendor roadmaps. The challenge is twofold. First, the technical complexity of hybrid deployments and crypto-agility introduces integration risk. Second, the absence of mature commercial tooling and testing frameworks means early movers must navigate uncertainty around interoperability, performance, and total cost of ownership.
A third challenge lies in workload dispersion. Encryption is no longer confined to perimeter networks or on-premises storage. Data protection requirements now span distributed cloud environments, hybrid identity architectures, edge devices, and payment ecosystems that must balance assurance with latency and throughput. Suppliers that cannot offer scalable key management, integration with cloud services, and modular assurance profiles will find themselves squeezed by both performance requirements and procurement expectations. The markets leading players are responding with certification breadth, cloud-optimized hardware, and software-centric data protection, but the structural tension between assurance depth and deployment agility remains unresolved.
Key Drivers Shaping Market Momentum
Market growth is being propelled by a convergence of technical, regulatory, and demand-side forces. The most visible driver is cryptographic assurance modernization. The shift toward FIPS 140-3 and the emergence of post-quantum standards are reshaping specification language and procurement requirements. Recent vendor activity makes this acceleration tangible. Utimaco achieved FIPS 140-3 Level 3 certification for its u.trust GP HSM Se-Series in May 2026, positioning the company as the only vendor with full FIPS 140-3 coverage across general-purpose and payment HSM portfolios. In December 2025, Thales secured NATO Secret classification for its Luna Network HSM 7 alongside FIPS 140-3 Level 3 validation. These milestones illustrate how high-assurance certification is becoming a competitive differentiator, especially in environments where data sensitivity spans commercial, government, and defense-adjacent use cases.
Demand-side behavior is changing in parallel. Enterprise data protection strategies are shifting from perimeter-based controls to pervasive, identity-aware encryption integrated with broader data security platforms. Regulatory exposure in financial services, healthcare, and public-sector operations continues to raise the baseline for key management and data-at-rest protection. At the same time, business leaders are pressing for faster deployment cycles, cloud-native integration, and reduced operational friction. The result is a market that values not only cryptographic strength but also manageability. Certification becomes a proxy for trust, and trust becomes a procurement gate.
Supply-side dynamics are increasingly shaped by cloud adoption and partnership models. Hardware security modules are no longer treated as standalone appliances in every context. Cloud-optimized HSM families are being selected to support managed cloud HSM services, extending encryption capabilities into elastic environments while maintaining key isolation. Marvell's LiquidSecurity HSM family, chosen by Microsoft for Azure Cloud HSM services in August 2025, reflects this pattern. The broader implication is that encryption infrastructure is being embedded into platform ecosystems, not simply layered as an independent product. For commercial encryption providers, this opens opportunities in integration design, attestation, and managed key services, but it also requires tighter alignment with cloud vendor roadmaps and operational expectations.
Emerging Influences Across the Ecosystem
Three additional dynamics are reinforcing these drivers. First, crypto-agility is moving from a technical aspiration to a procurement criterion. Buyers are increasingly interested in architectures that can adapt to evolving algorithms without wholesale replacement, especially as post-quantum migrations are planned. Second, product certification breadth is expanding beyond traditional enterprise and financial use cases into IoT and connectivity domains. The April 2026 announcement of FIPS 140-3 validation for cryptographic modules on Digi Accelerated Linux-based IoT and connectivity solutions signals that assurance requirements are reaching edge and embedded environments where security has historically been harder to standardize. Third, geopolitical and sector-specific assurance needs are creating differentiated demand. Classification achievements such as NATO Secret for select HSM products illustrate that high-assurance commercial encryption can unlock adjacent markets where data sensitivity and supply-chain trust are paramount.
PW Consulting Information & Electronics Research Center
Together, these drivers are pushing the market toward a more layered structure: certified hardware for high-assurance root operations, software and platform capabilities for data protection and key lifecycle management, and cloud-integrated services for scalability. Growth will be determined not only by how many organizations buy encryption products, but by how many can absorb them into workflows without compromising performance, compliance, or operational continuity.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a handful of established players with strong certification portfolios and a growing emphasis on integration with enterprise and cloud ecosystems. Thales Group maintains a broad commercial encryption and key management position through Luna Network HSMs, payShield payment HSMs, and CipherTrust data security solutions, with recent validation activity reinforcing its high-assurance credentials. Utimaco has concentrated on full-portfolio FIPS 140-3 coverage across general-purpose and payment HSMs, a differentiating posture in markets where procurement teams want a single, consistently validated vendor footprint. Entrust continues to anchor its commercial position in nShield HSMs for key protection, code signing, and enterprise encryption, appealing to organizations that value high-assurance key use cases within broader identity and data protection strategies.
Homomorphic Encryption Market
Futurex occupies a manufacturing-centric positioning with FIPS 140-2 Level 3 and PCI HSM validated products produced in the United States, an advantage in contexts where supply-chain provenance and domestic manufacturing are evaluation factors. IBM brings encryption software, Guardium data protection, and HSM offerings into the enterprise commercial data protection conversation, leveraging platform adjacencies and data security integration. Microsoft competes in a different layer of the stack, with Azure Key Vault and encryption services that incorporate HSM-backed key management for cloud data protection, effectively embedding encryption into a broader cloud platform. Marvell contributes cloud-optimized HSMs, notably through its selection for Azure Cloud HSM services, aligning hardware capability with hyperscale deployment requirements.
Strategic Positioning and Differentiation
Across these players, differentiation is emerging along several axes. Certification scope is one of the most visible. Vendors that can demonstrate consistent FIPS 140-3 validation, payment HSM validation, or elevated classification may secure preference in regulated environments where audit confidence is directly tied to specification language. Product breadth is another axis: players offering both general-purpose and payment HSMs, or hardware combined with software data protection, can address multiple procurement categories within a single relationship. Integration capability is becoming equally important. The ability to connect key management to cloud services, enterprise identity, and data security platforms reduces operational friction and strengthens the value proposition beyond raw cryptographic assurance.
Manufacturing origin and supply-chain narrative also matter in specific segments. Domestic manufacturing, transparent validation histories, and clear product category alignment can influence procurement decisions in government-adjacent, critical infrastructure, and payment environments. At the same time, cloud-native deployments are rewarding providers that can offer modular, scalable hardware or managed services that fit into elastic architectures rather than rigid appliance models.
Structural Evolution in the Market
The market is likely to evolve through both consolidation and niche differentiation. Larger platforms with broad data security, identity, and cloud ecosystems may expand their encryption footprint through product integration or selected partnerships. At the same time, specialized vendors with focused certification portfolios, strong payment or HSM credentials, and clear supply-chain value can thrive by serving high-assurance segments that are less price-elastic. New entrants are unlikely to displace incumbents through pure scale, but they may carve out positions in specific use cases such as cloud-optimized key services, modular assurance for hybrid deployments, or crypto-agility tooling that simplifies transition planning. The real contest will be over specification influence: vendors that help buyers translate compliance requirements into operational architectures will shape demand more than those that compete solely on feature parity.
Future Trends to Watch
Over the next three to five years, three trends are likely to shape the commercial encryption market most directly. First, FIPS 140-3 compliance will become a default procurement baseline rather than a differentiator, and the competitive advantage will shift toward breadth, speed of validation, and the ability to support hybrid and cloud-native deployments. Vendors with completed portfolios and clear migration support will gain preference in regulated sectors, while late movers risk exclusion from specification lists.
Second, post-quantum readiness will move from policy direction to operational planning. Migration inventories, crypto-agility architectures, and hybrid key management approaches will increasingly appear in enterprise and public-sector roadmaps. Commercial opportunity will emerge for providers that can simplify transition paths, support hybrid modes, and offer clear documentation and testing for algorithm flexibility. The associated risk is fragmentation: without common deployment patterns or interoperability expectations, early implementations may require expensive integration work and create vendor lock-in concerns.
Third, encryption will continue to converge with platform services. Managed cloud HSM, integrated key protection, and data security platforms will become the primary consumption model for a growing share of commercial workloads. This trend favors players that can embed security into workflows and reduce operational overhead, but it also raises questions about long-term control of cryptographic assets, audit visibility, and portability across environments. The opportunity lies in architectures that preserve assurance while making protection easier to consume; the risk lies in over-reliance on opaque or tightly coupled services that complicate governance.
Strategic Actions for Decision-Makers
For manufacturers and product vendors, the near-term priority is to align certification roadmaps with procurement reality. Completing FIPS 140-3 validation, clarifying payment and general-purpose coverage, and communicating migration support can influence specification outcomes in regulated demand channels. Vendors should also invest in integration and cloud compatibility, because assurance alone is unlikely to win deals where operational fit is weak. Differentiation should be expressed through portfolio consistency, deployment flexibility, and clear guidance for post-quantum transition planning.
For investors and strategic partners, the most informative signals are certification milestones, ecosystem partnerships, and evidence of adoption in cloud or platform services. Companies that combine validated hardware with usable key management and data protection integration are better positioned to capture recurring commercial demand than those competing primarily on price. Portfolio exposure should be assessed not only by product footprint but by the ability to serve regulated, high-assurance, and cloud-scale segments simultaneously.
For procurement and security leaders, the practical move is to treat encryption as a lifecycle decision rather than a point purchase. Early specification of FIPS 140-3 requirements, evaluation of crypto-agility options, and review of vendor support for post-quantum transition planning will reduce downstream risk. Buyers should also assess integration fit with existing cloud, identity, and data security environments to avoid new operational bottlenecks. Where demand is complex or region-specific, detailed segment intelligence can shorten evaluation cycles and improve specification accuracy. The broader market dynamics, segment differentiation, and vendor-level developments can be explored in depth through a complete market study that provides the detailed segmentation, competitive tracking, and scenario-based guidance needed for tailored planning.
For detailed analysis of this topic, please visit the official page: Commercial Encryption Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tonsil Cancer Treatment Market: Why the $996M Base & 6.42% CAGR Upend Strategy
By pmarketresearch, 2026-09-18
Tonsil Cancer Treatment Market: Strategic Shifts & Commercial Opportunities (2025-2032)
The Current Market Landscape and Core Challenges
The global market for tonsil cancer treatment is undergoing a significant structural transformation, driven by evolving therapeutic paradigms, shifting demographic patterns, and a maturing pharmaceutical ecosystem. Valued at approximately 1,000 million USD in the 2025 base year, the market has demonstrated consistent expansion, with historical growth trajectories reflecting increased diagnostic awareness, refined staging protocols, and broader access to advanced oncology interventions. Forecasts indicate sustained momentum through the end of the decade, supported by a steady compound annual growth rate and clear upward trajectory in total revenue. The market’s expansion is not merely a function of population growth or incidence rates; it reflects a fundamental recalibration of how oropharyngeal and tonsil malignancies are approached clinically, commercially, and financially.
Beneath these aggregate figures, several structural tensions are reshaping competitive priorities. First, pricing resilience and reimbursement uncertainty remain central concerns across most mature healthcare systems. Oncology portfolios increasingly rely on on-patent therapies that command premium pricing, yet the lifecycle economics of pharmaceutical products are well understood by payers and health technology assessment bodies. Once patent protection expires, generic and biosimilar entrants typically trigger rapid price compression, and procurement frameworks are increasingly designed to steer utilization toward lower-cost alternatives through tiered cost-sharing mechanisms. For manufacturers and care providers alike, this creates a narrow window to demonstrate differentiated clinical value, secure formulary positioning, and build durable reimbursement narratives before margin erosion accelerates.
Second, the regulatory and trade environment has introduced new supply chain and operational contingencies. Recent policy shifts have altered how pharmaceutical imports are evaluated, particularly for branded and patented products. Manufacturers without active domestic production commitments face heightened cost exposure and potential access friction in certain key markets. This development is prompting strategic reassessment of manufacturing footprints, logistics planning, and portfolio localization strategies, especially for companies whose tonsil cancer or broader head and neck oncology offerings depend on cross-border supply networks.
Third, clinical adoption pathways are becoming more nuanced as treatment algorithms move beyond one-size-fits-all cytotoxic regimens. The convergence of immunotherapy, targeted biologics, and conditionally active antibody-drug conjugates is changing the standard of care conversation, but integration into real-world clinical practice depends on biomarker stratification, multidisciplinary coordination, and institutional readiness. Healthcare systems and specialty centers must navigate the balance between innovation adoption and operational feasibility, particularly when newer modalities require specialized administration, monitoring, or patient selection criteria.
Collectively, these dynamics define a market that is expanding, but not uniformly. Growth is increasingly concentrated among players who can align product development with reimbursement strategy, adapt supply chain architectures to policy volatility, and support clinical adoption with robust evidence generation. The competitive battlefield is shifting from simple therapeutic availability toward value demonstration, access optimization, and integration readiness.
Key Drivers Shaping Market Trajectory
Several interlocking forces are accelerating change within the tonsil cancer treatment landscape. Understanding their interaction is essential for anticipating where commercial value will accumulate and which capabilities will separate resilient organizations from reactive ones.
Therapeutic Innovation and Biomarker-Aligned Oncology
The most consequential driver is the ongoing evolution of treatment architecture for head and neck malignancies, including tonsil and oropharyngeal disease. Immunotherapy has established itself as a core pillar in recurrent, metastatic, and increasingly perioperative contexts. Rather than replacing established modalities, the prevailing model is one of integration: checkpoint inhibitors and targeted biologics are being positioned alongside surgery, radiation, and chemotherapy in ways that aim to improve outcomes while moderating toxicity. This shift is particularly relevant in HPV-associated disease, where biological characteristics create opportunities for more selective targeting and refined patient stratification.
Recent regulatory milestones have reinforced this direction. The approval of pembrolizumab for perioperative use in resectable locally advanced head and neck squamous cell carcinoma, including PD-L1-positive tumors, marked a meaningful expansion of immunotherapy utility beyond later-stage settings. The therapeutic relevance extends to tonsil cancer where disease biology and staging overlap substantially with broader oropharyngeal indications. Simultaneously, conditionally active biologics and antibody-drug conjugates are advancing through late-stage development with a focus on HPV-positive populations. Alignment between developers and regulators on pivotal trial design indicates growing confidence in differentiated mechanisms of action, particularly where conventional treatment pathways leave residual unmet need.
PW Consulting
This innovation trajectory changes the commercial calculus in two ways. First, it raises the importance of companion diagnostics, biomarker testing infrastructure, and pathology workflow integration. Second, it increases the premium on clinical evidence that goes beyond median endpoints to address durability, quality of life, and toxicity management, all of which influence formulary decisions and provider adoption.
Policy, Regulation, and Access Frameworks
Regulatory and reimbursement dynamics are not merely compliance considerations; they are strategic determinants of market access and revenue durability. The 2025 approval expansion for perioperative immunotherapy underscored how regulatory decisions can reshape treatment intent, moving certain modalities earlier in the care continuum and altering competitive positioning across therapy classes. At the same time, the broader pricing environment emphasizes lifecycle management. Payers are increasingly attentive to value demonstration, and procurement structures are designed to encourage substitution when exclusivity lapses. This creates pressure on manufacturers to plan for the full product arc, including post-patent positioning, differentiated formulations, and combination strategies that may extend commercial relevance.
Trade policy adds another layer of complexity. Import-related measures that affect branded and patented pharmaceutical products can alter landed costs, supply continuity, and market entry timing. Companies with significant exposure to cross-border distribution are being forced to evaluate whether localized production, regional stocking strategies, or alternative sourcing models are warranted. This is especially salient for players whose tonsil cancer portfolios intersect with broader head and neck oncology franchises and whose manufacturing decisions affect multiple indications simultaneously.
Demand-Side Evolution in Care Delivery
Patient and provider behavior is shifting as clinical education improves and multidisciplinary care models mature. Awareness of HPV-associated oropharyngeal disease has increased attention to early presentation, staging accuracy, and risk stratification. At the same time, treatment decisions are increasingly made by coordinated teams rather than single-specialty decision makers. This favors therapies that fit cleanly into established surgical, radiation, and medical oncology workflows while minimizing disruption to patient throughput.
Demand is also being shaped by expectations around tolerability and functional outcomes. In cancers affecting the head and neck region, treatment burden can have pronounced effects on swallowing, speech, nutrition, and overall quality of life. Interventions that can preserve efficacy while reducing acute or long-term toxicity gain traction not only in clinical discussions but also in patient preference and provider referral patterns. Consequently, the market increasingly rewards solutions that couple clinical performance with manageable administration and supportive care integration.
Cost Structures and Competitive Realities
Cost dynamics are being redefined by several factors: the concentration of spending on newer on-patent therapies, the operational costs associated with advanced treatment administration, and the financial pressure on care sites to manage episode-related resource use. Hospital settings continue to represent the largest end-user segment, reflecting the complexity of surgical and multidisciplinary management. Specialty clinics and ambulatory surgical centers play a growing role where treatment pathways allow for shorter recovery times, streamlined administration, or outpatient-compatible protocols.
Mapping below outlines the core drivers and their commercial implications.
Worldwide Canine Mammary Tumor Treatment Market
- Therapeutic innovation : Expands addressable use cases, increases reliance on biomarker infrastructure, and raises evidence standards for adoption.
- Regulatory and reimbursement shifts : Accelerates earlier-line integration for some modalities, intensifies lifecycle pricing pressure, and strengthens the need for differentiated value narratives.
- Demand-side behavior : Favors multidisciplinary compatibility, tolerability, and functional outcomes, influencing referral patterns and site selection.
- Cost and supply dynamics : Encourages manufacturing localization, portfolio resilience planning, and reimbursement-aligned procurement strategies.
Competitive Landscape and Leading Strategies
The competitive environment in tonsil cancer treatment is defined by a mix of large oncology franchises, targeted biotech developers, and supportive-care participants, all operating within a moderately concentrated market. A handful of firms account for a substantial share of revenues, and CR3 and CR5 concentration indicators reflect the structural advantage held by companies with established immunotherapy platforms, broad commercialization capabilities, and integrated oncology portfolios. Concentration does not imply stagnation, however. In fact, the current phase is characterized by deliberate differentiation, where scale is necessary but not sufficient, and where pipeline novelty, regulatory timing, and access strategy increasingly determine relative positioning.
Among the most prominent participants, Merck & Co. has reinforced its position through a high-profile regulatory milestone for perioperative pembrolizumab in resectable locally advanced head and neck squamous cell carcinoma, including PD-L1-positive disease. The move is strategically significant because it broadens the immunotherapy conversation earlier in the treatment journey, where patient populations are larger and clinical decision-making is more highly coordinated. This positioning supports the company’s broader oncology narrative by demonstrating applicability across the care continuum rather than restricting relevance to later-line settings.
Bristol Myers Squibb continues to leverage nivolumab as an established immunotherapy option for recurrent and metastatic disease. Its strategic advantage lies in clinical familiarity, integration within existing treatment algorithms, and the durability of evidence built over prior adoption cycles. In a market where provider comfort and institutional protocols influence prescribing, such entrenched positioning can serve as a stable foundation even as newer modalities emerge.
Eli Lilly and AstraZeneca contribute distinct value propositions within the broader head and neck oncology ecosystem. Lilly’s involvement spans supportive agents and pipeline candidates relevant to squamous cell carcinomas, reflecting an interest in both direct treatment and the surrounding care architecture. AstraZeneca’s emphasis on durvalumab and combination-oriented research illustrates the industry’s appetite for regimen-level innovation, where the opportunity is not simply a single agent but a coordinated therapeutic sequence or combination that may improve outcomes in defined patient subsets.
Roche’s cetuximab remains relevant in combination with radiation or chemotherapy for advanced disease, including oropharyngeal cases. Its continued role reflects the persistence of targeted anti-EGFR strategies in selected settings and the practical reality that established biologics can retain clinical utility even as the innovation frontier advances. Sanofi’s oncology portfolio elements and supportive care contributions similarly underscore the importance of surrounding therapies that help manage complex cases and improve treatment tolerability.
The most notable competitive shift, however, comes from specialized developers pursuing biologically selective approaches. BioAtla’s conditionally active antibody-drug conjugate is advancing toward pivotal development in HPV-positive oropharyngeal disease, with regulatory alignment supporting potential accelerated pathways. This type of asset is strategically important because it targets a biologically defined subgroup and represents a move toward conditional activity design, where therapeutic action is intended to be more selective in the tumor environment. If clinical outcomes confirm the promise of such approaches, the commercial impact could include tighter biomarker-linked adoption, new partnering dynamics, and heightened value assessment requirements from payers and providers alike.
PDS Biotechnology’s HPV-focused clinical program reflects a parallel trend: vaccine-based and immune-priming strategies aimed at populations with viral-driven disease biology. This approach complements the broader momentum around HPV-associated oropharyngeal cancers and signals continued interest in modalities that address etiology as well as tumor burden. The presence of such programs in the competitive landscape suggests that future differentiation will increasingly depend on biology-driven targeting and regimen-level evidence rather than class-level presence alone.
Several structural trends are shaping how this landscape evolves.
- Integration over isolation : Companies that can position therapies within multidisciplinary pathways, including surgery, radiation, and supportive care, are likely to gain stronger adoption footholds.
- Biomarker-driven segmentation : HPV status, PD-L1 expression, and other molecular markers are becoming central to treatment selection, raising the stakes for diagnostic partnerships and evidence generation.
- Lifecycle and access planning : As exclusivity timelines shape pricing trajectories, leaders are preparing for generic and biosimilar pressure by building differentiated indications, combination strategies, and access narratives early.
- Manufacturing and geopolitical readiness : Trade and import-related contingencies are pushing firms to evaluate domestic production options and supply chain resilience as part of commercial strategy, not just operational logistics.
- Clinical trial leadership as influence : Academic and clinical centers that shape pivotal studies can influence adoption standards, guideline inclusion, and the credibility of new regimens, which indirectly affects competitive outcomes.
The competitive field is therefore moving toward a hybrid structure: large players maintain scale, breadth, and established relationships, while focused innovators compete on biological precision, trial design, and potential accelerated regulatory pathways. Over time, the most successful organizations will likely be those that can combine scientific differentiation with reimbursement fluency and real-world implementation support.
Future Trends and Market Outlook (2026–2032)
Looking ahead, three trends are likely to shape the next phase of market development. The first is the continued migration of immunotherapy and targeted modalities into earlier lines of care where clinically appropriate. This does not eliminate surgery, radiation, or chemotherapy; rather, it reframes them within more personalized sequences. For commercial players, this trend expands the scope of strategic planning beyond late-stage rescue therapy and into perioperative and consolidation contexts, where patient volume, treatment duration, and combination economics can be materially different.
Cancer Treatment Drugs Market
The second trend is the growing importance of biomarker and diagnostic ecosystems. As therapeutic selection becomes more dependent on HPV status, PD-L1 expression, and potentially other molecular features, the value of reliable testing, clear reporting, and coordinated pathology workflows will increase. This creates opportunities not only for diagnostic providers and companion test developers, but also for therapy manufacturers that can demonstrate how biomarker-guided use improves outcomes, reduces unnecessary toxicity, and strengthens reimbursement justification. Organizations that treat diagnosis as an integral part of the commercial model, rather than a separate transaction, will be better positioned to secure durable adoption.
The third trend is institutional adaptation to cost, access, and supply pressures. Healthcare systems and specialty sites will continue to optimize care delivery around tolerability, throughput, and total episode cost. At the same time, manufacturers will need to manage lifecycle risk more explicitly, anticipating biosimilar and generic entry, trade-related cost impacts, and the need for localized or regionally resilient supply. The likely outcome is a market in which financial and operational resilience become as important as clinical innovation. Products and programs that can navigate access complexity, support site-level efficiency, and maintain continuity under policy volatility will have a structural advantage.
Potential risks and uncertainties remain. Clinical development in biomarker-selected populations can be promising but also fragile, with regulatory and reimbursement outcomes depending on the strength and generalizability of trial results. Pricing pressure may intensify if healthcare budgets face renewed constraints or if payers become more assertive in value-based contracting. Trade and manufacturing policy could also create uneven access conditions across regions, complicating global launch strategies and potentially favoring companies with more flexible operational footprints. Finally, the pace of guideline adoption and multidisciplinary integration may vary by setting, meaning that the same clinical advancement can translate into different commercial outcomes depending on local care infrastructure.
Strategic Implications for Decision Makers
For executives and investors navigating this market, several priorities stand out.
For Manufacturers and Developers
Invest in biomarker-aligned development and evidence generation that supports earlier-line use where appropriate. Build reimbursement narratives that connect clinical differentiation with real-world value, including toxicity reduction, functional outcomes, and treatment sequencing. Evaluate manufacturing and supply chain localization proactively, particularly if portfolio exposure crosses multiple oncology indications and import-related cost risks are material.
For Investors
Focus on assets and companies with clear biomarker strategy, strong regulatory alignment, and credible lifecycle plans. Differentiate between broad franchise stability and innovation-driven optionality; both can be valuable, but they carry different risk profiles. Pay attention to supply chain readiness and access positioning, since commercial success increasingly depends on execution beyond clinical efficacy alone.
For Procurement and Care Providers
Prioritize therapies and service models that integrate efficiently into multidisciplinary workflows, support predictable utilization patterns, and align with site-level cost management. Build internal capability for biomarker-informed decision-making and evaluate total episode impact rather than unit price in isolation. Where possible, align contracting strategies with anticipated lifecycle changes, including the transition from branded exclusivity to lower-cost alternatives.
The tonsil cancer treatment market is expanding within a landscape defined by therapeutic innovation, biomarker-driven segmentation, access complexity, and supply-side recalibration. Organizations that understand these interconnections will be better equipped to allocate capital, shape pipelines, and plan for the commercial realities of the next several years. For teams seeking deeper segmentation data, company-level profiling, and tailored scenario planning across regions and therapy classes, detailed research resources are available for further exploration.
For detailed analysis of this topic, please visit the official page: Worldwide Tonsil Cancer Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Scar Treatment Supplies Market: Why 10% CAGR and 48.95 Billion in 2032 Matter
By pmarketresearch, 2026-09-18
Worldwide Scar Treatment Supplies Market: Strategic Trends and Commercial Opportunities
1. Market Landscape and Core Challenges
The worldwide market for scar treatment supplies has demonstrated sustained expansion over the past five years, reaching an estimated valuation of approximately 25.1 billion USD in the base year 2025. Historical trajectories from 2020 through 2025 reveal a consistent upward climb, reflecting growing clinical acceptance and broader consumer awareness of scar management solutions. Forward projections for the period 2026 to 2032 indicate that this momentum will continue, with the sector anticipated to approach 49 billion USD by the end of the forecast window. This evolution corresponds to a compound annual growth rate of roughly 10.0 percent, signaling a mature yet still accelerating demand environment. The scale and velocity of growth suggest that scar care has transitioned from a niche wound care adjunct to a distinct commercial category with its own supply chains, regulatory pathways, and competitive dynamics.
Scar Tape Market
Despite the favorable headline numbers, the industry is navigating a set of structural challenges that will shape competitive outcomes over the next several years. The first challenge lies in the fragmentation of product classifications and quality expectations across regions. Medical-grade silicone sheets, hydrogels, topical gels, compression garments, and adhesive tapes each occupy different regulatory and clinical positioning, which complicates market entry, manufacturing standardization, and cross-border distribution. Companies must balance the need for broad product portfolios against the operational burden of maintaining consistent quality and documentation across multiple device categories and therapeutic claims.
A second challenge stems from the tension between clinical efficacy and consumer accessibility. Scar treatment supplies serve a dual audience: healthcare professionals managing post-surgical, burn, and trauma outcomes, and consumers seeking non-invasive options for aesthetic or comfort-related concerns. This duality creates divergent purchasing behaviors, price sensitivities, and expectations around evidence. Suppliers that rely primarily on clinical credibility may find growth constrained if they cannot translate that credibility into user-friendly packaging, clear usage instructions, and retail or e-commerce visibility. Conversely, products positioned primarily for convenience risk scrutiny if clinical differentiation is perceived as thin.
A third challenge is the pressure on margin structures as the market matures. With a meaningful portion of revenue concentrated among a limited number of established players, smaller manufacturers and new entrants face rising costs for materials, regulatory compliance, and channel access. At the same time, larger organizations are increasingly looking to consolidate capabilities, streamline product lines, and push for value-based pricing. The result is a market where scale, regulatory fluency, and brand trust increasingly determine who can protect profitability while still expanding share.
2. Key Drivers of Market Change
Technological innovation remains one of the most powerful forces reshaping scar treatment supplies. Advances in silicone formulation, adhesion engineering, and barrier performance have improved the practical usability of sheets and gels, making them easier to apply, more comfortable for extended wear, and more reliable across different skin types and scar ages. Products that combine occlusion and hydration in a way that supports flattening, softening, and fading of raised scars have become central to both prophylactic and treatment-oriented use. The broader shift toward medical-grade materials that can be used on new and older scars—from surgery, burns, and trauma—has expanded the addressable use cases and encouraged product refinement rather than simple commodity competition.
Scar Treatment Market
Regulatory and policy dynamics are also acting as a major driver, particularly as classification expectations tighten in key markets. In the United States, silicone gel sheeting and hydrogel products for scar management are commonly regulated as Class I medical devices, with many products exempt from premarket notification but still subject to establishment registration and general controls. This framework lowers the procedural barrier for certain entrants while still demanding disciplined quality systems. In the European Union, the environment has moved toward more rigorous conformity assessment for a subset of scar and wound care products, with select gel and wound care items achieving Class IIb medical device certification under the Medical Device Regulation. Such developments elevate the importance of regulatory readiness, post-market surveillance, and documented safety and performance, especially for companies seeking to scale across multiple jurisdictions.
Demand-side change is accelerating the market as well. Clinicians and patients increasingly view scar management as a standard part of post-procedure care rather than an optional afterthought, especially following surgical interventions, burn recovery, and trauma-related healing. At the same time, the consumer side of the market is becoming more informed and more proactive, with growing interest in non-invasive options that can reduce itch, discomfort, and visible prominence. This dual demand expansion is pushing suppliers to develop offerings that satisfy professional procurement requirements while remaining accessible enough for direct-to-consumer and retail channels. The result is a broader product spectrum, from physician-exclusive lines to over-the-counter topical solutions, each targeting a different point in the care journey.
Supply chain and cost considerations are exerting a more subtle but persistent influence. Manufacturers of silicone sheets, gels, compression garments, and adhesive tapes must manage material availability, production consistency, and packaging requirements while responding to shifting channel expectations. The growing emphasis on branded and locally distributed portfolios has encouraged some companies to invest in manufacturing reliability and formulation consistency as differentiators, rather than competing primarily on price. At the same time, operations that can align procurement, regulatory documentation, and distribution logistics are better positioned to withstand volatility and maintain service levels for both clinical and consumer customers.
3. Competitive Landscape and Leading Strategies
The competitive field in scar treatment supplies is defined by a mix of established multinational players and specialized manufacturers, each pursuing a distinct route to differentiation. Several large organizations anchor their positions through well-known silicone sheeting and gel products designed for the management of hypertrophic and keloid scars. Smith & Nephew, for example, emphasizes self-adhesive silicone gel sheets intended to soften, flatten, and fade new and old red or raised scars arising from surgery, burns, and trauma. Mölnlycke Health Care takes a related but technically distinct approach with self-adherent soft silicone dressings built around a proprietary skin-friendly adhesive concept, supporting both prevention and treatment on old and new scars, including prophylactic use on closed wounds. These product narratives highlight how incumbents use clinical familiarity, application convenience, and prophylactic positioning to reinforce repeat usage and professional trust.
Specialist manufacturers are competing by sharpening the technical story around their materials. Bio Med Sciences focuses on silicone-based scar management products that incorporate a patented technology blending silicone with Teflon-like properties, offering adhesive gel sheets in clear, fabric, and foam variants for the prevention and reduction of hypertrophic and keloid scars. Biodermis and Newmedical Technology similarly concentrate on silicone-based sheets and gels for post-surgical and trauma-related scar reduction, while Enaltus markets a widely recognized silicone gel for topical treatment aimed at reducing the appearance of raised scars. This concentration on material science and application specificity allows smaller firms to compete on perceived performance and clinical fit rather than scale alone.
Other participants are expanding the therapeutic palette beyond traditional silicone sheeting. Sonoma Pharmaceuticals has built a presence around hypochlorous acid-based scar gels that aim to manage scars by reducing itch, pain, and appearance while supporting wound healing. Perrigo and Merz Pharmaceuticals contribute to the broader topical and dermatology-oriented side of the category, with Perrigo focusing on over-the-counter and branded scar treatment offerings through its portfolio, and Merz positioning topical scar solutions within a wider dermatology context for aesthetic and medical management. Scar Heal, operating under a physician-focused brand identity, offers silicone scar gels and sheets including exclusive lines for scar refinement. Together, these players illustrate a market where differentiation is being built through both material-based claims and broader care-pathway positioning.
Recent regulatory activity underscores how competitive positioning is increasingly tied to compliance capability as well as product performance. Sonoma Pharmaceuticals, for instance, completed the transition of its Epicyn scar gel and related items to EU Medical Device Regulation Class IIb certification for wound care, scar, and atopic dermatitis treatments in late 2024. Moves like this signal thatEU market access and credibility can depend on more advanced conformity assessment for certain product types, which in turn affects who can scale efficiently in that region. At the same time, the generally lighter regulatory pathway for many silicone hydrogel and gel sheeting products under FDA product codes continues to support a diverse set of entrants in the U.S., even as establishment registration and general controls remain baseline expectations.
PW Consulting
Looking at the broader evolution of the landscape, consolidation and portfolio rationalization appear likely to intensify. Larger organizations may pursue acquisitions or internal streamlining to reduce overlap, strengthen channel access, and build more coherent brand architectures across medical and consumer segments. At the same time, fragmentation is likely to persist in specialized niches where formulation, adhesion properties, comfort, and physician relationships create defensible positions. New entrants will probably continue to appear, but their success will increasingly depend on regulatory readiness, evidence-backed claims, and the ability to distribute through channels that match their target audience. The market is therefore moving toward a pattern where scale, compliance, and brand trust reinforce one another rather than operating as separate competitive dimensions.
4. Future Trends and Commercial Implications
Over the next three to five years, one likely trend is the continued sharpening of product differentiation around material performance and user experience. As clinicians and consumers compare options more systematically, products that offer easier application, better adhesion control, improved comfort over longer wear periods, and consistent outcomes across scar types will gain advantage. This creates commercial opportunities for manufacturers that invest in formulation refinement, packaging that supports adherence, and clear guidance for both prophylactic and treatment use. It also raises the stakes for suppliers whose products are perceived as interchangeable, since price competition alone is unlikely to sustain margins in a growing but increasingly discerning market.
A second trend is the deepening of regulatory stratification across regions and product types. While some categories will continue to benefit from lighter premarket requirements, others will face more demanding conformity, documentation, and post-market expectations. This uneven landscape creates opportunities for companies that build regulatory competence as a core capability rather than a back-office function. Firms that can navigate device classification, maintain robust quality systems, and adapt product claims to local expectations will be better positioned to expand internationally and to present themselves as lower-risk partners for distributors and clinical buyers. The unpredictability lies in how quickly regulators may adjust expectations and how consistently those adjustments are applied across product variants.
A third trend is the growth of hybrid distribution models that blend professional channels with consumer access. As scar care becomes more embedded in post-procedure routines and more visible in retail and online channels, companies will need to manage the tension between clinical credibility and consumer convenience. This opens opportunities for portfolios that are structured by use case—prophylaxis after surgery or trauma, management of hypertrophic and keloid scars, and consumer-focused topical solutions—while preserving consistent quality standards. The risk is brand dilution or channel conflict if product lines are not clearly differentiated by audience, evidence level, and intended use. Companies that can maintain disciplined segmentation while still reaching multiple purchasing paths are more likely to capture growth without eroding trust.
5. Strategic Options for Decision-Makers
Manufacturers should treat regulatory readiness, material consistency, and channel fit as interconnected priorities rather than isolated functions. Investing in formulation and adhesion performance can support differentiation, but that advantage only translates into share if the product is positioned clearly for its intended use and supported by documentation that matches the expectations of the markets served. Companies expanding across regions may benefit from sequencing their regulatory strategy, prioritizing markets where their product classification and quality systems align most naturally with local requirements before scaling into more demanding environments.
For investors, the key question is whether a company’s growth is backed by defensible differentiation or by broadly commoditized supply. Businesses with strong formulation expertise, recognizable clinical use narratives, and the ability to meet evolving device-classification expectations are better placed to sustain margins as the market expands. Caution is warranted where expansion depends mainly on volume without corresponding improvements in compliance, brand trust, or channel access, since these are the areas where competitive pressure is most likely to compress returns.
For procurement and supply chain leaders, the priority is to balance availability, quality assurance, and category fit when selecting suppliers. Evaluating manufacturers on the basis of regulatory status, product consistency, and suitability for specific scar types and care settings can reduce risk while supporting better outcomes. It also helps to structure sourcing around clearly defined use cases, so that procurement decisions reflect whether the need is prophylaxis, ongoing management of raised scars, or consumer-oriented topical support.
For organizations that need a more granular view of segment dynamics, regional splits, and company-level positioning, a detailed research report can provide the segmentation breakdowns, competitive profiles, and scenario analysis needed to translate these strategic themes into specific plans. The broader market trajectory suggests that those who act early on regulatory preparation, product differentiation, and channel strategy will be better placed to capture the next phase of growth in scar treatment supplies.
For detailed analysis of this topic, please visit the official page: Worldwide Scar Treatment Supplies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Educational and Training Software Market: Why 15.12% CAGR Reshapes Strategy
By pmarketresearch, 2026-09-18
Navigating the EdTech Inflection Point: Strategic Trends in the Educational and Training Software Market
Market Landscape and Core Challenges
The global educational and training software market has firmly entered a phase of accelerated expansion. Revenue climbed from approximately 175.4 billion USD in 2020 to 355.6 billion USD by 2025, reflecting sustained institutional adoption and shifting learning paradigms. Projections indicate the market will continue compounding at a 15.12 percent CAGR through 2032, reaching an estimated 952.84 billion USD. This trajectory is not merely a post-pandemic normalization but a structural reallocation of how organizations invest in knowledge delivery, skill development, and academic infrastructure.
Cloud-based deployment has become the dominant architecture, reflecting broader enterprise preferences for scalability, remote accessibility, and reduced on-premise maintenance overhead. The sector is broadly distributed across K-12 education, higher education, and corporate training, with each segment driving distinct procurement cycles, compliance requirements, and user experience expectations. In terms of application, learning management systems, student information systems, assessment and testing software, and content creation and simulation tools occupy significant portions of the value chain. Geographic adoption remains led by North America, followed by Europe and Asia Pacific, while Latin America and the Middle East and Africa represent faster-growing but still earlier-stage commercialization environments.
Despite this momentum, the market faces three structural challenges that will shape competitive outcomes over the next decade. First, integration fragmentation continues to burden end users. Institutions and enterprises frequently operate disjointed platforms for administration, instruction, assessment, and corporate skill tracking. Without interoperable data standards, organizations struggle to create unified learner profiles, measure continuous competency development, or automate cross-platform workflows. This friction raises total cost of ownership and slows the realization of analytics-driven decision making.
Second, data privacy and AI governance are becoming decisive procurement filters. Educational software now routinely processes sensitive demographic, performance, and behavioral data. Simultaneously, generative AI capabilities are embedded into tutoring, assessment design, content summarization, and administrative automation. Buyers are increasingly scrutinizing model transparency, data retention practices, bias mitigation, and compliance with emerging regulatory frameworks. Vendors that cannot articulate clear governance positions risk exclusion from RFPs, particularly in public sector and higher education procurement.
Third, the market is reaching a saturation inflection in mature segments. Base-level learning management and content delivery tools are becoming table stakes, pressuring vendors to differentiate through outcomes rather than feature lists. Buyers are asking harder questions about whether platforms demonstrably improve completion rates, skill transfer, instructor efficiency, or workforce readiness. This shift rewards vendors that can connect software deployment to measurable organizational impact, while exposing those that rely on perception-based marketing or fragmented point solutions.
For executives and investors, the implication is clear. Growth alone will not guarantee durable advantage. The winners will be organizations that navigate interoperability demands, embed responsible AI into product design, and prove value through outcome metrics rather than platform breadth alone.
Key Drivers Reshaping Demand and Value Creation
Four interconnected forces are driving the market’s next phase of expansion, each reshaping how software is designed, sold, and valued.
Technology Innovation and AI-Infused Learning Workflows
Generative AI has moved from experimental feature to core product architecture. Platforms are now integrating AI-assisted lesson planning, adaptive tutoring, automated rubric generation, multilingual content localization, and intelligent summarization of dense learning materials. These capabilities reduce the manual workload of educators and corporate trainers while enabling more personalized learning paths at scale. The shift is most visible in tools that support test preparation, workplace compliance training, and skills-based upskilling, where rapid content iteration and individualized pacing create tangible efficiency gains.
Equally important is the move toward AI-supported instruction rather than AI replacement. Educational institutions and employers are exploring tools that augment human facilitation, provide real-time feedback, and help managers identify skill gaps earlier in the learning journey. This balanced positioning is becoming a design principle for platforms seeking wide adoption across risk-averse and pedagogy-sensitive environments.
Policy, Regulation, and Institutional Standardization
Regulatory and policy environments are increasingly shaping procurement behavior. Public agencies and multilateral organizations are publishing guidance on responsible AI use in education, emphasizing transparency, age-appropriate design, and safeguards around student data. In parallel, regional frameworks are beginning to classify certain AI applications as higher-risk, particularly where biometric or emotion-recognition technologies intersect with learning environments. These developments do not slow adoption outright, but they do raise the bar for compliance, documentation, and vendor accountability.
At the same time, policy-driven workforce initiatives are expanding demand for accessible training tools. Government-backed literacy and AI readiness programs are surfacing as new adoption channels, especially when delivered through lightweight, mobile-friendly, or text-based formats that can reach workers outside traditional classroom settings. Such initiatives create downstream demand for content authoring, assessment, and tracking capabilities that can plug into broader skills infrastructure.
Demand-Side Shifts in Learning Behavior and Workforce Expectations
Learner expectations are changing faster than many legacy platforms can accommodate. Students, professionals, and managers increasingly expect seamless mobile experiences, modular microlearning, and visible connections between training and career progression. In corporate environments, learning is no longer treated as a separate HR function but as part of continuous performance enablement. This is driving demand for platforms that connect learning activity to role readiness, internal mobility, and compliance tracking.
In academic settings, there is growing emphasis on hybrid instruction models, credit-bearing digital credentials, and tools that reduce administrative load without compromising instructional quality. The line between formal education and professional training is blurring, encouraging platforms that can serve both contexts with consistent identity, assessment, and reporting experiences.
Education Software Market
Cost Structure and Deployment Economics
Economic pressures are reinforcing cloud-first adoption while also changing how organizations justify software spend. Budget holders want platforms that lower IT maintenance burdens, scale across campuses or enterprise units, and reduce content production costs through reusable templates, automated localization, and AI-assisted authoring. The economics of content creation are especially relevant in fast-moving technical fields where courseware can become outdated quickly. Vendors that shorten content update cycles and enable non-specialist staff to maintain materials are gaining an operational advantage.
At the same time, the cost of switching is rising as programs deepen their dependency on integrated ecosystems. Once a platform becomes the system of record for enrollment, assessment, or compliance, migration becomes politically and operationally difficult. This dynamic is strengthening retention for incumbents with broad deployment footprints, while making it harder for new entrants to displace established workflows without a clearly superior value proposition.
Competitive Landscape and Leading Strategies
The market remains comparatively fragmented at the top, with no single vendor holding dominant share. Industry concentration is moderate, with the top three players accounting for roughly 19.45 percent of revenue and the top five reaching about 29.8 percent. This structure leaves substantial room for differentiation, niche specialization, and regional expansion, but it also intensifies pressure on vendors to define a sharp strategic position rather than compete across every segment simultaneously.
Customer Support Training Software Market
Several strategic archetypes are emerging among leading players. Broad online learning platforms continue to scale by pairing content breadth with credentialing and professional signaling. Their advantage lies in audience reach, employer partnerships, and the ability to connect learning to career outcomes. Gamified and mobile-first learning apps occupy a different position, using engagement mechanics to lower barriers to entry and expand into adjacent subjects beyond their original focus. Their growth increasingly depends on converting casual users into sustained learning habits and leveraging platform ecosystems for cross-subject expansion.
Learning management system providers remain central to institutional adoption, competing on usability, integration depth, and support for diverse teaching and training models. Their differentiation often comes from how well they serve blended environments, simplify instructor workflows, and connect with student information or assessment systems. In parallel, corporate and skills-focused platforms compete on personalized learning paths, compliance coverage, leadership development, and technology skills curricula. These vendors are positioning learning as an operational capability rather than a one-off training event.
Large technology providers are layering educational capabilities onto existing productivity and cloud ecosystems. Their strategy typically emphasizes AI-enabled tools, identity and collaboration infrastructure, and low-friction adoption through familiar interfaces. By embedding learning assistance, content summarization, and classroom or workforce support tools into broader software environments, they aim to reduce switching costs and increase platform stickiness. Eu-based and multi-regional regulatory considerations are also shaping how these providers design data handling and AI features for education use cases.
Recent product and program activity illustrates how quickly the landscape is evolving. Major providers have launched educator-focused programs that bundle AI-supported teaching tools, content creation features, and improved access controls for instructional workflows. Other vendors have expanded personalized learning journeys and acquired AI content capabilities to speed creation and adaptation of training materials. In parallel, public-sector workforce initiatives are pairing free AI literacy resources with accessible delivery formats, expanding the reach of digital training beyond traditional buyers. The OECD’s recent exploration of generative AI design principles in education further underscores the growing expectation that learning tools should be effective, transparent, and context-aware.
The competitive trend points toward both consolidation and specialization. Larger platforms are likely to pursue integrations that cover identity, content, assessment, analytics, and administrative workflows in a more unified stack. At the same time, specialized providers will continue to thrive by solving narrow problems exceptionally well, such as high-stakes assessment, simulation-based training, language acquisition, or compliance-heavy corporate programs. New entrants are most likely to succeed where they can address underserved segments, offer superior UX for specific user groups, or provide interoperable tools that reduce integration burdens for existing ecosystems.
Future Trends and Commercial Opportunities
Over the next three to five years, three trends are likely to define where value concentrates. First, AI will become a standard layer across learning workflows, but differentiation will shift from “having AI” to “using AI responsibly and effectively.” Platforms that demonstrate measurable improvements in instructor efficiency, learner completion, and assessment quality will command stronger positioning than those that merely showcase automation features. Commercial opportunities will arise for vendors that can package AI capabilities as trustworthy, auditable, and aligned with institutional governance requirements.
Second, interoperability and unified learner data will become strategic purchasing criteria. Buyers will increasingly favor solutions that can exchange data cleanly across administrative, instructional, and workforce systems. This creates openings for middleware, analytics layers, and platforms designed with open integration as a core architectural choice. Companies that reduce the integration tax for schools, universities, and enterprises will be better placed to expand within accounts and cross-sell adjacent modules.
Third, the boundary between education and workforce training will keep eroding, especially in skills-based hiring and internal mobility programs. Organizations will look for tools that support continuous credentialing, competency mapping, and scenario-based simulation. This trend favors platforms that can serve both academic and corporate audiences with adaptable content models and reporting frameworks. There is also opportunity in lightweight, high-reach training formats that support large-scale literacy and upskilling initiatives, especially where accessibility and low friction matter more than feature density.
Risks remain significant. Regulatory uncertainty around AI in education could alter procurement requirements or limit certain use cases, particularly where sensitive data or high-stakes decisions are involved. Overreliance on automation may trigger pushback if learners or instructors perceive quality degradation or excessive surveillance. Macroeconomic pressure could also compress discretionary budgets, making outcome proof and total cost of ownership more important than novelty. Vendors and buyers alike will need to balance innovation with governance, integration, and measurable impact.
Strategic Actions for Decision-Makers
For platform builders and product leaders, the priority is to design for interoperability and governance from the start. Products should make it easy to exchange learner data, support modular content creation, and provide transparent controls for AI-assisted features. Differentiation should be anchored in workflows that reduce instructor or administrator burden while improving learning outcomes, not simply in the presence of advanced features.
For investors, due diligence should focus on retention economics, integration depth, and evidence of outcome-based value. The most durable opportunities are likely to sit in segments where software becomes embedded in daily operations, compliance, or credentialing, rather than in discretionary point tools. It is also important to assess how prepared portfolio companies are for evolving AI regulation and data-handling expectations, since these factors will increasingly influence procurement velocity.
For procurement and strategy teams, selection criteria should expand beyond feature checklists. Evaluations should include data portability, integration effort, AI governance documentation, and the vendor’s ability to demonstrate measurable improvements in efficiency or learner performance. Pilots should be structured to test whether a platform can reduce administrative load, support personalized learning or training paths, and fit within broader systems already in use.
Given the speed of product launches, regulatory updates, and adoption shifts across regions and sectors, high-level market narratives are no longer sufficient for planning. Decision-makers benefit from detailed segmentation data, company-level benchmarking, and scenario analysis that connects technology roadmaps with procurement realities. Those seeking a fuller view of segmentation dynamics, regional demand patterns, and vendor positioning can use the complete PW Consulting market research report to inform investment, product, and procurement decisions with greater precision.
PW Consulting Information & Electronics Research Center
For detailed analysis of this topic, please visit the official page: Educational and Training Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Ultra Low Temperature Freezers Medical Market: 5.42% CAGR Redefining Growth
By pmarketresearch, 2026-09-18
Global Ultra Low Temperature Freezers for Medical Market: Strategic Shifts and Commercial Pathways
The Worldwide Ultra Low Temperature Freezers for Medical Market has entered a phase of measured but meaningful expansion. Valued at approximately USD 915.0 Million in 2025, the market is projected to reach USD 1,324.0 Million by 2032, translating to a steady CAGR of 5.42 percent across the 2026–2032 forecast horizon. The trajectory from 2020 through 2025 reflects a compounding pattern of procurement normalization, biobank infrastructure build-outs, and sustained clinical sample preservation needs. What was once a niche laboratory equipment category has matured into a strategically critical component of healthcare logistics, pharmaceutical cold-chain operations, and biomedical research ecosystems. The growth curve is no longer driven purely by volume expansion; it is increasingly shaped by performance expectations, regulatory compliance, and total cost of ownership considerations.
Despite the clear upward trajectory, the sector faces structural inflection points that will separate value creators from commoditized players. First, energy intensity remains a stubborn operational burden. Legacy -86°C units draw substantial power over extended operating cycles, and hospitals, research facilities, and biobanks are increasingly auditing lifecycle operating costs rather than focusing solely on upfront capital expenditure. Second, regulatory scrutiny has tightened considerably. Equipment used to store vaccines, human cells, tissues, and high-value pharmaceutical products is now evaluated through stricter quality management, validation, and certification frameworks, raising the compliance burden for manufacturers and buyers alike. Third, the market is moving away from one-size-fits-all procurement toward application-specific configurations. Clinical environments demand robust temperature stability and rapid recovery, biobanks prioritize long-duration sample integrity and footprint optimization, while pharmaceutical and biotech operators focus on traceability, audit readiness, and integration with broader quality systems. These converging pressures are redefining what “competitive” means in this equipment category.
Key Demand Drivers Reshaping the Market
Technological Innovation and Performance Differentiation
Technological advancement is no longer a secondary feature; it is becoming a primary purchasing criterion. Manufacturers are deploying dual-cooling architectures, improved insulation materials, and smarter temperature management logic to reduce energy consumption while preserving sample safety. The emphasis has shifted from simply achieving low setpoints to delivering consistent temperature uniformity, faster recovery after door openings, and lower failure risk during extended unattended operation. Energy-efficient models that meaningfully cut daily power draw are gaining preference in hospital and laboratory modernization programs, particularly where facilities are under pressure to align equipment upgrades with broader sustainability and operating-cost targets. The practical implication for buyers is clear: total cost of ownership now outweighs sticker price in multi-year planning, and manufacturers that can quantify energy savings alongside reliability metrics are earning stronger consideration.
Regulatory and Compliance Evolution as a Market Filter
The regulatory environment is reshaping both product design and procurement decision-making. In the European Union, ultra-low temperature freezers intended for medical use are regulated as Class IIa medical devices under EU MDR, requiring compliance frameworks that support the storage of vaccines, human cells, and tissues. Meanwhile, the FDA’s new Quality Management System Regulation, which became effective in early 2026, has introduced additional validation expectations for equipment used to store high-value medical and pharmaceutical products. These developments are elevating the importance of documented quality systems, traceable manufacturing practices, and certified performance validation. For manufacturers, this means compliance capability is now a competitive moat rather than a baseline expectation. For procurement teams, it means vendor selection must increasingly account for certification status, validation support, and ongoing quality management discipline, especially in regulated clinical and biobanking environments.
Demand-Side Shifts in Healthcare and Life Sciences Operations
Demand is being reshaped by how biological materials are generated, stored, and utilized across the healthcare and life sciences value chain. Biobanking activity continues to expand as research programs, translational medicine initiatives, and population-scale sample collections require secure long-term preservation. Hospitals and clinics are reinforcing specimen storage practices for diagnostics, therapeutic workflows, and blood product management. Pharmaceutical and biotech organizations are investing in controlled storage environments that support development pipelines, stability programs, and clinical material handling. At the same time, organizations are seeking equipment that integrates more smoothly into quality operations, offering clearer documentation, reliable alarm pathways, and configurations aligned with specific storage profiles. The result is a more sophisticated buyer mindset: procurement decisions are increasingly tied to operational resilience, sample integrity risk reduction, and alignment with institutional quality standards.
Supply Chain and Cost Structure Realignment
Cost structures across the sector are being influenced by component availability, manufacturing scale, logistics complexity, and the premium associated with certified medical-grade production. Suppliers that maintain disciplined quality management systems, including ISO 13485 alongside ISO 9001, are better positioned to serve clinical and biobanking customers who require consistent process control and auditable manufacturing practices. At the same time, energy efficiency has become a leverage point for cost optimization, since operating expense over a freezer’s service life can dominate ownership economics. This has encouraged a broader reassessment of procurement timing, fleet replacement cycles, and regional sourcing strategies. For companies evaluating market entry or expansion, the opportunity lies not only in hardware specification but also in delivering verifiable efficiency gains, dependable after-sales support, and compliance-ready documentation that reduces friction for regulated buyers.
Medical Refrigerator Market
Competitive Landscape and Strategic Positioning
Incumbent Strengths and Differentiation Playbooks
The market is moderately concentrated, with leading players competing on reliability, compliance readiness, application fit, and energy performance rather than price alone. Thermo Fisher Scientific maintains a broad commercial footprint and a comprehensive ULT portfolio that emphasizes temperature stability, energy efficiency, and compliance-oriented design for medical, pharmaceutical, and biobanking use. PHC Corporation, including its PHCbi brand, has built recognition around dual-cooling technology and dependable long-term storage for biological samples, vaccines, and medical specimens, with recent launches reinforcing energy-efficient variants for research and clinical environments. Eppendorf continues to emphasize precise temperature control and sample safety for life sciences laboratories, while Haier Biomedical has expanded its presence with energy-efficient ULT models designed for hospital and clinical certification requirements. Helmer Scientific focuses on medical-grade storage for sensitive biological materials, blood products, and pharmaceuticals, and B Medical Systems has positioned itself around EU MDR Class IIa certification for vaccines, human cells, tissues, and laboratory samples. Other participants, including Arctiko, Stirling Ultracold, NuAire, So-Low, Labcold, BINDER, LAUDA, Corepoint Scientific, and Accucold, contribute further specialization across laboratory, blood bank, and healthcare storage applications.
Competitive Dynamics and Market Evolution
The competitive landscape is evolving along three interrelated directions. First, differentiation is increasingly anchored in verifiable efficiency and regulatory readiness. Products that can demonstrate lower energy consumption, robust temperature recovery, and clear certification alignment are gaining salience with buyers managing both operating budgets and compliance obligations. Second, the market is showing signs of both consolidation and fragmentation depending on segment and region. Larger incumbents leverage scale, service networks, and portfolio breadth to defend positions in high-volume clinical and biobanking channels, while smaller or regionally focused manufacturers compete through specialized configurations, responsive support, and tailored application solutions. Third, new entrants and product innovations are pressuring incumbents to keep advancing efficiency and usability. Recent launches such as PHC Corporation of North America’s TwinGuard ECO series illustrate how dual-cooling technology and enhanced energy performance are being used to reinforce long-term sample protection for medical and pharmaceutical facilities. The broader implication is that competitive advantage will increasingly depend on the ability to combine dependable cooling performance with compliance support, energy economics, and service reliability.
Forward Outlook: Trends Shaping the Next 3–5 Years
Efficiency as a Default Requirement, Not a Premium Feature
Over the next several years, energy-efficient ULT freezers are likely to shift from preferred options to baseline expectations in hospital, laboratory, and biobank procurement. As operating cost pressure persists and sustainability considerations become more embedded in facility planning, models that substantially reduce daily energy use will be favored in fleet upgrades and replacement cycles. The commercial opportunity lies in equipment that can deliver measurable efficiency gains without compromising temperature stability or sample protection. Manufacturers and distributors that can provide transparent performance comparisons and lifecycle cost framing will be better positioned to influence purchasing decisions.
Regulatory Compliance as a Defining Purchase Criterion
Compliance expectations will continue to deepen as quality management requirements and medical-device classification frameworks become more familiar to procurement and quality teams. Buyers will increasingly expect documented validation support, certified manufacturing practices, and equipment designed to fit into regulated storage workflows for vaccines, cells, tissues, and pharmaceutical materials. This trend creates a dual opportunity: manufacturers that invest early in certification readiness, quality system alignment, and validation documentation can command stronger procurement credibility, while buyers that align equipment selection with compliance pathways can reduce downstream audit and operational risk.
PW Consulting
Application-Specific Solutions and Regional Diversification
Demand will continue to diverge by use case, with biobanks, hospitals and clinics, pharmaceutical and biotech companies, and academic research institutes each prioritizing different performance attributes. Biobanks will emphasize long-term sample integrity and storage density, clinical settings will prioritize dependable temperature control and service responsiveness, and pharmaceutical and biotech users will focus on quality-system compatibility and traceability. Regionally, growth is likely to remain broad-based, with North America, Europe, and Asia Pacific each presenting distinct procurement rhythms, regulatory nuances, and infrastructure needs. The strategic opportunity is to move beyond generic product positioning and align offerings with the operational realities of each application and geography. The main uncertainty is the pace and consistency of regulatory interpretation across markets, which could affect product requirements, validation expectations, and time-to-market for new models.
Strategic Implications for Decision-Makers
For Manufacturers and Suppliers
Product strategy should balance performance credibility with compliance readiness and operating economics. Prioritize demonstrable energy efficiency, temperature stability, and service support, while ensuring that quality management and certification pathways are clearly articulated for regulated customers. Differentiation will increasingly come from how well a product fits into clinical, biobanking, or pharmaceutical workflows, not just from nominal cooling specifications.
For Investors and Strategic Partners
Investment attention should focus on companies with defensible compliance positions, efficiency-driven product roadmaps, and credible service and support models. The most durable value creation is likely to come from players that can combine reliable hardware with documentation, validation support, and total cost of ownership advantages that resonate with regulated buyers. Market growth is steady, but share gains will depend on execution in compliance, efficiency, and application alignment.
Ultra-low Temperature Freezers Market
For Procurement and Operations Leaders
Procurement decisions should evaluate ULT freezers through a lifecycle lens, weighing energy consumption, temperature reliability, certification status, validation support, and service responsiveness alongside initial capital cost. Aligning equipment selection with the intended application—clinical storage, biobanking, pharmaceutical handling, or research—will reduce operational friction and improve long-term sample integrity risk management. Requesting performance data, compliance documentation, and efficiency comparisons should become standard practice in vendor evaluation.
For organizations seeking deeper segmentation, regional procurement dynamics, and customized strategic recommendations, the full PW Consulting market analysis provides expanded data and targeted guidance across market size trajectories, competitive positioning, and application-specific demand patterns.
For detailed analysis of this topic, please visit the official page: Worldwide Ultra Low Temperature Freezers for Medical Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Oil & Gas Digital Rock Analysis Market: Why 12.44% CAGR Rewrites 2032 Planning
By pmarketresearch, 2026-09-18
The Digital Rock Analysis Market: Strategic Shifts and Emerging Opportunities in a High-Growth Sector
Market Snapshot and Core Challenges
The global oil and gas digital rock analysis market has transitioned from an experimental niche to a structural component of reservoir evaluation and production planning. Valued at approximately $412 million in 2020, the market expanded to $741 million by 2025, with projections indicating a trajectory toward nearly $1.7 billion by 2032. This growth reflects a compound annual growth rate of around 12.4 percent, signaling sustained demand rather than a temporary technology cycle. The expansion is driven by the industry's growing reliance on pore-scale insights to de-risk development decisions, particularly in complex plays where traditional core analysis alone no longer delivers the speed or resolution operators require.
Despite this momentum, the sector faces several structural challenges that will shape how value is captured over the next few years. First, data integration and workflow fragmentation persist as a significant bottleneck. Digital rock workflows typically require stitching together high-resolution imaging outputs, laboratory measurements, and simulation environments that often operate in silos. Organizations that lack standardized pipelines spend considerable time and capital reconciling data formats, validating model fidelity, and translating simulations into operational decisions. This friction raises the effective cost of adoption and can slow the return on investment even when the underlying technology is mature.
Second, talent and interpretation expertise remain constrained. Digital rock analysis produces rich, multi-dimensional datasets, but the value of those datasets depends heavily on the ability to interpret them within the context of reservoir geology, fluid behavior, and field development strategy. There is a limited supply of professionals who can bridge imaging science, petrophysics, and production engineering. As a result, some operators hesitate to scale digital rock programs beyond pilot studies because they are uncertain how to institutionalize the insights across asset teams.
Third, the market is navigating a shift in the meaning of "value" itself. Rising carbon management expectations, regulatory cost structures, and the need to optimize recovery from mature and unconventional reservoirs are changing the questions operators ask. Digital rock analysis is no longer evaluated solely on its ability to improve production forecasts; it is increasingly assessed on whether it can support lower-risk development designs, extend field life, and provide credible data for storage or fluid retention studies. Companies that frame their capabilities only around conventional reservoir characterization risk missing the broader set of decisions now being made.
PW Consulting
These challenges create a market that is expanding quickly but remains selective about where and how digital rock tools are deployed. The operators and service providers that succeed are likely to be those that reduce integration friction, strengthen interpretive credibility, and align their offerings with the full range of decisions facing asset teams today.
Key Drivers Shaping Market Expansion
Technology innovation continues to be the most visible driver of growth in digital rock analysis. High-resolution imaging, dual-energy CT scanning, and advanced NMR capabilities are improving the fidelity of pore-scale models, while software platforms are becoming more capable at translating 3D rock images into flow simulations and relative permeability estimates. The practical impact is that teams can evaluate multiple scenarios faster and with more detail than was possible when core analysis and modeling were more sequential. A recent example of this direction is the opening of a dedicated unconventional core analysis laboratory in Dammam, Saudi Arabia, which was equipped with high-resolution dual-energy CT scanning and high-frequency NMR to support advanced digital rock characterization. This kind of facility investment signals that digital rock analysis is moving from isolated software capability to integrated laboratory-plus-simulation workflows, especially where unconventional reservoirs require more detailed pore-structure understanding.
Digital Refractometers Market
A second driver is the convergence of laboratory data and digital workflows into faster, more repeatable delivery models. The industry is showing increasing interest in compressing the timeline between physical measurement and digital simulation. Collaborations that combine pore-scale digital rock analysis with laboratory-measured data illustrate this trend, including an initiative in the U.S. that aims to integrate the two approaches so that comprehensive digital rock solutions can be delivered in weeks rather than months while enabling parallel pore-scale simulations. This compression matters because reservoir teams often need timely answers during appraisal, well placement, or development optimization. When digital rock services can be delivered as part of an integrated, faster workflow, they become easier to justify within active project cycles.
Policy and regulatory dynamics are also reshaping demand. Carbon management priorities are influencing how subsurface assets are evaluated, not just for production but also for long-term containment, storage, and emissions-related decision-making. In 2025, Colorado’s Geologic Storage Stewardship Enterprise Board set an annual stewardship fee of $0.08 per metric ton of CO2 injected for Class VI wells, reinforcing the idea that geologic storage requires ongoing oversight and credible characterization. At the same time, carbon pricing mechanisms continue to expand globally, with carbon pricing covering around 28 percent of emissions in 2025 and mobilizing significant public budget resources. South Africa also increased its carbon tax rate to ZAR 236 per tCO2e in 2025 as part of its planned trajectory. These policy developments do not directly dictate digital rock demand, but they raise the stakes for subsurface understanding, especially where operators must demonstrate performance, containment, or efficiency under tighter cost and compliance conditions.
The demand side is evolving as well. Operators are under pressure to improve recovery efficiency, reduce uncertainty in unconventional reservoirs, and extend the productive life of mature assets. Digital rock analysis supports these objectives by providing pore-scale context that can help refine reservoir models, optimize stimulation design, and inform enhanced oil recovery studies. At the same time, there is growing interest in applying similar characterization approaches to carbon capture and sequestration projects. One recent example is a strategic collaboration focused on integrated carbon capture and sequestration services that combine digital rock analysis with geochemical, PVT, and monitoring techniques. This extension of digital rock analysis beyond conventional oil and gas development suggests that the addressable use cases are widening as organizations look for integrated subsurface insight across multiple objectives.
Finally, cost structure and supply chain considerations are influencing adoption patterns. Digital rock analysis can reduce the number of expensive, iterative physical tests by allowing teams to screen scenarios digitally before committing to laboratory or field programs. That does not eliminate the need for high-quality core analysis, but it can change the balance of spending toward more targeted experimental work and more extensive digital evaluation. For companies operating in multiple regions, the ability to access capable imaging and analysis infrastructure, or to partner with providers that can deliver consistent workflows across assets, is becoming more important than simply owning software licenses. The practical effect is a market in which value is increasingly determined by workflow integration, turnaround speed, and interpretative reliability rather than by any single technical feature.
Competitive Landscape and Leading Strategies
The competitive environment in digital rock analysis is defined by a mix of oilfield service majors, specialized core analysis firms, instrument and software providers, and smaller niche players with strong scientific or regional positioning. The market is moderately concentrated, with the top three companies accounting for roughly 56 percent of market share and the top five approaching 74 percent. This concentration suggests that scale, brand trust, and established laboratory-plus-digital infrastructure provide a meaningful advantage, but it also leaves room for differentiated specialists, especially where specific applications or geographies create unmet needs.
A clear strategic pattern among leading players is the move toward integrated digital rock offerings that combine physical measurement with modeling and simulation. Companies in the oilfield services space are increasingly emphasizing workflows that link core and fluid data with digital rock characterization so that reservoir insights can be generated faster and with greater scenario flexibility. For example, providers with digital special core analysis capabilities are positioning themselves around the ability to create 3D reservoir models that support rapid flow performance simulation across multiple scenarios, with the differentiator being not just imaging quality but also the speed and interpretability of the final deliverables. Peer firms offering fast pore-scale analysis and integrated workflows are pursuing a similar end: shortening the path from laboratory data to reservoir description and optimization. This integration-focused positioning is especially relevant for operators who need to make decisions within active development timelines rather than rely on long, sequential studies.
A second strategic grouping is centered on instrumentation, imaging, and software platforms. Companies that supply high-resolution microscopy, 3D visualization, and digital rock physics software are competing on the strength of their analytical environments, including capabilities for pore-structure quantification, non-destructive simulation, and relative permeability analysis under enhanced oil recovery conditions. These providers often serve as enabling technology partners for both service companies and operator-led research teams. Their competitive advantage lies in platform maturity, the ability to handle complex image data, and the capacity to support specialized workflows such as two-phase flow simulation and special core analysis on 3D rock images. In this layer of the market, differentiation comes from how well the software supports the scientific and engineering questions that follow once high-quality images are available.
The third competitive dynamic is the emergence of specialists expanding into adjacent applications, particularly carbon capture and sequestration. Some companies are building integrated suites that pair core and fluid analysis with digital rock characterization and monitoring techniques. This strategy broadens the commercial context for digital rock analysis and positions these firms to participate in projects where subsurface characterization must support both resource recovery and storage-related decisions. At the same time, regional and scientifically focused companies are carving out places in the market by emphasizing local laboratory capability, specialized imaging, or strong domain expertise in reservoir characterization. This mix of global scale players and focused specialists creates a landscape where customers can choose between broad integrated providers and more targeted partners depending on their project priorities.
Looking ahead, the competitive landscape is likely to continue evolving along three lines. First, consolidation and collaboration will remain important as companies seek to cover the full chain from imaging to simulation to interpretation without forcing customers to assemble fragmented solutions themselves. Second, differentiation will increasingly depend on turnaround time, workflow standardization, and the ability to support parallel simulations and faster delivery, especially in contexts where decisions are time-sensitive. Third, new entrants and specialists may gain traction by focusing on underserved application areas or regions, particularly where local laboratory capacity, carbon management needs, or unconventional resource complexity create specific demand. The most resilient competitors will be those that can demonstrate both technical depth and practical delivery advantages, rather than competing solely on the basis of imaging or software features in isolation.
Forward Outlook: Trends Likely to Shape the Next Three to Five Years
One of the most important trends is the continued movement from standalone digital rock modeling toward integrated, faster workflows that connect laboratory data, imaging, and simulation in a single decision-support pathway. As more collaborations and facility investments bring these capabilities closer together, the market is likely to reward providers that can reliably compress timelines while maintaining scientific rigor. The commercial implication is that digital rock analysis will become more embedded in routine reservoir characterization and project delivery, rather than remaining a specialized study reserved for high-uncertainty cases.
A second trend is the widening application set beyond conventional production optimization. Environmental and carbon management considerations are expanding the role of subsurface characterization, and digital rock analysis is well positioned to support decisions related to fluid behavior, containment, and storage evaluation. The addressable market may grow not only because more projects require pore-scale insight, but also because the same analytical approaches can be framed for multiple objectives. Organizations that can articulate how their digital rock capabilities support both recovery and subsurface stewardship are likely to find a broader set of opportunities than those limiting their messaging to a single use case.
A third trend is the rising premium on interpretability and trust. As models become more detailed and more widely used, operators will increasingly ask not just whether a simulation is possible, but whether its outputs can be confidently translated into development actions, risk assessments, and field decisions. That creates an opportunity for providers and internal teams that invest in validation practices, domain expertise, and clear communication of uncertainty. The most valuable offerings will likely be those that help users understand what the digital rock results mean in operational terms, not simply those that produce the most complex images or simulations.
At the same time, there are real uncertainties to monitor. Adoption may slow in organizations that struggle to standardize workflows or lack the expertise to integrate digital rock outputs into decision-making. Regulatory and cost environments can also shift the priority of projects, affecting how quickly new characterization programs are sanctioned. And as more players bundle services, the market may see pricing pressure and competitive overlap, particularly where offerings become less differentiated. Companies should therefore treat growth potential as real but conditional on their ability to deliver consistent, defensible, and operationally relevant results.
Practical Implications for Decision Makers
For service and technology providers, the priority is to reduce friction across the workflow. Investments that improve data handoffs, standardize interpretation steps, and shorten delivery timelines are likely to create more durable competitive advantage than feature-level improvements alone. Positioning should emphasize how digital rock analysis helps customers make faster, better-informed decisions across multiple subsurface objectives, including both reservoir development and emerging storage or containment applications.
For investors, the attractive opportunity lies in companies that can demonstrate integration across imaging, laboratory work, and simulation, along with a credible path to serving expanding use cases. The market’s growth rate suggests scale potential, but long-term value will likely accrue to firms that can convert technical strength into repeatable delivery and broad application relevance. Due diligence should focus on workflow maturity, turnaround capability, and evidence that the offering is being used to support real project decisions rather than remaining a pilot-only capability.
For operators and procurement teams, the strategic question is less about whether to use digital rock analysis and more about how to make it a reliable part of project execution. Selecting partners or internal capabilities that can integrate with existing core analysis, modeling, and field workflows will matter more than choosing the most impressive standalone tool. Teams should also assess whether the provider can support interpretation and uncertainty communication, since that often determines whether digital rock insights are actually adopted at scale. Given the speed of change in technology, regulation, and application scope, timely access to detailed segmentation data, company-level comparisons, and customized recommendations can materially improve sourcing, investment, and roadmap decisions. Detailed research on service categories, regional demand patterns, and competitive positioning can help decision makers move from general market awareness to a concrete action plan.
Worldwide Oil and Gas Accounting Software Market
For detailed analysis of this topic, please visit the official page: Worldwide Oil and Gas Digital Rock Analysis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Forensic Lab Equipment Market: Why the 7.15% CAGR Trajectory Changes Everything
By pmarketresearch, 2026-09-18
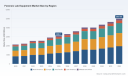
Strategic Trends and Commercial Opportunities in the Global Forensic Lab Equipment Market
Phase One: Market Snapshot and Core Headwinds
The worldwide forensic lab equipment market has demonstrated measured but consistent expansion, reaching approximately USD 3,088.1 million in 2025. Over the 2020 to 2025 period, the sector navigated the compounding effects of delayed lab modernization cycles, accelerated digital casework, and sustained capital allocation toward forensic science infrastructure. Growth is projected to continue through the 2026 to 2032 forecast window, with the total market expected to approach USD 5,007.68 million by the end of the period, reflecting a compound annual growth rate of 7.15 percent. This trajectory signals that forensic laboratories are steadily transitioning from isolated, legacy workflows toward integrated, technology-enabled ecosystems capable of processing higher caseloads with tighter turnaround expectations.
Within this broad expansion, several structural tensions are shaping how equipment buyers, manufacturers, and funding bodies navigate the landscape. First, the regulatory environment is entering a period of convergence rather than fragmentation. Quality management expectations, particularly the FDA Quality Management System Regulation that became effective in February 2026, have aligned device manufacturing requirements more closely with ISO 13485:2016 for applicable instrument categories. At the same time, forensic tests intended solely for law enforcement use remain excluded from the Laboratory-Developed Tests final rule phaseout policy, preserving a distinct regulatory pathway for certain public-sector workflows. The net effect is that firms must now manage overlapping quality, documentation, and validation expectations across jurisdictions and procurement channels.
Second, the public funding cycle creates both momentum and bottlenecks. Government forensic laboratories continue to dominate the end-user mix because public procurement channels support both capital equipment and recurring consumables. Grant activity has reinforced this pattern, with notable allocations in late 2023 directing resources toward advanced equipment and digital technology adoption among public laboratories. Yet the reliance on budgetary appropriations means that demand can shift quickly when fiscal priorities change, procurement timelines lengthen, or regional disparities widen between well-funded urban centers and under-resourced jurisdictions.
Third, the market is experiencing a technology integration inflection point. Advanced laboratory information management systems are reshaping how evidence moves from intake through analysis and reporting, making instrument interoperability, data standardization, and chain-of-custody integrity more valuable than ever. Laboratories that upgrade equipment in isolation often encounter workflow friction later, while those that plan upgrades around data architecture, sample tracking, and integration requirements are better positioned to capture long-term efficiency gains. The combination of quality regulation, public-sector dependence, and digital transformation is redefining what buyers consider a complete equipment investment rather than a standalone instrument purchase.
Phase Two: Key Drivers Behind Market Change
Technological innovation remains the most visible driver of demand. In DNA analysis, capillary electrophoresis platforms and next-generation sequencing systems have expanded the range of evidentiary questions that can be answered from limited or degraded samples. In chemistry-driven applications, mass spectrometry and chromatography platforms continue to improve throughput, selectivity, and reliability for toxicology and drug identification workflows. These advances are not simply pushing specifications higher; they are changing the scope of what forensic laboratories can reasonably pursue within operational constraints. When a single platform can handle multiple assay types or support both screening and confirmatory work with greater confidence, laboratories can consolidate workloads and reduce the hidden cost of maintaining fragmented instrument fleets.
DNA Forensic Market
Alongside the hardware evolution, analytical software and digital analysis tools are becoming central to the value proposition. Forensic casework increasingly depends on strong data management, traceable review processes, and reproducible reporting. The movement toward next-generation laboratory information management systems reflects this shift. A July 2024 guidance effort from the National Institute of Justice highlighted how technology integration can improve laboratory efficiency and evidence handling, signaling that IT and workflow architecture are now inseparable from instrument selection. For manufacturers, this means compatibility, cybersecurity posture, audit-ready data handling, and user experience are becoming competitive differentiators just as important as analytical performance.
Policy and funding dynamics are shaping demand in equally important ways. Federal and state funding streams continue to underpin procurement in public forensic laboratories, giving these institutions the ability to modernize equipment even when local budgets are strained. The BIOSECURE Act, signed in December 2025, also introduces a strategic layer to procurement planning by placing restrictions on certain biotechnology equipment and services for organizations receiving U.S. federal funding. This development does not shut down entire technologies, but it does change sourcing considerations for agencies that depend on federal dollars, encouraging buyers and suppliers to evaluate supply-chain continuity, origin of components, and long-term support arrangements more carefully. The broader regulatory climate adds further nuance: where medical-device frameworks apply, quality management expectations have become more standardized, while law-enforcement-focused forensic testing retains its own exclusionary treatment under certain FDA policies.
Demand-side behavior is changing as well. Modern casework is placing greater emphasis on turnaround time, backlog reduction, and multidisciplinary evidence processing. Digital evidence handling and secure evidence storage are growing in relevance as investigations rely more heavily on digital artifacts and as laboratories seek to preserve integrity across both physical and electronic records. In parallel, labor constraints in many public laboratories are driving interest in platforms that reduce manual prep time, simplify operator training, and support standardized workflows. As a result, procurement decisions are increasingly influenced by total cost of ownership rather than upfront instrument price alone. Consumables availability, service contracts, calibration cycles, analyst training, and data integration effort now all weigh into the business case.
PW Consulting
Supply chain and cost considerations are rounding out the driver set. Forensic instrumentation relies on precision components, specialized reagents, and calibrated subsystems, making continuity of supply a strategic concern. Events that disrupt manufacturing or logistics can cascade into longer support cycles or delayed deployments, especially for laboratories that depend on tightly scheduled grant-funded upgrades. Cost structures are also being re-evaluated as laboratories look beyond instrument purchase price and consider recurring expenses such as consumables, certified reference materials, software maintenance, and workforce training. Suppliers that can stabilize supply, offer predictable consumables pricing, and provide lifecycle support are gaining credibility with procurement teams that face both budget scrutiny and operational pressure.
Forensic Accounting Services Market
Phase Three: Competitive Landscape and Strategic Positioning
The competitive environment is concentrated, with a small group of large, diversified life science and analytical instrument manufacturers holding substantial share. Concentration metrics point to a market where the top three players account for a little over 42 percent of revenue and the top five account for nearly 58 percent. This structure favors firms that can bundle instruments, consumables, software, and service into coherent workflows, while also rewarding those that maintain strong reputations in validated analytical performance and laboratory support. The market is not only about analytical capability; it is about reliability, documentation, supply consistency, and the ability to support public-sector procurement requirements.
Several companies have carved out recognizable strategic positions. Thermo Fisher Scientific maintains a broad forensic portfolio that spans DNA analysis, toxicology, and evidence processing workflows, supported by integrated instrument and workflow offerings. Agilent Technologies emphasizes analytical systems for forensic toxicology and chemical identification, with a strong footprint in chromatography and spectroscopy applications. Waters Corporation focuses heavily on liquid chromatography and mass spectrometry solutions that are well suited to toxicology, drug testing, and metabolite identification. PerkinElmer offers a combination of spectroscopy, chromatography, and imaging equipment that supports both DNA-related applications and chemical or toxicology testing. Danaher, through SCIEX, specializes in high-performance mass spectrometry platforms used in drug screening, toxicology, and trace evidence analysis. QIAGEN and Promega anchor the DNA and human identification space, with QIAGEN focused on sample preparation and nucleic acid workflows and Promega specializing in forensic DNA reagents and capillary electrophoresis systems. Illumina, via Verogen, brings next-generation sequencing capabilities into forensic genomics, including STR and SNP analysis. Horiba, through its SPEX Forensics division, contributes specialized tools for trace evidence and particle analysis. Bruker and Shimadzu add mass spectrometry, spectroscopy, and chromatography depth across forensic chemistry and toxicology. In the evidence collection and field-to-lab segment, Sirchie and the Lynn Peavey Company provide consumables, packaging, and collection equipment that support both laboratory and crime scene workflows.
These players differentiate themselves through overlapping but distinct value propositions. Some compete on breadth and workflow integration, others on analytical depth in toxicology or DNA, and still others on forensic-specific application support and consumables ecosystems. Strategic positioning is increasingly tied to the ability to reduce operational friction: systems that are easier to validate, easier to train analysts on, and easier to integrate into laboratory data environments tend to generate stronger adoption momentum. Service networks, reagent and consumable availability, and regulatory readiness also influence purchasing decisions, especially for public laboratories that need predictable long-term support for grant-funded programs.
Recent developments illustrate how the competitive landscape is evolving. Promega continued to support its Spectrum CE Systems family for forensic capillary electrophoresis DNA analysis, reinforcing the importance of sustained instrument lifecycle support rather than one-time product launches. Regulatory and guidance activity has also been shaping competitive behavior. The FDA Quality Management System Regulation, effective in early 2026, is pushing applicable device manufacturers toward more standardized quality practices. At the same time, the exclusion of law-enforcement-focused forensic tests from the Laboratory-Developed Tests final rule phaseout policy preserves a separate pathway for certain forensic use cases, which matters for how vendors position products across public-sector and regulated diagnostic contexts. On the funding side, the November 2023 National Institute of Justice grant allocation of USD 1.9 million for advanced equipment and digital technology adoption in public forensic laboratories underscored the continuing role of public investment in easing modernization constraints. The July 2024 guidance on next-generation laboratory information management systems further highlighted how software and data integration are becoming competitive battlegrounds as much as instrument hardware.
Looking ahead, the market is likely to see both consolidation and specialization. Larger platforms that combine analytical hardware, consumables, and software will continue to compete for enterprise-level laboratory relationships, especially where labs want fewer vendor dependencies and more standardized workflows. At the same time, specialization is remaining attractive in niches such as forensic genomics, trace evidence characterization, and digital evidence handling, where application-specific toolkits and deep expert support can offset scale advantages. New entrants and niche specialists may find room by focusing on interoperability, niche workflows, or improved usability, particularly if they can help laboratories manage regulatory expectations or reduce total operating cost. The strategic battleground is shifting from isolated instrument performance to the broader question of how efficiently a laboratory can adopt, maintain, and integrate an equipment ecosystem.
Phase Four: Outlook for the Next Three to Five Years
One of the clearest near-term trends is the deepening integration of analytical instruments with laboratory data systems. As laboratories seek to reduce backlogs and improve evidentiary consistency, the value of instruments that connect cleanly to sample tracking, review workflows, and auditable reporting will rise. Equipment that can support multi-application use and interoperable data handling is likely to gain preference, especially in public-sector settings where staffing limitations make operational efficiency a priority. The opportunity here is not simply selling more instruments; it is selling reduced friction across the full evidence lifecycle. Companies that make integration easier, training faster, and documentation more straightforward will be positioned to capture more durable relationships and recurring consumables demand.
A second trend is the continued expansion of molecular and sequencing-based approaches in forensic applications. As workflows mature and application knowledge grows, next-generation tools are expected to play a larger role in human identification and complex evidentiary scenarios, complementing established capillary electrophoresis methods. This shift does not eliminate legacy techniques, but it broadens the analytical toolkit available to laboratories and increases demand for specialized reagents, validated panels, and expert implementation support. The commercial implication is that suppliers with strong forensic genomics capabilities, credible validation support, and interpretive software may see growing relevance alongside traditional hardware players. At the same time, laboratories will need realistic guidance around adoption costs, turnaround expectations, and data interpretation requirements before scaling these approaches across caseloads.
A third trend involves procurement strategy and supply-chain resilience. With public funding still central and federal policy adding new sourcing considerations, laboratories and suppliers alike will pay closer attention to long-term availability, service continuity, and component origin. The BIOSECURE Act and related procurement sensitivities are likely to encourage more deliberate sourcing choices for federally funded programs. That creates both caution and opportunity: suppliers that can demonstrate stable domestic or diversified sourcing, clear regulatory alignment, and dependable lifecycle support may find an advantage in procurement discussions. The uncertainty to watch is that policy specificity, funding cycles, and regional budget pressures can shift purchasing timing, leaving some modernization plans delayed even when technical demand is strong.
Phase Five: Actionable Guidance for Decision Makers
For equipment manufacturers and solution providers, the priority is to treat interoperability, quality documentation, and lifecycle support as core commercial assets rather than secondary service items. Positioning should address how a platform reduces training burden, supports repeatable workflows, fits into existing laboratory data environments, and maintains consumables and service availability over time. Firms that can align their product roadmaps with both analytical performance and operational practicality will be better placed to win procurement decisions in public and private laboratories alike.
For investors, the most durable opportunities lie in companies that combine recurring consumables revenue with software, service, and workflow integration that increase switching costs in a favorable way. Monitoring regulatory clarity, public funding patterns, and the pace of digital lab adoption will help identify which business models are most exposed to procurement delays and which are positioned for steady expansion. Specialization in forensic genomics, trace evidence, and digital evidence workflows may offer targeted growth, but execution risk around validation, adoption, and support capacity should be evaluated closely.
For procurement leaders and laboratory operators, the most useful question is how an equipment purchase changes day-to-day operations over the next several years, not merely what a specification sheet offers at launch. Decisions should weigh integration effort, consumables continuity, service response, and the ability to support future data standards or expanded casework needs. Early engagement with technical validation, training, and workflow mapping can reduce the risk that a modern instrument becomes an isolated asset rather than part of a more efficient laboratory system.
A fuller picture of the market—including detailed segmentation profiles, regional dynamics, competitive positioning, and policy-sensitive procurement considerations—is available in the complete PW Consulting study on the worldwide forensic lab equipment market. That report provides the deeper segmentation data and tailored scenario analysis needed for more specific planning across product strategy, investment evaluation, and procurement roadmaps.
For detailed analysis of this topic, please visit the official page: Worldwide Forensic Lab Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com