

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Forensic Lab Equipment Market: Why the 7.15% CAGR Trajectory Changes Everything

Strategic Trends and Commercial Opportunities in the Global Forensic Lab Equipment Market
Phase One: Market Snapshot and Core Headwinds
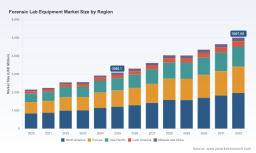
The worldwide forensic lab equipment market has demonstrated measured but consistent expansion, reaching approximately USD 3,088.1 million in 2025. Over the 2020 to 2025 period, the sector navigated the compounding effects of delayed lab modernization cycles, accelerated digital casework, and sustained capital allocation toward forensic science infrastructure. Growth is projected to continue through the 2026 to 2032 forecast window, with the total market expected to approach USD 5,007.68 million by the end of the period, reflecting a compound annual growth rate of 7.15 percent. This trajectory signals that forensic laboratories are steadily transitioning from isolated, legacy workflows toward integrated, technology-enabled ecosystems capable of processing higher caseloads with tighter turnaround expectations.
Within this broad expansion, several structural tensions are shaping how equipment buyers, manufacturers, and funding bodies navigate the landscape. First, the regulatory environment is entering a period of convergence rather than fragmentation. Quality management expectations, particularly the FDA Quality Management System Regulation that became effective in February 2026, have aligned device manufacturing requirements more closely with ISO 13485:2016 for applicable instrument categories. At the same time, forensic tests intended solely for law enforcement use remain excluded from the Laboratory-Developed Tests final rule phaseout policy, preserving a distinct regulatory pathway for certain public-sector workflows. The net effect is that firms must now manage overlapping quality, documentation, and validation expectations across jurisdictions and procurement channels.
Second, the public funding cycle creates both momentum and bottlenecks. Government forensic laboratories continue to dominate the end-user mix because public procurement channels support both capital equipment and recurring consumables. Grant activity has reinforced this pattern, with notable allocations in late 2023 directing resources toward advanced equipment and digital technology adoption among public laboratories. Yet the reliance on budgetary appropriations means that demand can shift quickly when fiscal priorities change, procurement timelines lengthen, or regional disparities widen between well-funded urban centers and under-resourced jurisdictions.
Third, the market is experiencing a technology integration inflection point. Advanced laboratory information management systems are reshaping how evidence moves from intake through analysis and reporting, making instrument interoperability, data standardization, and chain-of-custody integrity more valuable than ever. Laboratories that upgrade equipment in isolation often encounter workflow friction later, while those that plan upgrades around data architecture, sample tracking, and integration requirements are better positioned to capture long-term efficiency gains. The combination of quality regulation, public-sector dependence, and digital transformation is redefining what buyers consider a complete equipment investment rather than a standalone instrument purchase.
Phase Two: Key Drivers Behind Market Change
Technological innovation remains the most visible driver of demand. In DNA analysis, capillary electrophoresis platforms and next-generation sequencing systems have expanded the range of evidentiary questions that can be answered from limited or degraded samples. In chemistry-driven applications, mass spectrometry and chromatography platforms continue to improve throughput, selectivity, and reliability for toxicology and drug identification workflows. These advances are not simply pushing specifications higher; they are changing the scope of what forensic laboratories can reasonably pursue within operational constraints. When a single platform can handle multiple assay types or support both screening and confirmatory work with greater confidence, laboratories can consolidate workloads and reduce the hidden cost of maintaining fragmented instrument fleets.
DNA Forensic Market
Alongside the hardware evolution, analytical software and digital analysis tools are becoming central to the value proposition. Forensic casework increasingly depends on strong data management, traceable review processes, and reproducible reporting. The movement toward next-generation laboratory information management systems reflects this shift. A July 2024 guidance effort from the National Institute of Justice highlighted how technology integration can improve laboratory efficiency and evidence handling, signaling that IT and workflow architecture are now inseparable from instrument selection. For manufacturers, this means compatibility, cybersecurity posture, audit-ready data handling, and user experience are becoming competitive differentiators just as important as analytical performance.
Policy and funding dynamics are shaping demand in equally important ways. Federal and state funding streams continue to underpin procurement in public forensic laboratories, giving these institutions the ability to modernize equipment even when local budgets are strained. The BIOSECURE Act, signed in December 2025, also introduces a strategic layer to procurement planning by placing restrictions on certain biotechnology equipment and services for organizations receiving U.S. federal funding. This development does not shut down entire technologies, but it does change sourcing considerations for agencies that depend on federal dollars, encouraging buyers and suppliers to evaluate supply-chain continuity, origin of components, and long-term support arrangements more carefully. The broader regulatory climate adds further nuance: where medical-device frameworks apply, quality management expectations have become more standardized, while law-enforcement-focused forensic testing retains its own exclusionary treatment under certain FDA policies.
Demand-side behavior is changing as well. Modern casework is placing greater emphasis on turnaround time, backlog reduction, and multidisciplinary evidence processing. Digital evidence handling and secure evidence storage are growing in relevance as investigations rely more heavily on digital artifacts and as laboratories seek to preserve integrity across both physical and electronic records. In parallel, labor constraints in many public laboratories are driving interest in platforms that reduce manual prep time, simplify operator training, and support standardized workflows. As a result, procurement decisions are increasingly influenced by total cost of ownership rather than upfront instrument price alone. Consumables availability, service contracts, calibration cycles, analyst training, and data integration effort now all weigh into the business case.
PW Consulting
Supply chain and cost considerations are rounding out the driver set. Forensic instrumentation relies on precision components, specialized reagents, and calibrated subsystems, making continuity of supply a strategic concern. Events that disrupt manufacturing or logistics can cascade into longer support cycles or delayed deployments, especially for laboratories that depend on tightly scheduled grant-funded upgrades. Cost structures are also being re-evaluated as laboratories look beyond instrument purchase price and consider recurring expenses such as consumables, certified reference materials, software maintenance, and workforce training. Suppliers that can stabilize supply, offer predictable consumables pricing, and provide lifecycle support are gaining credibility with procurement teams that face both budget scrutiny and operational pressure.
Forensic Accounting Services Market
Phase Three: Competitive Landscape and Strategic Positioning
The competitive environment is concentrated, with a small group of large, diversified life science and analytical instrument manufacturers holding substantial share. Concentration metrics point to a market where the top three players account for a little over 42 percent of revenue and the top five account for nearly 58 percent. This structure favors firms that can bundle instruments, consumables, software, and service into coherent workflows, while also rewarding those that maintain strong reputations in validated analytical performance and laboratory support. The market is not only about analytical capability; it is about reliability, documentation, supply consistency, and the ability to support public-sector procurement requirements.
Several companies have carved out recognizable strategic positions. Thermo Fisher Scientific maintains a broad forensic portfolio that spans DNA analysis, toxicology, and evidence processing workflows, supported by integrated instrument and workflow offerings. Agilent Technologies emphasizes analytical systems for forensic toxicology and chemical identification, with a strong footprint in chromatography and spectroscopy applications. Waters Corporation focuses heavily on liquid chromatography and mass spectrometry solutions that are well suited to toxicology, drug testing, and metabolite identification. PerkinElmer offers a combination of spectroscopy, chromatography, and imaging equipment that supports both DNA-related applications and chemical or toxicology testing. Danaher, through SCIEX, specializes in high-performance mass spectrometry platforms used in drug screening, toxicology, and trace evidence analysis. QIAGEN and Promega anchor the DNA and human identification space, with QIAGEN focused on sample preparation and nucleic acid workflows and Promega specializing in forensic DNA reagents and capillary electrophoresis systems. Illumina, via Verogen, brings next-generation sequencing capabilities into forensic genomics, including STR and SNP analysis. Horiba, through its SPEX Forensics division, contributes specialized tools for trace evidence and particle analysis. Bruker and Shimadzu add mass spectrometry, spectroscopy, and chromatography depth across forensic chemistry and toxicology. In the evidence collection and field-to-lab segment, Sirchie and the Lynn Peavey Company provide consumables, packaging, and collection equipment that support both laboratory and crime scene workflows.
These players differentiate themselves through overlapping but distinct value propositions. Some compete on breadth and workflow integration, others on analytical depth in toxicology or DNA, and still others on forensic-specific application support and consumables ecosystems. Strategic positioning is increasingly tied to the ability to reduce operational friction: systems that are easier to validate, easier to train analysts on, and easier to integrate into laboratory data environments tend to generate stronger adoption momentum. Service networks, reagent and consumable availability, and regulatory readiness also influence purchasing decisions, especially for public laboratories that need predictable long-term support for grant-funded programs.
Recent developments illustrate how the competitive landscape is evolving. Promega continued to support its Spectrum CE Systems family for forensic capillary electrophoresis DNA analysis, reinforcing the importance of sustained instrument lifecycle support rather than one-time product launches. Regulatory and guidance activity has also been shaping competitive behavior. The FDA Quality Management System Regulation, effective in early 2026, is pushing applicable device manufacturers toward more standardized quality practices. At the same time, the exclusion of law-enforcement-focused forensic tests from the Laboratory-Developed Tests final rule phaseout policy preserves a separate pathway for certain forensic use cases, which matters for how vendors position products across public-sector and regulated diagnostic contexts. On the funding side, the November 2023 National Institute of Justice grant allocation of USD 1.9 million for advanced equipment and digital technology adoption in public forensic laboratories underscored the continuing role of public investment in easing modernization constraints. The July 2024 guidance on next-generation laboratory information management systems further highlighted how software and data integration are becoming competitive battlegrounds as much as instrument hardware.
Looking ahead, the market is likely to see both consolidation and specialization. Larger platforms that combine analytical hardware, consumables, and software will continue to compete for enterprise-level laboratory relationships, especially where labs want fewer vendor dependencies and more standardized workflows. At the same time, specialization is remaining attractive in niches such as forensic genomics, trace evidence characterization, and digital evidence handling, where application-specific toolkits and deep expert support can offset scale advantages. New entrants and niche specialists may find room by focusing on interoperability, niche workflows, or improved usability, particularly if they can help laboratories manage regulatory expectations or reduce total operating cost. The strategic battleground is shifting from isolated instrument performance to the broader question of how efficiently a laboratory can adopt, maintain, and integrate an equipment ecosystem.
Phase Four: Outlook for the Next Three to Five Years
One of the clearest near-term trends is the deepening integration of analytical instruments with laboratory data systems. As laboratories seek to reduce backlogs and improve evidentiary consistency, the value of instruments that connect cleanly to sample tracking, review workflows, and auditable reporting will rise. Equipment that can support multi-application use and interoperable data handling is likely to gain preference, especially in public-sector settings where staffing limitations make operational efficiency a priority. The opportunity here is not simply selling more instruments; it is selling reduced friction across the full evidence lifecycle. Companies that make integration easier, training faster, and documentation more straightforward will be positioned to capture more durable relationships and recurring consumables demand.
A second trend is the continued expansion of molecular and sequencing-based approaches in forensic applications. As workflows mature and application knowledge grows, next-generation tools are expected to play a larger role in human identification and complex evidentiary scenarios, complementing established capillary electrophoresis methods. This shift does not eliminate legacy techniques, but it broadens the analytical toolkit available to laboratories and increases demand for specialized reagents, validated panels, and expert implementation support. The commercial implication is that suppliers with strong forensic genomics capabilities, credible validation support, and interpretive software may see growing relevance alongside traditional hardware players. At the same time, laboratories will need realistic guidance around adoption costs, turnaround expectations, and data interpretation requirements before scaling these approaches across caseloads.
A third trend involves procurement strategy and supply-chain resilience. With public funding still central and federal policy adding new sourcing considerations, laboratories and suppliers alike will pay closer attention to long-term availability, service continuity, and component origin. The BIOSECURE Act and related procurement sensitivities are likely to encourage more deliberate sourcing choices for federally funded programs. That creates both caution and opportunity: suppliers that can demonstrate stable domestic or diversified sourcing, clear regulatory alignment, and dependable lifecycle support may find an advantage in procurement discussions. The uncertainty to watch is that policy specificity, funding cycles, and regional budget pressures can shift purchasing timing, leaving some modernization plans delayed even when technical demand is strong.
Phase Five: Actionable Guidance for Decision Makers
For equipment manufacturers and solution providers, the priority is to treat interoperability, quality documentation, and lifecycle support as core commercial assets rather than secondary service items. Positioning should address how a platform reduces training burden, supports repeatable workflows, fits into existing laboratory data environments, and maintains consumables and service availability over time. Firms that can align their product roadmaps with both analytical performance and operational practicality will be better placed to win procurement decisions in public and private laboratories alike.
For investors, the most durable opportunities lie in companies that combine recurring consumables revenue with software, service, and workflow integration that increase switching costs in a favorable way. Monitoring regulatory clarity, public funding patterns, and the pace of digital lab adoption will help identify which business models are most exposed to procurement delays and which are positioned for steady expansion. Specialization in forensic genomics, trace evidence, and digital evidence workflows may offer targeted growth, but execution risk around validation, adoption, and support capacity should be evaluated closely.
For procurement leaders and laboratory operators, the most useful question is how an equipment purchase changes day-to-day operations over the next several years, not merely what a specification sheet offers at launch. Decisions should weigh integration effort, consumables continuity, service response, and the ability to support future data standards or expanded casework needs. Early engagement with technical validation, training, and workflow mapping can reduce the risk that a modern instrument becomes an isolated asset rather than part of a more efficient laboratory system.
A fuller picture of the market—including detailed segmentation profiles, regional dynamics, competitive positioning, and policy-sensitive procurement considerations—is available in the complete PW Consulting study on the worldwide forensic lab equipment market. That report provides the deeper segmentation data and tailored scenario analysis needed for more specific planning across product strategy, investment evaluation, and procurement roadmaps.
For detailed analysis of this topic, please visit the official page: Worldwide Forensic Lab Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com