

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Scar Treatment Supplies Market: Why 10% CAGR and 48.95 Billion in 2032 Matter

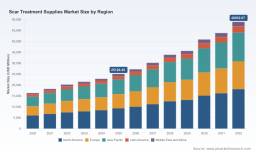
Worldwide Scar Treatment Supplies Market: Strategic Trends and Commercial Opportunities
1. Market Landscape and Core Challenges
The worldwide market for scar treatment supplies has demonstrated sustained expansion over the past five years, reaching an estimated valuation of approximately 25.1 billion USD in the base year 2025. Historical trajectories from 2020 through 2025 reveal a consistent upward climb, reflecting growing clinical acceptance and broader consumer awareness of scar management solutions. Forward projections for the period 2026 to 2032 indicate that this momentum will continue, with the sector anticipated to approach 49 billion USD by the end of the forecast window. This evolution corresponds to a compound annual growth rate of roughly 10.0 percent, signaling a mature yet still accelerating demand environment. The scale and velocity of growth suggest that scar care has transitioned from a niche wound care adjunct to a distinct commercial category with its own supply chains, regulatory pathways, and competitive dynamics.
Scar Tape Market
Despite the favorable headline numbers, the industry is navigating a set of structural challenges that will shape competitive outcomes over the next several years. The first challenge lies in the fragmentation of product classifications and quality expectations across regions. Medical-grade silicone sheets, hydrogels, topical gels, compression garments, and adhesive tapes each occupy different regulatory and clinical positioning, which complicates market entry, manufacturing standardization, and cross-border distribution. Companies must balance the need for broad product portfolios against the operational burden of maintaining consistent quality and documentation across multiple device categories and therapeutic claims.
A second challenge stems from the tension between clinical efficacy and consumer accessibility. Scar treatment supplies serve a dual audience: healthcare professionals managing post-surgical, burn, and trauma outcomes, and consumers seeking non-invasive options for aesthetic or comfort-related concerns. This duality creates divergent purchasing behaviors, price sensitivities, and expectations around evidence. Suppliers that rely primarily on clinical credibility may find growth constrained if they cannot translate that credibility into user-friendly packaging, clear usage instructions, and retail or e-commerce visibility. Conversely, products positioned primarily for convenience risk scrutiny if clinical differentiation is perceived as thin.
A third challenge is the pressure on margin structures as the market matures. With a meaningful portion of revenue concentrated among a limited number of established players, smaller manufacturers and new entrants face rising costs for materials, regulatory compliance, and channel access. At the same time, larger organizations are increasingly looking to consolidate capabilities, streamline product lines, and push for value-based pricing. The result is a market where scale, regulatory fluency, and brand trust increasingly determine who can protect profitability while still expanding share.
2. Key Drivers of Market Change
Technological innovation remains one of the most powerful forces reshaping scar treatment supplies. Advances in silicone formulation, adhesion engineering, and barrier performance have improved the practical usability of sheets and gels, making them easier to apply, more comfortable for extended wear, and more reliable across different skin types and scar ages. Products that combine occlusion and hydration in a way that supports flattening, softening, and fading of raised scars have become central to both prophylactic and treatment-oriented use. The broader shift toward medical-grade materials that can be used on new and older scars—from surgery, burns, and trauma—has expanded the addressable use cases and encouraged product refinement rather than simple commodity competition.
Scar Treatment Market
Regulatory and policy dynamics are also acting as a major driver, particularly as classification expectations tighten in key markets. In the United States, silicone gel sheeting and hydrogel products for scar management are commonly regulated as Class I medical devices, with many products exempt from premarket notification but still subject to establishment registration and general controls. This framework lowers the procedural barrier for certain entrants while still demanding disciplined quality systems. In the European Union, the environment has moved toward more rigorous conformity assessment for a subset of scar and wound care products, with select gel and wound care items achieving Class IIb medical device certification under the Medical Device Regulation. Such developments elevate the importance of regulatory readiness, post-market surveillance, and documented safety and performance, especially for companies seeking to scale across multiple jurisdictions.
Demand-side change is accelerating the market as well. Clinicians and patients increasingly view scar management as a standard part of post-procedure care rather than an optional afterthought, especially following surgical interventions, burn recovery, and trauma-related healing. At the same time, the consumer side of the market is becoming more informed and more proactive, with growing interest in non-invasive options that can reduce itch, discomfort, and visible prominence. This dual demand expansion is pushing suppliers to develop offerings that satisfy professional procurement requirements while remaining accessible enough for direct-to-consumer and retail channels. The result is a broader product spectrum, from physician-exclusive lines to over-the-counter topical solutions, each targeting a different point in the care journey.
Supply chain and cost considerations are exerting a more subtle but persistent influence. Manufacturers of silicone sheets, gels, compression garments, and adhesive tapes must manage material availability, production consistency, and packaging requirements while responding to shifting channel expectations. The growing emphasis on branded and locally distributed portfolios has encouraged some companies to invest in manufacturing reliability and formulation consistency as differentiators, rather than competing primarily on price. At the same time, operations that can align procurement, regulatory documentation, and distribution logistics are better positioned to withstand volatility and maintain service levels for both clinical and consumer customers.
3. Competitive Landscape and Leading Strategies
The competitive field in scar treatment supplies is defined by a mix of established multinational players and specialized manufacturers, each pursuing a distinct route to differentiation. Several large organizations anchor their positions through well-known silicone sheeting and gel products designed for the management of hypertrophic and keloid scars. Smith & Nephew, for example, emphasizes self-adhesive silicone gel sheets intended to soften, flatten, and fade new and old red or raised scars arising from surgery, burns, and trauma. Mölnlycke Health Care takes a related but technically distinct approach with self-adherent soft silicone dressings built around a proprietary skin-friendly adhesive concept, supporting both prevention and treatment on old and new scars, including prophylactic use on closed wounds. These product narratives highlight how incumbents use clinical familiarity, application convenience, and prophylactic positioning to reinforce repeat usage and professional trust.
Specialist manufacturers are competing by sharpening the technical story around their materials. Bio Med Sciences focuses on silicone-based scar management products that incorporate a patented technology blending silicone with Teflon-like properties, offering adhesive gel sheets in clear, fabric, and foam variants for the prevention and reduction of hypertrophic and keloid scars. Biodermis and Newmedical Technology similarly concentrate on silicone-based sheets and gels for post-surgical and trauma-related scar reduction, while Enaltus markets a widely recognized silicone gel for topical treatment aimed at reducing the appearance of raised scars. This concentration on material science and application specificity allows smaller firms to compete on perceived performance and clinical fit rather than scale alone.
Other participants are expanding the therapeutic palette beyond traditional silicone sheeting. Sonoma Pharmaceuticals has built a presence around hypochlorous acid-based scar gels that aim to manage scars by reducing itch, pain, and appearance while supporting wound healing. Perrigo and Merz Pharmaceuticals contribute to the broader topical and dermatology-oriented side of the category, with Perrigo focusing on over-the-counter and branded scar treatment offerings through its portfolio, and Merz positioning topical scar solutions within a wider dermatology context for aesthetic and medical management. Scar Heal, operating under a physician-focused brand identity, offers silicone scar gels and sheets including exclusive lines for scar refinement. Together, these players illustrate a market where differentiation is being built through both material-based claims and broader care-pathway positioning.
Recent regulatory activity underscores how competitive positioning is increasingly tied to compliance capability as well as product performance. Sonoma Pharmaceuticals, for instance, completed the transition of its Epicyn scar gel and related items to EU Medical Device Regulation Class IIb certification for wound care, scar, and atopic dermatitis treatments in late 2024. Moves like this signal thatEU market access and credibility can depend on more advanced conformity assessment for certain product types, which in turn affects who can scale efficiently in that region. At the same time, the generally lighter regulatory pathway for many silicone hydrogel and gel sheeting products under FDA product codes continues to support a diverse set of entrants in the U.S., even as establishment registration and general controls remain baseline expectations.
PW Consulting
Looking at the broader evolution of the landscape, consolidation and portfolio rationalization appear likely to intensify. Larger organizations may pursue acquisitions or internal streamlining to reduce overlap, strengthen channel access, and build more coherent brand architectures across medical and consumer segments. At the same time, fragmentation is likely to persist in specialized niches where formulation, adhesion properties, comfort, and physician relationships create defensible positions. New entrants will probably continue to appear, but their success will increasingly depend on regulatory readiness, evidence-backed claims, and the ability to distribute through channels that match their target audience. The market is therefore moving toward a pattern where scale, compliance, and brand trust reinforce one another rather than operating as separate competitive dimensions.
4. Future Trends and Commercial Implications
Over the next three to five years, one likely trend is the continued sharpening of product differentiation around material performance and user experience. As clinicians and consumers compare options more systematically, products that offer easier application, better adhesion control, improved comfort over longer wear periods, and consistent outcomes across scar types will gain advantage. This creates commercial opportunities for manufacturers that invest in formulation refinement, packaging that supports adherence, and clear guidance for both prophylactic and treatment use. It also raises the stakes for suppliers whose products are perceived as interchangeable, since price competition alone is unlikely to sustain margins in a growing but increasingly discerning market.
A second trend is the deepening of regulatory stratification across regions and product types. While some categories will continue to benefit from lighter premarket requirements, others will face more demanding conformity, documentation, and post-market expectations. This uneven landscape creates opportunities for companies that build regulatory competence as a core capability rather than a back-office function. Firms that can navigate device classification, maintain robust quality systems, and adapt product claims to local expectations will be better positioned to expand internationally and to present themselves as lower-risk partners for distributors and clinical buyers. The unpredictability lies in how quickly regulators may adjust expectations and how consistently those adjustments are applied across product variants.
A third trend is the growth of hybrid distribution models that blend professional channels with consumer access. As scar care becomes more embedded in post-procedure routines and more visible in retail and online channels, companies will need to manage the tension between clinical credibility and consumer convenience. This opens opportunities for portfolios that are structured by use case—prophylaxis after surgery or trauma, management of hypertrophic and keloid scars, and consumer-focused topical solutions—while preserving consistent quality standards. The risk is brand dilution or channel conflict if product lines are not clearly differentiated by audience, evidence level, and intended use. Companies that can maintain disciplined segmentation while still reaching multiple purchasing paths are more likely to capture growth without eroding trust.
5. Strategic Options for Decision-Makers
Manufacturers should treat regulatory readiness, material consistency, and channel fit as interconnected priorities rather than isolated functions. Investing in formulation and adhesion performance can support differentiation, but that advantage only translates into share if the product is positioned clearly for its intended use and supported by documentation that matches the expectations of the markets served. Companies expanding across regions may benefit from sequencing their regulatory strategy, prioritizing markets where their product classification and quality systems align most naturally with local requirements before scaling into more demanding environments.
For investors, the key question is whether a company’s growth is backed by defensible differentiation or by broadly commoditized supply. Businesses with strong formulation expertise, recognizable clinical use narratives, and the ability to meet evolving device-classification expectations are better placed to sustain margins as the market expands. Caution is warranted where expansion depends mainly on volume without corresponding improvements in compliance, brand trust, or channel access, since these are the areas where competitive pressure is most likely to compress returns.
For procurement and supply chain leaders, the priority is to balance availability, quality assurance, and category fit when selecting suppliers. Evaluating manufacturers on the basis of regulatory status, product consistency, and suitability for specific scar types and care settings can reduce risk while supporting better outcomes. It also helps to structure sourcing around clearly defined use cases, so that procurement decisions reflect whether the need is prophylaxis, ongoing management of raised scars, or consumer-oriented topical support.
For organizations that need a more granular view of segment dynamics, regional splits, and company-level positioning, a detailed research report can provide the segmentation breakdowns, competitive profiles, and scenario analysis needed to translate these strategic themes into specific plans. The broader market trajectory suggests that those who act early on regulatory preparation, product differentiation, and channel strategy will be better placed to capture the next phase of growth in scar treatment supplies.
For detailed analysis of this topic, please visit the official page: Worldwide Scar Treatment Supplies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com