

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Ultra Low Temperature Freezers Medical Market: 5.42% CAGR Redefining Growth

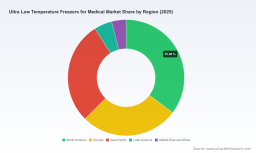
Global Ultra Low Temperature Freezers for Medical Market: Strategic Shifts and Commercial Pathways
The Worldwide Ultra Low Temperature Freezers for Medical Market has entered a phase of measured but meaningful expansion. Valued at approximately USD 915.0 Million in 2025, the market is projected to reach USD 1,324.0 Million by 2032, translating to a steady CAGR of 5.42 percent across the 2026–2032 forecast horizon. The trajectory from 2020 through 2025 reflects a compounding pattern of procurement normalization, biobank infrastructure build-outs, and sustained clinical sample preservation needs. What was once a niche laboratory equipment category has matured into a strategically critical component of healthcare logistics, pharmaceutical cold-chain operations, and biomedical research ecosystems. The growth curve is no longer driven purely by volume expansion; it is increasingly shaped by performance expectations, regulatory compliance, and total cost of ownership considerations.
Despite the clear upward trajectory, the sector faces structural inflection points that will separate value creators from commoditized players. First, energy intensity remains a stubborn operational burden. Legacy -86°C units draw substantial power over extended operating cycles, and hospitals, research facilities, and biobanks are increasingly auditing lifecycle operating costs rather than focusing solely on upfront capital expenditure. Second, regulatory scrutiny has tightened considerably. Equipment used to store vaccines, human cells, tissues, and high-value pharmaceutical products is now evaluated through stricter quality management, validation, and certification frameworks, raising the compliance burden for manufacturers and buyers alike. Third, the market is moving away from one-size-fits-all procurement toward application-specific configurations. Clinical environments demand robust temperature stability and rapid recovery, biobanks prioritize long-duration sample integrity and footprint optimization, while pharmaceutical and biotech operators focus on traceability, audit readiness, and integration with broader quality systems. These converging pressures are redefining what “competitive” means in this equipment category.
Key Demand Drivers Reshaping the Market
Technological Innovation and Performance Differentiation
Technological advancement is no longer a secondary feature; it is becoming a primary purchasing criterion. Manufacturers are deploying dual-cooling architectures, improved insulation materials, and smarter temperature management logic to reduce energy consumption while preserving sample safety. The emphasis has shifted from simply achieving low setpoints to delivering consistent temperature uniformity, faster recovery after door openings, and lower failure risk during extended unattended operation. Energy-efficient models that meaningfully cut daily power draw are gaining preference in hospital and laboratory modernization programs, particularly where facilities are under pressure to align equipment upgrades with broader sustainability and operating-cost targets. The practical implication for buyers is clear: total cost of ownership now outweighs sticker price in multi-year planning, and manufacturers that can quantify energy savings alongside reliability metrics are earning stronger consideration.
Regulatory and Compliance Evolution as a Market Filter
The regulatory environment is reshaping both product design and procurement decision-making. In the European Union, ultra-low temperature freezers intended for medical use are regulated as Class IIa medical devices under EU MDR, requiring compliance frameworks that support the storage of vaccines, human cells, and tissues. Meanwhile, the FDA’s new Quality Management System Regulation, which became effective in early 2026, has introduced additional validation expectations for equipment used to store high-value medical and pharmaceutical products. These developments are elevating the importance of documented quality systems, traceable manufacturing practices, and certified performance validation. For manufacturers, this means compliance capability is now a competitive moat rather than a baseline expectation. For procurement teams, it means vendor selection must increasingly account for certification status, validation support, and ongoing quality management discipline, especially in regulated clinical and biobanking environments.
Demand-Side Shifts in Healthcare and Life Sciences Operations
Demand is being reshaped by how biological materials are generated, stored, and utilized across the healthcare and life sciences value chain. Biobanking activity continues to expand as research programs, translational medicine initiatives, and population-scale sample collections require secure long-term preservation. Hospitals and clinics are reinforcing specimen storage practices for diagnostics, therapeutic workflows, and blood product management. Pharmaceutical and biotech organizations are investing in controlled storage environments that support development pipelines, stability programs, and clinical material handling. At the same time, organizations are seeking equipment that integrates more smoothly into quality operations, offering clearer documentation, reliable alarm pathways, and configurations aligned with specific storage profiles. The result is a more sophisticated buyer mindset: procurement decisions are increasingly tied to operational resilience, sample integrity risk reduction, and alignment with institutional quality standards.
Supply Chain and Cost Structure Realignment
Cost structures across the sector are being influenced by component availability, manufacturing scale, logistics complexity, and the premium associated with certified medical-grade production. Suppliers that maintain disciplined quality management systems, including ISO 13485 alongside ISO 9001, are better positioned to serve clinical and biobanking customers who require consistent process control and auditable manufacturing practices. At the same time, energy efficiency has become a leverage point for cost optimization, since operating expense over a freezer’s service life can dominate ownership economics. This has encouraged a broader reassessment of procurement timing, fleet replacement cycles, and regional sourcing strategies. For companies evaluating market entry or expansion, the opportunity lies not only in hardware specification but also in delivering verifiable efficiency gains, dependable after-sales support, and compliance-ready documentation that reduces friction for regulated buyers.
Medical Refrigerator Market
Competitive Landscape and Strategic Positioning
Incumbent Strengths and Differentiation Playbooks
The market is moderately concentrated, with leading players competing on reliability, compliance readiness, application fit, and energy performance rather than price alone. Thermo Fisher Scientific maintains a broad commercial footprint and a comprehensive ULT portfolio that emphasizes temperature stability, energy efficiency, and compliance-oriented design for medical, pharmaceutical, and biobanking use. PHC Corporation, including its PHCbi brand, has built recognition around dual-cooling technology and dependable long-term storage for biological samples, vaccines, and medical specimens, with recent launches reinforcing energy-efficient variants for research and clinical environments. Eppendorf continues to emphasize precise temperature control and sample safety for life sciences laboratories, while Haier Biomedical has expanded its presence with energy-efficient ULT models designed for hospital and clinical certification requirements. Helmer Scientific focuses on medical-grade storage for sensitive biological materials, blood products, and pharmaceuticals, and B Medical Systems has positioned itself around EU MDR Class IIa certification for vaccines, human cells, tissues, and laboratory samples. Other participants, including Arctiko, Stirling Ultracold, NuAire, So-Low, Labcold, BINDER, LAUDA, Corepoint Scientific, and Accucold, contribute further specialization across laboratory, blood bank, and healthcare storage applications.
Competitive Dynamics and Market Evolution
The competitive landscape is evolving along three interrelated directions. First, differentiation is increasingly anchored in verifiable efficiency and regulatory readiness. Products that can demonstrate lower energy consumption, robust temperature recovery, and clear certification alignment are gaining salience with buyers managing both operating budgets and compliance obligations. Second, the market is showing signs of both consolidation and fragmentation depending on segment and region. Larger incumbents leverage scale, service networks, and portfolio breadth to defend positions in high-volume clinical and biobanking channels, while smaller or regionally focused manufacturers compete through specialized configurations, responsive support, and tailored application solutions. Third, new entrants and product innovations are pressuring incumbents to keep advancing efficiency and usability. Recent launches such as PHC Corporation of North America’s TwinGuard ECO series illustrate how dual-cooling technology and enhanced energy performance are being used to reinforce long-term sample protection for medical and pharmaceutical facilities. The broader implication is that competitive advantage will increasingly depend on the ability to combine dependable cooling performance with compliance support, energy economics, and service reliability.
Forward Outlook: Trends Shaping the Next 3–5 Years
Efficiency as a Default Requirement, Not a Premium Feature
Over the next several years, energy-efficient ULT freezers are likely to shift from preferred options to baseline expectations in hospital, laboratory, and biobank procurement. As operating cost pressure persists and sustainability considerations become more embedded in facility planning, models that substantially reduce daily energy use will be favored in fleet upgrades and replacement cycles. The commercial opportunity lies in equipment that can deliver measurable efficiency gains without compromising temperature stability or sample protection. Manufacturers and distributors that can provide transparent performance comparisons and lifecycle cost framing will be better positioned to influence purchasing decisions.
Regulatory Compliance as a Defining Purchase Criterion
Compliance expectations will continue to deepen as quality management requirements and medical-device classification frameworks become more familiar to procurement and quality teams. Buyers will increasingly expect documented validation support, certified manufacturing practices, and equipment designed to fit into regulated storage workflows for vaccines, cells, tissues, and pharmaceutical materials. This trend creates a dual opportunity: manufacturers that invest early in certification readiness, quality system alignment, and validation documentation can command stronger procurement credibility, while buyers that align equipment selection with compliance pathways can reduce downstream audit and operational risk.
PW Consulting
Application-Specific Solutions and Regional Diversification
Demand will continue to diverge by use case, with biobanks, hospitals and clinics, pharmaceutical and biotech companies, and academic research institutes each prioritizing different performance attributes. Biobanks will emphasize long-term sample integrity and storage density, clinical settings will prioritize dependable temperature control and service responsiveness, and pharmaceutical and biotech users will focus on quality-system compatibility and traceability. Regionally, growth is likely to remain broad-based, with North America, Europe, and Asia Pacific each presenting distinct procurement rhythms, regulatory nuances, and infrastructure needs. The strategic opportunity is to move beyond generic product positioning and align offerings with the operational realities of each application and geography. The main uncertainty is the pace and consistency of regulatory interpretation across markets, which could affect product requirements, validation expectations, and time-to-market for new models.
Strategic Implications for Decision-Makers
For Manufacturers and Suppliers
Product strategy should balance performance credibility with compliance readiness and operating economics. Prioritize demonstrable energy efficiency, temperature stability, and service support, while ensuring that quality management and certification pathways are clearly articulated for regulated customers. Differentiation will increasingly come from how well a product fits into clinical, biobanking, or pharmaceutical workflows, not just from nominal cooling specifications.
For Investors and Strategic Partners
Investment attention should focus on companies with defensible compliance positions, efficiency-driven product roadmaps, and credible service and support models. The most durable value creation is likely to come from players that can combine reliable hardware with documentation, validation support, and total cost of ownership advantages that resonate with regulated buyers. Market growth is steady, but share gains will depend on execution in compliance, efficiency, and application alignment.
Ultra-low Temperature Freezers Market
For Procurement and Operations Leaders
Procurement decisions should evaluate ULT freezers through a lifecycle lens, weighing energy consumption, temperature reliability, certification status, validation support, and service responsiveness alongside initial capital cost. Aligning equipment selection with the intended application—clinical storage, biobanking, pharmaceutical handling, or research—will reduce operational friction and improve long-term sample integrity risk management. Requesting performance data, compliance documentation, and efficiency comparisons should become standard practice in vendor evaluation.
For organizations seeking deeper segmentation, regional procurement dynamics, and customized strategic recommendations, the full PW Consulting market analysis provides expanded data and targeted guidance across market size trajectories, competitive positioning, and application-specific demand patterns.
For detailed analysis of this topic, please visit the official page: Worldwide Ultra Low Temperature Freezers for Medical Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com