

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Global Oil & Gas Digital Rock Analysis Market: Why 12.44% CAGR Rewrites 2032 Planning

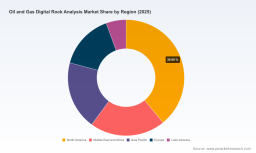
The Digital Rock Analysis Market: Strategic Shifts and Emerging Opportunities in a High-Growth Sector
Market Snapshot and Core Challenges
The global oil and gas digital rock analysis market has transitioned from an experimental niche to a structural component of reservoir evaluation and production planning. Valued at approximately $412 million in 2020, the market expanded to $741 million by 2025, with projections indicating a trajectory toward nearly $1.7 billion by 2032. This growth reflects a compound annual growth rate of around 12.4 percent, signaling sustained demand rather than a temporary technology cycle. The expansion is driven by the industry's growing reliance on pore-scale insights to de-risk development decisions, particularly in complex plays where traditional core analysis alone no longer delivers the speed or resolution operators require.
Despite this momentum, the sector faces several structural challenges that will shape how value is captured over the next few years. First, data integration and workflow fragmentation persist as a significant bottleneck. Digital rock workflows typically require stitching together high-resolution imaging outputs, laboratory measurements, and simulation environments that often operate in silos. Organizations that lack standardized pipelines spend considerable time and capital reconciling data formats, validating model fidelity, and translating simulations into operational decisions. This friction raises the effective cost of adoption and can slow the return on investment even when the underlying technology is mature.
Second, talent and interpretation expertise remain constrained. Digital rock analysis produces rich, multi-dimensional datasets, but the value of those datasets depends heavily on the ability to interpret them within the context of reservoir geology, fluid behavior, and field development strategy. There is a limited supply of professionals who can bridge imaging science, petrophysics, and production engineering. As a result, some operators hesitate to scale digital rock programs beyond pilot studies because they are uncertain how to institutionalize the insights across asset teams.
Third, the market is navigating a shift in the meaning of "value" itself. Rising carbon management expectations, regulatory cost structures, and the need to optimize recovery from mature and unconventional reservoirs are changing the questions operators ask. Digital rock analysis is no longer evaluated solely on its ability to improve production forecasts; it is increasingly assessed on whether it can support lower-risk development designs, extend field life, and provide credible data for storage or fluid retention studies. Companies that frame their capabilities only around conventional reservoir characterization risk missing the broader set of decisions now being made.
PW Consulting
These challenges create a market that is expanding quickly but remains selective about where and how digital rock tools are deployed. The operators and service providers that succeed are likely to be those that reduce integration friction, strengthen interpretive credibility, and align their offerings with the full range of decisions facing asset teams today.
Key Drivers Shaping Market Expansion
Technology innovation continues to be the most visible driver of growth in digital rock analysis. High-resolution imaging, dual-energy CT scanning, and advanced NMR capabilities are improving the fidelity of pore-scale models, while software platforms are becoming more capable at translating 3D rock images into flow simulations and relative permeability estimates. The practical impact is that teams can evaluate multiple scenarios faster and with more detail than was possible when core analysis and modeling were more sequential. A recent example of this direction is the opening of a dedicated unconventional core analysis laboratory in Dammam, Saudi Arabia, which was equipped with high-resolution dual-energy CT scanning and high-frequency NMR to support advanced digital rock characterization. This kind of facility investment signals that digital rock analysis is moving from isolated software capability to integrated laboratory-plus-simulation workflows, especially where unconventional reservoirs require more detailed pore-structure understanding.
Digital Refractometers Market
A second driver is the convergence of laboratory data and digital workflows into faster, more repeatable delivery models. The industry is showing increasing interest in compressing the timeline between physical measurement and digital simulation. Collaborations that combine pore-scale digital rock analysis with laboratory-measured data illustrate this trend, including an initiative in the U.S. that aims to integrate the two approaches so that comprehensive digital rock solutions can be delivered in weeks rather than months while enabling parallel pore-scale simulations. This compression matters because reservoir teams often need timely answers during appraisal, well placement, or development optimization. When digital rock services can be delivered as part of an integrated, faster workflow, they become easier to justify within active project cycles.
Policy and regulatory dynamics are also reshaping demand. Carbon management priorities are influencing how subsurface assets are evaluated, not just for production but also for long-term containment, storage, and emissions-related decision-making. In 2025, Colorado’s Geologic Storage Stewardship Enterprise Board set an annual stewardship fee of $0.08 per metric ton of CO2 injected for Class VI wells, reinforcing the idea that geologic storage requires ongoing oversight and credible characterization. At the same time, carbon pricing mechanisms continue to expand globally, with carbon pricing covering around 28 percent of emissions in 2025 and mobilizing significant public budget resources. South Africa also increased its carbon tax rate to ZAR 236 per tCO2e in 2025 as part of its planned trajectory. These policy developments do not directly dictate digital rock demand, but they raise the stakes for subsurface understanding, especially where operators must demonstrate performance, containment, or efficiency under tighter cost and compliance conditions.
The demand side is evolving as well. Operators are under pressure to improve recovery efficiency, reduce uncertainty in unconventional reservoirs, and extend the productive life of mature assets. Digital rock analysis supports these objectives by providing pore-scale context that can help refine reservoir models, optimize stimulation design, and inform enhanced oil recovery studies. At the same time, there is growing interest in applying similar characterization approaches to carbon capture and sequestration projects. One recent example is a strategic collaboration focused on integrated carbon capture and sequestration services that combine digital rock analysis with geochemical, PVT, and monitoring techniques. This extension of digital rock analysis beyond conventional oil and gas development suggests that the addressable use cases are widening as organizations look for integrated subsurface insight across multiple objectives.
Finally, cost structure and supply chain considerations are influencing adoption patterns. Digital rock analysis can reduce the number of expensive, iterative physical tests by allowing teams to screen scenarios digitally before committing to laboratory or field programs. That does not eliminate the need for high-quality core analysis, but it can change the balance of spending toward more targeted experimental work and more extensive digital evaluation. For companies operating in multiple regions, the ability to access capable imaging and analysis infrastructure, or to partner with providers that can deliver consistent workflows across assets, is becoming more important than simply owning software licenses. The practical effect is a market in which value is increasingly determined by workflow integration, turnaround speed, and interpretative reliability rather than by any single technical feature.
Competitive Landscape and Leading Strategies
The competitive environment in digital rock analysis is defined by a mix of oilfield service majors, specialized core analysis firms, instrument and software providers, and smaller niche players with strong scientific or regional positioning. The market is moderately concentrated, with the top three companies accounting for roughly 56 percent of market share and the top five approaching 74 percent. This concentration suggests that scale, brand trust, and established laboratory-plus-digital infrastructure provide a meaningful advantage, but it also leaves room for differentiated specialists, especially where specific applications or geographies create unmet needs.
A clear strategic pattern among leading players is the move toward integrated digital rock offerings that combine physical measurement with modeling and simulation. Companies in the oilfield services space are increasingly emphasizing workflows that link core and fluid data with digital rock characterization so that reservoir insights can be generated faster and with greater scenario flexibility. For example, providers with digital special core analysis capabilities are positioning themselves around the ability to create 3D reservoir models that support rapid flow performance simulation across multiple scenarios, with the differentiator being not just imaging quality but also the speed and interpretability of the final deliverables. Peer firms offering fast pore-scale analysis and integrated workflows are pursuing a similar end: shortening the path from laboratory data to reservoir description and optimization. This integration-focused positioning is especially relevant for operators who need to make decisions within active development timelines rather than rely on long, sequential studies.
A second strategic grouping is centered on instrumentation, imaging, and software platforms. Companies that supply high-resolution microscopy, 3D visualization, and digital rock physics software are competing on the strength of their analytical environments, including capabilities for pore-structure quantification, non-destructive simulation, and relative permeability analysis under enhanced oil recovery conditions. These providers often serve as enabling technology partners for both service companies and operator-led research teams. Their competitive advantage lies in platform maturity, the ability to handle complex image data, and the capacity to support specialized workflows such as two-phase flow simulation and special core analysis on 3D rock images. In this layer of the market, differentiation comes from how well the software supports the scientific and engineering questions that follow once high-quality images are available.
The third competitive dynamic is the emergence of specialists expanding into adjacent applications, particularly carbon capture and sequestration. Some companies are building integrated suites that pair core and fluid analysis with digital rock characterization and monitoring techniques. This strategy broadens the commercial context for digital rock analysis and positions these firms to participate in projects where subsurface characterization must support both resource recovery and storage-related decisions. At the same time, regional and scientifically focused companies are carving out places in the market by emphasizing local laboratory capability, specialized imaging, or strong domain expertise in reservoir characterization. This mix of global scale players and focused specialists creates a landscape where customers can choose between broad integrated providers and more targeted partners depending on their project priorities.
Looking ahead, the competitive landscape is likely to continue evolving along three lines. First, consolidation and collaboration will remain important as companies seek to cover the full chain from imaging to simulation to interpretation without forcing customers to assemble fragmented solutions themselves. Second, differentiation will increasingly depend on turnaround time, workflow standardization, and the ability to support parallel simulations and faster delivery, especially in contexts where decisions are time-sensitive. Third, new entrants and specialists may gain traction by focusing on underserved application areas or regions, particularly where local laboratory capacity, carbon management needs, or unconventional resource complexity create specific demand. The most resilient competitors will be those that can demonstrate both technical depth and practical delivery advantages, rather than competing solely on the basis of imaging or software features in isolation.
Forward Outlook: Trends Likely to Shape the Next Three to Five Years
One of the most important trends is the continued movement from standalone digital rock modeling toward integrated, faster workflows that connect laboratory data, imaging, and simulation in a single decision-support pathway. As more collaborations and facility investments bring these capabilities closer together, the market is likely to reward providers that can reliably compress timelines while maintaining scientific rigor. The commercial implication is that digital rock analysis will become more embedded in routine reservoir characterization and project delivery, rather than remaining a specialized study reserved for high-uncertainty cases.
A second trend is the widening application set beyond conventional production optimization. Environmental and carbon management considerations are expanding the role of subsurface characterization, and digital rock analysis is well positioned to support decisions related to fluid behavior, containment, and storage evaluation. The addressable market may grow not only because more projects require pore-scale insight, but also because the same analytical approaches can be framed for multiple objectives. Organizations that can articulate how their digital rock capabilities support both recovery and subsurface stewardship are likely to find a broader set of opportunities than those limiting their messaging to a single use case.
A third trend is the rising premium on interpretability and trust. As models become more detailed and more widely used, operators will increasingly ask not just whether a simulation is possible, but whether its outputs can be confidently translated into development actions, risk assessments, and field decisions. That creates an opportunity for providers and internal teams that invest in validation practices, domain expertise, and clear communication of uncertainty. The most valuable offerings will likely be those that help users understand what the digital rock results mean in operational terms, not simply those that produce the most complex images or simulations.
At the same time, there are real uncertainties to monitor. Adoption may slow in organizations that struggle to standardize workflows or lack the expertise to integrate digital rock outputs into decision-making. Regulatory and cost environments can also shift the priority of projects, affecting how quickly new characterization programs are sanctioned. And as more players bundle services, the market may see pricing pressure and competitive overlap, particularly where offerings become less differentiated. Companies should therefore treat growth potential as real but conditional on their ability to deliver consistent, defensible, and operationally relevant results.
Practical Implications for Decision Makers
For service and technology providers, the priority is to reduce friction across the workflow. Investments that improve data handoffs, standardize interpretation steps, and shorten delivery timelines are likely to create more durable competitive advantage than feature-level improvements alone. Positioning should emphasize how digital rock analysis helps customers make faster, better-informed decisions across multiple subsurface objectives, including both reservoir development and emerging storage or containment applications.
For investors, the attractive opportunity lies in companies that can demonstrate integration across imaging, laboratory work, and simulation, along with a credible path to serving expanding use cases. The market’s growth rate suggests scale potential, but long-term value will likely accrue to firms that can convert technical strength into repeatable delivery and broad application relevance. Due diligence should focus on workflow maturity, turnaround capability, and evidence that the offering is being used to support real project decisions rather than remaining a pilot-only capability.
For operators and procurement teams, the strategic question is less about whether to use digital rock analysis and more about how to make it a reliable part of project execution. Selecting partners or internal capabilities that can integrate with existing core analysis, modeling, and field workflows will matter more than choosing the most impressive standalone tool. Teams should also assess whether the provider can support interpretation and uncertainty communication, since that often determines whether digital rock insights are actually adopted at scale. Given the speed of change in technology, regulation, and application scope, timely access to detailed segmentation data, company-level comparisons, and customized recommendations can materially improve sourcing, investment, and roadmap decisions. Detailed research on service categories, regional demand patterns, and competitive positioning can help decision makers move from general market awareness to a concrete action plan.
Worldwide Oil and Gas Accounting Software Market
For detailed analysis of this topic, please visit the official page: Worldwide Oil and Gas Digital Rock Analysis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com