

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Air Intake Resonator Market: What the 6.85% CAGR Reveals About 2032 Growth
By pmarketresearch, 2026-09-18
Strategic Outlook: Navigating the Air Intake Resonator Market (2026–2032)
Market Overview and Core Challenges
The global air intake resonator market is characterized by steady, predictable growth driven by the broader automotive production landscape. Between 2020 and 2025, the market expanded from approximately $612.45 million to $812.4 million, reflecting a compound annual growth rate (CAGR) of 6.85% through the forecast period ending in 2032. This trajectory suggests a mature but evolving sector where volume growth is increasingly tied to technological refinement rather than raw unit production alone. By 2032, the market is projected to reach $1,291.2 million, indicating significant headroom for value creation despite the commoditization risks inherent in component manufacturing.
Regionally, the market weight is shifting. While North America and Europe remain substantial contributors with established OEM relationships, the Asia Pacific region currently represents the largest revenue share. This distribution highlights the dependency on manufacturing hubs in China, India, and Southeast Asia, where vehicle production volumes continue to outpace Western markets. However, reliance on these regions introduces exposure to supply chain volatility and varying regulatory timelines.
Three critical challenges define the current inflection point for industry stakeholders. First, the transition toward electrification complicates demand forecasting. While internal combustion engine (ICE) vehicles continue to dominate the global fleet, the long-term shift toward EVs threatens the traditional volume base for intake resonators, which are primarily designed for air-cooled combustion processes. Manufacturers must decide whether to pivot designs for hybrid applications or consolidate around ICE production in emerging markets where EV adoption lags.
PW Consulting Automotive & Machinery Research Center
Second, regulatory pressure is intensifying. Emission standards, particularly the EU Euro 7 framework, are expected to drive investment in advanced air intake systems that optimize combustion efficiency and reduce NOx and particulate emissions. Compliance is no longer optional but requires material and design changes that impact cost structures. Third, cost pressures from raw materials are reshaping bidding dynamics. The industry is seeing a divergence in material selection, where cost-effective polymers compete with high-performance engineering plastics, forcing suppliers to balance performance requirements against margin erosion.
Key Drivers of Market Dynamics
Several interconnected factors are propelling the market forward, creating both opportunities and constraints for participants. Understanding these drivers is essential for aligning product development and supply chain strategies with future demand.
Technological Innovation and Material Science
Material selection has become a primary battleground for performance differentiation. The industry is witnessing a dual-track development where glass-fiber-reinforced polyamides (PA6/PA66) continue to dominate premium turbocharged intake applications due to superior thermal resistance up to 220°C. These materials are critical for modern engines that operate at higher temperatures and pressures to meet efficiency targets. Conversely, polypropylene (PP) used in intake components offers a 15-20% cost reduction versus polyamide (PA) but is limited to lower temperature applications around 130-140°C. This cost-performance trade-off creates a segmentation opportunity where suppliers can target budget-conscious OEMs with PP solutions while retaining high-margin contracts with premium brands requiring PA-grade durability.
Innovation is not limited to materials. In-line resonators are capturing a larger share of the type segmentation compared to side branch resonators, reflecting a design preference for compact integration that minimizes engine bay footprint without sacrificing noise reduction. This shift aligns with the industry trend toward downsized, high-efficiency engines where packaging space is at a premium.
Policy and Regulatory Environment
Regulatory frameworks are acting as a forced catalyst for product upgrades. The anticipated implementation of EU Euro 7 emission standards is expected to drive investment in advanced air intake systems optimizing combustion efficiency and reducing NOx and particulate emissions. Unlike previous standards that focused heavily on tailpipe outputs, Euro 7 places greater emphasis on real-world driving emissions and durability, requiring intake systems that maintain performance consistency over the vehicle's lifespan. This regulatory shift benefits suppliers capable of engineering resonators that manage airflow turbulence and temperature more precisely, as inconsistent intake flow can lead to inefficient combustion and higher emissions.
In parallel, noise pollution regulations in urban centers are reinforcing the acoustic function of resonators. As cities impose stricter noise limits, OEMs are increasingly specifying resonators that contribute to overall vehicle sound signature management, extending the component's value proposition beyond mere engine protection.
Demand-Side Shifts and Consumer Behavior
Consumer preferences are bifurcating the market. On one end, the mainstream passenger car segment continues to drive the majority of volume, with buyers increasingly sensitive to fuel efficiency and engine smoothness. Resonators that contribute to quieter, more refined engine operation are becoming standard expectations rather than optional upgrades. On the other end, the performance aftermarket segment is showing renewed vigor. High-performance enthusiasts and modifications for trucks and SUVs are creating niche demand for resonator designs that balance airflow enhancement with sound tuning.
Recent product launches illustrate this demand divergence. In April 2025, K&N Engineering introduced NextGen Air Intake Systems for trucks and SUVs delivering horsepower gains, signaling sustained interest in performance-oriented intake upgrades. Similarly, in May 2025, Dinan released the LCI X3 M40i / X4 M40i Cold Air Intake with performance enhancements, targeting specific luxury performance models. These releases demonstrate that even as OEM volumes face long-term electrification risks, the aftermarket channel remains a viable growth vector for companies with strong brand recognition and engineering credibility.
Supply Chain and Cost Structure Evolution
Supply chain resilience has moved from a back-office concern to a strategic priority. The concentration of manufacturing in Asia Pacific means that geopolitical tensions, logistics disruptions, or regional policy changes can ripple through global availability. Suppliers are responding by diversifying supplier bases and exploring near-shoring options for critical components. Additionally, the cost structure is heavily influenced by polymer pricing volatility. The ability to switch between PP and PA based on application requirements provides a lever for cost management, but this requires flexible production lines and precise engineering validation to ensure material substitution does not compromise performance.
Cost pressures are also reshaping the competitive landscape. Companies that can achieve scale efficiencies while maintaining material flexibility are better positioned to protect margins during periods of raw material inflation. The market concentration, with the top three players holding a combined share of 38.5% and the top five at 52.7%, indicates that scale matters, but niche specialization can still command premium pricing.
Competitive Landscape and Leading Strategies
The market is defined by a mix of global Tier-1 suppliers, specialized automotive component manufacturers, and aftermarket performance leaders. Each segment employs distinct strategies to capture value, reflecting different risk tolerances and customer relationships.
Strategic Positioning of Key Players
MANN+HUMMEL stands out as a global leader in filtration solutions, designing and manufacturing air intake systems and resonators integrated into air cleaner housings for passenger cars, heavy-duty, and industrial applications. Their strategy centers on noise reduction and performance optimization, leveraging a broad portfolio that spans multiple vehicle segments. By integrating resonators directly into air cleaner housings, MANN+HUMMEL reduces separate component complexity for OEMs, offering a value proposition based on systems integration and reliability.
Röchling Automotive specializes in air intake systems with high-frequency resonators for optimized sound and performance. Their focus on integrating resonators, ducts, and filtration components for OEM automotive propulsion systems positions them as a solutions provider rather than a commodity parts supplier. This integration capability allows Röchling to capture higher margins by solving multi-functional requirements such as acoustic tuning, airflow management, and filtration in a unified design.
Toyoda Gosei manufactures air cleaner hoses with resonators and noise-absorbing air intake ducts to reduce engine intake noise while providing clean air for engine efficiency. Their approach emphasizes noise absorption and efficiency, catering to OEMs that prioritize refined engine characteristics. As a Japanese manufacturer, Toyoda Gosei benefits from strong relationships with domestic automakers and suppliers, though they face competition from European and North American players expanding into Asian markets.
Worldwide Automotive Air Filter Housing Market
Magna International provides comprehensive powertrain and vehicle engineering including air intake systems and components as part of broader automotive solutions for OEMs. Magna's scale and engineering breadth allow them to offer air intake resonators as part of a larger package, which can be attractive to OEMs seeking single-source accountability for complex vehicle subsystems. This holistic approach differentiates Magna from component-only suppliers.
Automotive Air Intake Manifold Market
K&N Engineering occupies a unique position as an aftermarket performance leader, offering cold air intake systems, some incorporating or compatible with resonator designs for enhanced airflow and sound. Their strength lies in brand loyalty among performance enthusiasts and a direct-to-consumer channel that bypasses traditional OEM supply chains. K&N's ability to deliver horsepower gains and sound enhancement makes them a benchmark for aftermarket quality, creating a halo effect that can influence OEM specifications indirectly.
Market Evolution and Competitive Trends
The competitive landscape is evolving through a combination of consolidation among large players and differentiation among specialists. The market concentration indicates that scale advantages are significant, encouraging mergers and partnerships that expand geographic reach and product portfolios. However, the presence of strong niche players like K&N Engineering suggests that specialization in performance or specific vehicle segments remains viable.
New entrants face high barriers due to the need for engineering validation, OEM qualification processes, and established supply chain relationships. However, companies that can innovate in material science or acoustic engineering may find opportunities to disrupt traditional supplier relationships, particularly if they can demonstrate clear advantages in cost or performance. The recent product activity from Dinan and K&N highlights that the aftermarket remains a dynamic space where innovation cycles are faster than in the OEM channel, providing a testing ground for new designs and materials.
Strategic differentiation is increasingly tied to material flexibility and regulatory compliance capabilities. Suppliers that can seamlessly switch between PP and PA grades based on application requirements, while meeting Euro 7 and noise standards, are better equipped to win contracts across diverse OEM segments. The ability to offer integrated solutions that combine resonators with filtration and ducting is also becoming a key differentiator, as OEMs seek to reduce assembly complexity and weight.
Future Trends and Commercial Opportunities
Looking toward the 2026–2032 horizon, several trends will shape the market's trajectory and create distinct commercial opportunities for prepared stakeholders.
Trend 1: Hybrids as a Bridge for Resonator Demand
The transition to full electrification will not be uniform across all markets. Hybrid vehicles, which retain ICE components alongside electric drivetrains, will sustain demand for air intake resonators in regions where full EV infrastructure is slow to develop. This creates a medium-term opportunity for suppliers to design resonators optimized for hybrid-specific operating conditions, such as frequent start-stop cycles and varied load demands. Manufacturers that can demonstrate improved durability and efficiency for hybrid applications will capture value from OEMs extending the life of ICE technology in hybrid platforms.
Trend 2: Material Innovation Driving Margin Recovery
As cost pressures persist, material innovation will be a critical lever for margin recovery. The divergence between PP and PA applications suggests that suppliers with expertise in material optimization can offer tiered solutions that match cost to performance requirements. Opportunities exist for companies that can develop novel composites or recycling pathways that reduce material costs while maintaining thermal and acoustic performance. Additionally, the push for sustainability may drive demand for resonators made from recycled polymers or bio-based materials, particularly in European markets where OEMs face pressure to reduce the carbon footprint of their supply chains.
Trend 3: Acoustic Performance as a Differentiator
Noise regulations and consumer expectations for refined vehicle acoustics will elevate the resonator's role beyond functional airflow management. Suppliers that can deliver precise acoustic tuning, reducing specific frequency bands associated with engine noise while maintaining airflow efficiency, will gain a competitive edge. This trend opens opportunities for collaboration with acoustic engineering firms or the development of proprietary tuning algorithms that optimize resonator design for specific engine families. The integration of resonators with active noise cancellation systems or variable geometry designs could further enhance value propositions for premium vehicle segments.
Risk Factors and Uncertainties
Despite these opportunities, risks remain. The pace of EV adoption could accelerate faster than anticipated in key markets, compressing the timeline for ICE component demand. Raw material costs could spike due to supply constraints or geopolitical events, squeezing margins for suppliers unable to pass costs through. Regulatory changes could also introduce new compliance requirements that increase engineering costs or delay product launches. Finally, the aftermarket segment, while dynamic, is subject to cyclical consumer spending and may not fully offset declines in OEM volumes if electrification progresses rapidly.
Strategic Actions for Decision Makers
Navigating the air intake resonator market requires aligned strategies across manufacturing, investment, and procurement functions. The following recommendations address the core priorities for each stakeholder group.
For Manufacturers and Suppliers
- Invest in material flexibility and engineering validation. Develop production capabilities that can efficiently switch between PP and PA grades based on customer requirements. Validate performance across temperature ranges to maximize application coverage while controlling costs.
- Strengthen hybrid and performance aftermarket capabilities. As ICE volumes face long-term headwinds, expand design expertise for hybrid-specific resonators and deepen aftermarket partnerships to capture growth from performance enthusiasts and modification markets.
- Align with regulatory roadmaps. Proactively engineer solutions that meet Euro 7 and emerging noise standards. Early compliance reduces qualification delays and positions suppliers as trusted partners for OEMs facing stringent emission targets.
For Investors and Strategic Partners
- Evaluate scale versus specialization. Assess potential targets based on their ability to leverage scale efficiencies while maintaining differentiated capabilities in material science, acoustic tuning, or aftermarket channels. Companies with both breadth and niche strength are better positioned to withstand margin pressures.
- Monitor regional shifts. Track production and demand trends in Asia Pacific, where volume growth is strongest, and assess exposure to supply chain risks. Investments in diversified manufacturing footprints or near-shoring capabilities can mitigate disruption risks.
- Consider aftermarket dynamics. Recognize that aftermarket performance brands can provide resilient revenue streams and brand visibility even as OEM volumes fluctuate. Partnerships or acquisitions in this space can offer growth avenues independent of traditional supply chain cycles.
For Procurement and OEM Stakeholders
- Prioritize suppliers with integrated solutions. Evaluate partners that can combine resonators with filtration and ducting to reduce assembly complexity and weight. Integrated offerings can lower total system cost and improve quality control.
- Develop material strategy aligned with application needs. Work with suppliers to match PP and PA materials to specific temperature and performance requirements, optimizing cost without compromising durability or compliance.
- Engage early in regulatory planning. Collaborate with suppliers to anticipate Euro 7 and noise regulation impacts, ensuring that intake system designs are validated well before mandatory implementation dates to avoid production delays.
The air intake resonator market is at a point where steady growth intersects with technological and regulatory change. Stakeholders who align their strategies with material innovation, hybrid demand, and acoustic differentiation will be best positioned to capture value through the forecast period. For deeper segmentation data, regional breakdowns, and customized strategic scenarios, access to comprehensive market intelligence is essential to refine these insights and support precise decision-making.
For detailed analysis of this topic, please visit the official page: Air Intake Resonator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Processed Seafood Market 2026: Why 5.12% CAGR and Asia Pacific Lead the Global Expansion
By pmarketresearch, 2026-09-18
Global Processed Seafood Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview: Scale, Trajectory, and Core Challenges
The global processed seafood market has demonstrated consistent expansion over the past five years, with total revenue reaching approximately $60.79 billion in 2025. The sector is projected to grow from $63.68 billion in 2026 to $86.11 billion by 2032, reflecting a compound annual growth rate of 5.12 percent. This trajectory signals a maturing but still dynamic industry where volume growth intersects with value creation through processing sophistication, branding, and supply chain optimization.
Regional distribution reveals a heavily Asia-Pacific-weighted landscape, followed by Europe and North America as substantial mature markets. Latin America and the Middle East and Africa collectively represent smaller but increasingly relevant consumption and sourcing corridors. Processing formats remain anchored by frozen seafood, which commands the largest share, while canned and smoked-dried segments provide complementary value propositions across retail and foodservice channels. Product-wise, fish-based processed goods dominate, with crustaceans and mollusks forming meaningful secondary categories that cater to specific culinary and convenience preferences.
Despite the favorable growth baseline, the industry faces several structural challenges that will define competitive outcomes over the forecast period:
Raw material cost volatility and supply uncertainty. Fishery and aquaculture commodity prices have been trending upward, with the FAO Fish Price Index averaging 127.4 points in March 2026, an 8.4 percent increase compared to March 2025. Salmon and shrimp prices have shown particularly notable rises. Simultaneously, USDA projections indicate that fish and seafood prices in the food-at-home category will increase faster than the 20-year historical average in 2026. For processors, this translates into margin compression risk unless pricing strategies, long-term supply contracts, and product mix adjustments are actively managed.
Traceability, compliance, and quality assurance pressures. Regulatory expectations around seafood traceability are intensifying. New FSMA traceability requirements apply to certain seafood on the Food Traceability List, mandating additional records for aquaculture farms and processing facilities to enable rapid identification and removal of contaminated products. In parallel, the Global Dialogue on Seafood Traceability launched a public consultation in March 2026 on an updated standard planned for release in July 2026, moving toward a commodity-agnostic modular approach applicable to processed seafood. These developments raise the compliance burden but also create differentiation opportunities for operators that can demonstrate robust, verifiable supply chain integrity.
Geopolitical and trade friction amid resilient demand. Tariffs, bans, and freight risks have introduced uncertainty into cross-border seafood flows. Yet global seafood trade is expected to continue growing into 2025 and 2026 without an anticipated reduction in key U.S. imports. This resilience suggests that demand fundamentals remain strong, but the operating environment is becoming more complex, requiring diversified sourcing, flexible logistics, and proactive regulatory monitoring.
These challenges are not merely headwinds; they are shaping a market where operational excellence, transparency, and strategic sourcing will separate outperformers from laggards.
Key Drivers: Technology, Regulation, Demand, and Supply Chain Dynamics
Several interconnected forces are accelerating change in the processed seafood sector. Understanding how these drivers interact is essential for prioritizing investment and capability-building decisions.
Technological Innovation and Processing Breakthroughs
Processing technology continues to improve product quality, shelf life, and value addition. Advanced freezing methods, controlled atmosphere packaging, and automated portioning are enabling producers to deliver convenience-oriented products that meet retail and foodservice specifications while reducing waste. In smoked and dried categories, precision smoking and dehydration technologies are enhancing consistency and flavor profiles, supporting premiumization in niche markets.
Traceability technology is another critical frontier. Digital record-keeping, lot-level tracking, and modular traceability frameworks are becoming operational necessities rather than optional enhancements. The shift toward commodity-agnostic traceability standards will likely accelerate adoption of interoperable systems that can be applied across fish, crustaceans, and mollusks, reducing the friction of managing multiple compliance regimes. For processors, technology investment is increasingly tied to market access: buyers and regulators are demanding verifiable provenance, and systems that can produce auditable records quickly will confer a competitive advantage.
Policy and Regulatory Environment
Regulatory dynamics are reshaping both cost structures and market entry conditions. Beyond traceability, short weighting enforcement has gained visibility. FDA released results from its 2022-2024 testing program on frozen seafood products for short weighting as part of ongoing compliance efforts, signaling sustained regulatory focus on accurate product representation. For processors, this underscores the importance of weight integrity, packaging accuracy, and internal quality controls.
Import eligibility and establishment compliance also remain critical. A 2025 recall of ineligible frozen Siluriformes fish products imported from Vietnam due to establishment ineligibility for U.S. export illustrates the consequences of non-compliance in supplier qualification. Similarly, recalls of frozen shrimp products associated with potential cesium-137 contamination concerns from specific processors highlight the sensitivity of safety and contamination risk management. These events reinforce that supplier vetting, facility audits, and risk-based monitoring are integral to maintaining market access and brand trust.
Demand-Side Shifts in Consumer and Business Behavior
Consumer preferences continue to tilt toward convenience, protein-rich diets, and products with clear quality and sustainability narratives. Processed seafood benefits from these trends because it offers ready-to-cook, ready-to-eat, and portion-controlled formats that fit modern meal planning. In foodservice, consistent supply, predictable specifications, and ease of preparation are valued highly, favoring processors that can deliver reliable, value-added products at scale.
At the same time, traceability and transparency are increasingly influencing purchase decisions. Retail and foodservice buyers are responding to consumer expectations by requiring suppliers to provide credible documentation on origin, handling, and compliance. This creates a reinforcing cycle: demand for transparent products pressures processors to invest in traceability, which in turn enables more confident purchasing by downstream customers.
Supply Chain and Cost Structure Evolution
Supply chain resilience has become a strategic priority. The combination of rising commodity prices, freight volatility, and trade friction is pushing processors to diversify sourcing, strengthen supplier relationships, and optimize inventory and logistics. Long-term contracts with aquaculture producers, strategic partnerships with wild-catch operators, and investment in cold chain infrastructure are becoming common responses to reduce exposure to price spikes and disruption.
Cost structures are also being reshaped by compliance and technology investments. While traceability systems and enhanced quality controls add upfront costs, they can reduce the risk of recalls, protect market access, and support premium positioning. The net effect is a shift from pure cost minimization toward total cost of ownership thinking, where reliability, compliance, and brand protection are weighted alongside unit production costs.
PW Consulting
Competitive Landscape: Strategic Positioning and Market Evolution
The processed seafood market is characterized by a moderately concentrated structure, with the top three players holding approximately 18.45 percent and the top five around 24.12 percent of total revenue. This level of concentration suggests that while large global players command meaningful scale, significant space remains for regional specialists, niche value-added producers, and emerging entrants that can differentiate through product innovation, sourcing advantage, or service model.
Leading companies are pursuing distinct strategic positions:
- Global integrated processors with strong branding. Thai Union Group and Maruha Nichiro Corporation exemplify operators with broad portfolios spanning canned tuna, frozen seafood, and value-added products. Their scale, worldwide supply chain capabilities, and brand portfolios enable them to serve diverse markets and channel requirements. Recent developments reinforce this orientation: Mitsubishi Corporation increased its stake in Thai Union to 20 percent in August 2025 to strengthen business alliance in global seafood operations, highlighting the strategic value of capital partnerships that bolster international reach and operational synergies.
- Aquaculture-focused salmon and whitefish leaders. Mowi ASA, Lerøy Seafood Group, and Cooke Inc. are positioned around farmed salmon and related processed products, with Mowi operating as the world’s largest salmon farming and processing company. Their advantage lies in controlling key parts of the value chain from production to processing, supporting consistent supply, quality management, and responsiveness to retailer and foodservice specifications. Austevoll Seafood ASA and Royal Greenland add further depth in farmed and cold-water seafood processing, broadening the geographic and species footprint of this cohort.
- Regional value-added specialists. High Liner Foods and Trident Seafoods demonstrate focused strategies in North American markets. High Liner Foods completed the acquisition of leading U.S. seafood brands Mrs. Paul’s and Van de Kamp’s from Conagra Brands in June 2025, strengthening its value-added frozen seafood portfolio and expanding its branded retail presence. Trident Seafoods specializes in wild-caught Alaskan seafood with extensive frozen and canned processed offerings, leveraging regional sourcing reputation and product familiarity.
- Broad international portfolios and regional distributors. Companies such as Nippon Suisan Kaisha, Kyokuyo Co. Ltd., Pacific Seafood Group, and Bolton Group illustrate the diversity of models across integrated procurement and processing, Pacific Northwest distribution focus, and European/international market portfolios. Nissui’s emphasis on global supply chains for frozen and highly-processed marine foods, and Boltton’s portfolio orientation in European and international markets, reflect the importance of channel reach and product breadth in serving varied customer bases.
Market structure is evolving along several axes. Consolidation is evident in branded retail and value-added segments, where acquisitions strengthen portfolio depth and channel leverage. At the same time, differentiation is intensifying around traceability, quality assurance, and sourcing credentials, creating room for companies that can credibly demonstrate superior compliance and product integrity. New entrants and smaller regional players can compete by specializing in particular species, processing methods, or local market relationships, especially where large players’ scale advantages are less decisive. The overall trend is toward a layered landscape: large integrators competing on scale, brand, and supply chain breadth; mid-tier and regional specialists competing on focus, responsiveness, and niche credibility; and traceability-conscious operators competing on transparency and risk management.
Forward Outlook: Trends Shaping the Next Three to Five Years
Looking ahead to 2032, several trends are likely to define the market’s evolution and the allocation of commercial opportunity.
Traceability becomes a market-access baseline. As traceability standards mature and FSMA requirements take full effect for listed seafood, the ability to produce modular, auditable, commodity-agnostic records will transition from differentiator to baseline expectation. Processors that invest early in interoperable systems and supplier data integration will be better positioned to serve demanding retail and foodservice buyers, while those lagging may face increasing friction in qualification and retention. The commercial opportunity lies not only in compliance but in using traceability as a trust signal that supports premium positioning and stronger customer relationships.
Value-added and convenience formats capture incremental growth. Frozen seafood will likely remain the largest processing format, but growth will be disproportionately driven by value-added products that reduce preparation effort, offer consistent portioning, and align with channel needs. Acquisitions such as High Liner Foods’ expansion of its branded U.S. portfolio indicate thatstrategic owners are betting on branded, value-added frozen seafood as a growth lever. Processors that can combine quality, convenience, and credible sourcing narratives are well placed to capture share in retail and foodservice.
Price volatility and supply diversification become strategic capabilities. With commodity prices trending above historical norms and trade friction persisting, the ability to manage input costs through diversified sourcing, forward contracting, and product mix flexibility will be a critical capability. Processors that can shift among species, origins, and formats in response to price signals, while maintaining quality and compliance, will protect margins more effectively. The risk is that operators with concentrated sourcing or rigid cost structures face disproportionate exposure to price spikes and disruption.
These trends point to a market where resilience, transparency, and value addition are increasingly intertwined. The upside is meaningful for operators that align capabilities with these directions; the downside risk is concentrated in businesses that remain dependent on single-source sourcing, minimal compliance investment, and undifferentiated product offerings.
Actionable Guidance for Decision Makers
For manufacturers and processors, the priority is to strengthen traceability infrastructure and supplier data integration now, ahead of the July 2026 standard update and the full operationalization of FSMA traceability requirements for listed seafood. Parallel investment in value-added product development, branded portfolio expansion, and diversified sourcing will help capture growth while mitigating input cost volatility. Weight integrity, facility compliance, and contamination risk management should be treated as core operational metrics, not peripheral quality tasks.
For investors, the market’s moderate concentration and ongoing consolidation create opportunities to assess companies with credible scale advantages, strong brand portfolios, and resilient sourcing models. Capital partnerships, such as the increased Mitsubishi stake in Thai Union, signal that strategic alliances are being used to reinforce global operations; similar structures may be relevant for companies seeking to accelerate international reach or technology adoption. Due diligence should weigh traceability readiness, compliance history, and product mix flexibility as indicators of long-term market access and margin stability.
For procurement leaders in retail and foodservice, supplier qualification should place greater weight on verifiable traceability, establishment compliance, and risk-based monitoring. Diversifying the supplier base across regions and species can reduce exposure to tariffs, freight risks, and single-source disruptions, while still capturing the growth expected in global seafood trade. Requiring modular, auditable traceability records and clear documentation on weight and safety compliance will help protect brand integrity and consumer trust.
Processed Vegetable Market
Detailed segment-level data, company-specific benchmarks, and scenario analysis can materially sharpen these decisions. For executives seeking granular breakdowns across regions, processing types, and product categories, as well as customized strategic guidance tailored to specific operating models, an in-depth market report is available for further review.
Processed Cheese Market
For detailed analysis of this topic, please visit the official page: Worldwide Processed Seafood Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
AGV Charging System Market: Why 8.45% CAGR and Asia Pacific’s Lead Redefine Investment
By pmarketresearch, 2026-09-18
The AGV Charging System Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The automated guided vehicle charging infrastructure market has transitioned from a peripheral consideration to a central component of intralogistics strategy. The sector expanded from roughly 312 million USD in 2020 to an estimated 613 million USD in 2025, with projections indicating a steady trajectory toward just over 1 billion USD by 2032. This growth reflects annualized expansion of 8.45 percent, a pace that outstrips broader industrial automation adoption and signals a structural shift in how facilities approach material handling power management.
Despite the upward trajectory, the market sits at a critical inflection point. Operators are no longer evaluating charging systems as simple utility attachments. Instead, charging infrastructure is becoming a bottleneck or an accelerant for throughput, depending on design choices. Three challenges define the current landscape.
First, downtime economics have intensified. Warehouse and manufacturing environments now operate under tighter labor constraints and higher throughput expectations, making vehicle idle time directly visible in operational cost. Charging solutions that require prolonged dock occupancy or complex manual alignment create hidden capacity losses that compound across fleets. Second, standardization gaps persist across safety, interoperability, and performance metrics. As automated vehicle deployments scale across mixed fleets and multi-vendor environments, facilities encounter integration friction when charging hardware, communication protocols, and docking behaviors are not aligned. Third, the pace of battery chemistry evolution is outstripping charger design cycles. Higher energy densities, faster charge acceptance, and shifting thermal profiles require charging systems that can adapt without forcing full vehicle redesigns.
These challenges are not isolated technical issues. They shape procurement decisions, vendor selection, and facility planning. Companies that treat charging as an afterthought increasingly discover that power delivery constraints limit automation ROI, while early actors are using charging architecture to differentiate operational flexibility.
Strategic Drivers Reshaping the Market
The expansion of AGV charging infrastructure is being pulled by a combination of technology, regulatory pressure, operational behavior, and cost dynamics. Understanding how these forces interact is essential for anticipating where value will concentrate.
Technology Innovation and Performance Thresholds
Charging technology is moving away from static, long-duration docking toward high-efficiency, flexible power delivery. Inductive and contact-based systems are both advancing, but the strategic question is increasingly about when and where energy is transferred. Opportunities for in-process or short-break charging reduce the need for large battery packs and long charging windows. Award recognition for in-process charging technology in early 2025 highlighted how the industry is rewarding solutions that minimize interruption rather than simply improving charger wattage. At the same time, high-voltage DC connectors and microgrid-enabled fast charging concepts have emerged to support next-generation vehicles with reduced downtime.
Battery-side developments reinforce this shift. Lithium-ion adoption continues to benefit from cost and performance improvements, and charging architectures are being optimized for higher charge rates, including transitions from conventional 1C charging toward 3C surge profiles in suitable applications. This changes the design logic for both stationary and onboard charging units, placing greater importance on thermal management, power conversion efficiency, and control software.
Policy Pressure and Compliance-Driven Adoption
Regulatory expectations are reshaping industrial facility planning. European sustainability targets require industrial operations to move toward carbon neutrality by 2050, with a 55 percent emission reduction milestone by 2030. These targets accelerate interest in efficient charging approaches that reduce energy waste and support broader decarbonization strategies. Wireless and opportunity charging solutions gain relevance here because they can lower mechanical wear, simplify integration into continuous workflows, and support more consistent energy use patterns when deployed thoughtfully.
Safety and interoperability standards are equally influential. Conformance to AGV safety requirements drives demand for charging systems that are not only electrically robust but also integrated into the vehicle’s operational safety logic. In warehouse automation, this means charging infrastructure must align with vehicle behavior, zone design, and risk controls rather than functioning as a standalone utility.
Demand-Side Changes in Logistics and Manufacturing
Operational expectations are changing on the demand side. Facilities are deploying larger fleets of automated vehicles and expecting them to support continuous or near-continuous workflows. This is especially visible in warehousing and logistics, where throughput pressure has made charging strategy part of overall slotting, routing, and shift design. Automotive manufacturing and adjacent industrial sectors are also pushing for more flexible power solutions that can accommodate high-utilization vehicles without expanding floor congestion.
Behaviorally, operators are moving from a “charge when parked” mindset to a “charge where and when it fits the process” mindset. That shift increases interest in solutions that support fast top-ups, autonomous docking, and reduced manual intervention. The commercial implication is that charging systems are being evaluated on process compatibility as much as on electrical performance.
Supply Chain and Cost Structure Evolution
Cost dynamics are improving the feasibility of advanced charging solutions, but they are also reshaping supplier competition. Better lithium-ion economics reduce the penalty of higher-performance batteries, which in turn enables more aggressive charging strategies. However, total cost of ownership calculations now include power conversion efficiency, maintenance exposure, and integration labor. Suppliers that can reduce mechanical wear, simplify installation, or support modular scaling gain an advantage because facilities are looking to avoid hidden operational costs.
Supply chain maturity is also affecting time-to-deployment. As charging modules, connectors, and control systems become more standardized in certain segments, integration complexity can decline. Yet in custom intralogistics environments, bespoke engineering remains a significant value driver, especially where high-current delivery, custom docking, or mixed-vehicle environments are involved.
Competitive Dynamics and Differentiated Playbooks
The market features a diverse set of participants spanning specialist charging providers, industrial power companies, and broader automation integrators. Rather than competing on a single dimension, leading players are defining advantage through technology focus, deployment scale, integration depth, and regional footprint.
Wireless inductive specialists have positioned themselves around continuous operation and reduced mechanical wear. Wiferion, for example, has built recognition around inductive systems designed for opportunity charging, with recent industry acknowledgment for in-process charging technology. The strategic appeal is clear: if vehicles can charge without precise mechanical engagement or extended stationary periods, facilities can reduce downtime and maintenance overhead. VAHLE takes a complementary angle with conductive contacts and shuttle charging systems, emphasizing high-current fast charging and custom integration in intralogistics. This reflects a different bet: that robust contact-based infrastructure remains essential where high power, predictability, and integration with existing floor systems matter most.
Other participants compete on scale and ecosystem breadth. Delta Electronics has emphasized a large deployed base across industrial vehicles and AGVs, presenting its charging portfolio as part of a broader mobility and automation offering. This scale narrative matters because it suggests maturity in manufacturing, support, and multi-vehicle compatibility. Micropower Group focuses on high-frequency battery chargers for AGV applications, including onboard and stationary units with support for lithium-ion and opportunity charging, targeting flexibility on both the hardware and application side. EnerSys leans into integrated battery and charging solutions, framing power delivery as part of reliable industrial automation rather than as a standalone hardware category.
In Asia, several firms emphasize precision docking, non-contact power transfer, and system-level integration. Daihen and B&PLUS illustrate the focus on docking and non-contact power supply mechanisms, while Daifuku positions charging within broader material handling automation solutions. Guangdong Titans Intelligent Power highlights autonomous docking and multi-function charging for automated material handling, reflecting an emphasis on customized deployment and functional integration. Vicor Power enters from a different angle with high-efficiency power conversion and charging modules tailored for AGV battery systems, showing how component-level performance can matter as a differentiated layer within broader assemblies.
Recent events illustrate how these positions are being reinforced. Delta Electronics showcased its battery charging portfolio at LogiMAT in early 2026, underscoring the reach of its deployed solutions. Schaltbau advanced high-voltage DC connectors and microgrid concepts for faster charging of next-generation AGVs, pointing toward infrastructure-level enablement beyond individual vehicle charging units. These moves suggest a market that is not only refining vehicle-side charging but also rethinking how power is delivered, distributed, and integrated across facilities.
Looking ahead, the competitive landscape is likely to evolve through both convergence and specialization. Integration-heavy players may absorb more charging functionality into automation platforms, while specialist suppliers may deepen advantage in wireless efficiency, high-current contact systems, or docking precision. New entrants can still compete by targeting specific pain points such as autonomous docking reliability, modular scalability, or plug-and-play interoperability. The most important strategic question is whether a supplier competes as a component vendor, a system enabler, or a process-integrated solution provider.
PW Consulting Automotive & Machinery Research Center
Outlook: Key Trends Over the Next Three to Five Years
The next phase of market development will likely be defined by how charging systems fit into broader operational design rather than by simple capacity increases. Several trends stand out.
One major direction is the rise of charging as an integral workflow element. Facilities will increasingly design routes, staging areas, and vehicle Utilization patterns around short charging windows and opportunity charging points. This creates demand for systems that support autonomous alignment, fast energy transfer, and dependable docking behavior. The commercial opportunity lies in solutions that reduce the operational friction of charging rather than only improving raw power output.
Worldwide Mobile Charging Robot for Electric Vehicle Market
A second trend is the continued blending of contact and wireless approaches. Different applications will favor different methods, but many environments will need hybrid strategies. High-utilization vehicles may benefit from inductive top-ups in flow paths, while fixed docking points may use contact systems for rapid high-power replenishment. Suppliers that can offer interoperable architectures or clearly defined application-specific playbooks will be better positioned than those pushing a single technology in all contexts.
A third trend is infrastructure-level thinking. As charging demand grows, facilities will pay more attention to power distribution, microgrid integration, and centralized energy management. This shifts some value from pure vehicle-side hardware to broader electrical architecture and control software. Companies that can connect charging performance with facility-level energy planning will have an opening to become strategic partners rather than equipment suppliers.
These trends are not without risk. Standardization may lag behind deployment, creating fragmentation and integration cost. Overly aggressive charge-rate expectations could introduce thermal or battery-life constraints if not matched with robust system design. Demand may also vary by region and sector, making broad generalizations risky. The opportunity is strongest where charging strategy is aligned with actual process requirements, fleet composition, and total cost of ownership rather than treated as a one-size-fits-all upgrade.
Strategic Actions for Decision-Makers
For AGV manufacturers and automation integrators, the priority is to treat charging as part of the vehicle and workflow architecture, not as a bolt-on accessory. Design choices around battery size, docking tolerance, charge acceptance, and safety integration will influence customer throughput and maintenance costs. Suppliers that can demonstrate measurable reductions in downtime, simpler installation, or cleaner integration with mixed fleets will differentiate more effectively than those competing only on hardware specifications.
Worldwide Automatic Guided Vehicle Sensing System Market
For investors and corporate strategy teams, the most valuable exposure may come from companies that combine technical differentiation with deployment scalability. Wireless efficiency, high-current contact reliability, power conversion performance, and integration-ready software are all potential value drivers, but the key is whether those capabilities translate into repeatable deployments and lower integration risk. Monitoring how suppliers expand from component or system roles into broader facility-level solutions can provide early signals of competitive momentum.
For procurement and operations leaders, charging decisions should be evaluated against process impact. The right solution depends on vehicle utilization patterns, shift structure, floor layout, and tolerance for manual intervention. Opportunities to reduce idle time, simplify docking, or support opportunity charging in active flow paths can create operational benefits that outweigh raw hardware comparisons. Detailed segment-level data, application-specific benchmarks, and vendor-by-vendor capability mapping can materially improve procurement decisions and reduce implementation risk. For teams planning multi-phase automation rollouts, deeper research into charging architecture options, regional supplier dynamics, and total cost of ownership scenarios can help convert a technical choice into a strategic advantage.
For detailed analysis of this topic, please visit the official page: AGV Charging System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Bubble Tea Syrup Market beyond 7.45% CAGR: 5 Strategic Shifts Shaping 2032 Growth
By pmarketresearch, 2026-09-18
Beyond the Boba Cup: Strategic Trends and Commercial Opportunities in the Bubble Tea Syrup Market
Market Snapshot: Navigating a Phase of Maturation and Complexity
The global bubble tea syrup market has entered a defining expansion phase, with total revenue reaching $2,150.0 million in base year 2025. Driven by sustained consumer enthusiasm and the international diffusion of Asian beverage culture, the market is projected to grow at a compound annual growth rate of 7.45%, advancing to an estimated $2,243.73 million in 2026 and reaching $3,555.43 million by 2032. Over the historical period from 2020 through 2025, the sector demonstrated consistent upward momentum, transitioning from a niche novelty to a structured global ingredient category. This trajectory reflects more than simple volume growth; it signals a market that is maturing, professionalizing, and increasingly susceptible to macroeconomic and regulatory forces.
PW Consulting Health Care Research Center
Despite the favorable growth backdrop, industry participants are navigating a period of structural transition. The first critical challenge lies in flavor standardization versus localization. As bubble tea operators scale across diverse cultural contexts, syrup providers must balance consistent taste profiles with regional palates, driving formulation complexity and elevating inventory management costs. The second challenge centers on supply chain fragility. Production depends heavily on sugar, fruit extracts, and natural flavor compounds, all of which remain exposed to agricultural volatility, export restrictions, and logistics bottlenecks. Price fluctuations in these inputs can quickly compress margins, particularly for mid-sized manufacturers operating with limited hedging capacity. The third challenge is the tightening regulatory perimeter. Markets in North America and Europe increasingly demand rigorous food safety certifications, traceability documentation, and compliance testing for imported syrup products. Navigating divergent regulatory frameworks while maintaining competitive lead times has become a prerequisite for sustained market access rather than a back-office compliance exercise.
Together, these dynamics are reshaping how syrup companies prioritize portfolio design, sourcing strategies, and geographic expansion. The market's continued growth is no longer solely a function of rising tea shop openings; it is increasingly determined by which players can align product innovation with supply resilience and regulatory readiness.
Key Demand Drivers: Forces Reshaping the Value Chain
Ingredient Innovation and Formulation Agility
The beverage landscape is shifting away from uniform sweetness profiles toward layered, experience-driven flavor architectures. Syrup manufacturers are responding by investing in multi-stage flavor layering, juicy acid-sugar balances, and texture-enhancing additives that complement tapioca pearls, jellies, and popping toppings. Recent activity in the sector highlights this strategic pivot. Companies are actively showcasing advanced syrup portfolios at major international trade events, using platforms like TUTTOFOOD Milano, IFE London, and the Winter Fancy Food Show San Diego to preview formulations tailored to emerging consumer expectations. These exhibitions have become essential testing grounds for cross-category inspiration, where fruit-forward blends, dessert-inspired reductions, and botanical accents are evaluated for mainstream commercial viability.
Equally significant is the acceleration of functional and health-aligned formulations. Consumer habits are evolving toward reduced-sugar, natural, and functional syrup concepts, including adaptogen-infused flavors and clean-label profiles. Syrup suppliers that embed these attributes early are capturing premium positioning and building loyalty with health-conscious operators. The competitive advantage now lies not just in taste replication but in delivering formulations that align with broader wellness narratives without sacrificing the indulgent experience that defines bubble tea.
Regulatory Pressure as a Catalyst for Quality Infrastructure
Food safety regulations in major Western markets have tightened considerably, requiring extensive testing, certification, and documentation for imported syrups. Rather than treating compliance as a reactive hurdle, leading manufacturers are using regulatory convergence as a driver of operational excellence. Suppliers are building internal quality frameworks that integrate HACCP, ISO, FDA, and Halal standards, creating multi-certified product lines that can cross borders with reduced friction. This shift is also reshaping buyer expectations. Franchise chains and QSR operators now prioritize suppliers who can demonstrate auditable quality processes across multiple jurisdictions, effectively turning regulatory capability into a procurement differentiator.
Cost Structure and Supply Chain Reconfiguration
Raw materials account for roughly 45-55% of operating expenses in bubble tea-related manufacturing, with sweeteners and fruit derivatives representing the largest cost blocks. This concentration makes cost volatility a strategic risk. Industry participants are responding by diversifying sourcing geographies, securing forward contracts for key inputs, and investing in formulation optimization to reduce dependency on price-sensitive commodities. Several manufacturers are also exploring concentrated juice and pulp integration to add perceived value while managing base ingredient costs. The broader effect is a supply chain under structural recalibration, where resilience and cost predictability are becoming as important as flavor performance.
Worldwide Flavor Tea Market
Competitive Landscape: Positioning, Diversification, and Consolidation Signals
The market remains relatively fragmented, with CR3 and CR5 concentration levels at 22.4% and 31.8% respectively. This structure leaves ample room for specialized players while simultaneously encouraging consolidation among manufacturers seeking scale, certification breadth, and geographic reach. Several core companies illustrate the strategic diversity emerging across the competitive field. Taiwan-based Sunnysyrup Food Co., Ltd. leverages more than six decades of manufacturing experience to offer concentrated juice, flavor syrups, popping boba, and full bubble tea ingredient suites, supported by OEM/ODM capabilities. Its active presence at multiple international trade shows reflects a go-to-market strategy centered on showcasing integrated solutions rather than single-ingredient transactions.
Chinese manufacturer Zonegoing Food has built its positioning around bulk boba syrup supply, including caramelized milk and brown sugar varieties, backed by HACCP, ISO, FDA, and Halal certifications. This multi-certification footprint enables cross-border flexibility and supports wholesale and private-label partnerships. Meanwhile, Fanale Drinks differentiates through ingredient transparency, offering flavoring syrups made in Taiwan with up to 25% real fruit juice and pulp, targeting operators seeking premium fruit-forward positioning. On the distribution side, Bossen and Qbubble serve as wholesale gateways, with Qbubble adding training and consultation services to deepen operator relationships beyond ingredient supply. Inspire Food Company has carved out a European leadership role by combining syrups, popping boba, tapioca pearls, and accessories into a single-channel offering, simplifying procurement for regional operators. Possmei extends its Taiwanese manufacturing base through U.S. agents and global distribution, while Yujie Food focuses on bulk syrups, jams, and cane sugar inputs, appealing to cost-sensitive and volume-driven segments.
Bubble Tea Market
The strategic divergence across these players points to a market that is simultaneously consolidating around certification and scale while fragmenting around niche differentiation. Leading manufacturers are moving beyond commodity syrup supply into integrated ingredient ecosystems, technical support, and portfolio depth. New entrants are likely to succeed by targeting underserved flavor specializations, functional claims, or regional compliance readiness rather than competing solely on price. The next phase of competitive evolution will favor companies that can combine formulation agility with reliable export infrastructure and clear brand narratives around quality, flavor authenticity, and operational support.
Future Outlook: Trends Shaping the Next Three to Five Years
Premiumization and Functional Flavor Convergence
Over the next three to five years, the syrup market is likely to see accelerated convergence between premium taste design and functional positioning. Consumers and operators will increasingly expect syrups that deliver layered flavor experiences while aligning with reduced-sugar, natural, or wellness-oriented narratives. This trend creates commercial opportunities for manufacturers who can develop clean-label bases, adaptogen or botanical additives, and fruit-forward formulations that command higher margins without alienating core indulgence buyers. Brands that invest early in R&D around these hybrid profiles will be better positioned to secure premium contracts with expanding tea houses and specialty beverage concepts.
Geographic Expansion in Asia Pacific and North America
Asia Pacific continues to anchor significant demand, supported by cultural familiarity, dense tea house networks, and rapid novelty adoption. North America remains a powerful growth engine driven by mainstream beverage experimentation, QSR integration, and wholesale distribution. Syrup suppliers that build localized portfolio strategies for these regions—adapting flavor intensity, packaging sizes, and certification readiness—can capture disproportionate share during the forecast period. Expansion success will depend less on blanket global offerings and more on region-specific product architectures that match local procurement habits and regulatory expectations.
Operational Resilience as a Competitive Moat
Supply chain volatility and raw material cost sensitivity will continue to reward manufacturers with diversified sourcing, forward procurement discipline, and formulation efficiency. Companies that treat cost resilience as a core capability rather than an operational afterthought will be better equipped to maintain pricing stability and margin protection. At the same time, regulatory divergence across markets will increase the premium on multi-certified production systems. The operational players that can scale while preserving compliance agility will hold a durable advantage, especially as larger franchise and retail buyers consolidate supplier lists around reliability and risk management.
Potential risks include overinvestment in narrowly defined flavor trends that may cycle quickly, escalating input costs that erode pricing power, and regulatory shifts that alter import requirements faster than supplier certification cycles can adapt. Navigating these uncertainties will require scenario-aware portfolio planning and flexible manufacturing footprints.
Strategic Actions for Decision Makers
For syrup manufacturers and ingredient suppliers: prioritize formulation platforms that can scale across premium, reduced-sugar, and functional variants without fragmenting production efficiency. Invest in multi-certification readiness and geographic sourcing diversification to reduce exposure to raw material volatility and import barriers. Use trade show channels and technical consultation services to deepen relationships with operators, turning ingredient supply into a broader operational partnership.
For investors evaluating exposure: focus on companies with credible OEM/ODM capabilities, multi-region certification coverage, and distribution infrastructure that supports export scalability. Favor business models that combine portfolio breadth with clear differentiation in flavor authenticity or functional positioning, as these are likely to command resilience in a fragmented but consolidating market. Monitor consolidation indicators, particularly around certification-driven M&A or regional distribution tie-ups.
For tea house operators, QSR buyers, and procurement teams: treat syrup selection as a strategic input that affects menu differentiation, compliance risk, and margin stability. Prioritize suppliers who can demonstrate consistent quality, regional certification coverage, and portfolio flexibility across fruit, brown sugar, and floral/herbal lines. Negotiate for formulation support and menu co-development where possible, since supplier collaboration can accelerate seasonal launches and reduce time-to-market for new offerings.
For operators, investors, and manufacturers seeking detailed segmentation data, region-specific demand mapping, and tailored scenario planning across the 2026-2032 forecast horizon, PW Consulting's full market research report provides deeper quantitative breakdowns and customized strategic guidance.
For detailed analysis of this topic, please visit the official page: Bubble Tea Syrup Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Pin Surface Treatment Chemicals Market: Why 6.74% CAGR Predicts 2032's $2.13B Trajectory
By pmarketresearch, 2026-09-18
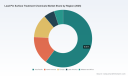
Strategic Shifts and Commercial Opportunities in the Global Lead Pin Surface Treatment Chemicals Market
Market Landscape and Core Challenges
The global market for lead pin surface treatment chemicals has demonstrated consistent expansion over the past half-decade, reflecting the broader trajectory of advanced electronic packaging and precision metal finishing sectors. Valued at approximately $984 million in 2020, the market has progressed through steady annual increments to reach an estimated $1.35 billion in 2025. Forward projections indicate continued momentum, with the market expected to surpass $1.84 billion by 2030 and approach $2.13 billion by 2032, translating to a compound annual growth rate of roughly 6.74% across the forecast horizon. This growth trajectory is underpinned by persistent demand for reliable surface finishing solutions that enhance conductivity, corrosion resistance, and solderability in complex electronic assemblies.
Structurally, the market exhibits notable regional concentration, with Asia Pacific accounting for the largest share of revenue generation, followed by North America, Europe, Latin America, and the Middle East and Africa. Chemical type segmentation reveals that electroplating solutions dominate the product mix, while cleaning and degreasing agents, de-flashing chemicals, and surface passivation agents collectively represent the remainder of industry spend. Application-wise, integrated circuit packaging and consumer electronics connectors remain the primary demand centers, with automotive electronic components and industrial/telecommunications applications rounding out the core end-use segments. The competitive environment is moderately consolidated, with the top three participants commanding over 40% of total market revenue and the top five firms capturing nearly 57%, indicating that scale, proprietary formulations, and established customer relationships continue to provide meaningful barriers to entry.
Despite this favorable growth backdrop, the industry faces several structural challenges that will define competitive outcomes over the next several years. First, regulatory pressure continues to intensify across major jurisdictions. Stricter environmental legislation, including REACH enforcement and evolving EPA restrictions on hazardous substances, is reshaping formulation requirements. Surface treatment chemistry for lead pins and electronic components must increasingly eliminate or reduce reliance on hexavalent chromium, minimize volatile organic compound emissions, and accommodate lower-toxicity metal alloys. These compliance demands raise formulation complexity and can extend qualification timelines, particularly for high-reliability applications. Second, raw material volatility has become a persistent operational concern. Prices for metal salts, acids, and specialty additives that form the backbone of electroplating baths and cleaning solutions remain subject to geopolitical supply disruptions, energy cost fluctuations, and shifting mining outputs. This creates margin compression risk for producers who cannot pass through cost increases quickly or who lack diversified sourcing strategies. Third, the rapid evolution of electronic packaging architectures is forcing surface treatment suppliers to adapt at a faster pace than historical norms. Miniaturization, high-density interconnect designs, and mixed-material substrates place new demands on plating uniformity, adhesion, and defect control, requiring more frequent process innovation and closer collaboration with equipment manufacturers and end users.
These dynamics create a clear inflection point. Companies that rely on legacy product lines without regulatory or performance upgrades risk gradual share erosion, while those investing in compliant formulations, flexible supply chains, and application-specific engineering support are positioned to capture disproportionate value as customers navigate qualification and compliance transitions.
Key Growth Drivers
Technological Innovation in Surface Finishing Chemistry
One of the most significant accelerants for the market is the ongoing development of advanced plating chemistries and surface treatment processes tailored to the precision requirements of modern electronic components. Electroplating solutions continue to dominate product demand because they deliver the combination of conductivity, solderability, and mechanical protection that lead frames, connectors, and IC packaging structures require. However, the nature of innovation is shifting from incremental performance gains toward multi-functional formulations that simultaneously address corrosion resistance, interfacial adhesion, thermal stability, and environmental compliance.
Recent industry activity illustrates this shift in practice. In February 2026, Technic Inc. showcased surface finishing solutions aimed at complex precision component challenges, including chemistry relevant to electronic component manufacturing for medical device applications. While the demonstration emphasized medical device use cases, the underlying capability set—controlled deposit uniformity, specialty alloy and tin/tin alloy chemistry, and process integration for high-precision substrates—directly parallels demands in lead frame and connector surface treatment. Demonstrations of this type signal that leading suppliers are building application cross-over expertise, using adjacent high-reliability sectors to refine chemistries that can be redeployed into electronic packaging environments with demanding tolerance requirements.
Beyond electroplating, complementary process chemistry is also advancing. Cleaning and degreasing agents, de-flashing chemicals, and surface passivation agents are increasingly specified as integrated pre-treatment and post-treatment steps rather than standalone consumables. This reflects a broader recognition that surface quality is determined by the full process chain. Suppliers that can offer compatible chemistry suites—cleaner, activator, plating bath, and passivation—reduce variability for manufacturing lines and shorten process qualification cycles, which is a meaningful commercial advantage in cost-sensitive, high-volume production environments.
Worldwide Lead Solder Ball Market
Regulatory and Environmental Compliance Pressures
Regulatory developments continue to act as both a constraint and a catalyst. Stringent global environmental regulations, including REACH and EPA restrictions on hazardous substances, are accelerating the transition toward eco-friendly, chrome-free, and lower-VOC surface treatment formulations for electronics applications. For lead pin and lead frame surface treatment specifically, the shift is particularly consequential because traditional brighteners, corrosion inhibitors, and passivation chemistries have historically relied on substances that are increasingly scrutinized.
Compliance is not merely a defensive requirement; it is becoming a competitive differentiator. End users in consumer electronics, automotive electronics, and industrial systems are under their own sustainability and disclosure mandates, which flow down to component suppliers and further to chemical providers. Formulations that reduce hazardous substance exposure, support waste treatment efficiency, and lower energy consumption during bath maintenance are increasingly preferred in supplier selection. As a result, companies that proactively develop and validate compliant chemistries can secure longer qualification cycles, deeper integration into customer process workflows, and a stronger position in regions where regulatory enforcement is most active.
PW Consulting
Demand-Side Shifts in Electronics and Automotive Electronics
Demand-side behavior is being reshaped by three interrelated forces: the proliferation of high-reliability electronic interconnects, the expansion of automotive electronic content, and the continued scaling of consumer electronics connector usage. Integrated circuit packaging remains the largest application driver because surface treatment quality directly affects signal integrity, solder joint reliability, and protection against environmental degradation. As packaging complexity increases, particularly in advanced interconnection schemes and finer pitch layouts, the surface treatment layer becomes more critical to overall assembly yield.
Consumer electronics connectors also sustain robust chemical demand. The ongoing refresh cycle for mobile devices, wearables, and connected peripherals sustains high volumes of connector production, where surface finish consistency influences contact resistance, corrosion life, and mating reliability. Meanwhile, automotive electronic components represent a structurally important growth avenue. Vehicle electrification, advanced driver-assistance systems, and in-vehicle connectivity continue to increase the number and complexity of electronic control units and interconnect assemblies. Automotive-grade requirements for thermal cycling, vibration resistance, and long-term corrosion protection place elevated demands on plating and passivation chemistry, encouraging adoption of higher-performance surface treatment solutions.
Supply Chain Dynamics and Cost Structure Evolution
Cost structure dynamics are evolving as raw material price fluctuations in metal salts, acids, and specialty additives continue to influence production economics for electroplating and cleaning solutions. These inputs are essential to bath chemistry, and price instability can quickly affect gross margins, especially for high-volume commodity-grade products. At the same time, supply chain regionalization is reshaping procurement strategies. Customers are increasingly prioritizing supply continuity and geographic proximity for critical process chemicals, particularly where production facilities are concentrated in Asia Pacific or near major electronics manufacturing clusters.
This environment favors suppliers with diversified input sourcing, inventory buffer strategies, and the ability to offer technical support that helps customers optimize bath life, reuse, and waste handling. The competitive implication is clear: cost leadership alone is becoming less durable, while total cost of ownership advantages—derived from better process stability, fewer defect-related reworks, and reduced compliance risk—can command stronger customer retention.
Competitive Landscape and Leading Strategies
The market’s competitive structure reflects a blend of established specialty chemical manufacturers and regionally focused suppliers with strong application ties. Technic Inc., headquartered in Cranston, Rhode Island, is a prominent participant in specialty electroplating chemistry for lead frames, connectors, and electronic components. Its portfolio emphasis on precious metal and tin/tin alloy solutions for lead frame and LED substrate applications, along with connector-leadframe components, positions the company within the higher-value segment of the market where performance and qualification support matter more than price alone. Technic’s recent trade show participation, highlighting surface finishing solutions for complex precision manufacturing including medical device-related electronic component chemistry, suggests a strategy of extending application expertise across adjacent high-reliability segments, potentially reinforcing technical credibility and cross-industry learning.
MKS | Atotech, based in Berlin, operates with a strong focus on wet chemical process solutions for leadframe and connector applications. Its Puronon family of cleaners, chemical deflashing offerings, and pre-treatment processes tailored for IC lead frames and electronic packaging illustrate a process-integration orientation. Rather than competing solely on chemical formulation, the company appears to emphasize the fit between cleaning, treatment, and plating steps within production lines. This approach can reduce customer friction during process setup and improve consistency, supporting deeper relationships in IC packaging and connector manufacturing environments.
JCU Corporation, headquartered in Tokyo, offers surface treatment chemical products including alkaline electrocleaners, etching agents, and activators specifically intended for IC lead frames and electronic parts plating lines. Its product focus suggests a strong alignment with precision pre-treatment and process cleanliness, an area that is increasingly important as feature sizes shrink and defect sensitivity rises. By concentrating on the early stages of surface preparation, JCU addresses a part of the value chain where small variations can have outsized effects on downstream plating quality and final assembly reliability.
Lead Frames Market
Shanghai Sinyang Semiconductor Materials Co., Ltd. participates in the market through traditional packaging lead pin surface treatment chemicals as part of a broader portfolio spanning wafer processing and semiconductor electronic chemicals. Its positioning reflects the strategic importance of domestic supply in key Asian manufacturing ecosystems. Companies with local formulation, production, and technical service capabilities can gain advantages in responsiveness, logistics, and alignment with regional qualification requirements, particularly where electronics manufacturing activity is densely concentrated.
Nihon Parkerizing Co., Ltd., also based in Tokyo, supplies surface treatment chemicals for cleaning substrates and adding functionality, serving broad industrial applications including electronics and metal components. Its wider application footprint provides diversification across end markets and exposes the company to cross-sector innovation in surface functionality, which may feed back into electronics-specific development over time.
Several strategic themes emerge from this landscape. First, differentiation is increasingly tied to application-specific engineering capability. Companies that can combine formulation expertise with process troubleshooting, qualification support, and technical service are better positioned to defend margins than those competing primarily on product price. Second, the moderately concentrated market structure—where the top three firms capture a sizable share and the top five account for a majority—suggests that scale benefits matter, but they are not insurmountable. Smaller or regionally focused players can succeed by serving niche applications, offering specialized process chemistry, or building strong local service networks. Third, the market appears primed for selective consolidation and portfolio expansion. Larger participants may seek to acquire complementary process chemistries, regional service assets, or formulation capabilities that strengthen their ability to deliver end-to-end solutions. At the same time, new entrants with differentiated technology—such as low-environmental-impact chemistries or advanced deposit control—may find opportunities in segments where incumbents face regulatory or performance transitions.
Future Trends and Commercial Implications
Looking ahead, three trends are likely to shape the market over the next three to five years. The first is the continued expansion of compliance-driven formulation development. As environmental regulations and corporate sustainability expectations tighten, demand will increasingly favor chrome-free, lower-VOC, and otherwise reduced-hazard surface treatment chemistries. This will create commercial opportunities for suppliers that can demonstrate equivalent or superior performance while meeting regulatory and customer disclosure requirements. It will also raise the cost of inaction for companies still dependent on legacy formulations that face longer qualification timelines or sourcing constraints.
The second trend is the growing importance of integrated process chemistry rather than standalone consumables. As lead pin and connector manufacturers seek to reduce variability, improve yield, and accelerate line changeovers, they will favor suppliers that can support the full sequence of cleaning, surface activation, plating, and passivation. This trend favors companies with broader portfolios and stronger technical service depth, and it increases the strategic value of partnerships between chemical suppliers, equipment providers, and end users.
The third trend is the geographic realignment of supply and technical support around major manufacturing hubs. Demand concentration in Asia Pacific will continue to reward suppliers with local formulation, production, and service capabilities, while also encouraging multinational participants to strengthen regional presence and responsiveness. Over time, this may contribute to a more multi-polar competitive structure, where global technology leadership and local execution capability both matter.
Associated risks deserve attention. Raw material price volatility may persist, especially if input supply chains remain exposed to geopolitical disruption or energy cost swings. Regulatory requirements may evolve faster than formulation cycles in some jurisdictions, creating compliance misalignment risk for slower-moving players. In addition, changes in electronic packaging architecture and interconnect design could shift demand patterns between chemical types and application segments more quickly than historical trends would suggest, making portfolio flexibility a critical capability.
Strategic Recommendations for Decision-Makers
For manufacturers and process engineers, the priority is to align surface treatment chemistry choices with both performance targets and compliance trajectories. Selecting formulations with stronger environmental profiles and broader process compatibility can reduce qualification risk and support smoother transitions as regulatory expectations rise. Manufacturers should also evaluate suppliers based on total process support rather than product price alone, since formulation stability, defect reduction, and technical responsiveness often have a larger impact on operating economics than unit cost differences.
For investors and business development teams, the key is to identify companies with durable differentiation in application-specific chemistry, regulatory readiness, and regional service capability. Portfolio breadth, technical service depth, and the ability to integrate cleaning, plating, and passivation solutions are likely to be more predictive of competitive resilience than scale alone. Opportunities may also arise in adjacent high-reliability sectors, where cross-industry learning can accelerate product development for electronics applications.
For procurement and supply chain leaders, diversification of supplier sources and chemistry options can reduce exposure to raw material volatility and single-source qualification risk. Cost management should increasingly account for bath life optimization, waste handling efficiency, and process stability, since these factors influence total ownership cost. As regional manufacturing concentration continues, proximity of supply and local technical support may become more important selection criteria, particularly for high-volume or high-reliability programs.
Given the pace of regulatory change, raw material variability, and application-level demand shifts, detailed and current segmentation data will be essential for precise planning. The full report provides deeper visibility into regional revenue distributions, chemical type and application splits, competitive share dynamics, and scenario-based forecasts that can support more targeted strategic decisions and customized operational planning.
For detailed analysis of this topic, please visit the official page: Worldwide Lead Pin Surface Treatment Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
5-Bromo-2,4-dichloropyrimidine Market: Why 6.31% CAGR Changes Asia Pacific Winners
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Global 5-Bromo-2,4-dichloropyrimidine Market
Market Overview and Core Challenges
The global market for 5-Bromo-2,4-dichloropyrimidine has entered a phase of steady structural expansion, driven by its entrenched role as a critical heterocyclic building block in pharmaceutical and fine chemical value chains. Valued at approximately USD 142.5 million in 2025, the market has demonstrated consistent compounding growth since 2020, when it stood at USD 102.34 million. Projections indicate that this upward trajectory will persist through the end of the decade, with the market expected to surpass USD 200 million by 2031 and approach USD 218.69 million by 2032. This expansion translates to a compound annual growth rate of 6.31 percent across the 2026 to 2032 forecast window.
Such growth is neither accidental nor isolated. It reflects a broader industry pattern wherein specialized halogenated pyrimidine intermediates have become indispensable to modern drug discovery and process chemistry. The compound serves as a versatile electrophilic scaffold, enabling nucleophilic substitution and cross-coupling reactions that underpin the synthesis of kinase inhibitors, immunomodulators, and other targeted therapeutics. Parallel to pharmaceutical demand, academic and industrial laboratory research continues to provide a stable baseline of consumption, while niche applications in agrochemical synthesis add incremental volume.
Beneath the headline growth figures, however, the market faces structural friction that will define profitability and supply reliability over the next several years. The first challenge lies in raw material volatility and its downstream impact on pricing discipline. The synthesis of related chlorinated pyrimidine derivatives depends heavily on chlorination agents and precursor heterocycles that have experienced quarterly price swings exceeding 40 percent since 2022. These fluctuations force manufacturers into unpredictable cost structures, compress margins on standardized grades, and complicate long-term contract negotiations with downstream formulators.
The second challenge centers on regulatory classification and logistics complexity. The material is classified for transport as UN3261, a corrosive solid, acidic, organic, n.o.s., falling under Hazard Class 8, Packing Group III under DOT, IATA, and IMDG frameworks. This designation introduces mandatory compliance layers for packaging, labeling, carrier qualification, and cross-border documentation. For manufacturers and distributors operating across multiple jurisdictions, the cumulative administrative and operational burden restricts agility in scaling shipment volumes and increases the cost of market entry for smaller regional players.
A third pressure point is the clustering of commercial activity around a concentrated supplier base. The top three firms account for roughly 42 percent of market share, while the top five capture nearly 59 percent. Such concentration creates an environment where pricing transparency is limited, alternative sourcing paths are narrow, and supply disruptions at a single facility can ripple through downstream pipelines. At the same time, this structure incentivizes incumbents to protect margin by differentiating on purity consistency, documentation quality, and technical support, raising the barrier for new entrants who lack established quality systems or regulatory familiarity.
For business leaders, the implication is clear: the market is growing reliably, but growth alone does not guarantee operational stability or margin preservation. Firms that navigate raw material exposure, transport compliance, and supplier concentration with disciplined sourcing strategies and technical differentiation will be better positioned to convert volume expansion into sustainable commercial advantage.
Key Drivers of Market Change
Several interlocking forces are reshaping how 5-Bromo-2,4-dichloropyrimidine is produced, priced, and deployed across end-use sectors. Understanding these drivers is essential for anticipating where capacity, pricing power, and partnership opportunities will emerge.
Technological Innovation and Process Optimization
Advances in synthetic methodology and scale-up engineering are gradually reshaping the cost and quality profile of the compound. Manufacturers that have invested in continuous or semi-continuous chlorination and bromination pathways are achieving tighter control over impurity profiles, which directly supports the production of higher-purity grades demanded by pharmaceutical clients. At the same time, process intensification efforts are reducing batch-to-batch variability and improving yield reproducibility, which matters greatly for customers running multi-step syntheses where intermediate purity can influence downstream reaction efficiency.
Recent commercial listings and supplier updates illustrate this trajectory. In late 2025, multiple suppliers maintained or expanded offerings emphasizing 99 percent purity thresholds, while others continued to supply the 98 percent grade that remains a workhorse standard for many intermediate applications. The coexistence of these purity tiers reflects a market that is simultaneously optimizing for cost-effective scale and for the stricter analytical specifications required by regulated drug development programs. Suppliers that can reliably bridge both segments, without compromising documentation or lot consistency, are gaining preferential positioning in procurementreviews.
Policy and Regulatory Evolution
The regulatory backdrop is steadily maturing, albeit without introducing abrupt restrictions that would fundamentally constrain trade. In the United States, the compound is listed under the TSCA inventory, providing a recognized pathway for commercial handling and import. Within the European framework, the substance does not currently appear under specific Annex XIV authorization requirements or Annex XVII restrictions under REACH, which reduces immediate compliance friction for EU-facing supply chains. These conditions create a permissive but monitored environment where established manufacturers can operate with predictable regulatory overhead, provided they maintain up-to-date safety documentation and transport classification compliance.
This environment is not static. Updated Safety Data Sheets, such as those refreshed in late 2025 by major distributors, reaffirm the corrosive solid classification and emphasize ongoing commercial availability under hazard-aligned logistics protocols. The practical effect is a market where regulatory clarity supports continuity, but where any future tightening of classification, packaging mandates, or import documentation could quickly alter cost structures. Firms that proactively maintain compliance infrastructure and monitor jurisdictional updates will be better insulated against sudden operational shifts.
Demand-Side Shifts in Pharmaceutical and Research Workflows
Demand dynamics are being reshaped by the broader architecture of modern drug development and fine chemical synthesis. The compound's role as a trisubstituted pyrimidine precursor positions it squarely within the workflow of kinase inhibitor programs and other targeted therapy pipelines, where modular building blocks are repeatedly iterated across lead optimization and process development phases. As these pipelines expand and as development timelines compress, the demand for intermediates that offer predictable reactivity, well-characterized impurity profiles, and reliable lot availability increases correspondingly.
PW Consulting
Beyond drug development, the laboratory research segment continues to serve as a stable demand anchor. Academic groups, contract research organizations, and internal R&D teams rely on the intermediate for exploratory synthesis, method development, and small-scale feasibility studies. While this segment rarely drives the largest volume swings, it contributes to baseline consumption and supports the supply ecosystem that larger commercial buyers depend upon. A third, smaller demand stream emerges from agrochemical synthesis, where the same heterocyclic scaffold supports the construction of active ingredients and formulation intermediates. Though modest in relative size, this segment adds diversification to the demand base and can become more significant if crop protection portfolios expand their use of halogenated pyrimidine chemistry.
2-Amino-5-bromothiazole Monohydrobromide Market
Supply Chain and Cost Structure Dynamics
Cost structures remain highly sensitive to upstream chemical volatility. The dependence on pyrimidine derivatives and chlorination agents means that price swings in basic halogenation inputs propagate rapidly through the value chain. Since 2022, quarterly fluctuations in these inputs have exceeded 40 percent at times, creating an environment where static pricing models quickly become unsustainable. Suppliers have responded by adopting more flexible contract structures, hedging strategies where feasible, and closer integration with precursor suppliers to improve visibility into input availability and cost trends.
Logistics and handling costs form another layer of the supply chain equation. The corrosive solid classification requires specific packaging, carrier training, and documentation workflows that add cost at every transfer point. Companies that standardize these processes, invest in compliant packaging inventories, and maintain relationships with trained logistics partners can reduce per-unit handling premiums. Conversely, organizations that treat transport compliance as an afterthought often encounter delays, rework, and unexpected surcharges that erode margin.
Taken together, these drivers point to a market where competitive advantage is increasingly derived from process reliability, documentation rigor, and supply chain agility rather than from volume alone. Buyers are prioritizing partners who can demonstrate consistent purity, transparent lot records, and the operational capacity to manage regulated transport without disruption. Suppliers that align their capabilities with these expectations are capturing stronger commercial positioning even in a price-sensitive environment.
Competitive Landscape and Leading Strategies
The competitive environment for 5-Bromo-2,4-dichloropyrimidine is characterized by a mix of established fine chemical manufacturers, regional producers with integrated synthesis capabilities, and global scientific suppliers that bridge laboratory-scale and commercial-scale demand. Rather than competing solely on price, leading players differentiate through purity consistency, application-specific documentation, scale flexibility, and technical support that reduces friction for downstream users.
In India, several manufacturers have built commercial positions around the production of the intermediate for pharmaceutical applications. Jay Finechem, headquartered in Gujarat, is known for supplying the compound in powder form with a 98 percent assay, supporting drug development programs for medicines such as Ribociclib, Trilaciclib, and Palbociclib. Simson Pharma and Vandana Chem similarly serve domestic and international clients, emphasizing competitive quality and export-oriented logistics. These Indian-based producers benefit from established fine chemical manufacturing infrastructure, proximity to key precursor supply networks, and growing experience in serving regulated pharmaceutical supply chains. Their strategic positioning tends to center on reliable batch output, assay consistency, and the ability to support both intermediate production and downstream formulator requirements.
Across China, the landscape features manufacturers and suppliers that span research-grade and larger-scale commercial offerings. COLORKEM, based in Zhejiang, offers the compound as a pale yellow liquid pharmaceutical intermediate with content at or above 99 percent, packaged in standard bag sizes for chemical and pharmaceutical applications. BLD Pharmatech, in Shanghai, supplies the material primarily for research and development use in pharmaceutical and fine chemical synthesis, catering to teams that require well-characterized lots for exploratory and scale-up studies. AstaTech (Chengdu) Biopharmaceutical Corp. positions its offering around intermediate applications in nucleophilic substitution and cross-coupling reactions, emphasizing compatibility with trisubstituted pyrimidine synthesis workflows. In late 2025, additional commercial activity appeared from regional producers such as Henan Aochuang Chemical, which indicated supply capability at the ton scale for 98 percent purity material, and Shaanxi Dideu New Materials, which listed 99.0 percent purity material at industrial scale. These listings reflect a market in which Chinese suppliers are actively expanding both purity options and volume capacity to capture demand from cost-conscious development programs and production-scale buyers.
Global scientific distributors add a distinct layer to the competitive field. TCI America, operating under Tokyo Chemical Industry, supplies high-purity material at 97 percent or higher for laboratory and synthesis use across pharmaceutical and agrochemical applications. Thermo Fisher Scientific, including its Alfa Aesar portfolio, provides 98 percent material for chemical synthesis and intermediate applications, supported by broad distribution infrastructure and standardized quality documentation. Sigma-Aldrich, under Merck KGaA, offers 97 percent material as a halogenated pyrimidine intermediate for organic synthesis in pharmaceutical and agrochemical sectors. These firms leverage global reach, established procurement pathways, and strong technical support networks to serve customers who value availability, documentation completeness, and multi-region logistics more than localized price advantages.
Recent operational developments reinforce how these players are adapting. Updated safety documentation from Thermo Fisher Scientific in September 2025 confirmed the transport classification and reaffirmed ongoing commercial availability, signaling that major distributors continue to prioritize compliance clarity alongside supply continuity. Meanwhile, new listings and scale indications from regional producers in 2025 point to growing capacity and an intensifying focus on purity tiers that match specific buyer requirements. This dynamic suggests a market that is gradually bifurcating: one track emphasizing high-purity, well-documented material for regulated pharmaceutical workflows, and another emphasizing cost-competitive, scale-oriented supply for research and intermediate production where specifications are slightly less restrictive.
Strategically, the market concentration pattern reinforces the importance of differentiation. With the top three and top five suppliers holding substantial share, incumbents protect their positions by reducing buyer risk through lot traceability, analytical support, and responsive logistics. New entrants face a challenging path unless they bring clear advantages in purity control, regional proximity, or specialized application support. The most probable evolution in the near term is a combination of consolidation among smaller distributors seeking scale efficiencies and selective fragmentation as regional manufacturers expand capacity to capture demand from specific therapeutic or geographic segments.
For decision-makers evaluating supplier relationships, the practical takeaway is that competitive strength in this market is not measured by catalog breadth alone. It is reflected in the ability to deliver consistent assay results, maintain audit-ready documentation, manage regulated transport without disruption, and support the specific synthetic workflows of downstream users. Suppliers that build these capabilities systematically tend to secure longer-term procurement relationships and greater resilience against pricing pressure.
Future Trends and Commercial Implications
Looking ahead to the next three to five years, the market for 5-Bromo-2,4-dichloropyrimidine is likely to be shaped by three interrelated trends, each carrying distinct commercial implications.
The first trend is a continued drift toward higher and more consistently documented purity tiers for pharmaceutical-facing supply. As drug development programs increasingly rely on well-characterized intermediates to reduce downstream variability and support regulatory submissions, buyers will place greater weight on lot-to-lot reproducibility, analytical certificates, and traceability. Suppliers that standardize high-purity production and can provide robust documentation packages will find expanding opportunities to serve regulated pipelines and command pricing that reflects reduced technical risk for their customers. A related opportunity lies in offering tiered product configurations, allowing buyers to select between 99 percent grades for sensitive synthetic steps and 98 percent grades for cost-sensitive stages without sacrificing quality assurance.
The second trend is the gradual regional rebalancing of supply and demand. Demand from pharmaceutical development and fine chemical synthesis is not uniformly distributed, and procurement teams are increasingly sensitive to lead times, transport compliance costs, and currency exposure. This creates room for regional manufacturers that can offer shorter logistics paths, localized technical support, and flexible batch sizes. At the same time, global scientific distributors will continue to play a crucial role for buyers who require multi-region availability and standardized quality systems. The commercial opportunity here lies in building supply networks that combine regional responsiveness with globally recognized documentation standards, rather than treating proximity and scale as mutually exclusive options.
The third trend involves ongoing sensitivity to input cost volatility and regulatory adaptation. Because precursor chlorination agents and pyrimidine derivatives remain prone to significant quarterly price movement, suppliers and buyers alike will need to adopt more dynamic contracting approaches and maintain deeper visibility into upstream conditions. On the regulatory side, while the current classification and inventory status support stable operations, any future adjustments to hazard packaging requirements, import documentation, or jurisdictional listings could shift cost structures quickly. Firms that invest in compliance readiness, packaging standardization, and proactive monitoring of regulatory updates will be better prepared to absorb such changes without losing service reliability.
The principal risks to watch include sustained input price swings that erode margin predictability, supply disruptions concentrated among a limited number of high-share producers, and potential regulatory changes that increase handling or documentation burdens. These risks do not undermine the market's growth trajectory, but they do raise the importance of portfolio diversification, supplier redundancy, and technical due diligence in procurement decisions.
Actionable Guidance for Decision-Makers
For manufacturers and suppliers, the priority is to convert process reliability into differentiated commercial value. Investing in consistent purity output, robust analytical documentation, and compliant packaging inventories can reduce buyer-perceived risk and support longer-term contracts. Developing flexibility across purity tiers and scale options allows suppliers to serve both research-stage and production-stage customers without compromising quality standards. Where feasible, strengthening visibility into precursor availability and cost trends will improve pricing resilience amid volatile input markets.
Worldwide Bromoacetic Acid Market
For investors evaluating exposure to this segment, the emphasis should be on operational maturity and supply chain positioning rather than on volume growth alone. Suppliers with established quality systems, audit-ready documentation, and diversified customer bases are better equipped to maintain margin stability through input volatility and regulatory adjustments. Capacity expansion that is paired with documentation capability and logistics compliance offers a more durable value proposition than capacity growth in isolation.
For procurement teams and sourcing managers, the most effective approach is to evaluate suppliers on a combination of purity consistency, documentation completeness, transport compliance readiness, and technical support quality. Diversifying across regional and global partners can reduce exposure to single-source disruption while maintaining access to different scale and purity configurations. Establishing clear specification requirements, lot traceability expectations, and compliance documentation standards at the outset of a procurement relationship will reduce friction during scale-up and limit the risk of unexpected handling or logistics costs.
Detailed segmentation data, purity-grade dynamics, regional volume patterns, and company-level strategic profiles can help translate these observations into precise sourcing, investment, and capacity decisions. Readers seeking a deeper breakdown of market splits, competitive benchmarking, and forward-looking scenario analysis are encouraged to review the full study, which provides the granular data and structured frameworks needed to support enterprise-level planning.
For detailed analysis of this topic, please visit the official page: Worldwide 5-Bromo-2,4-dichloropyrimidine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Digital Signage Design Services Market: How 7.5% CAGR Redefines Revenue Trajectories to 2032
By pmarketresearch, 2026-09-18
The Digital Signage Design Services Market: Navigating Growth Amid Structural Shifts
Market Overview and Core Challenges
The global digital signage design services market has demonstrated steady expansion over the past five years, growing from approximately $1.57 billion in 2020 to an estimated $2.25 billion in 2025. This trajectory reflects a compound annual growth rate of 7.5 percent, with forecasts projecting further acceleration through 2032 as organizations across sectors increasingly treat in-store and in-facility visual communication as a strategic capability rather than a decorative afterthought. The baseline revenue expansion, when mapped against evolving deployment patterns, points to a market that is maturing but far from saturated at the design and content layer. Hardware commoditization has lowered entry barriers for screen deployment, yet the value capture has progressively shifted toward creative strategy, motion design, interactive architecture, and content management integration—the very service components that determine whether a digital display resonates or simply occupies wall space.
Beneath these headline figures, three structural tensions are reshaping how service providers compete and how buyers evaluate formats. First, the industry is confronting a demographic and talent bottleneck in specialized design labor. A significant share of professional sign designers in developed markets is over fifty years old, intensifying talent scarcity and placing upward pressure on project costs and turnaround times. This demographic reality is colliding with demand for more sophisticated visual storytelling, interactive wayfinding, and multi-screen content orchestration, creating a supply-demand imbalance that favors firms with structured design operations or scalable creative outsourcing models.
Second, regulatory complexity is rising across wireless emissions, data privacy, workplace safety, and accessibility. Deployments that incorporate wireless components must navigate radio-frequency compliance, while interactive screens processing personal data face consent and minimization requirements under privacy frameworks. Workplace and public-facing displays are also subject to visibility and accessibility standards that influence both content placement and system architecture. These obligations are not merely legal checkboxes; they shape design workflows, content governance, and the commercial terms of service engagements, particularly for enterprises operating across multiple jurisdictions.
Third, the market is experiencing a functional split between commodity display installation and differentiated content design. As networks scale into hundreds or thousands of nodes, buyers increasingly expect design services to be tightly coupled with content strategy, template governance, and platform integration. Providers that only deliver visual assets without strategic planning or CMS alignment are seeing margin compression, while those that unify creative, technical, and operational capabilities are capturing more durable engagements. The challenge for decision-makers is distinguishing between providers that can produce compelling visuals and those that can sustain brand consistency, compliance, and performance across entire screen estates.
Key Drivers Shaping Market Dynamics
Technological Innovation and Content Sophistication
A defining driver of current growth is the convergence of advanced display technologies with more capable content creation and management workflows. LED formats, high-brightness outdoor panels, touch-enabled interfaces, and cloud-based CMS platforms have expanded the creative palette, but the real commercial impact comes from how design services translate these capabilities into coherent visual experiences. Providers are increasingly expected to deliver motion graphics, templated content kits, and interactive wayfinding that can be updated at scale without losing brand integrity. The ability to design once and deploy consistently across multiple locations has become a decisive competitive dimension, especially for retail chains, hospitality groups, and large corporate campuses.
Recent industry activity underscores this shift toward design-plus-management offerings. In early 2026, a major retail operator implemented a platform to control digital signage screens across more than 900 stores, integrating content design and centralized management into a single operational workflow. This kind of deployment signals that buyers are no longer purchasing isolated design projects; they are investing in repeatable content systems that reduce localized production burden while maintaining visual quality. As creative teams adopt more modular design approaches—templates, motion libraries, localized variants—the service market is being reshaped around scalability, governance, and rapid iteration rather than one-off bespoke production.
Policy and Regulatory Influence on Design Practice
Regulatory expectations are becoming embedded into design processes rather than treated as post-deployment contingencies. Wireless connectivity requirements, privacy obligations for interactive kiosks, workplace visibility standards, and accessibility guidelines all influence how content is structured, where screens are positioned, and what data flows are permissible. For international operators, the challenge is multiplied by uneven regulatory expectations across regions, which can affect template design, consent mechanisms, and compliance documentation.
This environment favors providers that build compliance into the design stage. Firms that offer ADA-aligned visual considerations, privacy-aware interactive design, and documentation supporting workplace safety visibility can reduce retrofit risk for clients and create stronger differentiation. At the same time, regulatory attention raises the importance of content governance: who can update what, how personalization is handled, and how audit trails are maintained. Design services are therefore evolving from aesthetic production toward governed visual communication systems, a transition that expands the scope of professional engagements and raises the strategic stakes for buyers selecting partners.
Demand-Side Shifts in Consumer and Enterprise Behavior
End-user expectations are a powerful force behind service demand. In retail and hospitality, customers increasingly expect dynamic, context-aware visuals that support navigation, promotions, and experience design. In corporate and education environments, digital displays serve internal communication, wayfinding, and brand reinforcement functions that must feel consistent with broader identity systems. Healthcare and transportation settings add another layer of complexity, where clarity, accessibility, and real-time information accuracy can directly affect user experience and operational outcomes.
PW Consulting Information & Electronics Research Center
These demand patterns are pushing buyers toward service models that combine strategy, visual design, and platform integration. A display without a content plan tends to underperform, while a well-orchestrated visual system can improve engagement, reduce staff workload, and support localized messaging at scale. The commercial implication is clear: design services are being evaluated less on isolated creative quality and more on their contribution to operational efficiency, brand consistency, and user experience across multiple touchpoints. This is why enterprises are gravitating toward providers with in-house creative teams, reusable content structures, and proven deployment track records.
Supply-Side and Cost Structure Considerations
On the supply side, the maturation of fabrication networks, installation capabilities, and outsourced design models is altering cost structures and delivery models. Large national networks can bundle design, production, and installation, while specialized outsourcing firms offer flexibility for concept development, LED layout planning, and compliance-oriented signage solutions. This combination expands access to design capacity but also increases the importance of vendor management, quality control, and coordination between creative and technical teams.
Labor scarcity and demographic concentration in the design workforce add another layer of cost pressure. As experienced designers retire and demand rises for more complex interactive and multi-screen work, firms that can institutionalize design assets, build reusable libraries, and integrate production with clear technical specifications are better positioned to manage cost and turnaround. For buyers, this means total project economics increasingly depend on how well design services are structured for repeatability and how effectively providers balance creative quality with operational discipline.
Worldwide Product Design Service Market
Competitive Landscape and Leading Strategies
The competitive field is populated by organizations with distinct strategic anchors. Some providers compete through end-to-end capability, pairing in-house creative teams with installation and management services to deliver branded visual experiences across retail and hospitality environments. Others emphasize software-enabled visual communication with dedicated design support, offering custom signage designs, content kits, templates, and interactive wayfinding for enterprise clients. A further cluster of players operates as national or regional production networks, specializing in custom design, fabrication, and installation for menus, directories, promotions, and dynamic displays. Alongside these, architectural and urban integration specialists focus on landmark-scale experiences, while outsourced design firms provide concept development, LED layouts, and compliance-aware signage solutions.
This diversity produces clear differentiation paths. End-to-end providers gain advantage from integrated delivery, where creative, technical, and operational responsibilities are coordinated under one relationship, reducing fragmentation for multi-site clients. Software-centric players leverage repeatable content structures and enterprise visual communication expertise, making them attractive to organizations that need governance across many screens. Production networks differentiate through scale, localized execution, and speed to install, which matters for time-sensitive rollouts or distributed locations. Architectural integrators command premium positioning by linking digital displays to physical environments and experiential design, a niche that can be highly valuable for landmark projects but less applicable to broad-based deployments.
The market is evolving through both consolidation and specialization. Larger operators are expanding service portfolios and partnership networks to cover more of the value chain, while niche specialists deepen expertise in areas such as interactive design, accessibility, or outdoor durability. At the same time, recent partnership activity shows how installation-focused players are layering in custom design integration to strengthen their offerings. For example, a major signage network partnered to support digital signage installations in hospital environments with tailored design integration, illustrating how healthcare deployments are pushing providers to combine technical reliability with context-sensitive creative work.
Strategic positioning is increasingly defined by three questions: can the provider unify design strategy with content management, can it scale creative output without losing consistency, and can it navigate regulatory and accessibility requirements as part of the design process? Firms that answer these convincingly are building moats around recurring content operations rather than one-off projects. Buyers, in turn, are rewarded for selecting partners based on delivery discipline, content governance, and the ability to adapt creative assets across locations and use cases.
Forward-Looking Trends for the Next Three to Five Years
Design-as-a-System Becomes the Standard
Over the next several years, design services are likely to be judged increasingly on systemization rather than isolated creative output. Expect broader adoption of templated motion libraries, localized content variants, and governance frameworks that let enterprises update large screen networks efficiently. This trend will create opportunities for providers that can deliver modular design assets, clear style rules, and integration with CMS platforms, while also increasing the value of partners who can train internal teams and manage content workflows over time.
Interactive and Data-Rich Experiences Will Expand, With Guardrails
Interactive wayfinding, touch-enabled directories, and personalization-enabled displays will continue to grow in high-traffic and service-oriented environments. However, privacy expectations and compliance requirements will shape how these experiences are designed, particularly where personal data is processed. The commercial opportunity lies in building interactive experiences that are compelling without over-collecting data, supported by consent design and transparent data handling. Providers that can balance engagement with compliance will be better positioned for enterprise and public-sector work.
Integration with Physical Environments and Multi-Channel Identity Will Deepen
Digital signage will increasingly be treated as part of a broader environmental and brand identity system, not a standalone medium. Architectural integration, lighting considerations, and coordination with broader communication channels will matter more as deployments seek to reinforce cohesive experiences across spaces. This creates opportunities for specialists who can bridge design, physical installation, and operational planning, but it also raises execution risk where coordination is weak. Projects that treat design, installation, and content management as separable silos are likely to face more rework, inconsistent results, and slower time to value.
Potential risks include talent constraints that slow creative delivery, regulatory changes that add compliance overhead, and price competition in commoditizing segments that pressure margins. Market participants that depend heavily on manual, bespoke workflows may find it harder to scale, while those that invest in reusable assets, structured processes, and integration-ready design will be better equipped to manage volatility.
Strategic Implications for Decision-Makers
For enterprises evaluating digital signage design services, the priority is to define the engagement around content systems rather than individual displays. This means specifying how strategy, visual design, localization, accessibility, and CMS integration will work together before scoping individual projects. Buyers should assess providers on repeatability, governance, and the ability to maintain brand consistency across multiple locations, not only on creative quality in isolation.
For investors and strategic planners, the most durable value appears to be linked to providers that combine creative capability with operational scale and integration-ready workflows. Businesses that can institutionalize design assets, support compliance-by-design practices, and deliver content across distributed networks are more likely to secure recurring engagements. Market observers should watch for consolidation among service providers, deeper partnerships between fabrication/installation networks and creative teams, and growing demand for interactive experiences that meet privacy and accessibility expectations.
For manufacturers and technology suppliers, the opportunity is to support design-led deployments with tools and specifications that make content creation, management, and compliance easier. Clearer technical standards, interoperability with common CMS platforms, and guidance on accessibility and visibility can help reduce friction between creative teams and installation operations. In a market where screens are increasingly commoditized, the differentiator is often how smoothly the surrounding design and management ecosystem functions.
Digital Signage Market
For all of these audiences, the strategic value lies in understanding where the market is heading before committing to large-scale deployments or partnership decisions. Detailed segmentation data, regional dynamics, end-user patterns, and provider-level benchmarks can sharpen planning significantly, especially when aligning investment or procurement choices with the likely trajectory of the market through the end of the decade and into the early 2030s.
For detailed analysis of this topic, please visit the official page: Digital Signage Design Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Prostaglandins Market: Why 5.24% CAGR and Ophthalmology Demand Reshape 2032
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Global Prostaglandins and Related Drugs Market
Market Overview and Core Challenges
The global market for prostaglandins and related drugs has demonstrated steady expansion over the past half-decade, moving from a valuation of approximately $12.45 billion in 2020 to an estimated $16.17 billion in 2025. This trajectory reflects a compound annual growth rate of 5.24 percent through 2032, signaling a maturing yet still dynamic therapeutic segment. The market’s resilience stems from its entrenched role in managing chronic conditions where prostaglandin-based mechanisms deliver measurable clinical outcomes. Revenue generation is broadly distributed across advanced economies and emerging regions, with North America and Europe collectively accounting for a significant share of total sales, while Asia Pacific continues to capture incremental growth driven by expanding healthcare access and localized manufacturing capacity.
Despite the favorable top-line momentum, the industry faces structural headwinds that will shape competitive positioning in the coming years. First, the proliferation of generic alternatives following the patent expirations of major branded prostaglandin analogs between 2010 and 2020 has fundamentally altered pricing dynamics. While this has improved patient access and broadened prescription volumes, it has simultaneously compressed margins for originator manufacturers and intensified the need for cost-efficient production models. Second, the segment is experiencing heightened scrutiny around supply chain resilience, particularly for active pharmaceutical ingredients where synthesis complexity and regulatory compliance requirements create bottlenecks. Third, reimbursement pressures are reshaping commercial strategies, as evidence from historical spending data shows a shift in payer behavior—from a period where branded products dominated utilization to an environment where formulary restrictions and cost-containment policies demand clearer value differentiation.
Prostaglandin Market
For executives and investors, these dynamics point to a market where scale, intellectual property strategy, and manufacturing agility will separate long-term winners from passive participants. The growth trajectory remains intact, but capturing value now requires navigating a landscape where clinical differentiation, regulatory navigation, and supply chain integration matter as much as therapeutic efficacy.
Key Drivers of Market Evolution
Technological Innovation and Formulation Breakthroughs
Advancements in drug delivery and molecule engineering are redefining how prostaglandin therapies are administered and experienced by patients. The introduction of sustained-release formats, such as intracameral implants, illustrates a broader shift toward reducing treatment burden and improving adherence in chronic conditions like glaucoma. Regulatory milestones have validated these approaches, with approvals expanding the clinical utility of established molecular classes into new administration routes and patient populations. Beyond ophthalmology, the extension of prostaglandin-based therapies into areas like severe frostbite management demonstrates how legacy molecules can find renewed relevance when paired with innovative delivery mechanisms or new clinical indications. These developments create commercial pathways for companies that can successfully integrate formulation science with clinical evidence generation.
Regulatory Environment and Policy Dynamics
The regulatory landscape continues to shape market entry, pricing, and competitive intensity. Approval timelines and label expansions directly influence the commercial lifespan of branded products and the pace at which generics can capture market share. Recent regulatory actions have underscored a dual trend: agencies are encouraging therapeutic innovation through expedited pathways for unmet needs, while simultaneously maintaining rigorous standards that reward high-quality manufacturing and comprehensive clinical data. For manufacturers, this environment rewards early investment in regulatory strategy, robust quality systems, and proactive engagement with evolving safety and efficacy expectations. Policy shifts around formulary management and reimbursement benchmarks further incentivize companies to articulate clear value propositions that align with payer priorities.
Demand-Side Shifts and Clinical Utilization Patterns
Clinical demand is being reshaped by demographic trends and evolving treatment paradigms. The growing prevalence of chronic conditions requiring long-term prostaglandin therapy, particularly in ophthalmology and cardiovascular care, sustains baseline demand while creating opportunities for differentiated products that address adherence, tolerability, or convenience. At the same time, healthcare providers and payers are increasingly focused on total cost of care, favoring therapies that reduce follow-up burden, minimize adverse effects, or simplify administration. This behavior shift encourages manufacturers to invest in real-world evidence, patient support programs, and hybrid delivery models that align with the practical realities of chronic disease management. In parallel, emerging markets are expanding their healthcare footprints, creating incremental demand for both branded and generic prostaglandin products as diagnostic capacity and treatment access improve.
Supply Chain Dynamics and Cost Structure Pressures
The cost and reliability of prostaglandin manufacturing remain central to competitive positioning. Synthesis complexity, stringent quality requirements, and the need for specialized infrastructure create barriers that favor companies with vertically integrated or strategically partnered production capabilities. Recent capacity expansion announcements highlight how leading manufacturers are responding to anticipated demand growth by investing in dedicated facilities, process optimization, and regional production footprints. These investments are not merely scale plays; they are strategic hedges against supply disruptions, regulatory delays, and margin erosion from price competition. For buyers and downstream partners, this trend signals a market where supply reliability and quality consistency will increasingly influence sourcing decisions, particularly as demand for both branded and generic formulations continues to expand across therapeutic areas.
Competitive Landscape and Leading Strategies
The competitive ecosystem for prostaglandins and related drugs blends large global pharmaceutical companies with specialized active pharmaceutical ingredient manufacturers and generic-focused producers. Each group occupies a distinct strategic position, and the interplay between them is reshaping how value is created and captured across the supply chain.
Large multinational firms maintain strong commercial presence in high-value therapeutic areas, particularly ophthalmology, where prostaglandin analogs are well established for intraocular pressure management. These companies leverage extensive commercial infrastructure, established physician relationships, and brand recognition to sustain market relevance even as generic alternatives proliferate. Their differentiation often rests on formulation optimization, delivery device innovation, and integrated patient support ecosystems. Some also extend their reach through complementary portfolio acquisitions or division-level focus, ensuring that established molecules remain commercially viable through lifecycle management and combination strategies.
Specialized API manufacturers occupy a critical position in the value chain, particularly where synthesis complexity and regulatory rigor create meaningful barriers. Companies that have invested in fully integrated production sites or possess complete prostaglandin portfolios are positioned to serve both branded and generic customers with greater supply reliability and cost predictability. Strategic capacity expansion in regions that offer manufacturing efficiency and regulatory alignment reflects a long-term bet on sustained demand growth and the need for resilient sourcing. For these players, the value proposition is built on technical capability, production scale, and the ability to support downstream formulation partners with consistent quality.
Generic manufacturers have expanded access and intensified price competition, particularly following the wave of patent expirations that opened the market to multiple alternatives. Their strategy centers on regulatory agility, cost-efficient production, and the ability to launch equivalents across multiple dosage forms and markets. Recent approvals of generic prostaglandin ophthalmic solutions illustrate how generic entrants continue to broaden therapeutic access while reinforcing the importance of manufacturing quality and supply consistency in a crowded field. These companies often compete on distribution reach, formulary positioning, and operational efficiency, making them essential participants in the market’s overall growth dynamics.
Regional and mid-sized producers, including specialized firms in Asia and Europe, add further depth to the competitive landscape by focusing on intermediates, niche formulations, and local market requirements. Their presence supports broader supply diversification and can provide downstream partners with flexible sourcing options. At the same time, the market is showing signs of gradual consolidation pressure, as scale advantages in manufacturing, regulatory compliance, and commercial reach become increasingly valuable. New entrants face a steep path unless they bring clear differentiation—whether through novel delivery technologies, unique molecular variants, or highly specialized manufacturing expertise.
For decision-makers, the key takeaway is that competitive advantage in this market is no longer defined by a single molecule or therapy area. It is increasingly determined by the ability to integrate clinical differentiation, manufacturing reliability, regulatory foresight, and commercial execution into a coherent strategy. Companies that can align these elements will be best positioned to defend share in mature segments while capturing growth in evolving applications.
Future Trends and Strategic Outlook
Over the next three to five years, the prostaglandins and related drugs market is likely to be shaped by three reinforcing trends. First, formulation and delivery innovation will continue to create commercial differentiation, especially in chronic therapy areas where adherence and treatment burden are persistent challenges. Sustained-release systems, alternative administration routes, and device-drug combinations are expected to gain further traction as clinical evidence and payer acceptance mature. These advances open opportunities for companies that can demonstrate tangible improvements in patient outcomes and total cost of care.
Second, supply chain localization and capacity investment will become more prominent as manufacturers seek to reduce dependency on concentrated production networks and mitigate regulatory or logistical disruptions. Expect continued capital deployment in dedicated facilities, process intensification, and regional manufacturing footprints designed to support both branded and generic demand. This trend will reward suppliers that can offer predictable quality, scalable capacity, and transparent compliance records.
Third, pricing and reimbursement dynamics will keep pressure on undifferentiated products while rewarding therapies with clear clinical or economic value. As health systems refine formulary strategies and emphasize cost-effectiveness, the market will increasingly separate products that compete primarily on price from those that can justify positioning through superior delivery, tolerability, or evidence-based value arguments. This environment will favor strategic portfolio management, lifecycle planning, and early engagement with payer and provider stakeholders.
Potential uncertainties include the pace of new indication approvals, the trajectory of generic penetration in key markets, and the impact of regulatory changes on manufacturing requirements and launch timelines. Macroeconomic factors affecting raw material costs, capital availability, and healthcare spending patterns may also influence investment timing and margin expectations. Companies that monitor these variables closely and maintain flexible strategic plans will be better equipped to navigate shifts in demand and competitive intensity.
Decision-Maker Action Recommendations
For manufacturers, the priority is to strengthen the foundation that supports both margin defense and growth capture. Invest in formulation and delivery capabilities that differentiate offerings beyond molecule identity, and align manufacturing strategy with long-term demand signals rather than short-term volume fluctuations. Companies that can combine supply reliability with clear clinical or practical value will have greater leverage in formulary negotiations and partnership discussions.
For investors, focus on organizations that demonstrate durable competitive advantages in API production, regulatory execution, and commercial reach within prostaglandin-related therapy areas. Evaluate exposure to segments where generic pressure is balanced by differentiated delivery, where regional demand growth is supported by healthcare expansion, and where supply chain resilience translates into more predictable revenue streams. Portfolio positioning should account for both the steady-growth core and the higher-upside potential of novel delivery or expanded indications.
For procurement and sourcing leaders, evaluate suppliers not only on unit cost but on quality consistency, capacity visibility, and regulatory standing. In a market where price competition is intense and supply interruptions can carry significant clinical and commercial consequences, multi-source strategies and supplier qualification rigor can reduce risk while supporting continuity of care. Early engagement with manufacturers that are expanding capacity or modernizing production can also improve long-term negotiating positioning.
Worldwide Carboprost Tromethamine Market
Given the pace of regulatory change, generic entry dynamics, and evolving demand patterns, access to timely and granular market intelligence is essential for informed decision-making. Detailed segmentation data, company-level tracking, and scenario-based forecasts can help organizations refine strategy, anticipate competitive moves, and identify the most relevant opportunities across regions and therapeutic applications. For those seeking a deeper, structured view of the market’s trajectory and strategic implications, the full PW Consulting research report provides the detailed breakdowns and customized analysis needed to support execution at the operational and portfolio level.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Prostaglandins and Related Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com