

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Digital Signage Design Services Market: How 7.5% CAGR Redefines Revenue Trajectories to 2032

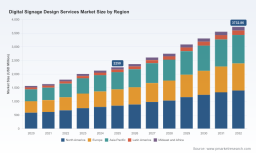
The Digital Signage Design Services Market: Navigating Growth Amid Structural Shifts
Market Overview and Core Challenges
The global digital signage design services market has demonstrated steady expansion over the past five years, growing from approximately $1.57 billion in 2020 to an estimated $2.25 billion in 2025. This trajectory reflects a compound annual growth rate of 7.5 percent, with forecasts projecting further acceleration through 2032 as organizations across sectors increasingly treat in-store and in-facility visual communication as a strategic capability rather than a decorative afterthought. The baseline revenue expansion, when mapped against evolving deployment patterns, points to a market that is maturing but far from saturated at the design and content layer. Hardware commoditization has lowered entry barriers for screen deployment, yet the value capture has progressively shifted toward creative strategy, motion design, interactive architecture, and content management integration—the very service components that determine whether a digital display resonates or simply occupies wall space.
Beneath these headline figures, three structural tensions are reshaping how service providers compete and how buyers evaluate formats. First, the industry is confronting a demographic and talent bottleneck in specialized design labor. A significant share of professional sign designers in developed markets is over fifty years old, intensifying talent scarcity and placing upward pressure on project costs and turnaround times. This demographic reality is colliding with demand for more sophisticated visual storytelling, interactive wayfinding, and multi-screen content orchestration, creating a supply-demand imbalance that favors firms with structured design operations or scalable creative outsourcing models.
Second, regulatory complexity is rising across wireless emissions, data privacy, workplace safety, and accessibility. Deployments that incorporate wireless components must navigate radio-frequency compliance, while interactive screens processing personal data face consent and minimization requirements under privacy frameworks. Workplace and public-facing displays are also subject to visibility and accessibility standards that influence both content placement and system architecture. These obligations are not merely legal checkboxes; they shape design workflows, content governance, and the commercial terms of service engagements, particularly for enterprises operating across multiple jurisdictions.
Third, the market is experiencing a functional split between commodity display installation and differentiated content design. As networks scale into hundreds or thousands of nodes, buyers increasingly expect design services to be tightly coupled with content strategy, template governance, and platform integration. Providers that only deliver visual assets without strategic planning or CMS alignment are seeing margin compression, while those that unify creative, technical, and operational capabilities are capturing more durable engagements. The challenge for decision-makers is distinguishing between providers that can produce compelling visuals and those that can sustain brand consistency, compliance, and performance across entire screen estates.
Key Drivers Shaping Market Dynamics
Technological Innovation and Content Sophistication
A defining driver of current growth is the convergence of advanced display technologies with more capable content creation and management workflows. LED formats, high-brightness outdoor panels, touch-enabled interfaces, and cloud-based CMS platforms have expanded the creative palette, but the real commercial impact comes from how design services translate these capabilities into coherent visual experiences. Providers are increasingly expected to deliver motion graphics, templated content kits, and interactive wayfinding that can be updated at scale without losing brand integrity. The ability to design once and deploy consistently across multiple locations has become a decisive competitive dimension, especially for retail chains, hospitality groups, and large corporate campuses.
Recent industry activity underscores this shift toward design-plus-management offerings. In early 2026, a major retail operator implemented a platform to control digital signage screens across more than 900 stores, integrating content design and centralized management into a single operational workflow. This kind of deployment signals that buyers are no longer purchasing isolated design projects; they are investing in repeatable content systems that reduce localized production burden while maintaining visual quality. As creative teams adopt more modular design approaches—templates, motion libraries, localized variants—the service market is being reshaped around scalability, governance, and rapid iteration rather than one-off bespoke production.
Policy and Regulatory Influence on Design Practice
Regulatory expectations are becoming embedded into design processes rather than treated as post-deployment contingencies. Wireless connectivity requirements, privacy obligations for interactive kiosks, workplace visibility standards, and accessibility guidelines all influence how content is structured, where screens are positioned, and what data flows are permissible. For international operators, the challenge is multiplied by uneven regulatory expectations across regions, which can affect template design, consent mechanisms, and compliance documentation.
This environment favors providers that build compliance into the design stage. Firms that offer ADA-aligned visual considerations, privacy-aware interactive design, and documentation supporting workplace safety visibility can reduce retrofit risk for clients and create stronger differentiation. At the same time, regulatory attention raises the importance of content governance: who can update what, how personalization is handled, and how audit trails are maintained. Design services are therefore evolving from aesthetic production toward governed visual communication systems, a transition that expands the scope of professional engagements and raises the strategic stakes for buyers selecting partners.
Demand-Side Shifts in Consumer and Enterprise Behavior
End-user expectations are a powerful force behind service demand. In retail and hospitality, customers increasingly expect dynamic, context-aware visuals that support navigation, promotions, and experience design. In corporate and education environments, digital displays serve internal communication, wayfinding, and brand reinforcement functions that must feel consistent with broader identity systems. Healthcare and transportation settings add another layer of complexity, where clarity, accessibility, and real-time information accuracy can directly affect user experience and operational outcomes.
PW Consulting Information & Electronics Research Center
These demand patterns are pushing buyers toward service models that combine strategy, visual design, and platform integration. A display without a content plan tends to underperform, while a well-orchestrated visual system can improve engagement, reduce staff workload, and support localized messaging at scale. The commercial implication is clear: design services are being evaluated less on isolated creative quality and more on their contribution to operational efficiency, brand consistency, and user experience across multiple touchpoints. This is why enterprises are gravitating toward providers with in-house creative teams, reusable content structures, and proven deployment track records.
Supply-Side and Cost Structure Considerations
On the supply side, the maturation of fabrication networks, installation capabilities, and outsourced design models is altering cost structures and delivery models. Large national networks can bundle design, production, and installation, while specialized outsourcing firms offer flexibility for concept development, LED layout planning, and compliance-oriented signage solutions. This combination expands access to design capacity but also increases the importance of vendor management, quality control, and coordination between creative and technical teams.
Labor scarcity and demographic concentration in the design workforce add another layer of cost pressure. As experienced designers retire and demand rises for more complex interactive and multi-screen work, firms that can institutionalize design assets, build reusable libraries, and integrate production with clear technical specifications are better positioned to manage cost and turnaround. For buyers, this means total project economics increasingly depend on how well design services are structured for repeatability and how effectively providers balance creative quality with operational discipline.
Worldwide Product Design Service Market
Competitive Landscape and Leading Strategies
The competitive field is populated by organizations with distinct strategic anchors. Some providers compete through end-to-end capability, pairing in-house creative teams with installation and management services to deliver branded visual experiences across retail and hospitality environments. Others emphasize software-enabled visual communication with dedicated design support, offering custom signage designs, content kits, templates, and interactive wayfinding for enterprise clients. A further cluster of players operates as national or regional production networks, specializing in custom design, fabrication, and installation for menus, directories, promotions, and dynamic displays. Alongside these, architectural and urban integration specialists focus on landmark-scale experiences, while outsourced design firms provide concept development, LED layouts, and compliance-aware signage solutions.
This diversity produces clear differentiation paths. End-to-end providers gain advantage from integrated delivery, where creative, technical, and operational responsibilities are coordinated under one relationship, reducing fragmentation for multi-site clients. Software-centric players leverage repeatable content structures and enterprise visual communication expertise, making them attractive to organizations that need governance across many screens. Production networks differentiate through scale, localized execution, and speed to install, which matters for time-sensitive rollouts or distributed locations. Architectural integrators command premium positioning by linking digital displays to physical environments and experiential design, a niche that can be highly valuable for landmark projects but less applicable to broad-based deployments.
The market is evolving through both consolidation and specialization. Larger operators are expanding service portfolios and partnership networks to cover more of the value chain, while niche specialists deepen expertise in areas such as interactive design, accessibility, or outdoor durability. At the same time, recent partnership activity shows how installation-focused players are layering in custom design integration to strengthen their offerings. For example, a major signage network partnered to support digital signage installations in hospital environments with tailored design integration, illustrating how healthcare deployments are pushing providers to combine technical reliability with context-sensitive creative work.
Strategic positioning is increasingly defined by three questions: can the provider unify design strategy with content management, can it scale creative output without losing consistency, and can it navigate regulatory and accessibility requirements as part of the design process? Firms that answer these convincingly are building moats around recurring content operations rather than one-off projects. Buyers, in turn, are rewarded for selecting partners based on delivery discipline, content governance, and the ability to adapt creative assets across locations and use cases.
Forward-Looking Trends for the Next Three to Five Years
Design-as-a-System Becomes the Standard
Over the next several years, design services are likely to be judged increasingly on systemization rather than isolated creative output. Expect broader adoption of templated motion libraries, localized content variants, and governance frameworks that let enterprises update large screen networks efficiently. This trend will create opportunities for providers that can deliver modular design assets, clear style rules, and integration with CMS platforms, while also increasing the value of partners who can train internal teams and manage content workflows over time.
Interactive and Data-Rich Experiences Will Expand, With Guardrails
Interactive wayfinding, touch-enabled directories, and personalization-enabled displays will continue to grow in high-traffic and service-oriented environments. However, privacy expectations and compliance requirements will shape how these experiences are designed, particularly where personal data is processed. The commercial opportunity lies in building interactive experiences that are compelling without over-collecting data, supported by consent design and transparent data handling. Providers that can balance engagement with compliance will be better positioned for enterprise and public-sector work.
Integration with Physical Environments and Multi-Channel Identity Will Deepen
Digital signage will increasingly be treated as part of a broader environmental and brand identity system, not a standalone medium. Architectural integration, lighting considerations, and coordination with broader communication channels will matter more as deployments seek to reinforce cohesive experiences across spaces. This creates opportunities for specialists who can bridge design, physical installation, and operational planning, but it also raises execution risk where coordination is weak. Projects that treat design, installation, and content management as separable silos are likely to face more rework, inconsistent results, and slower time to value.
Potential risks include talent constraints that slow creative delivery, regulatory changes that add compliance overhead, and price competition in commoditizing segments that pressure margins. Market participants that depend heavily on manual, bespoke workflows may find it harder to scale, while those that invest in reusable assets, structured processes, and integration-ready design will be better equipped to manage volatility.
Strategic Implications for Decision-Makers
For enterprises evaluating digital signage design services, the priority is to define the engagement around content systems rather than individual displays. This means specifying how strategy, visual design, localization, accessibility, and CMS integration will work together before scoping individual projects. Buyers should assess providers on repeatability, governance, and the ability to maintain brand consistency across multiple locations, not only on creative quality in isolation.
For investors and strategic planners, the most durable value appears to be linked to providers that combine creative capability with operational scale and integration-ready workflows. Businesses that can institutionalize design assets, support compliance-by-design practices, and deliver content across distributed networks are more likely to secure recurring engagements. Market observers should watch for consolidation among service providers, deeper partnerships between fabrication/installation networks and creative teams, and growing demand for interactive experiences that meet privacy and accessibility expectations.
For manufacturers and technology suppliers, the opportunity is to support design-led deployments with tools and specifications that make content creation, management, and compliance easier. Clearer technical standards, interoperability with common CMS platforms, and guidance on accessibility and visibility can help reduce friction between creative teams and installation operations. In a market where screens are increasingly commoditized, the differentiator is often how smoothly the surrounding design and management ecosystem functions.
Digital Signage Market
For all of these audiences, the strategic value lies in understanding where the market is heading before committing to large-scale deployments or partnership decisions. Detailed segmentation data, regional dynamics, end-user patterns, and provider-level benchmarks can sharpen planning significantly, especially when aligning investment or procurement choices with the likely trajectory of the market through the end of the decade and into the early 2030s.
For detailed analysis of this topic, please visit the official page: Digital Signage Design Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com