

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
AGV Charging System Market: Why 8.45% CAGR and Asia Pacific’s Lead Redefine Investment

The AGV Charging System Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The automated guided vehicle charging infrastructure market has transitioned from a peripheral consideration to a central component of intralogistics strategy. The sector expanded from roughly 312 million USD in 2020 to an estimated 613 million USD in 2025, with projections indicating a steady trajectory toward just over 1 billion USD by 2032. This growth reflects annualized expansion of 8.45 percent, a pace that outstrips broader industrial automation adoption and signals a structural shift in how facilities approach material handling power management.
Despite the upward trajectory, the market sits at a critical inflection point. Operators are no longer evaluating charging systems as simple utility attachments. Instead, charging infrastructure is becoming a bottleneck or an accelerant for throughput, depending on design choices. Three challenges define the current landscape.
First, downtime economics have intensified. Warehouse and manufacturing environments now operate under tighter labor constraints and higher throughput expectations, making vehicle idle time directly visible in operational cost. Charging solutions that require prolonged dock occupancy or complex manual alignment create hidden capacity losses that compound across fleets. Second, standardization gaps persist across safety, interoperability, and performance metrics. As automated vehicle deployments scale across mixed fleets and multi-vendor environments, facilities encounter integration friction when charging hardware, communication protocols, and docking behaviors are not aligned. Third, the pace of battery chemistry evolution is outstripping charger design cycles. Higher energy densities, faster charge acceptance, and shifting thermal profiles require charging systems that can adapt without forcing full vehicle redesigns.
These challenges are not isolated technical issues. They shape procurement decisions, vendor selection, and facility planning. Companies that treat charging as an afterthought increasingly discover that power delivery constraints limit automation ROI, while early actors are using charging architecture to differentiate operational flexibility.
Strategic Drivers Reshaping the Market
The expansion of AGV charging infrastructure is being pulled by a combination of technology, regulatory pressure, operational behavior, and cost dynamics. Understanding how these forces interact is essential for anticipating where value will concentrate.
Technology Innovation and Performance Thresholds
Charging technology is moving away from static, long-duration docking toward high-efficiency, flexible power delivery. Inductive and contact-based systems are both advancing, but the strategic question is increasingly about when and where energy is transferred. Opportunities for in-process or short-break charging reduce the need for large battery packs and long charging windows. Award recognition for in-process charging technology in early 2025 highlighted how the industry is rewarding solutions that minimize interruption rather than simply improving charger wattage. At the same time, high-voltage DC connectors and microgrid-enabled fast charging concepts have emerged to support next-generation vehicles with reduced downtime.
Battery-side developments reinforce this shift. Lithium-ion adoption continues to benefit from cost and performance improvements, and charging architectures are being optimized for higher charge rates, including transitions from conventional 1C charging toward 3C surge profiles in suitable applications. This changes the design logic for both stationary and onboard charging units, placing greater importance on thermal management, power conversion efficiency, and control software.
Policy Pressure and Compliance-Driven Adoption
Regulatory expectations are reshaping industrial facility planning. European sustainability targets require industrial operations to move toward carbon neutrality by 2050, with a 55 percent emission reduction milestone by 2030. These targets accelerate interest in efficient charging approaches that reduce energy waste and support broader decarbonization strategies. Wireless and opportunity charging solutions gain relevance here because they can lower mechanical wear, simplify integration into continuous workflows, and support more consistent energy use patterns when deployed thoughtfully.
Safety and interoperability standards are equally influential. Conformance to AGV safety requirements drives demand for charging systems that are not only electrically robust but also integrated into the vehicle’s operational safety logic. In warehouse automation, this means charging infrastructure must align with vehicle behavior, zone design, and risk controls rather than functioning as a standalone utility.
Demand-Side Changes in Logistics and Manufacturing
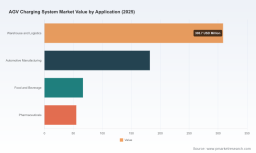
Operational expectations are changing on the demand side. Facilities are deploying larger fleets of automated vehicles and expecting them to support continuous or near-continuous workflows. This is especially visible in warehousing and logistics, where throughput pressure has made charging strategy part of overall slotting, routing, and shift design. Automotive manufacturing and adjacent industrial sectors are also pushing for more flexible power solutions that can accommodate high-utilization vehicles without expanding floor congestion.
Behaviorally, operators are moving from a “charge when parked” mindset to a “charge where and when it fits the process” mindset. That shift increases interest in solutions that support fast top-ups, autonomous docking, and reduced manual intervention. The commercial implication is that charging systems are being evaluated on process compatibility as much as on electrical performance.
Supply Chain and Cost Structure Evolution
Cost dynamics are improving the feasibility of advanced charging solutions, but they are also reshaping supplier competition. Better lithium-ion economics reduce the penalty of higher-performance batteries, which in turn enables more aggressive charging strategies. However, total cost of ownership calculations now include power conversion efficiency, maintenance exposure, and integration labor. Suppliers that can reduce mechanical wear, simplify installation, or support modular scaling gain an advantage because facilities are looking to avoid hidden operational costs.
Supply chain maturity is also affecting time-to-deployment. As charging modules, connectors, and control systems become more standardized in certain segments, integration complexity can decline. Yet in custom intralogistics environments, bespoke engineering remains a significant value driver, especially where high-current delivery, custom docking, or mixed-vehicle environments are involved.
Competitive Dynamics and Differentiated Playbooks
The market features a diverse set of participants spanning specialist charging providers, industrial power companies, and broader automation integrators. Rather than competing on a single dimension, leading players are defining advantage through technology focus, deployment scale, integration depth, and regional footprint.
Wireless inductive specialists have positioned themselves around continuous operation and reduced mechanical wear. Wiferion, for example, has built recognition around inductive systems designed for opportunity charging, with recent industry acknowledgment for in-process charging technology. The strategic appeal is clear: if vehicles can charge without precise mechanical engagement or extended stationary periods, facilities can reduce downtime and maintenance overhead. VAHLE takes a complementary angle with conductive contacts and shuttle charging systems, emphasizing high-current fast charging and custom integration in intralogistics. This reflects a different bet: that robust contact-based infrastructure remains essential where high power, predictability, and integration with existing floor systems matter most.
Other participants compete on scale and ecosystem breadth. Delta Electronics has emphasized a large deployed base across industrial vehicles and AGVs, presenting its charging portfolio as part of a broader mobility and automation offering. This scale narrative matters because it suggests maturity in manufacturing, support, and multi-vehicle compatibility. Micropower Group focuses on high-frequency battery chargers for AGV applications, including onboard and stationary units with support for lithium-ion and opportunity charging, targeting flexibility on both the hardware and application side. EnerSys leans into integrated battery and charging solutions, framing power delivery as part of reliable industrial automation rather than as a standalone hardware category.
In Asia, several firms emphasize precision docking, non-contact power transfer, and system-level integration. Daihen and B&PLUS illustrate the focus on docking and non-contact power supply mechanisms, while Daifuku positions charging within broader material handling automation solutions. Guangdong Titans Intelligent Power highlights autonomous docking and multi-function charging for automated material handling, reflecting an emphasis on customized deployment and functional integration. Vicor Power enters from a different angle with high-efficiency power conversion and charging modules tailored for AGV battery systems, showing how component-level performance can matter as a differentiated layer within broader assemblies.
Recent events illustrate how these positions are being reinforced. Delta Electronics showcased its battery charging portfolio at LogiMAT in early 2026, underscoring the reach of its deployed solutions. Schaltbau advanced high-voltage DC connectors and microgrid concepts for faster charging of next-generation AGVs, pointing toward infrastructure-level enablement beyond individual vehicle charging units. These moves suggest a market that is not only refining vehicle-side charging but also rethinking how power is delivered, distributed, and integrated across facilities.
Looking ahead, the competitive landscape is likely to evolve through both convergence and specialization. Integration-heavy players may absorb more charging functionality into automation platforms, while specialist suppliers may deepen advantage in wireless efficiency, high-current contact systems, or docking precision. New entrants can still compete by targeting specific pain points such as autonomous docking reliability, modular scalability, or plug-and-play interoperability. The most important strategic question is whether a supplier competes as a component vendor, a system enabler, or a process-integrated solution provider.
PW Consulting Automotive & Machinery Research Center
Outlook: Key Trends Over the Next Three to Five Years
The next phase of market development will likely be defined by how charging systems fit into broader operational design rather than by simple capacity increases. Several trends stand out.
One major direction is the rise of charging as an integral workflow element. Facilities will increasingly design routes, staging areas, and vehicle Utilization patterns around short charging windows and opportunity charging points. This creates demand for systems that support autonomous alignment, fast energy transfer, and dependable docking behavior. The commercial opportunity lies in solutions that reduce the operational friction of charging rather than only improving raw power output.
Worldwide Mobile Charging Robot for Electric Vehicle Market
A second trend is the continued blending of contact and wireless approaches. Different applications will favor different methods, but many environments will need hybrid strategies. High-utilization vehicles may benefit from inductive top-ups in flow paths, while fixed docking points may use contact systems for rapid high-power replenishment. Suppliers that can offer interoperable architectures or clearly defined application-specific playbooks will be better positioned than those pushing a single technology in all contexts.
A third trend is infrastructure-level thinking. As charging demand grows, facilities will pay more attention to power distribution, microgrid integration, and centralized energy management. This shifts some value from pure vehicle-side hardware to broader electrical architecture and control software. Companies that can connect charging performance with facility-level energy planning will have an opening to become strategic partners rather than equipment suppliers.
These trends are not without risk. Standardization may lag behind deployment, creating fragmentation and integration cost. Overly aggressive charge-rate expectations could introduce thermal or battery-life constraints if not matched with robust system design. Demand may also vary by region and sector, making broad generalizations risky. The opportunity is strongest where charging strategy is aligned with actual process requirements, fleet composition, and total cost of ownership rather than treated as a one-size-fits-all upgrade.
Strategic Actions for Decision-Makers
For AGV manufacturers and automation integrators, the priority is to treat charging as part of the vehicle and workflow architecture, not as a bolt-on accessory. Design choices around battery size, docking tolerance, charge acceptance, and safety integration will influence customer throughput and maintenance costs. Suppliers that can demonstrate measurable reductions in downtime, simpler installation, or cleaner integration with mixed fleets will differentiate more effectively than those competing only on hardware specifications.
Worldwide Automatic Guided Vehicle Sensing System Market
For investors and corporate strategy teams, the most valuable exposure may come from companies that combine technical differentiation with deployment scalability. Wireless efficiency, high-current contact reliability, power conversion performance, and integration-ready software are all potential value drivers, but the key is whether those capabilities translate into repeatable deployments and lower integration risk. Monitoring how suppliers expand from component or system roles into broader facility-level solutions can provide early signals of competitive momentum.
For procurement and operations leaders, charging decisions should be evaluated against process impact. The right solution depends on vehicle utilization patterns, shift structure, floor layout, and tolerance for manual intervention. Opportunities to reduce idle time, simplify docking, or support opportunity charging in active flow paths can create operational benefits that outweigh raw hardware comparisons. Detailed segment-level data, application-specific benchmarks, and vendor-by-vendor capability mapping can materially improve procurement decisions and reduce implementation risk. For teams planning multi-phase automation rollouts, deeper research into charging architecture options, regional supplier dynamics, and total cost of ownership scenarios can help convert a technical choice into a strategic advantage.
For detailed analysis of this topic, please visit the official page: AGV Charging System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com