

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
5-Bromo-2,4-dichloropyrimidine Market: Why 6.31% CAGR Changes Asia Pacific Winners

Strategic Trends and Commercial Opportunities in the Global 5-Bromo-2,4-dichloropyrimidine Market
Market Overview and Core Challenges
The global market for 5-Bromo-2,4-dichloropyrimidine has entered a phase of steady structural expansion, driven by its entrenched role as a critical heterocyclic building block in pharmaceutical and fine chemical value chains. Valued at approximately USD 142.5 million in 2025, the market has demonstrated consistent compounding growth since 2020, when it stood at USD 102.34 million. Projections indicate that this upward trajectory will persist through the end of the decade, with the market expected to surpass USD 200 million by 2031 and approach USD 218.69 million by 2032. This expansion translates to a compound annual growth rate of 6.31 percent across the 2026 to 2032 forecast window.
Such growth is neither accidental nor isolated. It reflects a broader industry pattern wherein specialized halogenated pyrimidine intermediates have become indispensable to modern drug discovery and process chemistry. The compound serves as a versatile electrophilic scaffold, enabling nucleophilic substitution and cross-coupling reactions that underpin the synthesis of kinase inhibitors, immunomodulators, and other targeted therapeutics. Parallel to pharmaceutical demand, academic and industrial laboratory research continues to provide a stable baseline of consumption, while niche applications in agrochemical synthesis add incremental volume.
Beneath the headline growth figures, however, the market faces structural friction that will define profitability and supply reliability over the next several years. The first challenge lies in raw material volatility and its downstream impact on pricing discipline. The synthesis of related chlorinated pyrimidine derivatives depends heavily on chlorination agents and precursor heterocycles that have experienced quarterly price swings exceeding 40 percent since 2022. These fluctuations force manufacturers into unpredictable cost structures, compress margins on standardized grades, and complicate long-term contract negotiations with downstream formulators.
The second challenge centers on regulatory classification and logistics complexity. The material is classified for transport as UN3261, a corrosive solid, acidic, organic, n.o.s., falling under Hazard Class 8, Packing Group III under DOT, IATA, and IMDG frameworks. This designation introduces mandatory compliance layers for packaging, labeling, carrier qualification, and cross-border documentation. For manufacturers and distributors operating across multiple jurisdictions, the cumulative administrative and operational burden restricts agility in scaling shipment volumes and increases the cost of market entry for smaller regional players.
A third pressure point is the clustering of commercial activity around a concentrated supplier base. The top three firms account for roughly 42 percent of market share, while the top five capture nearly 59 percent. Such concentration creates an environment where pricing transparency is limited, alternative sourcing paths are narrow, and supply disruptions at a single facility can ripple through downstream pipelines. At the same time, this structure incentivizes incumbents to protect margin by differentiating on purity consistency, documentation quality, and technical support, raising the barrier for new entrants who lack established quality systems or regulatory familiarity.
For business leaders, the implication is clear: the market is growing reliably, but growth alone does not guarantee operational stability or margin preservation. Firms that navigate raw material exposure, transport compliance, and supplier concentration with disciplined sourcing strategies and technical differentiation will be better positioned to convert volume expansion into sustainable commercial advantage.
Key Drivers of Market Change
Several interlocking forces are reshaping how 5-Bromo-2,4-dichloropyrimidine is produced, priced, and deployed across end-use sectors. Understanding these drivers is essential for anticipating where capacity, pricing power, and partnership opportunities will emerge.
Technological Innovation and Process Optimization
Advances in synthetic methodology and scale-up engineering are gradually reshaping the cost and quality profile of the compound. Manufacturers that have invested in continuous or semi-continuous chlorination and bromination pathways are achieving tighter control over impurity profiles, which directly supports the production of higher-purity grades demanded by pharmaceutical clients. At the same time, process intensification efforts are reducing batch-to-batch variability and improving yield reproducibility, which matters greatly for customers running multi-step syntheses where intermediate purity can influence downstream reaction efficiency.
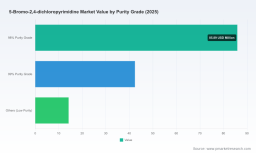
Recent commercial listings and supplier updates illustrate this trajectory. In late 2025, multiple suppliers maintained or expanded offerings emphasizing 99 percent purity thresholds, while others continued to supply the 98 percent grade that remains a workhorse standard for many intermediate applications. The coexistence of these purity tiers reflects a market that is simultaneously optimizing for cost-effective scale and for the stricter analytical specifications required by regulated drug development programs. Suppliers that can reliably bridge both segments, without compromising documentation or lot consistency, are gaining preferential positioning in procurementreviews.
Policy and Regulatory Evolution
The regulatory backdrop is steadily maturing, albeit without introducing abrupt restrictions that would fundamentally constrain trade. In the United States, the compound is listed under the TSCA inventory, providing a recognized pathway for commercial handling and import. Within the European framework, the substance does not currently appear under specific Annex XIV authorization requirements or Annex XVII restrictions under REACH, which reduces immediate compliance friction for EU-facing supply chains. These conditions create a permissive but monitored environment where established manufacturers can operate with predictable regulatory overhead, provided they maintain up-to-date safety documentation and transport classification compliance.
This environment is not static. Updated Safety Data Sheets, such as those refreshed in late 2025 by major distributors, reaffirm the corrosive solid classification and emphasize ongoing commercial availability under hazard-aligned logistics protocols. The practical effect is a market where regulatory clarity supports continuity, but where any future tightening of classification, packaging mandates, or import documentation could quickly alter cost structures. Firms that proactively maintain compliance infrastructure and monitor jurisdictional updates will be better insulated against sudden operational shifts.
Demand-Side Shifts in Pharmaceutical and Research Workflows
Demand dynamics are being reshaped by the broader architecture of modern drug development and fine chemical synthesis. The compound's role as a trisubstituted pyrimidine precursor positions it squarely within the workflow of kinase inhibitor programs and other targeted therapy pipelines, where modular building blocks are repeatedly iterated across lead optimization and process development phases. As these pipelines expand and as development timelines compress, the demand for intermediates that offer predictable reactivity, well-characterized impurity profiles, and reliable lot availability increases correspondingly.
PW Consulting
Beyond drug development, the laboratory research segment continues to serve as a stable demand anchor. Academic groups, contract research organizations, and internal R&D teams rely on the intermediate for exploratory synthesis, method development, and small-scale feasibility studies. While this segment rarely drives the largest volume swings, it contributes to baseline consumption and supports the supply ecosystem that larger commercial buyers depend upon. A third, smaller demand stream emerges from agrochemical synthesis, where the same heterocyclic scaffold supports the construction of active ingredients and formulation intermediates. Though modest in relative size, this segment adds diversification to the demand base and can become more significant if crop protection portfolios expand their use of halogenated pyrimidine chemistry.
2-Amino-5-bromothiazole Monohydrobromide Market
Supply Chain and Cost Structure Dynamics
Cost structures remain highly sensitive to upstream chemical volatility. The dependence on pyrimidine derivatives and chlorination agents means that price swings in basic halogenation inputs propagate rapidly through the value chain. Since 2022, quarterly fluctuations in these inputs have exceeded 40 percent at times, creating an environment where static pricing models quickly become unsustainable. Suppliers have responded by adopting more flexible contract structures, hedging strategies where feasible, and closer integration with precursor suppliers to improve visibility into input availability and cost trends.
Logistics and handling costs form another layer of the supply chain equation. The corrosive solid classification requires specific packaging, carrier training, and documentation workflows that add cost at every transfer point. Companies that standardize these processes, invest in compliant packaging inventories, and maintain relationships with trained logistics partners can reduce per-unit handling premiums. Conversely, organizations that treat transport compliance as an afterthought often encounter delays, rework, and unexpected surcharges that erode margin.
Taken together, these drivers point to a market where competitive advantage is increasingly derived from process reliability, documentation rigor, and supply chain agility rather than from volume alone. Buyers are prioritizing partners who can demonstrate consistent purity, transparent lot records, and the operational capacity to manage regulated transport without disruption. Suppliers that align their capabilities with these expectations are capturing stronger commercial positioning even in a price-sensitive environment.
Competitive Landscape and Leading Strategies
The competitive environment for 5-Bromo-2,4-dichloropyrimidine is characterized by a mix of established fine chemical manufacturers, regional producers with integrated synthesis capabilities, and global scientific suppliers that bridge laboratory-scale and commercial-scale demand. Rather than competing solely on price, leading players differentiate through purity consistency, application-specific documentation, scale flexibility, and technical support that reduces friction for downstream users.
In India, several manufacturers have built commercial positions around the production of the intermediate for pharmaceutical applications. Jay Finechem, headquartered in Gujarat, is known for supplying the compound in powder form with a 98 percent assay, supporting drug development programs for medicines such as Ribociclib, Trilaciclib, and Palbociclib. Simson Pharma and Vandana Chem similarly serve domestic and international clients, emphasizing competitive quality and export-oriented logistics. These Indian-based producers benefit from established fine chemical manufacturing infrastructure, proximity to key precursor supply networks, and growing experience in serving regulated pharmaceutical supply chains. Their strategic positioning tends to center on reliable batch output, assay consistency, and the ability to support both intermediate production and downstream formulator requirements.
Across China, the landscape features manufacturers and suppliers that span research-grade and larger-scale commercial offerings. COLORKEM, based in Zhejiang, offers the compound as a pale yellow liquid pharmaceutical intermediate with content at or above 99 percent, packaged in standard bag sizes for chemical and pharmaceutical applications. BLD Pharmatech, in Shanghai, supplies the material primarily for research and development use in pharmaceutical and fine chemical synthesis, catering to teams that require well-characterized lots for exploratory and scale-up studies. AstaTech (Chengdu) Biopharmaceutical Corp. positions its offering around intermediate applications in nucleophilic substitution and cross-coupling reactions, emphasizing compatibility with trisubstituted pyrimidine synthesis workflows. In late 2025, additional commercial activity appeared from regional producers such as Henan Aochuang Chemical, which indicated supply capability at the ton scale for 98 percent purity material, and Shaanxi Dideu New Materials, which listed 99.0 percent purity material at industrial scale. These listings reflect a market in which Chinese suppliers are actively expanding both purity options and volume capacity to capture demand from cost-conscious development programs and production-scale buyers.
Global scientific distributors add a distinct layer to the competitive field. TCI America, operating under Tokyo Chemical Industry, supplies high-purity material at 97 percent or higher for laboratory and synthesis use across pharmaceutical and agrochemical applications. Thermo Fisher Scientific, including its Alfa Aesar portfolio, provides 98 percent material for chemical synthesis and intermediate applications, supported by broad distribution infrastructure and standardized quality documentation. Sigma-Aldrich, under Merck KGaA, offers 97 percent material as a halogenated pyrimidine intermediate for organic synthesis in pharmaceutical and agrochemical sectors. These firms leverage global reach, established procurement pathways, and strong technical support networks to serve customers who value availability, documentation completeness, and multi-region logistics more than localized price advantages.
Recent operational developments reinforce how these players are adapting. Updated safety documentation from Thermo Fisher Scientific in September 2025 confirmed the transport classification and reaffirmed ongoing commercial availability, signaling that major distributors continue to prioritize compliance clarity alongside supply continuity. Meanwhile, new listings and scale indications from regional producers in 2025 point to growing capacity and an intensifying focus on purity tiers that match specific buyer requirements. This dynamic suggests a market that is gradually bifurcating: one track emphasizing high-purity, well-documented material for regulated pharmaceutical workflows, and another emphasizing cost-competitive, scale-oriented supply for research and intermediate production where specifications are slightly less restrictive.
Strategically, the market concentration pattern reinforces the importance of differentiation. With the top three and top five suppliers holding substantial share, incumbents protect their positions by reducing buyer risk through lot traceability, analytical support, and responsive logistics. New entrants face a challenging path unless they bring clear advantages in purity control, regional proximity, or specialized application support. The most probable evolution in the near term is a combination of consolidation among smaller distributors seeking scale efficiencies and selective fragmentation as regional manufacturers expand capacity to capture demand from specific therapeutic or geographic segments.
For decision-makers evaluating supplier relationships, the practical takeaway is that competitive strength in this market is not measured by catalog breadth alone. It is reflected in the ability to deliver consistent assay results, maintain audit-ready documentation, manage regulated transport without disruption, and support the specific synthetic workflows of downstream users. Suppliers that build these capabilities systematically tend to secure longer-term procurement relationships and greater resilience against pricing pressure.
Future Trends and Commercial Implications
Looking ahead to the next three to five years, the market for 5-Bromo-2,4-dichloropyrimidine is likely to be shaped by three interrelated trends, each carrying distinct commercial implications.
The first trend is a continued drift toward higher and more consistently documented purity tiers for pharmaceutical-facing supply. As drug development programs increasingly rely on well-characterized intermediates to reduce downstream variability and support regulatory submissions, buyers will place greater weight on lot-to-lot reproducibility, analytical certificates, and traceability. Suppliers that standardize high-purity production and can provide robust documentation packages will find expanding opportunities to serve regulated pipelines and command pricing that reflects reduced technical risk for their customers. A related opportunity lies in offering tiered product configurations, allowing buyers to select between 99 percent grades for sensitive synthetic steps and 98 percent grades for cost-sensitive stages without sacrificing quality assurance.
The second trend is the gradual regional rebalancing of supply and demand. Demand from pharmaceutical development and fine chemical synthesis is not uniformly distributed, and procurement teams are increasingly sensitive to lead times, transport compliance costs, and currency exposure. This creates room for regional manufacturers that can offer shorter logistics paths, localized technical support, and flexible batch sizes. At the same time, global scientific distributors will continue to play a crucial role for buyers who require multi-region availability and standardized quality systems. The commercial opportunity here lies in building supply networks that combine regional responsiveness with globally recognized documentation standards, rather than treating proximity and scale as mutually exclusive options.
The third trend involves ongoing sensitivity to input cost volatility and regulatory adaptation. Because precursor chlorination agents and pyrimidine derivatives remain prone to significant quarterly price movement, suppliers and buyers alike will need to adopt more dynamic contracting approaches and maintain deeper visibility into upstream conditions. On the regulatory side, while the current classification and inventory status support stable operations, any future adjustments to hazard packaging requirements, import documentation, or jurisdictional listings could shift cost structures quickly. Firms that invest in compliance readiness, packaging standardization, and proactive monitoring of regulatory updates will be better prepared to absorb such changes without losing service reliability.
The principal risks to watch include sustained input price swings that erode margin predictability, supply disruptions concentrated among a limited number of high-share producers, and potential regulatory changes that increase handling or documentation burdens. These risks do not undermine the market's growth trajectory, but they do raise the importance of portfolio diversification, supplier redundancy, and technical due diligence in procurement decisions.
Actionable Guidance for Decision-Makers
For manufacturers and suppliers, the priority is to convert process reliability into differentiated commercial value. Investing in consistent purity output, robust analytical documentation, and compliant packaging inventories can reduce buyer-perceived risk and support longer-term contracts. Developing flexibility across purity tiers and scale options allows suppliers to serve both research-stage and production-stage customers without compromising quality standards. Where feasible, strengthening visibility into precursor availability and cost trends will improve pricing resilience amid volatile input markets.
Worldwide Bromoacetic Acid Market
For investors evaluating exposure to this segment, the emphasis should be on operational maturity and supply chain positioning rather than on volume growth alone. Suppliers with established quality systems, audit-ready documentation, and diversified customer bases are better equipped to maintain margin stability through input volatility and regulatory adjustments. Capacity expansion that is paired with documentation capability and logistics compliance offers a more durable value proposition than capacity growth in isolation.
For procurement teams and sourcing managers, the most effective approach is to evaluate suppliers on a combination of purity consistency, documentation completeness, transport compliance readiness, and technical support quality. Diversifying across regional and global partners can reduce exposure to single-source disruption while maintaining access to different scale and purity configurations. Establishing clear specification requirements, lot traceability expectations, and compliance documentation standards at the outset of a procurement relationship will reduce friction during scale-up and limit the risk of unexpected handling or logistics costs.
Detailed segmentation data, purity-grade dynamics, regional volume patterns, and company-level strategic profiles can help translate these observations into precise sourcing, investment, and capacity decisions. Readers seeking a deeper breakdown of market splits, competitive benchmarking, and forward-looking scenario analysis are encouraged to review the full study, which provides the granular data and structured frameworks needed to support enterprise-level planning.
For detailed analysis of this topic, please visit the official page: Worldwide 5-Bromo-2,4-dichloropyrimidine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com