

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Air Intake Resonator Market: What the 6.85% CAGR Reveals About 2032 Growth

Strategic Outlook: Navigating the Air Intake Resonator Market (2026–2032)
Market Overview and Core Challenges
The global air intake resonator market is characterized by steady, predictable growth driven by the broader automotive production landscape. Between 2020 and 2025, the market expanded from approximately $612.45 million to $812.4 million, reflecting a compound annual growth rate (CAGR) of 6.85% through the forecast period ending in 2032. This trajectory suggests a mature but evolving sector where volume growth is increasingly tied to technological refinement rather than raw unit production alone. By 2032, the market is projected to reach $1,291.2 million, indicating significant headroom for value creation despite the commoditization risks inherent in component manufacturing.
Regionally, the market weight is shifting. While North America and Europe remain substantial contributors with established OEM relationships, the Asia Pacific region currently represents the largest revenue share. This distribution highlights the dependency on manufacturing hubs in China, India, and Southeast Asia, where vehicle production volumes continue to outpace Western markets. However, reliance on these regions introduces exposure to supply chain volatility and varying regulatory timelines.
Three critical challenges define the current inflection point for industry stakeholders. First, the transition toward electrification complicates demand forecasting. While internal combustion engine (ICE) vehicles continue to dominate the global fleet, the long-term shift toward EVs threatens the traditional volume base for intake resonators, which are primarily designed for air-cooled combustion processes. Manufacturers must decide whether to pivot designs for hybrid applications or consolidate around ICE production in emerging markets where EV adoption lags.
PW Consulting Automotive & Machinery Research Center
Second, regulatory pressure is intensifying. Emission standards, particularly the EU Euro 7 framework, are expected to drive investment in advanced air intake systems that optimize combustion efficiency and reduce NOx and particulate emissions. Compliance is no longer optional but requires material and design changes that impact cost structures. Third, cost pressures from raw materials are reshaping bidding dynamics. The industry is seeing a divergence in material selection, where cost-effective polymers compete with high-performance engineering plastics, forcing suppliers to balance performance requirements against margin erosion.
Key Drivers of Market Dynamics
Several interconnected factors are propelling the market forward, creating both opportunities and constraints for participants. Understanding these drivers is essential for aligning product development and supply chain strategies with future demand.
Technological Innovation and Material Science
Material selection has become a primary battleground for performance differentiation. The industry is witnessing a dual-track development where glass-fiber-reinforced polyamides (PA6/PA66) continue to dominate premium turbocharged intake applications due to superior thermal resistance up to 220°C. These materials are critical for modern engines that operate at higher temperatures and pressures to meet efficiency targets. Conversely, polypropylene (PP) used in intake components offers a 15-20% cost reduction versus polyamide (PA) but is limited to lower temperature applications around 130-140°C. This cost-performance trade-off creates a segmentation opportunity where suppliers can target budget-conscious OEMs with PP solutions while retaining high-margin contracts with premium brands requiring PA-grade durability.
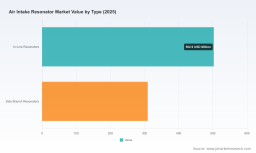
Innovation is not limited to materials. In-line resonators are capturing a larger share of the type segmentation compared to side branch resonators, reflecting a design preference for compact integration that minimizes engine bay footprint without sacrificing noise reduction. This shift aligns with the industry trend toward downsized, high-efficiency engines where packaging space is at a premium.
Policy and Regulatory Environment
Regulatory frameworks are acting as a forced catalyst for product upgrades. The anticipated implementation of EU Euro 7 emission standards is expected to drive investment in advanced air intake systems optimizing combustion efficiency and reducing NOx and particulate emissions. Unlike previous standards that focused heavily on tailpipe outputs, Euro 7 places greater emphasis on real-world driving emissions and durability, requiring intake systems that maintain performance consistency over the vehicle's lifespan. This regulatory shift benefits suppliers capable of engineering resonators that manage airflow turbulence and temperature more precisely, as inconsistent intake flow can lead to inefficient combustion and higher emissions.
In parallel, noise pollution regulations in urban centers are reinforcing the acoustic function of resonators. As cities impose stricter noise limits, OEMs are increasingly specifying resonators that contribute to overall vehicle sound signature management, extending the component's value proposition beyond mere engine protection.
Demand-Side Shifts and Consumer Behavior
Consumer preferences are bifurcating the market. On one end, the mainstream passenger car segment continues to drive the majority of volume, with buyers increasingly sensitive to fuel efficiency and engine smoothness. Resonators that contribute to quieter, more refined engine operation are becoming standard expectations rather than optional upgrades. On the other end, the performance aftermarket segment is showing renewed vigor. High-performance enthusiasts and modifications for trucks and SUVs are creating niche demand for resonator designs that balance airflow enhancement with sound tuning.
Recent product launches illustrate this demand divergence. In April 2025, K&N Engineering introduced NextGen Air Intake Systems for trucks and SUVs delivering horsepower gains, signaling sustained interest in performance-oriented intake upgrades. Similarly, in May 2025, Dinan released the LCI X3 M40i / X4 M40i Cold Air Intake with performance enhancements, targeting specific luxury performance models. These releases demonstrate that even as OEM volumes face long-term electrification risks, the aftermarket channel remains a viable growth vector for companies with strong brand recognition and engineering credibility.
Supply Chain and Cost Structure Evolution
Supply chain resilience has moved from a back-office concern to a strategic priority. The concentration of manufacturing in Asia Pacific means that geopolitical tensions, logistics disruptions, or regional policy changes can ripple through global availability. Suppliers are responding by diversifying supplier bases and exploring near-shoring options for critical components. Additionally, the cost structure is heavily influenced by polymer pricing volatility. The ability to switch between PP and PA based on application requirements provides a lever for cost management, but this requires flexible production lines and precise engineering validation to ensure material substitution does not compromise performance.
Cost pressures are also reshaping the competitive landscape. Companies that can achieve scale efficiencies while maintaining material flexibility are better positioned to protect margins during periods of raw material inflation. The market concentration, with the top three players holding a combined share of 38.5% and the top five at 52.7%, indicates that scale matters, but niche specialization can still command premium pricing.
Competitive Landscape and Leading Strategies
The market is defined by a mix of global Tier-1 suppliers, specialized automotive component manufacturers, and aftermarket performance leaders. Each segment employs distinct strategies to capture value, reflecting different risk tolerances and customer relationships.
Strategic Positioning of Key Players
MANN+HUMMEL stands out as a global leader in filtration solutions, designing and manufacturing air intake systems and resonators integrated into air cleaner housings for passenger cars, heavy-duty, and industrial applications. Their strategy centers on noise reduction and performance optimization, leveraging a broad portfolio that spans multiple vehicle segments. By integrating resonators directly into air cleaner housings, MANN+HUMMEL reduces separate component complexity for OEMs, offering a value proposition based on systems integration and reliability.
Röchling Automotive specializes in air intake systems with high-frequency resonators for optimized sound and performance. Their focus on integrating resonators, ducts, and filtration components for OEM automotive propulsion systems positions them as a solutions provider rather than a commodity parts supplier. This integration capability allows Röchling to capture higher margins by solving multi-functional requirements such as acoustic tuning, airflow management, and filtration in a unified design.
Toyoda Gosei manufactures air cleaner hoses with resonators and noise-absorbing air intake ducts to reduce engine intake noise while providing clean air for engine efficiency. Their approach emphasizes noise absorption and efficiency, catering to OEMs that prioritize refined engine characteristics. As a Japanese manufacturer, Toyoda Gosei benefits from strong relationships with domestic automakers and suppliers, though they face competition from European and North American players expanding into Asian markets.
Worldwide Automotive Air Filter Housing Market
Magna International provides comprehensive powertrain and vehicle engineering including air intake systems and components as part of broader automotive solutions for OEMs. Magna's scale and engineering breadth allow them to offer air intake resonators as part of a larger package, which can be attractive to OEMs seeking single-source accountability for complex vehicle subsystems. This holistic approach differentiates Magna from component-only suppliers.
Automotive Air Intake Manifold Market
K&N Engineering occupies a unique position as an aftermarket performance leader, offering cold air intake systems, some incorporating or compatible with resonator designs for enhanced airflow and sound. Their strength lies in brand loyalty among performance enthusiasts and a direct-to-consumer channel that bypasses traditional OEM supply chains. K&N's ability to deliver horsepower gains and sound enhancement makes them a benchmark for aftermarket quality, creating a halo effect that can influence OEM specifications indirectly.
Market Evolution and Competitive Trends
The competitive landscape is evolving through a combination of consolidation among large players and differentiation among specialists. The market concentration indicates that scale advantages are significant, encouraging mergers and partnerships that expand geographic reach and product portfolios. However, the presence of strong niche players like K&N Engineering suggests that specialization in performance or specific vehicle segments remains viable.
New entrants face high barriers due to the need for engineering validation, OEM qualification processes, and established supply chain relationships. However, companies that can innovate in material science or acoustic engineering may find opportunities to disrupt traditional supplier relationships, particularly if they can demonstrate clear advantages in cost or performance. The recent product activity from Dinan and K&N highlights that the aftermarket remains a dynamic space where innovation cycles are faster than in the OEM channel, providing a testing ground for new designs and materials.
Strategic differentiation is increasingly tied to material flexibility and regulatory compliance capabilities. Suppliers that can seamlessly switch between PP and PA grades based on application requirements, while meeting Euro 7 and noise standards, are better equipped to win contracts across diverse OEM segments. The ability to offer integrated solutions that combine resonators with filtration and ducting is also becoming a key differentiator, as OEMs seek to reduce assembly complexity and weight.
Future Trends and Commercial Opportunities
Looking toward the 2026–2032 horizon, several trends will shape the market's trajectory and create distinct commercial opportunities for prepared stakeholders.
Trend 1: Hybrids as a Bridge for Resonator Demand
The transition to full electrification will not be uniform across all markets. Hybrid vehicles, which retain ICE components alongside electric drivetrains, will sustain demand for air intake resonators in regions where full EV infrastructure is slow to develop. This creates a medium-term opportunity for suppliers to design resonators optimized for hybrid-specific operating conditions, such as frequent start-stop cycles and varied load demands. Manufacturers that can demonstrate improved durability and efficiency for hybrid applications will capture value from OEMs extending the life of ICE technology in hybrid platforms.
Trend 2: Material Innovation Driving Margin Recovery
As cost pressures persist, material innovation will be a critical lever for margin recovery. The divergence between PP and PA applications suggests that suppliers with expertise in material optimization can offer tiered solutions that match cost to performance requirements. Opportunities exist for companies that can develop novel composites or recycling pathways that reduce material costs while maintaining thermal and acoustic performance. Additionally, the push for sustainability may drive demand for resonators made from recycled polymers or bio-based materials, particularly in European markets where OEMs face pressure to reduce the carbon footprint of their supply chains.
Trend 3: Acoustic Performance as a Differentiator
Noise regulations and consumer expectations for refined vehicle acoustics will elevate the resonator's role beyond functional airflow management. Suppliers that can deliver precise acoustic tuning, reducing specific frequency bands associated with engine noise while maintaining airflow efficiency, will gain a competitive edge. This trend opens opportunities for collaboration with acoustic engineering firms or the development of proprietary tuning algorithms that optimize resonator design for specific engine families. The integration of resonators with active noise cancellation systems or variable geometry designs could further enhance value propositions for premium vehicle segments.
Risk Factors and Uncertainties
Despite these opportunities, risks remain. The pace of EV adoption could accelerate faster than anticipated in key markets, compressing the timeline for ICE component demand. Raw material costs could spike due to supply constraints or geopolitical events, squeezing margins for suppliers unable to pass costs through. Regulatory changes could also introduce new compliance requirements that increase engineering costs or delay product launches. Finally, the aftermarket segment, while dynamic, is subject to cyclical consumer spending and may not fully offset declines in OEM volumes if electrification progresses rapidly.
Strategic Actions for Decision Makers
Navigating the air intake resonator market requires aligned strategies across manufacturing, investment, and procurement functions. The following recommendations address the core priorities for each stakeholder group.
For Manufacturers and Suppliers
- Invest in material flexibility and engineering validation. Develop production capabilities that can efficiently switch between PP and PA grades based on customer requirements. Validate performance across temperature ranges to maximize application coverage while controlling costs.
- Strengthen hybrid and performance aftermarket capabilities. As ICE volumes face long-term headwinds, expand design expertise for hybrid-specific resonators and deepen aftermarket partnerships to capture growth from performance enthusiasts and modification markets.
- Align with regulatory roadmaps. Proactively engineer solutions that meet Euro 7 and emerging noise standards. Early compliance reduces qualification delays and positions suppliers as trusted partners for OEMs facing stringent emission targets.
For Investors and Strategic Partners
- Evaluate scale versus specialization. Assess potential targets based on their ability to leverage scale efficiencies while maintaining differentiated capabilities in material science, acoustic tuning, or aftermarket channels. Companies with both breadth and niche strength are better positioned to withstand margin pressures.
- Monitor regional shifts. Track production and demand trends in Asia Pacific, where volume growth is strongest, and assess exposure to supply chain risks. Investments in diversified manufacturing footprints or near-shoring capabilities can mitigate disruption risks.
- Consider aftermarket dynamics. Recognize that aftermarket performance brands can provide resilient revenue streams and brand visibility even as OEM volumes fluctuate. Partnerships or acquisitions in this space can offer growth avenues independent of traditional supply chain cycles.
For Procurement and OEM Stakeholders
- Prioritize suppliers with integrated solutions. Evaluate partners that can combine resonators with filtration and ducting to reduce assembly complexity and weight. Integrated offerings can lower total system cost and improve quality control.
- Develop material strategy aligned with application needs. Work with suppliers to match PP and PA materials to specific temperature and performance requirements, optimizing cost without compromising durability or compliance.
- Engage early in regulatory planning. Collaborate with suppliers to anticipate Euro 7 and noise regulation impacts, ensuring that intake system designs are validated well before mandatory implementation dates to avoid production delays.
The air intake resonator market is at a point where steady growth intersects with technological and regulatory change. Stakeholders who align their strategies with material innovation, hybrid demand, and acoustic differentiation will be best positioned to capture value through the forecast period. For deeper segmentation data, regional breakdowns, and customized strategic scenarios, access to comprehensive market intelligence is essential to refine these insights and support precise decision-making.
For detailed analysis of this topic, please visit the official page: Air Intake Resonator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com