

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Pin Surface Treatment Chemicals Market: Why 6.74% CAGR Predicts 2032's $2.13B Trajectory

Strategic Shifts and Commercial Opportunities in the Global Lead Pin Surface Treatment Chemicals Market
Market Landscape and Core Challenges
The global market for lead pin surface treatment chemicals has demonstrated consistent expansion over the past half-decade, reflecting the broader trajectory of advanced electronic packaging and precision metal finishing sectors. Valued at approximately $984 million in 2020, the market has progressed through steady annual increments to reach an estimated $1.35 billion in 2025. Forward projections indicate continued momentum, with the market expected to surpass $1.84 billion by 2030 and approach $2.13 billion by 2032, translating to a compound annual growth rate of roughly 6.74% across the forecast horizon. This growth trajectory is underpinned by persistent demand for reliable surface finishing solutions that enhance conductivity, corrosion resistance, and solderability in complex electronic assemblies.
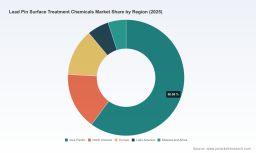
Structurally, the market exhibits notable regional concentration, with Asia Pacific accounting for the largest share of revenue generation, followed by North America, Europe, Latin America, and the Middle East and Africa. Chemical type segmentation reveals that electroplating solutions dominate the product mix, while cleaning and degreasing agents, de-flashing chemicals, and surface passivation agents collectively represent the remainder of industry spend. Application-wise, integrated circuit packaging and consumer electronics connectors remain the primary demand centers, with automotive electronic components and industrial/telecommunications applications rounding out the core end-use segments. The competitive environment is moderately consolidated, with the top three participants commanding over 40% of total market revenue and the top five firms capturing nearly 57%, indicating that scale, proprietary formulations, and established customer relationships continue to provide meaningful barriers to entry.
Despite this favorable growth backdrop, the industry faces several structural challenges that will define competitive outcomes over the next several years. First, regulatory pressure continues to intensify across major jurisdictions. Stricter environmental legislation, including REACH enforcement and evolving EPA restrictions on hazardous substances, is reshaping formulation requirements. Surface treatment chemistry for lead pins and electronic components must increasingly eliminate or reduce reliance on hexavalent chromium, minimize volatile organic compound emissions, and accommodate lower-toxicity metal alloys. These compliance demands raise formulation complexity and can extend qualification timelines, particularly for high-reliability applications. Second, raw material volatility has become a persistent operational concern. Prices for metal salts, acids, and specialty additives that form the backbone of electroplating baths and cleaning solutions remain subject to geopolitical supply disruptions, energy cost fluctuations, and shifting mining outputs. This creates margin compression risk for producers who cannot pass through cost increases quickly or who lack diversified sourcing strategies. Third, the rapid evolution of electronic packaging architectures is forcing surface treatment suppliers to adapt at a faster pace than historical norms. Miniaturization, high-density interconnect designs, and mixed-material substrates place new demands on plating uniformity, adhesion, and defect control, requiring more frequent process innovation and closer collaboration with equipment manufacturers and end users.
These dynamics create a clear inflection point. Companies that rely on legacy product lines without regulatory or performance upgrades risk gradual share erosion, while those investing in compliant formulations, flexible supply chains, and application-specific engineering support are positioned to capture disproportionate value as customers navigate qualification and compliance transitions.
Key Growth Drivers
Technological Innovation in Surface Finishing Chemistry
One of the most significant accelerants for the market is the ongoing development of advanced plating chemistries and surface treatment processes tailored to the precision requirements of modern electronic components. Electroplating solutions continue to dominate product demand because they deliver the combination of conductivity, solderability, and mechanical protection that lead frames, connectors, and IC packaging structures require. However, the nature of innovation is shifting from incremental performance gains toward multi-functional formulations that simultaneously address corrosion resistance, interfacial adhesion, thermal stability, and environmental compliance.
Recent industry activity illustrates this shift in practice. In February 2026, Technic Inc. showcased surface finishing solutions aimed at complex precision component challenges, including chemistry relevant to electronic component manufacturing for medical device applications. While the demonstration emphasized medical device use cases, the underlying capability set—controlled deposit uniformity, specialty alloy and tin/tin alloy chemistry, and process integration for high-precision substrates—directly parallels demands in lead frame and connector surface treatment. Demonstrations of this type signal that leading suppliers are building application cross-over expertise, using adjacent high-reliability sectors to refine chemistries that can be redeployed into electronic packaging environments with demanding tolerance requirements.
Beyond electroplating, complementary process chemistry is also advancing. Cleaning and degreasing agents, de-flashing chemicals, and surface passivation agents are increasingly specified as integrated pre-treatment and post-treatment steps rather than standalone consumables. This reflects a broader recognition that surface quality is determined by the full process chain. Suppliers that can offer compatible chemistry suites—cleaner, activator, plating bath, and passivation—reduce variability for manufacturing lines and shorten process qualification cycles, which is a meaningful commercial advantage in cost-sensitive, high-volume production environments.
Worldwide Lead Solder Ball Market
Regulatory and Environmental Compliance Pressures
Regulatory developments continue to act as both a constraint and a catalyst. Stringent global environmental regulations, including REACH and EPA restrictions on hazardous substances, are accelerating the transition toward eco-friendly, chrome-free, and lower-VOC surface treatment formulations for electronics applications. For lead pin and lead frame surface treatment specifically, the shift is particularly consequential because traditional brighteners, corrosion inhibitors, and passivation chemistries have historically relied on substances that are increasingly scrutinized.
Compliance is not merely a defensive requirement; it is becoming a competitive differentiator. End users in consumer electronics, automotive electronics, and industrial systems are under their own sustainability and disclosure mandates, which flow down to component suppliers and further to chemical providers. Formulations that reduce hazardous substance exposure, support waste treatment efficiency, and lower energy consumption during bath maintenance are increasingly preferred in supplier selection. As a result, companies that proactively develop and validate compliant chemistries can secure longer qualification cycles, deeper integration into customer process workflows, and a stronger position in regions where regulatory enforcement is most active.
PW Consulting
Demand-Side Shifts in Electronics and Automotive Electronics
Demand-side behavior is being reshaped by three interrelated forces: the proliferation of high-reliability electronic interconnects, the expansion of automotive electronic content, and the continued scaling of consumer electronics connector usage. Integrated circuit packaging remains the largest application driver because surface treatment quality directly affects signal integrity, solder joint reliability, and protection against environmental degradation. As packaging complexity increases, particularly in advanced interconnection schemes and finer pitch layouts, the surface treatment layer becomes more critical to overall assembly yield.
Consumer electronics connectors also sustain robust chemical demand. The ongoing refresh cycle for mobile devices, wearables, and connected peripherals sustains high volumes of connector production, where surface finish consistency influences contact resistance, corrosion life, and mating reliability. Meanwhile, automotive electronic components represent a structurally important growth avenue. Vehicle electrification, advanced driver-assistance systems, and in-vehicle connectivity continue to increase the number and complexity of electronic control units and interconnect assemblies. Automotive-grade requirements for thermal cycling, vibration resistance, and long-term corrosion protection place elevated demands on plating and passivation chemistry, encouraging adoption of higher-performance surface treatment solutions.
Supply Chain Dynamics and Cost Structure Evolution
Cost structure dynamics are evolving as raw material price fluctuations in metal salts, acids, and specialty additives continue to influence production economics for electroplating and cleaning solutions. These inputs are essential to bath chemistry, and price instability can quickly affect gross margins, especially for high-volume commodity-grade products. At the same time, supply chain regionalization is reshaping procurement strategies. Customers are increasingly prioritizing supply continuity and geographic proximity for critical process chemicals, particularly where production facilities are concentrated in Asia Pacific or near major electronics manufacturing clusters.
This environment favors suppliers with diversified input sourcing, inventory buffer strategies, and the ability to offer technical support that helps customers optimize bath life, reuse, and waste handling. The competitive implication is clear: cost leadership alone is becoming less durable, while total cost of ownership advantages—derived from better process stability, fewer defect-related reworks, and reduced compliance risk—can command stronger customer retention.
Competitive Landscape and Leading Strategies
The market’s competitive structure reflects a blend of established specialty chemical manufacturers and regionally focused suppliers with strong application ties. Technic Inc., headquartered in Cranston, Rhode Island, is a prominent participant in specialty electroplating chemistry for lead frames, connectors, and electronic components. Its portfolio emphasis on precious metal and tin/tin alloy solutions for lead frame and LED substrate applications, along with connector-leadframe components, positions the company within the higher-value segment of the market where performance and qualification support matter more than price alone. Technic’s recent trade show participation, highlighting surface finishing solutions for complex precision manufacturing including medical device-related electronic component chemistry, suggests a strategy of extending application expertise across adjacent high-reliability segments, potentially reinforcing technical credibility and cross-industry learning.
MKS | Atotech, based in Berlin, operates with a strong focus on wet chemical process solutions for leadframe and connector applications. Its Puronon family of cleaners, chemical deflashing offerings, and pre-treatment processes tailored for IC lead frames and electronic packaging illustrate a process-integration orientation. Rather than competing solely on chemical formulation, the company appears to emphasize the fit between cleaning, treatment, and plating steps within production lines. This approach can reduce customer friction during process setup and improve consistency, supporting deeper relationships in IC packaging and connector manufacturing environments.
JCU Corporation, headquartered in Tokyo, offers surface treatment chemical products including alkaline electrocleaners, etching agents, and activators specifically intended for IC lead frames and electronic parts plating lines. Its product focus suggests a strong alignment with precision pre-treatment and process cleanliness, an area that is increasingly important as feature sizes shrink and defect sensitivity rises. By concentrating on the early stages of surface preparation, JCU addresses a part of the value chain where small variations can have outsized effects on downstream plating quality and final assembly reliability.
Lead Frames Market
Shanghai Sinyang Semiconductor Materials Co., Ltd. participates in the market through traditional packaging lead pin surface treatment chemicals as part of a broader portfolio spanning wafer processing and semiconductor electronic chemicals. Its positioning reflects the strategic importance of domestic supply in key Asian manufacturing ecosystems. Companies with local formulation, production, and technical service capabilities can gain advantages in responsiveness, logistics, and alignment with regional qualification requirements, particularly where electronics manufacturing activity is densely concentrated.
Nihon Parkerizing Co., Ltd., also based in Tokyo, supplies surface treatment chemicals for cleaning substrates and adding functionality, serving broad industrial applications including electronics and metal components. Its wider application footprint provides diversification across end markets and exposes the company to cross-sector innovation in surface functionality, which may feed back into electronics-specific development over time.
Several strategic themes emerge from this landscape. First, differentiation is increasingly tied to application-specific engineering capability. Companies that can combine formulation expertise with process troubleshooting, qualification support, and technical service are better positioned to defend margins than those competing primarily on product price. Second, the moderately concentrated market structure—where the top three firms capture a sizable share and the top five account for a majority—suggests that scale benefits matter, but they are not insurmountable. Smaller or regionally focused players can succeed by serving niche applications, offering specialized process chemistry, or building strong local service networks. Third, the market appears primed for selective consolidation and portfolio expansion. Larger participants may seek to acquire complementary process chemistries, regional service assets, or formulation capabilities that strengthen their ability to deliver end-to-end solutions. At the same time, new entrants with differentiated technology—such as low-environmental-impact chemistries or advanced deposit control—may find opportunities in segments where incumbents face regulatory or performance transitions.
Future Trends and Commercial Implications
Looking ahead, three trends are likely to shape the market over the next three to five years. The first is the continued expansion of compliance-driven formulation development. As environmental regulations and corporate sustainability expectations tighten, demand will increasingly favor chrome-free, lower-VOC, and otherwise reduced-hazard surface treatment chemistries. This will create commercial opportunities for suppliers that can demonstrate equivalent or superior performance while meeting regulatory and customer disclosure requirements. It will also raise the cost of inaction for companies still dependent on legacy formulations that face longer qualification timelines or sourcing constraints.
The second trend is the growing importance of integrated process chemistry rather than standalone consumables. As lead pin and connector manufacturers seek to reduce variability, improve yield, and accelerate line changeovers, they will favor suppliers that can support the full sequence of cleaning, surface activation, plating, and passivation. This trend favors companies with broader portfolios and stronger technical service depth, and it increases the strategic value of partnerships between chemical suppliers, equipment providers, and end users.
The third trend is the geographic realignment of supply and technical support around major manufacturing hubs. Demand concentration in Asia Pacific will continue to reward suppliers with local formulation, production, and service capabilities, while also encouraging multinational participants to strengthen regional presence and responsiveness. Over time, this may contribute to a more multi-polar competitive structure, where global technology leadership and local execution capability both matter.
Associated risks deserve attention. Raw material price volatility may persist, especially if input supply chains remain exposed to geopolitical disruption or energy cost swings. Regulatory requirements may evolve faster than formulation cycles in some jurisdictions, creating compliance misalignment risk for slower-moving players. In addition, changes in electronic packaging architecture and interconnect design could shift demand patterns between chemical types and application segments more quickly than historical trends would suggest, making portfolio flexibility a critical capability.
Strategic Recommendations for Decision-Makers
For manufacturers and process engineers, the priority is to align surface treatment chemistry choices with both performance targets and compliance trajectories. Selecting formulations with stronger environmental profiles and broader process compatibility can reduce qualification risk and support smoother transitions as regulatory expectations rise. Manufacturers should also evaluate suppliers based on total process support rather than product price alone, since formulation stability, defect reduction, and technical responsiveness often have a larger impact on operating economics than unit cost differences.
For investors and business development teams, the key is to identify companies with durable differentiation in application-specific chemistry, regulatory readiness, and regional service capability. Portfolio breadth, technical service depth, and the ability to integrate cleaning, plating, and passivation solutions are likely to be more predictive of competitive resilience than scale alone. Opportunities may also arise in adjacent high-reliability sectors, where cross-industry learning can accelerate product development for electronics applications.
For procurement and supply chain leaders, diversification of supplier sources and chemistry options can reduce exposure to raw material volatility and single-source qualification risk. Cost management should increasingly account for bath life optimization, waste handling efficiency, and process stability, since these factors influence total ownership cost. As regional manufacturing concentration continues, proximity of supply and local technical support may become more important selection criteria, particularly for high-volume or high-reliability programs.
Given the pace of regulatory change, raw material variability, and application-level demand shifts, detailed and current segmentation data will be essential for precise planning. The full report provides deeper visibility into regional revenue distributions, chemical type and application splits, competitive share dynamics, and scenario-based forecasts that can support more targeted strategic decisions and customized operational planning.
For detailed analysis of this topic, please visit the official page: Worldwide Lead Pin Surface Treatment Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com