

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Processed Seafood Market 2026: Why 5.12% CAGR and Asia Pacific Lead the Global Expansion

Global Processed Seafood Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview: Scale, Trajectory, and Core Challenges
The global processed seafood market has demonstrated consistent expansion over the past five years, with total revenue reaching approximately $60.79 billion in 2025. The sector is projected to grow from $63.68 billion in 2026 to $86.11 billion by 2032, reflecting a compound annual growth rate of 5.12 percent. This trajectory signals a maturing but still dynamic industry where volume growth intersects with value creation through processing sophistication, branding, and supply chain optimization.
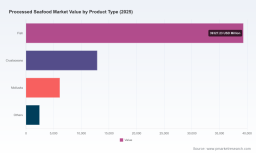
Regional distribution reveals a heavily Asia-Pacific-weighted landscape, followed by Europe and North America as substantial mature markets. Latin America and the Middle East and Africa collectively represent smaller but increasingly relevant consumption and sourcing corridors. Processing formats remain anchored by frozen seafood, which commands the largest share, while canned and smoked-dried segments provide complementary value propositions across retail and foodservice channels. Product-wise, fish-based processed goods dominate, with crustaceans and mollusks forming meaningful secondary categories that cater to specific culinary and convenience preferences.
Despite the favorable growth baseline, the industry faces several structural challenges that will define competitive outcomes over the forecast period:
Raw material cost volatility and supply uncertainty. Fishery and aquaculture commodity prices have been trending upward, with the FAO Fish Price Index averaging 127.4 points in March 2026, an 8.4 percent increase compared to March 2025. Salmon and shrimp prices have shown particularly notable rises. Simultaneously, USDA projections indicate that fish and seafood prices in the food-at-home category will increase faster than the 20-year historical average in 2026. For processors, this translates into margin compression risk unless pricing strategies, long-term supply contracts, and product mix adjustments are actively managed.
Traceability, compliance, and quality assurance pressures. Regulatory expectations around seafood traceability are intensifying. New FSMA traceability requirements apply to certain seafood on the Food Traceability List, mandating additional records for aquaculture farms and processing facilities to enable rapid identification and removal of contaminated products. In parallel, the Global Dialogue on Seafood Traceability launched a public consultation in March 2026 on an updated standard planned for release in July 2026, moving toward a commodity-agnostic modular approach applicable to processed seafood. These developments raise the compliance burden but also create differentiation opportunities for operators that can demonstrate robust, verifiable supply chain integrity.
Geopolitical and trade friction amid resilient demand. Tariffs, bans, and freight risks have introduced uncertainty into cross-border seafood flows. Yet global seafood trade is expected to continue growing into 2025 and 2026 without an anticipated reduction in key U.S. imports. This resilience suggests that demand fundamentals remain strong, but the operating environment is becoming more complex, requiring diversified sourcing, flexible logistics, and proactive regulatory monitoring.
These challenges are not merely headwinds; they are shaping a market where operational excellence, transparency, and strategic sourcing will separate outperformers from laggards.
Key Drivers: Technology, Regulation, Demand, and Supply Chain Dynamics
Several interconnected forces are accelerating change in the processed seafood sector. Understanding how these drivers interact is essential for prioritizing investment and capability-building decisions.
Technological Innovation and Processing Breakthroughs
Processing technology continues to improve product quality, shelf life, and value addition. Advanced freezing methods, controlled atmosphere packaging, and automated portioning are enabling producers to deliver convenience-oriented products that meet retail and foodservice specifications while reducing waste. In smoked and dried categories, precision smoking and dehydration technologies are enhancing consistency and flavor profiles, supporting premiumization in niche markets.
Traceability technology is another critical frontier. Digital record-keeping, lot-level tracking, and modular traceability frameworks are becoming operational necessities rather than optional enhancements. The shift toward commodity-agnostic traceability standards will likely accelerate adoption of interoperable systems that can be applied across fish, crustaceans, and mollusks, reducing the friction of managing multiple compliance regimes. For processors, technology investment is increasingly tied to market access: buyers and regulators are demanding verifiable provenance, and systems that can produce auditable records quickly will confer a competitive advantage.
Policy and Regulatory Environment
Regulatory dynamics are reshaping both cost structures and market entry conditions. Beyond traceability, short weighting enforcement has gained visibility. FDA released results from its 2022-2024 testing program on frozen seafood products for short weighting as part of ongoing compliance efforts, signaling sustained regulatory focus on accurate product representation. For processors, this underscores the importance of weight integrity, packaging accuracy, and internal quality controls.
Import eligibility and establishment compliance also remain critical. A 2025 recall of ineligible frozen Siluriformes fish products imported from Vietnam due to establishment ineligibility for U.S. export illustrates the consequences of non-compliance in supplier qualification. Similarly, recalls of frozen shrimp products associated with potential cesium-137 contamination concerns from specific processors highlight the sensitivity of safety and contamination risk management. These events reinforce that supplier vetting, facility audits, and risk-based monitoring are integral to maintaining market access and brand trust.
Demand-Side Shifts in Consumer and Business Behavior
Consumer preferences continue to tilt toward convenience, protein-rich diets, and products with clear quality and sustainability narratives. Processed seafood benefits from these trends because it offers ready-to-cook, ready-to-eat, and portion-controlled formats that fit modern meal planning. In foodservice, consistent supply, predictable specifications, and ease of preparation are valued highly, favoring processors that can deliver reliable, value-added products at scale.
At the same time, traceability and transparency are increasingly influencing purchase decisions. Retail and foodservice buyers are responding to consumer expectations by requiring suppliers to provide credible documentation on origin, handling, and compliance. This creates a reinforcing cycle: demand for transparent products pressures processors to invest in traceability, which in turn enables more confident purchasing by downstream customers.
Supply Chain and Cost Structure Evolution
Supply chain resilience has become a strategic priority. The combination of rising commodity prices, freight volatility, and trade friction is pushing processors to diversify sourcing, strengthen supplier relationships, and optimize inventory and logistics. Long-term contracts with aquaculture producers, strategic partnerships with wild-catch operators, and investment in cold chain infrastructure are becoming common responses to reduce exposure to price spikes and disruption.
Cost structures are also being reshaped by compliance and technology investments. While traceability systems and enhanced quality controls add upfront costs, they can reduce the risk of recalls, protect market access, and support premium positioning. The net effect is a shift from pure cost minimization toward total cost of ownership thinking, where reliability, compliance, and brand protection are weighted alongside unit production costs.
PW Consulting
Competitive Landscape: Strategic Positioning and Market Evolution
The processed seafood market is characterized by a moderately concentrated structure, with the top three players holding approximately 18.45 percent and the top five around 24.12 percent of total revenue. This level of concentration suggests that while large global players command meaningful scale, significant space remains for regional specialists, niche value-added producers, and emerging entrants that can differentiate through product innovation, sourcing advantage, or service model.
Leading companies are pursuing distinct strategic positions:
- Global integrated processors with strong branding. Thai Union Group and Maruha Nichiro Corporation exemplify operators with broad portfolios spanning canned tuna, frozen seafood, and value-added products. Their scale, worldwide supply chain capabilities, and brand portfolios enable them to serve diverse markets and channel requirements. Recent developments reinforce this orientation: Mitsubishi Corporation increased its stake in Thai Union to 20 percent in August 2025 to strengthen business alliance in global seafood operations, highlighting the strategic value of capital partnerships that bolster international reach and operational synergies.
- Aquaculture-focused salmon and whitefish leaders. Mowi ASA, Lerøy Seafood Group, and Cooke Inc. are positioned around farmed salmon and related processed products, with Mowi operating as the world’s largest salmon farming and processing company. Their advantage lies in controlling key parts of the value chain from production to processing, supporting consistent supply, quality management, and responsiveness to retailer and foodservice specifications. Austevoll Seafood ASA and Royal Greenland add further depth in farmed and cold-water seafood processing, broadening the geographic and species footprint of this cohort.
- Regional value-added specialists. High Liner Foods and Trident Seafoods demonstrate focused strategies in North American markets. High Liner Foods completed the acquisition of leading U.S. seafood brands Mrs. Paul’s and Van de Kamp’s from Conagra Brands in June 2025, strengthening its value-added frozen seafood portfolio and expanding its branded retail presence. Trident Seafoods specializes in wild-caught Alaskan seafood with extensive frozen and canned processed offerings, leveraging regional sourcing reputation and product familiarity.
- Broad international portfolios and regional distributors. Companies such as Nippon Suisan Kaisha, Kyokuyo Co. Ltd., Pacific Seafood Group, and Bolton Group illustrate the diversity of models across integrated procurement and processing, Pacific Northwest distribution focus, and European/international market portfolios. Nissui’s emphasis on global supply chains for frozen and highly-processed marine foods, and Boltton’s portfolio orientation in European and international markets, reflect the importance of channel reach and product breadth in serving varied customer bases.
Market structure is evolving along several axes. Consolidation is evident in branded retail and value-added segments, where acquisitions strengthen portfolio depth and channel leverage. At the same time, differentiation is intensifying around traceability, quality assurance, and sourcing credentials, creating room for companies that can credibly demonstrate superior compliance and product integrity. New entrants and smaller regional players can compete by specializing in particular species, processing methods, or local market relationships, especially where large players’ scale advantages are less decisive. The overall trend is toward a layered landscape: large integrators competing on scale, brand, and supply chain breadth; mid-tier and regional specialists competing on focus, responsiveness, and niche credibility; and traceability-conscious operators competing on transparency and risk management.
Forward Outlook: Trends Shaping the Next Three to Five Years
Looking ahead to 2032, several trends are likely to define the market’s evolution and the allocation of commercial opportunity.
Traceability becomes a market-access baseline. As traceability standards mature and FSMA requirements take full effect for listed seafood, the ability to produce modular, auditable, commodity-agnostic records will transition from differentiator to baseline expectation. Processors that invest early in interoperable systems and supplier data integration will be better positioned to serve demanding retail and foodservice buyers, while those lagging may face increasing friction in qualification and retention. The commercial opportunity lies not only in compliance but in using traceability as a trust signal that supports premium positioning and stronger customer relationships.
Value-added and convenience formats capture incremental growth. Frozen seafood will likely remain the largest processing format, but growth will be disproportionately driven by value-added products that reduce preparation effort, offer consistent portioning, and align with channel needs. Acquisitions such as High Liner Foods’ expansion of its branded U.S. portfolio indicate thatstrategic owners are betting on branded, value-added frozen seafood as a growth lever. Processors that can combine quality, convenience, and credible sourcing narratives are well placed to capture share in retail and foodservice.
Price volatility and supply diversification become strategic capabilities. With commodity prices trending above historical norms and trade friction persisting, the ability to manage input costs through diversified sourcing, forward contracting, and product mix flexibility will be a critical capability. Processors that can shift among species, origins, and formats in response to price signals, while maintaining quality and compliance, will protect margins more effectively. The risk is that operators with concentrated sourcing or rigid cost structures face disproportionate exposure to price spikes and disruption.
These trends point to a market where resilience, transparency, and value addition are increasingly intertwined. The upside is meaningful for operators that align capabilities with these directions; the downside risk is concentrated in businesses that remain dependent on single-source sourcing, minimal compliance investment, and undifferentiated product offerings.
Actionable Guidance for Decision Makers
For manufacturers and processors, the priority is to strengthen traceability infrastructure and supplier data integration now, ahead of the July 2026 standard update and the full operationalization of FSMA traceability requirements for listed seafood. Parallel investment in value-added product development, branded portfolio expansion, and diversified sourcing will help capture growth while mitigating input cost volatility. Weight integrity, facility compliance, and contamination risk management should be treated as core operational metrics, not peripheral quality tasks.
For investors, the market’s moderate concentration and ongoing consolidation create opportunities to assess companies with credible scale advantages, strong brand portfolios, and resilient sourcing models. Capital partnerships, such as the increased Mitsubishi stake in Thai Union, signal that strategic alliances are being used to reinforce global operations; similar structures may be relevant for companies seeking to accelerate international reach or technology adoption. Due diligence should weigh traceability readiness, compliance history, and product mix flexibility as indicators of long-term market access and margin stability.
For procurement leaders in retail and foodservice, supplier qualification should place greater weight on verifiable traceability, establishment compliance, and risk-based monitoring. Diversifying the supplier base across regions and species can reduce exposure to tariffs, freight risks, and single-source disruptions, while still capturing the growth expected in global seafood trade. Requiring modular, auditable traceability records and clear documentation on weight and safety compliance will help protect brand integrity and consumer trust.
Processed Vegetable Market
Detailed segment-level data, company-specific benchmarks, and scenario analysis can materially sharpen these decisions. For executives seeking granular breakdowns across regions, processing types, and product categories, as well as customized strategic guidance tailored to specific operating models, an in-depth market report is available for further review.
Processed Cheese Market
For detailed analysis of this topic, please visit the official page: Worldwide Processed Seafood Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com