

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Prostaglandins Market: Why 5.24% CAGR and Ophthalmology Demand Reshape 2032

Strategic Trends and Commercial Opportunities in the Global Prostaglandins and Related Drugs Market
Market Overview and Core Challenges
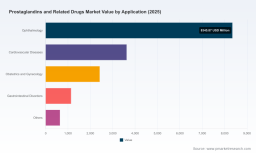
The global market for prostaglandins and related drugs has demonstrated steady expansion over the past half-decade, moving from a valuation of approximately $12.45 billion in 2020 to an estimated $16.17 billion in 2025. This trajectory reflects a compound annual growth rate of 5.24 percent through 2032, signaling a maturing yet still dynamic therapeutic segment. The market’s resilience stems from its entrenched role in managing chronic conditions where prostaglandin-based mechanisms deliver measurable clinical outcomes. Revenue generation is broadly distributed across advanced economies and emerging regions, with North America and Europe collectively accounting for a significant share of total sales, while Asia Pacific continues to capture incremental growth driven by expanding healthcare access and localized manufacturing capacity.
Despite the favorable top-line momentum, the industry faces structural headwinds that will shape competitive positioning in the coming years. First, the proliferation of generic alternatives following the patent expirations of major branded prostaglandin analogs between 2010 and 2020 has fundamentally altered pricing dynamics. While this has improved patient access and broadened prescription volumes, it has simultaneously compressed margins for originator manufacturers and intensified the need for cost-efficient production models. Second, the segment is experiencing heightened scrutiny around supply chain resilience, particularly for active pharmaceutical ingredients where synthesis complexity and regulatory compliance requirements create bottlenecks. Third, reimbursement pressures are reshaping commercial strategies, as evidence from historical spending data shows a shift in payer behavior—from a period where branded products dominated utilization to an environment where formulary restrictions and cost-containment policies demand clearer value differentiation.
Prostaglandin Market
For executives and investors, these dynamics point to a market where scale, intellectual property strategy, and manufacturing agility will separate long-term winners from passive participants. The growth trajectory remains intact, but capturing value now requires navigating a landscape where clinical differentiation, regulatory navigation, and supply chain integration matter as much as therapeutic efficacy.
Key Drivers of Market Evolution
Technological Innovation and Formulation Breakthroughs
Advancements in drug delivery and molecule engineering are redefining how prostaglandin therapies are administered and experienced by patients. The introduction of sustained-release formats, such as intracameral implants, illustrates a broader shift toward reducing treatment burden and improving adherence in chronic conditions like glaucoma. Regulatory milestones have validated these approaches, with approvals expanding the clinical utility of established molecular classes into new administration routes and patient populations. Beyond ophthalmology, the extension of prostaglandin-based therapies into areas like severe frostbite management demonstrates how legacy molecules can find renewed relevance when paired with innovative delivery mechanisms or new clinical indications. These developments create commercial pathways for companies that can successfully integrate formulation science with clinical evidence generation.
Regulatory Environment and Policy Dynamics
The regulatory landscape continues to shape market entry, pricing, and competitive intensity. Approval timelines and label expansions directly influence the commercial lifespan of branded products and the pace at which generics can capture market share. Recent regulatory actions have underscored a dual trend: agencies are encouraging therapeutic innovation through expedited pathways for unmet needs, while simultaneously maintaining rigorous standards that reward high-quality manufacturing and comprehensive clinical data. For manufacturers, this environment rewards early investment in regulatory strategy, robust quality systems, and proactive engagement with evolving safety and efficacy expectations. Policy shifts around formulary management and reimbursement benchmarks further incentivize companies to articulate clear value propositions that align with payer priorities.
Demand-Side Shifts and Clinical Utilization Patterns
Clinical demand is being reshaped by demographic trends and evolving treatment paradigms. The growing prevalence of chronic conditions requiring long-term prostaglandin therapy, particularly in ophthalmology and cardiovascular care, sustains baseline demand while creating opportunities for differentiated products that address adherence, tolerability, or convenience. At the same time, healthcare providers and payers are increasingly focused on total cost of care, favoring therapies that reduce follow-up burden, minimize adverse effects, or simplify administration. This behavior shift encourages manufacturers to invest in real-world evidence, patient support programs, and hybrid delivery models that align with the practical realities of chronic disease management. In parallel, emerging markets are expanding their healthcare footprints, creating incremental demand for both branded and generic prostaglandin products as diagnostic capacity and treatment access improve.
Supply Chain Dynamics and Cost Structure Pressures
The cost and reliability of prostaglandin manufacturing remain central to competitive positioning. Synthesis complexity, stringent quality requirements, and the need for specialized infrastructure create barriers that favor companies with vertically integrated or strategically partnered production capabilities. Recent capacity expansion announcements highlight how leading manufacturers are responding to anticipated demand growth by investing in dedicated facilities, process optimization, and regional production footprints. These investments are not merely scale plays; they are strategic hedges against supply disruptions, regulatory delays, and margin erosion from price competition. For buyers and downstream partners, this trend signals a market where supply reliability and quality consistency will increasingly influence sourcing decisions, particularly as demand for both branded and generic formulations continues to expand across therapeutic areas.
Competitive Landscape and Leading Strategies
The competitive ecosystem for prostaglandins and related drugs blends large global pharmaceutical companies with specialized active pharmaceutical ingredient manufacturers and generic-focused producers. Each group occupies a distinct strategic position, and the interplay between them is reshaping how value is created and captured across the supply chain.
Large multinational firms maintain strong commercial presence in high-value therapeutic areas, particularly ophthalmology, where prostaglandin analogs are well established for intraocular pressure management. These companies leverage extensive commercial infrastructure, established physician relationships, and brand recognition to sustain market relevance even as generic alternatives proliferate. Their differentiation often rests on formulation optimization, delivery device innovation, and integrated patient support ecosystems. Some also extend their reach through complementary portfolio acquisitions or division-level focus, ensuring that established molecules remain commercially viable through lifecycle management and combination strategies.
Specialized API manufacturers occupy a critical position in the value chain, particularly where synthesis complexity and regulatory rigor create meaningful barriers. Companies that have invested in fully integrated production sites or possess complete prostaglandin portfolios are positioned to serve both branded and generic customers with greater supply reliability and cost predictability. Strategic capacity expansion in regions that offer manufacturing efficiency and regulatory alignment reflects a long-term bet on sustained demand growth and the need for resilient sourcing. For these players, the value proposition is built on technical capability, production scale, and the ability to support downstream formulation partners with consistent quality.
Generic manufacturers have expanded access and intensified price competition, particularly following the wave of patent expirations that opened the market to multiple alternatives. Their strategy centers on regulatory agility, cost-efficient production, and the ability to launch equivalents across multiple dosage forms and markets. Recent approvals of generic prostaglandin ophthalmic solutions illustrate how generic entrants continue to broaden therapeutic access while reinforcing the importance of manufacturing quality and supply consistency in a crowded field. These companies often compete on distribution reach, formulary positioning, and operational efficiency, making them essential participants in the market’s overall growth dynamics.
Regional and mid-sized producers, including specialized firms in Asia and Europe, add further depth to the competitive landscape by focusing on intermediates, niche formulations, and local market requirements. Their presence supports broader supply diversification and can provide downstream partners with flexible sourcing options. At the same time, the market is showing signs of gradual consolidation pressure, as scale advantages in manufacturing, regulatory compliance, and commercial reach become increasingly valuable. New entrants face a steep path unless they bring clear differentiation—whether through novel delivery technologies, unique molecular variants, or highly specialized manufacturing expertise.
For decision-makers, the key takeaway is that competitive advantage in this market is no longer defined by a single molecule or therapy area. It is increasingly determined by the ability to integrate clinical differentiation, manufacturing reliability, regulatory foresight, and commercial execution into a coherent strategy. Companies that can align these elements will be best positioned to defend share in mature segments while capturing growth in evolving applications.
Future Trends and Strategic Outlook
Over the next three to five years, the prostaglandins and related drugs market is likely to be shaped by three reinforcing trends. First, formulation and delivery innovation will continue to create commercial differentiation, especially in chronic therapy areas where adherence and treatment burden are persistent challenges. Sustained-release systems, alternative administration routes, and device-drug combinations are expected to gain further traction as clinical evidence and payer acceptance mature. These advances open opportunities for companies that can demonstrate tangible improvements in patient outcomes and total cost of care.
Second, supply chain localization and capacity investment will become more prominent as manufacturers seek to reduce dependency on concentrated production networks and mitigate regulatory or logistical disruptions. Expect continued capital deployment in dedicated facilities, process intensification, and regional manufacturing footprints designed to support both branded and generic demand. This trend will reward suppliers that can offer predictable quality, scalable capacity, and transparent compliance records.
Third, pricing and reimbursement dynamics will keep pressure on undifferentiated products while rewarding therapies with clear clinical or economic value. As health systems refine formulary strategies and emphasize cost-effectiveness, the market will increasingly separate products that compete primarily on price from those that can justify positioning through superior delivery, tolerability, or evidence-based value arguments. This environment will favor strategic portfolio management, lifecycle planning, and early engagement with payer and provider stakeholders.
Potential uncertainties include the pace of new indication approvals, the trajectory of generic penetration in key markets, and the impact of regulatory changes on manufacturing requirements and launch timelines. Macroeconomic factors affecting raw material costs, capital availability, and healthcare spending patterns may also influence investment timing and margin expectations. Companies that monitor these variables closely and maintain flexible strategic plans will be better equipped to navigate shifts in demand and competitive intensity.
Decision-Maker Action Recommendations
For manufacturers, the priority is to strengthen the foundation that supports both margin defense and growth capture. Invest in formulation and delivery capabilities that differentiate offerings beyond molecule identity, and align manufacturing strategy with long-term demand signals rather than short-term volume fluctuations. Companies that can combine supply reliability with clear clinical or practical value will have greater leverage in formulary negotiations and partnership discussions.
For investors, focus on organizations that demonstrate durable competitive advantages in API production, regulatory execution, and commercial reach within prostaglandin-related therapy areas. Evaluate exposure to segments where generic pressure is balanced by differentiated delivery, where regional demand growth is supported by healthcare expansion, and where supply chain resilience translates into more predictable revenue streams. Portfolio positioning should account for both the steady-growth core and the higher-upside potential of novel delivery or expanded indications.
For procurement and sourcing leaders, evaluate suppliers not only on unit cost but on quality consistency, capacity visibility, and regulatory standing. In a market where price competition is intense and supply interruptions can carry significant clinical and commercial consequences, multi-source strategies and supplier qualification rigor can reduce risk while supporting continuity of care. Early engagement with manufacturers that are expanding capacity or modernizing production can also improve long-term negotiating positioning.
Worldwide Carboprost Tromethamine Market
Given the pace of regulatory change, generic entry dynamics, and evolving demand patterns, access to timely and granular market intelligence is essential for informed decision-making. Detailed segmentation data, company-level tracking, and scenario-based forecasts can help organizations refine strategy, anticipate competitive moves, and identify the most relevant opportunities across regions and therapeutic applications. For those seeking a deeper, structured view of the market’s trajectory and strategic implications, the full PW Consulting research report provides the detailed breakdowns and customized analysis needed to support execution at the operational and portfolio level.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Prostaglandins and Related Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com