

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Landscape Rock Market: 5.45% CAGR Fuels Reshaping Competition

Global Landscape Rock Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The worldwide landscape rock market has established itself as a resilient component of the broader landscaping and construction materials sector. Valued at approximately 4,333 million USD in 2020, the market expanded to an estimated 5,650 million USD by 2025, reflecting consistent growth across diverse geographic and application segments. Forward projections indicate the market will reach 8,191 million USD by 2032, supported by a compound annual growth rate of 5.45 percent over the 2026–2032 forecast horizon. This trajectory underscores sustained demand for natural and processed stone materials in outdoor design, infrastructure development, and recreational space creation.
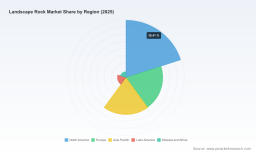
From a structural standpoint, the market exhibits moderate fragmentation. The top three companies collectively account for roughly 12.5 percent of total revenue, while the top five hold approximately 18.2 percent. Such concentration levels suggest that while major players maintain meaningful market share, the landscape remains open to specialized operators, regional distributors, and niche product innovators. The revenue distribution across regions reflects a mature base in North America, complemented by steady demand across Europe and the Asia Pacific, alongside emerging opportunities in Latin America and the Middle East and Africa. Application-wise, residential landscaping continues to represent the largest demand driver, followed by commercial infrastructure and public parks and recreational facilities. By product type, crushed granite and stone, river rock, lava rock, and boulders and decorative stones each serve distinct aesthetic and functional requirements across these end-use segments.
Despite the constructive growth outlook, the industry faces several structural challenges that will shape competitive dynamics over the coming years. First, environmental scrutiny and regulatory tightening around quarrying operations, land reclamation, and water usage are increasingly influencing site approvals and operational costs. Companies must navigate evolving local and state requirements while maintaining supply continuity, which can compress margins and delay expansion timelines. Second, the market's reliance on natural stone extraction creates inherent supply constraints. Geological availability, transportation logistics, and quarry permitting cycles introduce volatility in lead times and pricing, particularly for specialty or imported stone varieties. Third, the residential landscaping segment, while dominant, is sensitive to macroeconomic cycles, housing market fluctuations, and discretionary spending patterns. Shifts in consumer confidence or interest rate environments can quickly alter project pacing and material procurement behavior, requiring suppliers and distributors to maintain flexible inventory and pricing strategies.
These challenges are not insurmountable, but they demand proactive strategic positioning. Operators that invest in sustainable extraction practices, diversify product portfolios, and strengthen downstream distribution capabilities are better equipped to absorb regulatory and demand-side shocks. At the same time, the moderate concentration of the market leaves room for consolidation, partnership models, and targeted acquisitions that can enhance scale, geographic reach, and product differentiation.
Key Demand Drivers and Structural Shifts
Several interconnected forces are reshaping the landscape rock market, creating both pressure and opportunity for stakeholders across the value chain. Understanding these drivers is essential for anticipating where growth will concentrate and which capabilities will differentiate leaders from laggards.
Technological Innovation and Product Differentiation
Advances in crushing, screening, and finishing technologies have expanded the range of available stone profiles, enabling more consistent sizing, improved surface textures, and tailored color variations. Producers are increasingly leveraging precision processing to offer specialized aggregates that meet aesthetic and functional specifications for hardscaping, pool deck surrounds, vertical masonry, and decorative ground cover. In parallel, the adoption of eco-friendly extraction techniques and sustainable quarrying practices is gaining traction among natural stone producers seeking to minimize environmental impact while aligning with buyer expectations for responsibly sourced materials. These innovations are not merely operational improvements; they are becoming competitive differentiators that influence procurement decisions among landscape contractors, designers, and retail distributors.
A notable illustration of this trend is the introduction of premium imported natural stone lines designed for hardscape, pool deck, and vertical masonry applications. Such launches signal a broader industry movement toward higher-margin, design-forward product categories that cater to upscale residential and commercial projects. By emphasizing imported specialty stones and curated finishes, suppliers are capturing demand from buyers who prioritize visual appeal, durability, and project-specific performance over commodity-grade alternatives.
Policy and Regulatory Environment
Regulatory frameworks governing quarry operations, reclamation obligations, and water usage continue to evolve, particularly in regions where residential and commercial development intersect with environmentally sensitive areas. Aggregates and landscape materials face local and state requirements that shape permitting timelines, operational boundaries, and post-extraction land management. Companies that proactively integrate compliance into their operational planning—through responsible site design, water conservation measures, and reclamation commitments—can reduce approval friction and build stronger relationships with regulators and community stakeholders.
At the same time, the growing emphasis on sustainable sourcing is influencing procurement standards among larger contractors and commercial developers. Buyers are increasingly requesting documentation on extraction practices, environmental stewardship, and supply chain transparency. This shift is encouraging producers to adopt more formalized sustainability reporting and to differentiate their offerings based on responsible sourcing credentials, which can become a decisive factor in competitive bids and long-term supply agreements.
Demand-Side Behavior and End-Use Evolution
Consumer and enterprise behavior is shifting toward outdoor spaces that serve multiple functions: aesthetic enhancement, recreational use, and durable hardscaping. Residential landscaping remains the largest application driver, supported by home improvement activity, curb appeal investments, and the popularity of low-maintenance outdoor design. Commercial infrastructure demand is also sustained by urban redevelopment, hospitality projects, and mixed-use developments that incorporate landscaped courtyards, pedestrian pathways, and decorative stone elements. Public parks and recreational facilities contribute additional volume, particularly where municipalities invest in trail systems, green spaces, and community amenities.
Limestone Market
Within this demand environment, buyers are placing greater emphasis on coverage efficiency, material consistency, and installation practicality. For example, landscape rock ground cover is commonly evaluated by square footage coverage at specified depths, while cobble or rubble stone is assessed by coverage per ton. These practical considerations influence product selection and pricing sensitivity, encouraging suppliers to provide clear specifications and reliable volume guidance. The result is a market where technical performance and aesthetic value are increasingly intertwined, and where distributors that can articulate usage parameters gain an edge in customer conversations.
Supply Chain and Cost Structure Dynamics
Supply chain considerations are becoming more prominent as operators manage quarry output, transportation constraints, and inventory positioning across regional markets. North America remains a major market for landscape rock, supported by significant domestic quarrying in the United States and selective imports of specialty stones. This dual structure allows suppliers to balance cost efficiency with product variety, but it also requires careful coordination between extraction schedules, logistics capacity, and downstream fulfillment.
Cost structures are influenced by energy inputs, equipment maintenance, labor availability, and site-specific extraction conditions. In response, several operators are pursuing capacity expansion and operational optimization to improve throughput and reduce unit costs. Recent planning approvals for expanded quarry operations illustrate how companies are seeking to scale production footprints to meet projected demand while improving supply reliability. Such expansion decisions are often driven by the expectation that stronger demand visibility and improved operational scale will support margin stability through the forecast period.
Industry performance signals also point to cautious optimism among aggregates and stone operators. Steady performance in core operations, combined with positive outlooks for the near term, suggests that many producers are navigating current conditions with disciplined cost management and selective investment. This environment favors companies that can align capacity plans with demand signals, maintain inventory flexibility, and respond quickly to regional procurement shifts.
Worldwide Natural Stone Market
Competitive Landscape and Leading Strategies
The competitive landscape of the landscape rock market is characterized by a mix of global aggregates leaders, regional stone specialists, and focused decorative product suppliers. This diversity creates multiple pathways to competitive advantage, depending on whether a company competes on scale, product specialization, geographic coverage, or design-oriented branding.
PW Consulting
Global aggregates leaders such as Holcim, CRH plc, Vulcan Materials Company, Martin Marietta, and Heidelberg Materials bring extensive production capabilities, broad distribution networks, and deep experience in crushed stone and landscape rock supply for construction and landscaping projects. Their scale enables them to serve large commercial infrastructure programs, maintain consistent output across multiple regions, and invest in processing infrastructure that supports a wide range of product grades. For these companies, differentiation often comes from supply reliability, standard product breadth, and the ability to integrate landscape rock offerings within broader aggregates and building materials portfolios.
Regional and specialty players occupy a different strategic space. Companies such as Aggregates International, Polycor Inc., Kafka Granite LLC, RCP Block & Brick, Inc., Techo-Bloc, Yardco Rock & Stone, Euro Quarries, Minick Materials, Basalite Concrete Products, and Boral Limited compete by emphasizing curated decorative aggregates, natural stone quarrying expertise, hardscape product integration, and nationwide or regional delivery capabilities. Their portfolios often include pebbles, chippings, rockery, decomposed granite, flagstone, and complementary concrete or pavers, allowing them to address design-sensitive residential and commercial projects with a more tailored value proposition. For these operators, differentiation is frequently built on product variety, aesthetic positioning, sourcing flexibility, and service responsiveness.
Recent market developments highlight how companies are executing on these strategic paths. The launch of premium imported natural stone lines for hardscape, pool deck, and vertical masonry applications reflects a deliberate move toward higher-value product categories that align with upscale project requirements. At the same time, capacity expansion initiatives, such as planning approvals to significantly increase quarry acreage, demonstrate efforts to strengthen production scale and supply resilience. Alongside these moves, steady operational performance and constructive near-term outlooks among aggregates and stone operators indicate that disciplined execution remains central to navigating demand variability and cost pressures.
The market structure is evolving along several trends. Consolidation is likely to continue where larger players seek to expand regional coverage, acquire specialized product lines, or integrate downstream distribution. At the same time, fragmentation will persist in segments where local sourcing, decorative specialization, and customer intimacy matter most. New entrants and expanding distributors can gain traction by focusing on underserved geographies, importing distinctive stone varieties, or combining landscape rock with complementary hardscape products. The net effect is a competitive environment where scale and specialization are not mutually exclusive; rather, successful companies often blend both by operating efficient core production while cultivating differentiated product and service offerings.
Future Trends and Strategic Implications
Looking ahead over the next three to five years, several trends are likely to shape the direction of the landscape rock market and inform where commercial opportunities will emerge.
One key trend is the continued expansion of design-forward and specialty stone categories. As residential and commercial projects place greater emphasis on outdoor aesthetics, durable hardscaping, and multi-functional recreational spaces, demand for curated finishes, imported varieties, and application-specific products is expected to grow. This creates opportunities for suppliers that can reliably source, process, and distribute distinctive materials while providing clear guidance on coverage, installation, and performance. Companies that invest in product education, specification support, and visual merchandising will be better positioned to capture higher-margin demand.
A second trend is the increasing importance of sustainable sourcing and regulatory readiness as competitive factors. Buyers, contractors, and municipal purchasers are likely to place greater weight on responsible extraction practices, environmental documentation, and long-term site stewardship. Operators that formalize sustainability credentials, adopt eco-friendly extraction techniques, and maintain strong compliance records can use these attributes to strengthen bids, build customer trust, and reduce regulatory risk. This trend also favors partnerships and supply chain transparency, as downstream buyers seek assurance across the sourcing-to-delivery chain.
A third trend is the ongoing alignment of capacity and distribution with regional demand patterns. As housing activity, commercial development, and public space investment fluctuate across markets, suppliers will need to balance production scale with inventory agility. Capacity expansions that improve throughput and reduce lead times can strengthen market position, but they must be paired with demand forecasting and logistics coordination to avoid oversupply or underutilized assets. In this environment, companies that develop flexible distribution models, regional stock positioning, and responsive customer service will be more resilient to localized demand shifts.
These trends carry potential risks and uncertainties. Regulatory changes can alter permitting timelines and operating costs, particularly in areas where quarry expansion intersects with community or environmental concerns. Macroeconomic conditions may affect discretionary residential spending and the pace of commercial construction, creating variability in order flow. Supply disruptions, transportation constraints, and shifts in energy or input costs can also pressure margins. Companies should therefore treat growth planning as conditional on scenario awareness, maintaining flexibility in capacity commitments, product mix, and pricing strategy.
Actionable Guidance for Decision-Makers
For manufacturers and producers, the priority is to align processing capability and product breadth with the growing demand for specialty and design-oriented stone categories. Investing in finishing consistency, curated color and texture options, and clear usage specifications can help capture higher-value demand while supporting customer installation success. At the same time, strengthening sustainable sourcing practices and compliance documentation will increasingly serve as a baseline expectation rather than a differentiator alone.
For investors, the market's moderate concentration and diverse competitive pathways suggest value in evaluating both scaled aggregates operators and specialized decorative stone suppliers. Due diligence should focus on geographic exposure, capacity expansion plans, product mix toward higher-margin categories, and the ability to manage regulatory and supply chain risk. Companies with disciplined cost structures, flexible distribution, and credible sustainability positioning are likely to be better prepared for demand variability and evolving buyer standards.
For procurement teams and distributors, the emphasis should be on supplier reliability, specification clarity, and inventory responsiveness. Understanding coverage parameters, material consistency, and regional availability can reduce project risk and improve customer outcomes. Building relationships with suppliers that offer both dependable core products and distinctive specialty lines can provide a balanced portfolio that serves a wider range of residential, commercial, and public-sector projects.
Given the number of moving parts across regulation, demand cycles, product innovation, and competitive consolidation, timely access to detailed segment data, regional breakdowns, and company-level benchmarking can materially improve planning quality. For decision-makers seeking deeper segmentation, granular regional insights, and customized strategic recommendations, the full PW Consulting research report provides the supporting detail needed to translate these market-level trends into specific investment, sourcing, and growth decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Landscape Rock Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com