

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Tonsil Cancer Treatment Market: Why the $996M Base & 6.42% CAGR Upend Strategy

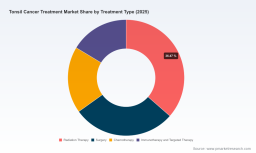
Tonsil Cancer Treatment Market: Strategic Shifts & Commercial Opportunities (2025-2032)
The Current Market Landscape and Core Challenges
The global market for tonsil cancer treatment is undergoing a significant structural transformation, driven by evolving therapeutic paradigms, shifting demographic patterns, and a maturing pharmaceutical ecosystem. Valued at approximately 1,000 million USD in the 2025 base year, the market has demonstrated consistent expansion, with historical growth trajectories reflecting increased diagnostic awareness, refined staging protocols, and broader access to advanced oncology interventions. Forecasts indicate sustained momentum through the end of the decade, supported by a steady compound annual growth rate and clear upward trajectory in total revenue. The market’s expansion is not merely a function of population growth or incidence rates; it reflects a fundamental recalibration of how oropharyngeal and tonsil malignancies are approached clinically, commercially, and financially.
Beneath these aggregate figures, several structural tensions are reshaping competitive priorities. First, pricing resilience and reimbursement uncertainty remain central concerns across most mature healthcare systems. Oncology portfolios increasingly rely on on-patent therapies that command premium pricing, yet the lifecycle economics of pharmaceutical products are well understood by payers and health technology assessment bodies. Once patent protection expires, generic and biosimilar entrants typically trigger rapid price compression, and procurement frameworks are increasingly designed to steer utilization toward lower-cost alternatives through tiered cost-sharing mechanisms. For manufacturers and care providers alike, this creates a narrow window to demonstrate differentiated clinical value, secure formulary positioning, and build durable reimbursement narratives before margin erosion accelerates.
Second, the regulatory and trade environment has introduced new supply chain and operational contingencies. Recent policy shifts have altered how pharmaceutical imports are evaluated, particularly for branded and patented products. Manufacturers without active domestic production commitments face heightened cost exposure and potential access friction in certain key markets. This development is prompting strategic reassessment of manufacturing footprints, logistics planning, and portfolio localization strategies, especially for companies whose tonsil cancer or broader head and neck oncology offerings depend on cross-border supply networks.
Third, clinical adoption pathways are becoming more nuanced as treatment algorithms move beyond one-size-fits-all cytotoxic regimens. The convergence of immunotherapy, targeted biologics, and conditionally active antibody-drug conjugates is changing the standard of care conversation, but integration into real-world clinical practice depends on biomarker stratification, multidisciplinary coordination, and institutional readiness. Healthcare systems and specialty centers must navigate the balance between innovation adoption and operational feasibility, particularly when newer modalities require specialized administration, monitoring, or patient selection criteria.
Collectively, these dynamics define a market that is expanding, but not uniformly. Growth is increasingly concentrated among players who can align product development with reimbursement strategy, adapt supply chain architectures to policy volatility, and support clinical adoption with robust evidence generation. The competitive battlefield is shifting from simple therapeutic availability toward value demonstration, access optimization, and integration readiness.
Key Drivers Shaping Market Trajectory
Several interlocking forces are accelerating change within the tonsil cancer treatment landscape. Understanding their interaction is essential for anticipating where commercial value will accumulate and which capabilities will separate resilient organizations from reactive ones.
Therapeutic Innovation and Biomarker-Aligned Oncology
The most consequential driver is the ongoing evolution of treatment architecture for head and neck malignancies, including tonsil and oropharyngeal disease. Immunotherapy has established itself as a core pillar in recurrent, metastatic, and increasingly perioperative contexts. Rather than replacing established modalities, the prevailing model is one of integration: checkpoint inhibitors and targeted biologics are being positioned alongside surgery, radiation, and chemotherapy in ways that aim to improve outcomes while moderating toxicity. This shift is particularly relevant in HPV-associated disease, where biological characteristics create opportunities for more selective targeting and refined patient stratification.
Recent regulatory milestones have reinforced this direction. The approval of pembrolizumab for perioperative use in resectable locally advanced head and neck squamous cell carcinoma, including PD-L1-positive tumors, marked a meaningful expansion of immunotherapy utility beyond later-stage settings. The therapeutic relevance extends to tonsil cancer where disease biology and staging overlap substantially with broader oropharyngeal indications. Simultaneously, conditionally active biologics and antibody-drug conjugates are advancing through late-stage development with a focus on HPV-positive populations. Alignment between developers and regulators on pivotal trial design indicates growing confidence in differentiated mechanisms of action, particularly where conventional treatment pathways leave residual unmet need.
PW Consulting
This innovation trajectory changes the commercial calculus in two ways. First, it raises the importance of companion diagnostics, biomarker testing infrastructure, and pathology workflow integration. Second, it increases the premium on clinical evidence that goes beyond median endpoints to address durability, quality of life, and toxicity management, all of which influence formulary decisions and provider adoption.
Policy, Regulation, and Access Frameworks
Regulatory and reimbursement dynamics are not merely compliance considerations; they are strategic determinants of market access and revenue durability. The 2025 approval expansion for perioperative immunotherapy underscored how regulatory decisions can reshape treatment intent, moving certain modalities earlier in the care continuum and altering competitive positioning across therapy classes. At the same time, the broader pricing environment emphasizes lifecycle management. Payers are increasingly attentive to value demonstration, and procurement structures are designed to encourage substitution when exclusivity lapses. This creates pressure on manufacturers to plan for the full product arc, including post-patent positioning, differentiated formulations, and combination strategies that may extend commercial relevance.
Trade policy adds another layer of complexity. Import-related measures that affect branded and patented pharmaceutical products can alter landed costs, supply continuity, and market entry timing. Companies with significant exposure to cross-border distribution are being forced to evaluate whether localized production, regional stocking strategies, or alternative sourcing models are warranted. This is especially salient for players whose tonsil cancer portfolios intersect with broader head and neck oncology franchises and whose manufacturing decisions affect multiple indications simultaneously.
Demand-Side Evolution in Care Delivery
Patient and provider behavior is shifting as clinical education improves and multidisciplinary care models mature. Awareness of HPV-associated oropharyngeal disease has increased attention to early presentation, staging accuracy, and risk stratification. At the same time, treatment decisions are increasingly made by coordinated teams rather than single-specialty decision makers. This favors therapies that fit cleanly into established surgical, radiation, and medical oncology workflows while minimizing disruption to patient throughput.
Demand is also being shaped by expectations around tolerability and functional outcomes. In cancers affecting the head and neck region, treatment burden can have pronounced effects on swallowing, speech, nutrition, and overall quality of life. Interventions that can preserve efficacy while reducing acute or long-term toxicity gain traction not only in clinical discussions but also in patient preference and provider referral patterns. Consequently, the market increasingly rewards solutions that couple clinical performance with manageable administration and supportive care integration.
Cost Structures and Competitive Realities
Cost dynamics are being redefined by several factors: the concentration of spending on newer on-patent therapies, the operational costs associated with advanced treatment administration, and the financial pressure on care sites to manage episode-related resource use. Hospital settings continue to represent the largest end-user segment, reflecting the complexity of surgical and multidisciplinary management. Specialty clinics and ambulatory surgical centers play a growing role where treatment pathways allow for shorter recovery times, streamlined administration, or outpatient-compatible protocols.
Mapping below outlines the core drivers and their commercial implications.
Worldwide Canine Mammary Tumor Treatment Market
- Therapeutic innovation : Expands addressable use cases, increases reliance on biomarker infrastructure, and raises evidence standards for adoption.
- Regulatory and reimbursement shifts : Accelerates earlier-line integration for some modalities, intensifies lifecycle pricing pressure, and strengthens the need for differentiated value narratives.
- Demand-side behavior : Favors multidisciplinary compatibility, tolerability, and functional outcomes, influencing referral patterns and site selection.
- Cost and supply dynamics : Encourages manufacturing localization, portfolio resilience planning, and reimbursement-aligned procurement strategies.
Competitive Landscape and Leading Strategies
The competitive environment in tonsil cancer treatment is defined by a mix of large oncology franchises, targeted biotech developers, and supportive-care participants, all operating within a moderately concentrated market. A handful of firms account for a substantial share of revenues, and CR3 and CR5 concentration indicators reflect the structural advantage held by companies with established immunotherapy platforms, broad commercialization capabilities, and integrated oncology portfolios. Concentration does not imply stagnation, however. In fact, the current phase is characterized by deliberate differentiation, where scale is necessary but not sufficient, and where pipeline novelty, regulatory timing, and access strategy increasingly determine relative positioning.
Among the most prominent participants, Merck & Co. has reinforced its position through a high-profile regulatory milestone for perioperative pembrolizumab in resectable locally advanced head and neck squamous cell carcinoma, including PD-L1-positive disease. The move is strategically significant because it broadens the immunotherapy conversation earlier in the treatment journey, where patient populations are larger and clinical decision-making is more highly coordinated. This positioning supports the company’s broader oncology narrative by demonstrating applicability across the care continuum rather than restricting relevance to later-line settings.
Bristol Myers Squibb continues to leverage nivolumab as an established immunotherapy option for recurrent and metastatic disease. Its strategic advantage lies in clinical familiarity, integration within existing treatment algorithms, and the durability of evidence built over prior adoption cycles. In a market where provider comfort and institutional protocols influence prescribing, such entrenched positioning can serve as a stable foundation even as newer modalities emerge.
Eli Lilly and AstraZeneca contribute distinct value propositions within the broader head and neck oncology ecosystem. Lilly’s involvement spans supportive agents and pipeline candidates relevant to squamous cell carcinomas, reflecting an interest in both direct treatment and the surrounding care architecture. AstraZeneca’s emphasis on durvalumab and combination-oriented research illustrates the industry’s appetite for regimen-level innovation, where the opportunity is not simply a single agent but a coordinated therapeutic sequence or combination that may improve outcomes in defined patient subsets.
Roche’s cetuximab remains relevant in combination with radiation or chemotherapy for advanced disease, including oropharyngeal cases. Its continued role reflects the persistence of targeted anti-EGFR strategies in selected settings and the practical reality that established biologics can retain clinical utility even as the innovation frontier advances. Sanofi’s oncology portfolio elements and supportive care contributions similarly underscore the importance of surrounding therapies that help manage complex cases and improve treatment tolerability.
The most notable competitive shift, however, comes from specialized developers pursuing biologically selective approaches. BioAtla’s conditionally active antibody-drug conjugate is advancing toward pivotal development in HPV-positive oropharyngeal disease, with regulatory alignment supporting potential accelerated pathways. This type of asset is strategically important because it targets a biologically defined subgroup and represents a move toward conditional activity design, where therapeutic action is intended to be more selective in the tumor environment. If clinical outcomes confirm the promise of such approaches, the commercial impact could include tighter biomarker-linked adoption, new partnering dynamics, and heightened value assessment requirements from payers and providers alike.
PDS Biotechnology’s HPV-focused clinical program reflects a parallel trend: vaccine-based and immune-priming strategies aimed at populations with viral-driven disease biology. This approach complements the broader momentum around HPV-associated oropharyngeal cancers and signals continued interest in modalities that address etiology as well as tumor burden. The presence of such programs in the competitive landscape suggests that future differentiation will increasingly depend on biology-driven targeting and regimen-level evidence rather than class-level presence alone.
Several structural trends are shaping how this landscape evolves.
- Integration over isolation : Companies that can position therapies within multidisciplinary pathways, including surgery, radiation, and supportive care, are likely to gain stronger adoption footholds.
- Biomarker-driven segmentation : HPV status, PD-L1 expression, and other molecular markers are becoming central to treatment selection, raising the stakes for diagnostic partnerships and evidence generation.
- Lifecycle and access planning : As exclusivity timelines shape pricing trajectories, leaders are preparing for generic and biosimilar pressure by building differentiated indications, combination strategies, and access narratives early.
- Manufacturing and geopolitical readiness : Trade and import-related contingencies are pushing firms to evaluate domestic production options and supply chain resilience as part of commercial strategy, not just operational logistics.
- Clinical trial leadership as influence : Academic and clinical centers that shape pivotal studies can influence adoption standards, guideline inclusion, and the credibility of new regimens, which indirectly affects competitive outcomes.
The competitive field is therefore moving toward a hybrid structure: large players maintain scale, breadth, and established relationships, while focused innovators compete on biological precision, trial design, and potential accelerated regulatory pathways. Over time, the most successful organizations will likely be those that can combine scientific differentiation with reimbursement fluency and real-world implementation support.
Future Trends and Market Outlook (2026–2032)
Looking ahead, three trends are likely to shape the next phase of market development. The first is the continued migration of immunotherapy and targeted modalities into earlier lines of care where clinically appropriate. This does not eliminate surgery, radiation, or chemotherapy; rather, it reframes them within more personalized sequences. For commercial players, this trend expands the scope of strategic planning beyond late-stage rescue therapy and into perioperative and consolidation contexts, where patient volume, treatment duration, and combination economics can be materially different.
Cancer Treatment Drugs Market
The second trend is the growing importance of biomarker and diagnostic ecosystems. As therapeutic selection becomes more dependent on HPV status, PD-L1 expression, and potentially other molecular features, the value of reliable testing, clear reporting, and coordinated pathology workflows will increase. This creates opportunities not only for diagnostic providers and companion test developers, but also for therapy manufacturers that can demonstrate how biomarker-guided use improves outcomes, reduces unnecessary toxicity, and strengthens reimbursement justification. Organizations that treat diagnosis as an integral part of the commercial model, rather than a separate transaction, will be better positioned to secure durable adoption.
The third trend is institutional adaptation to cost, access, and supply pressures. Healthcare systems and specialty sites will continue to optimize care delivery around tolerability, throughput, and total episode cost. At the same time, manufacturers will need to manage lifecycle risk more explicitly, anticipating biosimilar and generic entry, trade-related cost impacts, and the need for localized or regionally resilient supply. The likely outcome is a market in which financial and operational resilience become as important as clinical innovation. Products and programs that can navigate access complexity, support site-level efficiency, and maintain continuity under policy volatility will have a structural advantage.
Potential risks and uncertainties remain. Clinical development in biomarker-selected populations can be promising but also fragile, with regulatory and reimbursement outcomes depending on the strength and generalizability of trial results. Pricing pressure may intensify if healthcare budgets face renewed constraints or if payers become more assertive in value-based contracting. Trade and manufacturing policy could also create uneven access conditions across regions, complicating global launch strategies and potentially favoring companies with more flexible operational footprints. Finally, the pace of guideline adoption and multidisciplinary integration may vary by setting, meaning that the same clinical advancement can translate into different commercial outcomes depending on local care infrastructure.
Strategic Implications for Decision Makers
For executives and investors navigating this market, several priorities stand out.
For Manufacturers and Developers
Invest in biomarker-aligned development and evidence generation that supports earlier-line use where appropriate. Build reimbursement narratives that connect clinical differentiation with real-world value, including toxicity reduction, functional outcomes, and treatment sequencing. Evaluate manufacturing and supply chain localization proactively, particularly if portfolio exposure crosses multiple oncology indications and import-related cost risks are material.
For Investors
Focus on assets and companies with clear biomarker strategy, strong regulatory alignment, and credible lifecycle plans. Differentiate between broad franchise stability and innovation-driven optionality; both can be valuable, but they carry different risk profiles. Pay attention to supply chain readiness and access positioning, since commercial success increasingly depends on execution beyond clinical efficacy alone.
For Procurement and Care Providers
Prioritize therapies and service models that integrate efficiently into multidisciplinary workflows, support predictable utilization patterns, and align with site-level cost management. Build internal capability for biomarker-informed decision-making and evaluate total episode impact rather than unit price in isolation. Where possible, align contracting strategies with anticipated lifecycle changes, including the transition from branded exclusivity to lower-cost alternatives.
The tonsil cancer treatment market is expanding within a landscape defined by therapeutic innovation, biomarker-driven segmentation, access complexity, and supply-side recalibration. Organizations that understand these interconnections will be better equipped to allocate capital, shape pipelines, and plan for the commercial realities of the next several years. For teams seeking deeper segmentation data, company-level profiling, and tailored scenario planning across regions and therapy classes, detailed research resources are available for further exploration.
For detailed analysis of this topic, please visit the official page: Worldwide Tonsil Cancer Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com